
 High-End Accelerometer Market | 2026-2036
High-End Accelerometer Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Accelerometer Market Intelligence
Defense prime contractors and satellite operators are unwinding the historical dominance of general industrial buyers in high-end accelerometer procurement. Robert Bosch leverages captive semiconductor fabrication to control MEMS wafer supply for automotive inertial measurement units. Analog Devices sustains technology leadership through proprietary capacitive architectures optimized for navigation-grade precision. Safran Colibrys anchors European supply security via French-based cleanroom production of quartz MEMS devices.
High-end accelerometers are precision inertial sensors that measure linear acceleration along one or more axes, typically achieving bias stability below 50 micro-g and operating across temperature ranges exceeding 125 degrees Celsius for navigation, guidance, and structural monitoring applications. MEMS-based designs now dominate volume production due to silicon batch-fabrication economics, while piezoelectric variants retain structural health monitoring applications where extreme shock resistance outweighs cost sensitivity. Capacitive sensing architectures capture the largest margin pool in aerospace and defense procurement, whereas optical accelerometers occupy emerging niches in scientific instrumentation demanding immunity to electromagnetic interference.
FAA certification requirements under DO-178C and DO-254 govern accelerometer qualification for commercial aviation deployment, extending development cycles and concentrating supplier relationships among pre-qualified vendors. EASA's equivalent CS-ETSO standards create parallel compliance burdens for European aerospace programs, while REACH chemical restrictions affect piezoelectric material selection across EU manufacturing. Stakeholders must monitor evolving export control classifications for inertial sensors, as dual-use technology designations increasingly constrain cross-border transfer of navigation-grade components.
Market Dynamics
Aerospace procurement consolidation around navigation-grade MEMS is compressing supplier qualification timelines while elevating certification barriers for new entrants. Defense primes now mandate dual-source redundancy for critical inertial channels, forcing accelerometer vendors to replicate cleanroom capacity across politically aligned manufacturing zones.
Growth Catalysts
- DO-178C and DO-254 mandates:FAA certification requirements for commercial aviation extend development cycles but lock in long-term supplier relationships with pre-qualified vendors, creating defensive moats for incumbent precision MEMS manufacturers.
- Quartz MEMS batch fabrication:French cleanroom production of resonant quartz devices achieves bias stability below 10 micro-g, opening satellite constellation markets previously reserved for fiber-optic gyroscope alternatives.
- Automotive LiDAR integration:German OEM clusters around Stuttgart and Munich are specifying high-g shock-resistant accelerometers for autonomous vehicle perception systems, pulling volume from traditional industrial automation channels.
Market Restraints
- Specialized foundry concentration:Navigation-grade MEMS fabrication depends on a handful of European and US-based 200mm wafer facilities, creating geographic chokepoints that amplify disruption risk from regional trade restrictions.
- Piezoelectric material cost volatility:Lead zirconate titanate ceramic supply faces ECHA REACH chemical registration burdens and raw material sourcing constraints from concentrated African tantalum processing.
- Optical interferometry substitution:Scientific instrumentation segments are migrating toward fiber-optic accelerometers for electromagnetic immunity, eroding capacitive MEMS margins in niche high-precision applications.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for electronic components and DGFT import substitution mandates create captive demand for locally packaged navigation-grade sensors in missile guidance and unmanned aerial platforms.
- Structural health monitoring convergence:Fusion of MEMS accelerometers with wireless mesh networks enables continuous civil infrastructure monitoring, displacing periodic manual inspection regimes in aging bridge and dam portfolios.
- Japan METI carbon-neutral aviation roadmap:Hydrogen-powered regional aircraft development programs require novel inertial reference systems capable of operating in cryogenic fuel tank proximity, opening specification windows for thermal-resistant sensor architectures.
Industry Challenges
- Multi-physics simulation expertise scarcity:Coupled electro-mechanical-thermal modeling for MEMS design requires rare cross-disciplinary talent pools concentrated in Zurich, Grenoble, and Boston academic corridors.
- EASA CS-ETSO certification timeline compression:European aerospace programs demand parallel compliance documentation that strains engineering bandwidth without commensurate contract milestone acceleration.
- Legacy avionics bus integration complexity:ARINC 429 and MIL-STD-1553 interface requirements force custom signal conditioning development for each airframe platform, fragmenting product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Accelerometer Market |
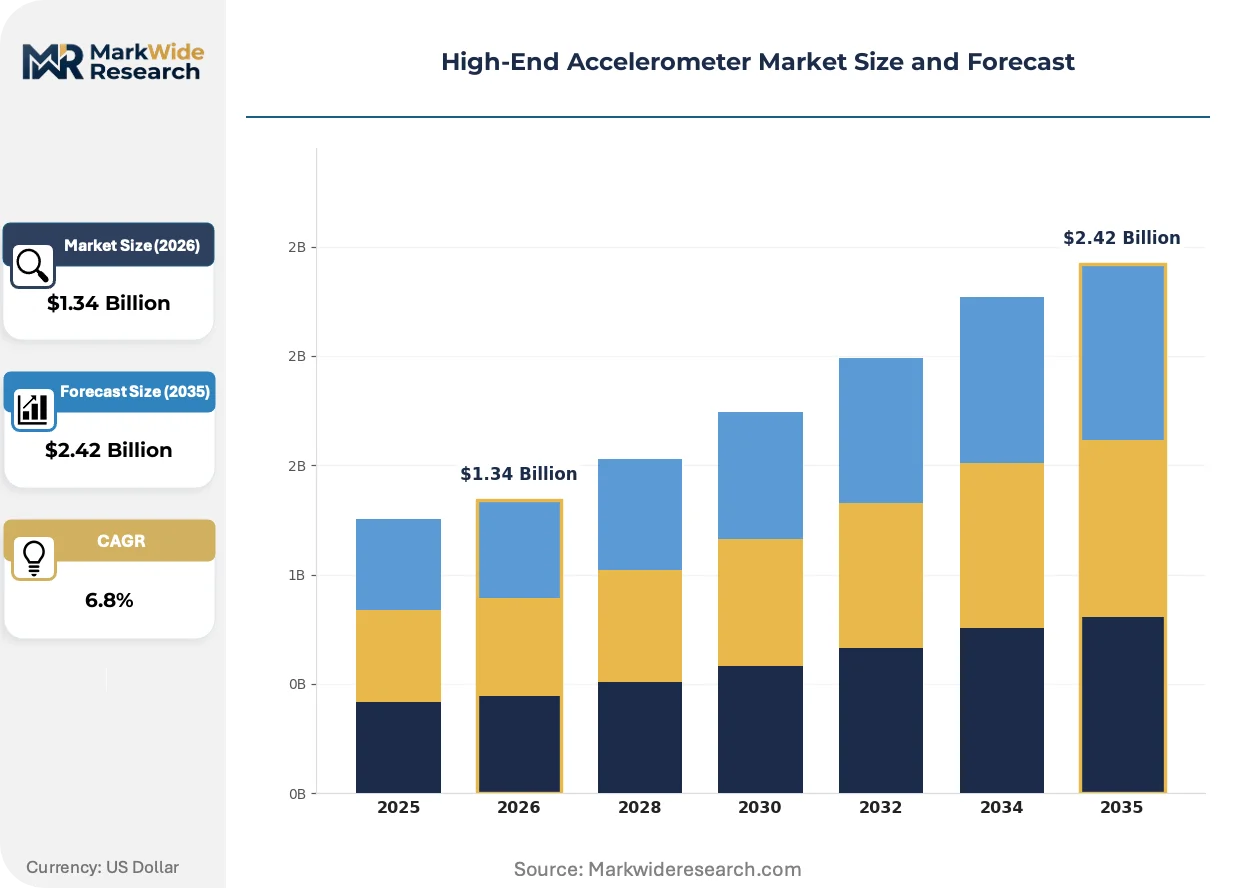
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS, Capacitive, Piezoelectric, Optical End User: Aerospace, Consumer Electronics, Automotive, Industrial Technology: Analog, Digital, Wireless, Hybrid Application: Motion Tracking, Vibration Monitoring, Structural Health, Gaming |
| Companies Covered | Robert Bosch, Thales Group, Analog Devices, Physical Logic, Sensonor, Honeywell International, STMicroelectronics, TE Connectivity, Safran Colibrys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Accelerometer Market Strategic Shifts & Innovations
Silicon photonics integration and advanced packaging architectures are dissolving the traditional boundary between discrete sensor components and system-level inertial measurement units. These developments compress form factors while elevating environmental tolerance specifications.
Capacitive MEMS with through-silicon via interconnects is miniaturizing inertial measurement unit footprints from cubic centimeters to cubic millimeters. Satellite operators deploying dense LEO constellations are adopting these devices for attitude determination at volume scale. The technology is miniaturing power budgets and thermal management requirements, enabling previously inaccessible CubeSat and small launcher applications.
EASA's evolving CS-ETSO standards for unmanned aircraft systems are mandating redundant accelerometer channels for beyond-visual-line-of-sight operations. European drone manufacturers are redesigning flight control electronics to accommodate dual tri-axial packages. Urban air mobility developers in Toulouse and Munich are responding with modular sensor fusion architectures that accelerate certification pathway flexibility.
Defense procurement offices are consolidating inertial sensor purchasing through prime contractor platform contracts rather than component-level sourcing. Tier-two accelerometer vendors now face exclusive negotiation with Lockheed Martin, Northrop Grumman, and BAE Systems platform divisions. This concentration is most visible in US hypersonic weapon programs and UK next-generation fighter development, where sole-source agreements lock out independent component suppliers.
High-End Accelerometer Market Segmentation
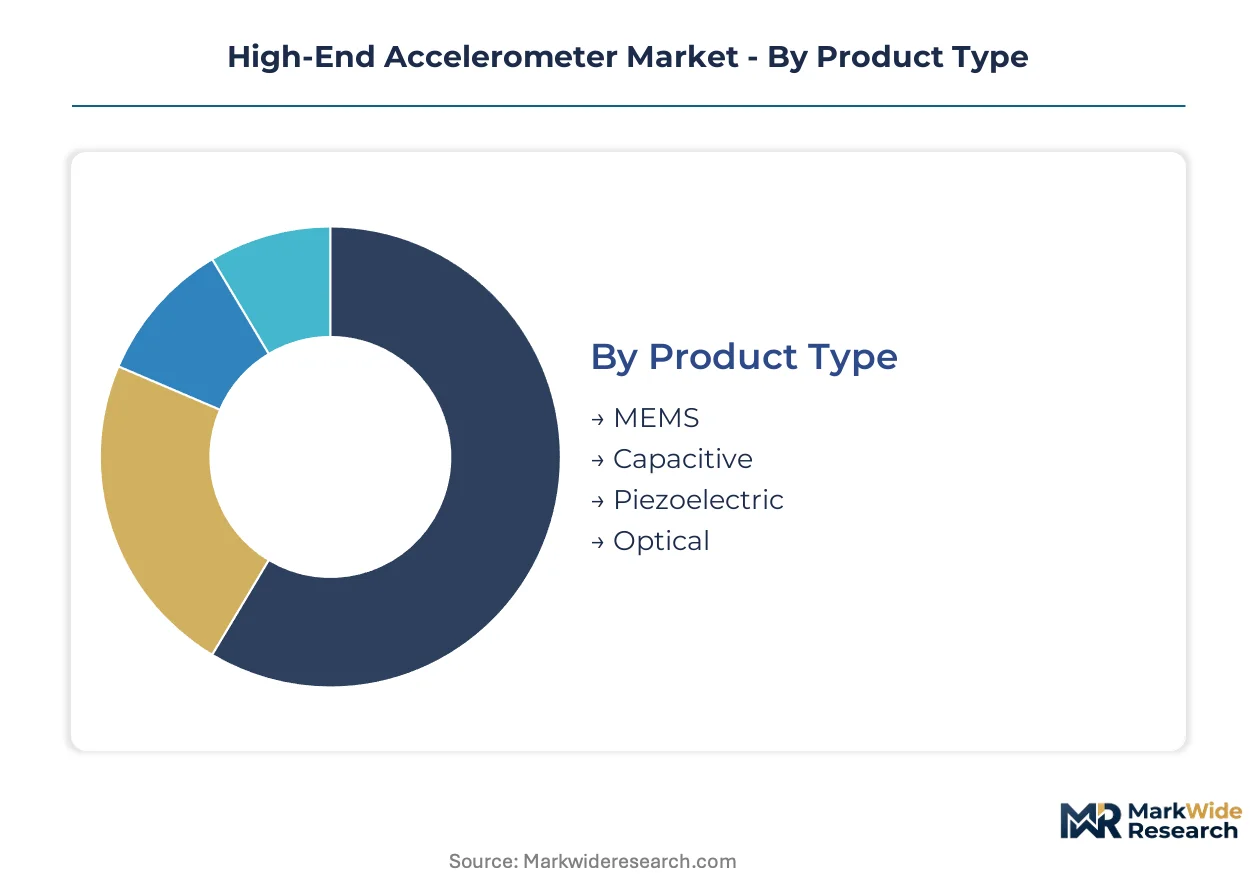
Precision requirements diverge sharply across end-use applications, fragmenting procurement channels and qualification standards. Navigation-grade aerospace buyers demand bias stability below 10 micro-g, while industrial automation tolerates 100x looser specifications. Channel economics thus split between certified defense primes and volume-driven automotive tier-one suppliers.
Product Type:
Channel distribution maps directly to fabrication complexity: MEMS devices flow through automotive and consumer electronics distributors, while quartz and optical variants route exclusively through defense-aerospace prime contractor channels.
- MEMS:Silicon batch-fabrication enables cubic-millimeter form factors with sub-50 micro-g bias stability. German automotive clusters around Stuttgart specify these for autonomous vehicle LiDAR stabilization, pulling volume from industrial channels.
- Capacitive:Electrostatic sensing architectures achieve navigation-grade precision through proprietary electrode geometries. Aerospace procurement concentrates here for FAA DO-178C certification pathways, locking supplier relationships across multi-year platform contracts.
- Piezoelectric:Lead zirconate titanate ceramics deliver extreme shock resistance for structural health monitoring.
- Optical:Fiber-interferometric designs provide electromagnetic immunity for scientific instrumentation.
By volume, MEMS leads. By growth pace, optical architectures are climbing the fastest.
End User:
Margin concentration follows certification burden: aerospace programs absorb 60-70% unit cost premiums for traceable calibration chains, while automotive buyers prioritize shock-tolerance over absolute precision.
- Aerospace:Commercial aviation and satellite operators mandate dual-source redundancy for critical inertial channels. EASA CS-ETSO standards extend qualification timelines, concentrating procurement among pre-qualified French and US vendors.
- Automotive:German OEM clusters specify high-g shock-resistant packages for autonomous perception systems. Stuttgart and Munich engineering centers are pulling accelerometer volume toward automotive-grade MEMS foundries.
- Industrial:Factory automation and robotics applications prioritize cost-optimized packages with moderate precision.
- Consumer Electronics:Smartphone and wearable manufacturers drive lowest-cost, highest-volume MEMS consumption.
Aerospace commands the steepest pricing tiers. Automotive is gaining share fastest.
Technology:
Signal conditioning architecture determines interface compatibility with legacy avionics buses and emerging wireless mesh networks.
- Digital:SPI and I2C interfaces dominate new aerospace designs, enabling direct microcontroller integration without analog front-end components.
- Analog:Voltage-output devices retain installed base in legacy ARINC 429 avionics systems requiring custom signal conditioning per airframe.
- Wireless:Bluetooth Low Energy and proprietary mesh protocols enable structural health monitoring without cabling infrastructure.
- Hybrid:Combined analog-digital architectures bridge legacy and modern system requirements.
Digital outputs dominate new design wins. Wireless is expanding most quickly in civil infrastructure applications.
Application:
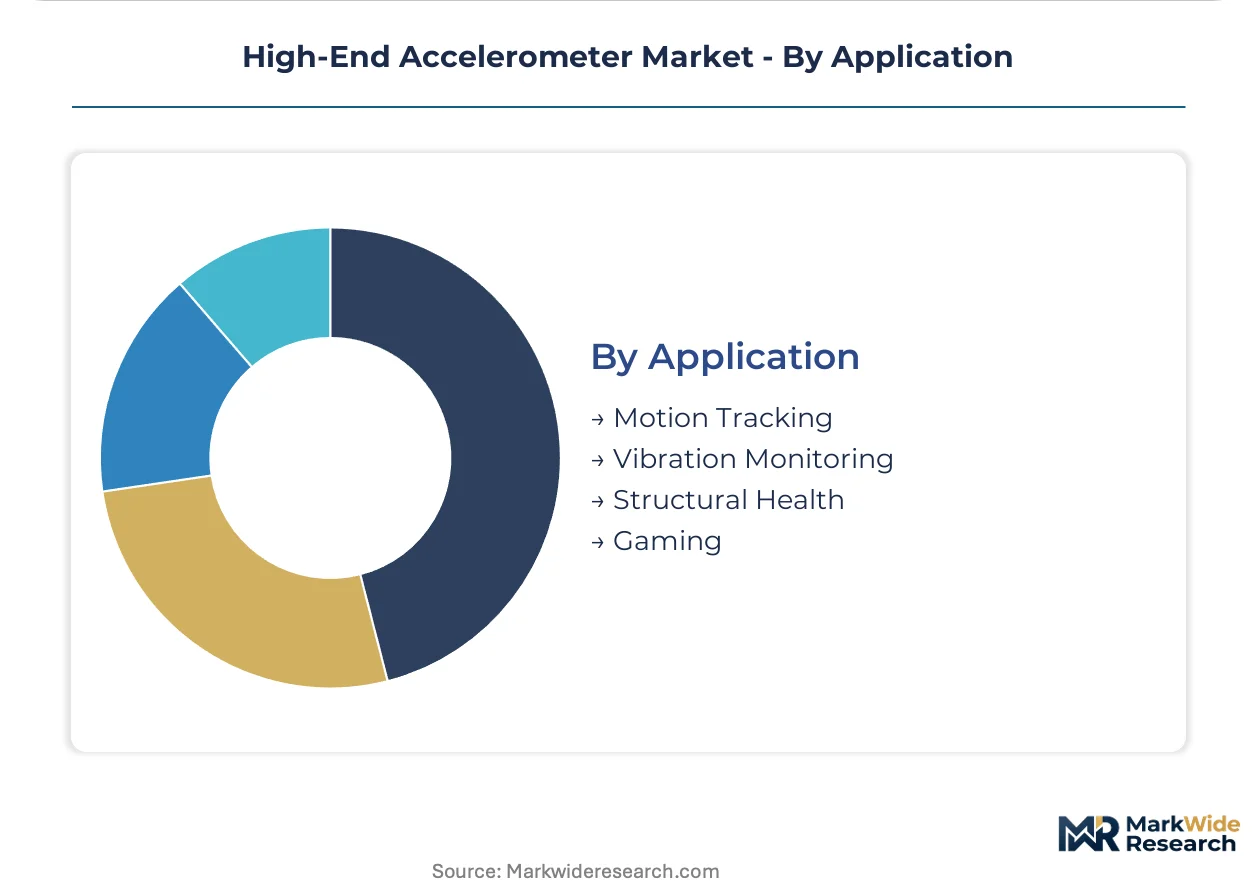
Performance specifications stratify by measurement dynamics: static tilt sensing tolerates lower bandwidth than vibration capture or motion tracking.
- Structural Health:Continuous bridge and dam monitoring fuses MEMS accelerometers with wireless mesh networks, displacing periodic manual inspection regimes. Japan's aging civil infrastructure portfolio is driving specification windows for 10-year unattended operation.
- Motion Tracking:Inertial navigation for unmanned systems demands tight integration with gyroscope channels. India's defense indigenization programs under PLI schemes are creating captive demand for locally packaged navigation-grade sensors.
- Vibration Monitoring:Predictive maintenance in rotating machinery requires frequency response flatness across temperature extremes.
- Gaming:Consumer VR controllers and haptic feedback systems prioritize lowest-cost MEMS with minimal precision requirements.
Structural health leads by project pipeline value. Motion tracking is gaining share fastest in defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in precision MEMS fabrication, connecting Stuttgart engineering clusters to Austrian semiconductor packaging facilities.
United States
Hypersonic weapon programs and next-generation fighter development at Lockheed Martin and Northrop Grumman drive navigation-grade accelerometer procurement. FAA DO-178C and DO-254 certification requirements extend supplier qualification timelines, locking in multi-year platform contracts. Boston academic corridors concentrate multi-physics simulation expertise for coupled electro-mechanical-thermal MEMS design.
Germany
Automotive OEM clusters around Stuttgart and Munich specify high-g shock-resistant accelerometers for autonomous vehicle LiDAR stabilization. KBA vehicle safety regulations mandate traceable calibration chains for inertial sensors in SAE Level 3+ systems. Precision MEMS foundries in Baden-Württemberg pull volume from traditional industrial automation channels.
France
Safran Colibrys anchors European supply security through French-based cleanroom production of quartz MEMS devices achieving bias stability below 10 micro-g. EASA CS-ETSO standards create parallel compliance burdens for aerospace programs, concentrating procurement among pre-qualified vendors. Toulouse urban air mobility developers respond with modular sensor fusion architectures.
Japan
METI's carbon-neutral aviation roadmap drives hydrogen-powered regional aircraft programs requiring thermal-resistant inertial reference systems. Aging civil infrastructure portfolios in Kanto and Kansai regions drive specification windows for 10-year unattended MEMS operation. Nagoya aerospace suppliers integrate accelerometers into attitude determination systems for small launcher applications.
India
Defense indigenization under PLI schemes and DGFT import substitution mandates create captive demand for locally packaged navigation-grade sensors. Missile guidance and unmanned aerial platform programs require dual-source redundancy for critical inertial channels. Bangalore and Hyderabad engineering centers develop indigenous packaging capabilities for satellite constellation applications.
High-End Accelerometer Market Key Industry Players
Listed leaders compete with private specialists across certification-grade precision tiers. The vendor base splits between scale-driven semiconductor conglomerates and captive fabrication specialists serving defense primes. Three archetypes dominate: automotive-grade MEMS volume producers, aerospace-certified quartz specialists, and navigation-grade capacitive architects. Competitive moves concentrate on dual-source redundancy mandates and geographic replication of cleanroom capacity across politically aligned manufacturing zones.
Within the European quartz MEMS tier, Safran Colibrys and Thales Group exemplify defense-aerospace integration. Robert Bosch and Analog Devices occupy positions spanning automotive and industrial channels, with Bosch leveraging captive semiconductor fabrication and Analog Devices sustaining technology leadership through proprietary architectures. Among diversified industrial conglomerates, Honeywell International and STMicroelectronics represent scale-driven approaches to precision sensor markets.
| Leading Market Players |
|---|
| Robert Bosch |
| Thales Group |
| Analog Devices |
| Physical Logic |
| Sensonor |
| Honeywell International |
| STMicroelectronics |
| TE Connectivity |
| Safran Colibrys |
| Others |
Cost & Logistics Intelligence
Eighteen-month qualification timelines for FAA DO-178C certification concentrate supplier power among pre-qualified vendors while fragmenting buyer leverage across defense primes and automotive OEMs. This lead-time band locks procurement relationships and shields incumbent pricing from volume-driven compression.
Pricing Analysis
Three-tier pricing structure across navigation-grade, automotive-grade, and industrial-grade certification levels stratifies accelerometer markets by traceability burden. Price differentiation centers on bias stability thresholds and dual-source redundancy mandates, with aerospace programs absorbing substantial premiums for EASA CS-ETSO documentation. Cost compression in automotive-grade MEMS channels is intensifying because Stuttgart and Munich OEM clusters are consolidating specification authority around captive foundry partnerships. Industrial automation buyers exhibit the highest price sensitivity, while satellite operators demonstrate minimal elasticity due to mission-critical reliability requirements.
Supply Chain Analysis
Strategic stockpiling of quartz MEMS wafers dominates defense procurement patterns, contrasting with just-in-time inventory practices in automotive channels. Supply concentrates in France, Germany, and the United States, with cleanroom fabrication drawing from European 200mm wafer facilities and Boston-area multi-physics design talent. Raw material dependencies include lead zirconate titanate ceramics, silicon-on-insulator substrates, and tantalum-based capacitor components. Single-source vulnerability pervades navigation-grade resonant quartz production, where Safran Colibrys maintains French-based captive capacity. Distribution runs through defense prime contractor platforms rather than component-level channels, compressing tier-two vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among defense prime contractors and German automotive OEMs, fragmenting supplier negotiation leverage across fragmented tier-two accelerometer vendors. This consolidation dynamic elevates the strategic premium on certification pre-qualification and geographic manufacturing replication.
For Market Incumbents: Shield navigation-grade market position through redundant cleanroom replication in politically aligned manufacturing zones, responding to dual-source mandates from Lockheed Martin and Northrop Grumman platform divisions. Prioritize EASA CS-ETSO certification pathway acceleration to defend against emerging quartz MEMS specialists. Backward integration into silicon-on-insulator wafer supply secures margin control against foundry concentration risk. For New Entrants and Emerging Players: Differentiate on structural health monitoring wireless integration, where Japan's aging civil infrastructure portfolio creates specification windows for 10-year unattended operation. Target India's defense indigenization programs under PLI schemes, where DGFT import substitution mandates generate captive demand for locally packaged sensors. Pursue urban air mobility developers in Toulouse with modular sensor fusion architectures that compress EASA certification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quartz MEMS cleanroom fabrication, favoring scaled incumbents over venture-backed entrants. Long-term viability across the analysis window rests on certification-grade precision tier positioning rather than volume scale. Acquisition targets should exhibit established FAA DO-178C qualification and French or US-based manufacturing footprints. The signal to watch is EASA unmanned aircraft system standard evolution, which will dictate redundant channel specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Replication | Dual-source redundancy mandates from defense primes force geographic manufacturing dispersion across aligned zones. |
| Certification Pre-Qualification Investment | FAA DO-178C and EASA CS-ETSO documentation creates defensive moats against unqualified entrants. |
| Wireless Sensor Fusion Development | Structural health monitoring convergence in Japan's civil infrastructure opens unattended operation specifications. |
| Defense Indigenization Partnership | India's PLI schemes and DGFT mandates generate captive demand for locally packaged navigation-grade sensors. |
| Quartz MEMS Batch Fabrication Scale-Up | French cleanroom production of resonant devices achieves bias stability thresholds for satellite constellation markets. |
Research Approach
The analysis maps MEMS, capacitive, piezoelectric, and optical accelerometer sub-sectors, each validated through defense procurement officers, automotive platform engineers, and precision foundry operations heads. Primary interviews with satellite operator attitude determination specialists, urban air mobility flight control architects, and civil infrastructure monitoring system integrators combined with secondary validation against FAA certification databases, EASA CS-ETSO documentation registries, and customs trade data for inertial sensor components. Bottom-up and top-down triangulation cross-referenced foundry capacity disclosures with platform contract award patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, end-user industry, precision grade tier, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth trajectory synthesis incorporating hydrogen-powered aircraft thermal specification evolution and India defense indigenization program pacing. Industry-specific forecast inputs included LEO constellation deployment schedules and automotive SAE Level 3+ system rollout patterns.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement consolidation or EASA unmanned aircraft regulatory acceleration would require recalibration. Forecasts reflect assumptions regarding cleanroom capacity expansion timelines and REACH chemical restriction stability. Revision becomes warranted when quartz MEMS foundry concentration or dual-use technology export control thresholds cross critical inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Wireless Flow Sensors Market