
 Global Infrared Thermography Market | 2026-2036
Global Infrared Thermography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infrared Thermography Market Intelligence
Buyer concentration in the energy sector is decoupling from traditional utility procurement patterns as distributed renewable operators and battery storage developers enter the procurement base. Teledyne FLIR LLC leverages its cooled detector heritage to dominate defense and aerospace channels. Fluke Corporation anchors the industrial maintenance segment with handheld thermal imagers purpose-built for electrical contractors. Zhejiang Dali Technology Co., Ltd. competes aggressively on cost in the Asian commercial security market.
Infrared thermography captures thermal radiation emitted by objects and converts it into visible images through detector arrays sensitive to wavelengths between 7 and 14 micrometers, enabling non-contact temperature measurement across surfaces and systems. The technology serves predictive maintenance, electrical fault detection, building envelope analysis, and process control in industrial environments. Handheld cameras sustain the largest revenue pool due to versatility across field service applications, while fixed camera installations are displacing periodic manual inspections in continuous manufacturing settings. Uncooled microbolometer detectors occupy the volume leadership position because they eliminate cryogenic cooling systems and reduce unit costs for commercial buyers.
CE marking under the EU Machinery Directive and RoHS substance restrictions shape product design requirements for European market access, while FDA device classification influences clinical thermography applications in the United States. China's GB standards and NMPA oversight govern medical and industrial thermal imaging equipment sold domestically. Japan's METI energy efficiency programs stimulate building diagnostic deployments. Stakeholders must monitor evolving AI-enabled image analysis regulations and detector export control classifications that could restructure competitive access across defense and civilian segments.
Market Dynamics
Manufacturing plants are replacing scheduled manual thermal inspections with continuous fixed-camera monitoring, compressing maintenance cycles and forcing vendors to restructure service revenue models around software subscriptions rather than hardware replacement.
Growth Catalysts
- EU AI Act compliance requirements:Equipment manufacturers must integrate algorithmic transparency features into thermal imaging systems, creating upgrade cycles across European industrial facilities.
- Battery storage developer procurement:Distributed renewable operators require thermal monitoring for lithium-ion installations, expanding the buyer base beyond traditional utilities.
- Uncooled microbolometer maturation:Elimination of cryogenic cooling systems reduces unit costs and extends commercial viability to price-sensitive security applications.
Market Restraints
- Detector supply concentration:Advanced cooled detector fabrication relies on limited specialty semiconductor foundries in the United States and Europe, creating single-source vulnerability.
- Indium antimonide and mercury cadmium telluride cost volatility:Rare earth and exotic semiconductor material prices fluctuate with defense procurement cycles, compressing margins on high-performance systems.
- Optical glass substitution pressure:Germanium lens alternatives from chalcogenide glasses threaten traditional material supply chains for long-wave infrared optics.
Strategic Opportunities
- India building diagnostic penetration:Energy efficiency mandates under Bureau of Energy Efficiency programs stimulate first-time thermal inspection adoption in commercial real estate.
- Clinical thermography regulatory tailwind:FDA 510(k) pathway clarification for fever screening applications opens institutional healthcare procurement channels.
- AI-enabled predictive maintenance convergence:Machine vision algorithms fused with thermal data streams enable automated anomaly detection, differentiating vendor platforms.
Industry Challenges
- Thermography technician certification bottlenecks:ASNT and BINDT qualification timelines stretch 12-18 months, constraining service provider scaling.
- Legacy SCADA integration complexity:Fixed thermal monitoring systems require protocol translation layers for Modbus and OPC-UA industrial networks, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infrared Thermography Market |
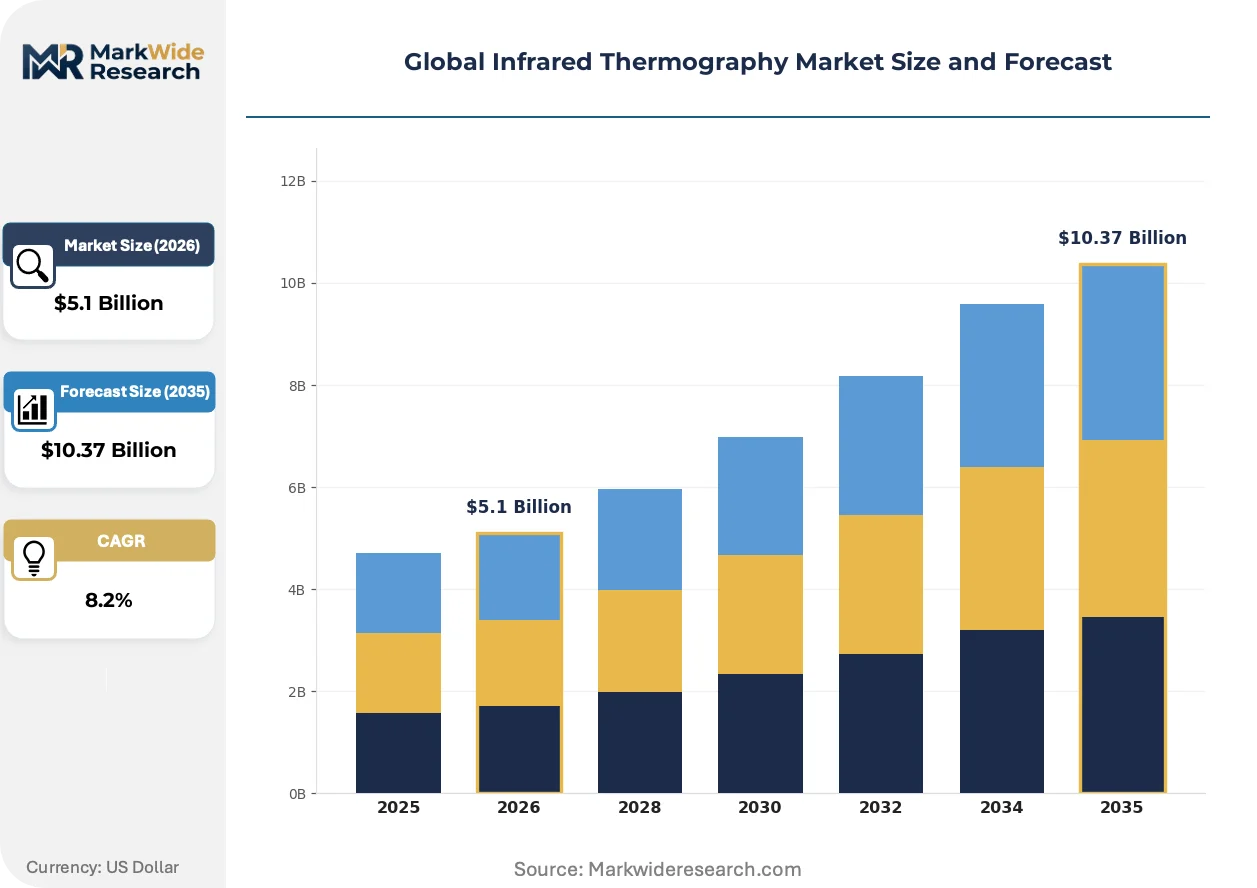
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.37 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Camera, Fixed Camera, Customized Camera, Smartphone Attachment Technology: Uncooled Detectors, Cooled Detectors, Focal Plane Array, Microbolometer Application: Electrical Inspection, Building Diagnostics, Predictive Maintenance, Research & Development End User: Manufacturing Plants, Energy Facilities, Public Safety Agencies, Scientific Institutions |
| Companies Covered | Teledyne FLIR LLC, Fluke Corporation, L3Harris Technologies, Inc., Leonardo DRS, Inc., BAE Systems, Jenoptik AG, Axis Communications AB, Zhejiang Dali Technology Co., Ltd., InfraTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infrared Thermography Market Strategic Shifts & Innovations
Software-defined thermal imaging is compressing hardware differentiation cycles, forcing vendors to compete on analytics platforms rather than detector specifications alone. Three developments are restructuring competitive positioning.
Multispectral sensor fusion is unifying thermal, visible, and near-infrared channels into single hardware packages. Automotive tier-one suppliers adopt these modules for pedestrian detection and battery thermal runaway monitoring. The technology is unifying previously separate camera installations, reducing per-vehicle sensor count and compressing supplier margins through volume consolidation.
REACH substance restrictions on lead and cadmium in optical coatings are forcing reformulation of infrared-transparent window materials. Germanium suppliers must certify alternative deposition processes or exit European medical device markets. Industrial equipment vendors in Germany and France accelerate qualification of chalcogenide substitutes to maintain CE marking compliance.
Continuous monitoring contracts are displacing periodic inspection services in process manufacturing. Food and pharmaceutical plants in the United States and Japan subscribe to thermal analytics platforms with guaranteed uptime clauses. Vendors absorb hardware capital expenditure while capturing recurring revenue, reversing traditional equipment sales economics.
Global Infrared Thermography Market Segmentation
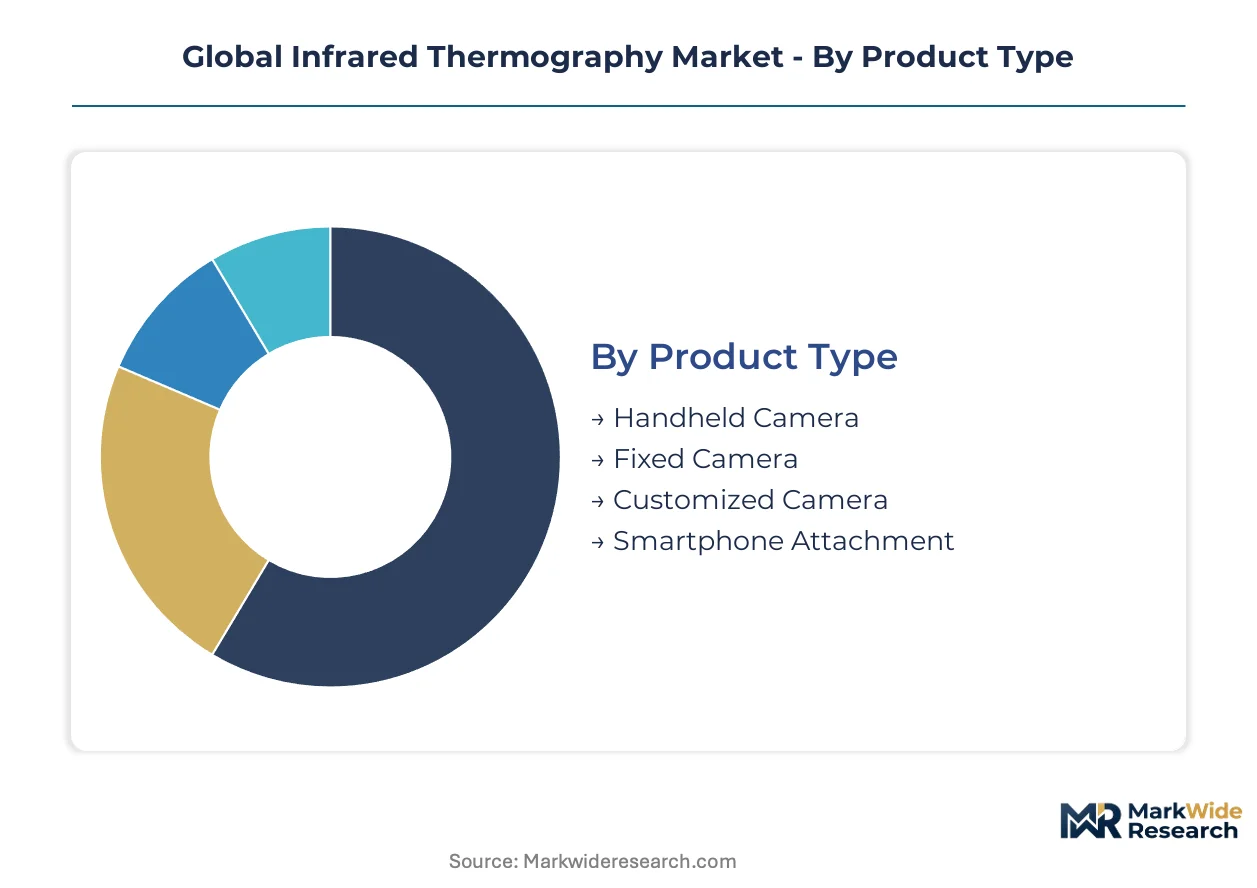
Segmentation reveals how infrared thermography vendors allocate R&D resources across hardware form factors and detector architectures. Product type and technology choices determine margin structures, while application and end-user splits expose where procurement budgets are concentrating fastest.
Product Type:
Supply concentration in detector fabrication favors vendors with scale economies in specific form factors.
- Handheld Camera:Portable units integrate uncooled microbolometer arrays with rechargeable power systems for field mobility. Electrical contractors in Germany and the United States drive replacement cycles as preventive maintenance programs expand beyond scheduled shutdowns. Battery chemistry improvements and ergonomic housing designs sustain hardware refresh demand.
- Fixed Camera:Permanent installations mount on production lines, substations, and server racks for continuous thermal monitoring. Japanese automotive plants and Chinese battery gigafactories deploy these systems to eliminate manual inspection labor. Ethernet connectivity and PoE power simplify integration with factory automation networks.
- Customized Camera:Modified housings and specialized optics serve defense, aerospace, and scientific research requirements. These units incorporate cooled detectors and precision calibration for quantitative radiometry.
- Smartphone Attachment:Compact modules clip to consumer mobile devices for entry-level thermal imaging. Price compression limits margin capture despite volume potential in building trades and outdoor recreation.
Today's leader: Handheld Camera. Tomorrow's challenger: Fixed Camera.
Technology:
Cost tier stratification separates volume commercial applications from premium defense and scientific systems.
- Uncooled Detectors:Microbolometer arrays operate at ambient temperature using vanadium oxide or amorphous silicon sensing layers. Elimination of Stirling cycle coolers reduces unit cost and power consumption for security and building diagnostic applications. Chinese manufacturers dominate wafer-level packaging for these detectors.
- Cooled Detectors:Indium antimonide and mercury cadmium telluride photodiodes require cryogenic cooling to achieve superior sensitivity and frame rates. United States and European foundries control epitaxial growth capabilities for these materials. Military procurement and gas imaging applications sustain demand despite price premiums.
- Focal Plane Array:Two-dimensional detector arrangements enable staring-array imaging without mechanical scanning. Readout integrated circuit design determines noise performance and dynamic range.
- Microbolometer:Thermal detector technology converts absorbed infrared radiation into resistance changes for signal processing. Pixel pitch reduction below 12 micrometers enables higher resolution without optical enlargement.
Uncooled Detectors capture current volume leadership. Cooled Detectors retain the steepest expansion trajectory in defense and scientific verticals.
Application:
Customer type diversity spans industrial maintenance, construction, and research institutions with distinct procurement workflows.
- Electrical Inspection:Thermographers identify loose connections, overload conditions, and insulation failures in switchgear and distribution panels. NFPA 70B maintenance standards in the United States mandate periodic thermal surveys for critical facilities.
- Building Diagnostics:Energy auditors locate air leakage, moisture intrusion, and insulation deficiencies in building envelopes. Germany's Building Energy Act and similar efficiency codes across the European Union stimulate inspection demand.
- Predictive Maintenance:Condition-based monitoring of rotating machinery, refractory linings, and process vessels prevents unplanned outages. Japanese steel mills and petrochemical complexes in the United States lead adoption of continuous thermal monitoring.
- Research & Development:Laboratories employ calibrated thermal imagers for materials characterization, combustion analysis, and biomedical studies. Academic and government research budgets in China and the United States fund precision instrument acquisition.
Electrical Inspection anchors near-term revenue. Predictive Maintenance is gaining share fastest as Industry 4.0 investments accelerate.
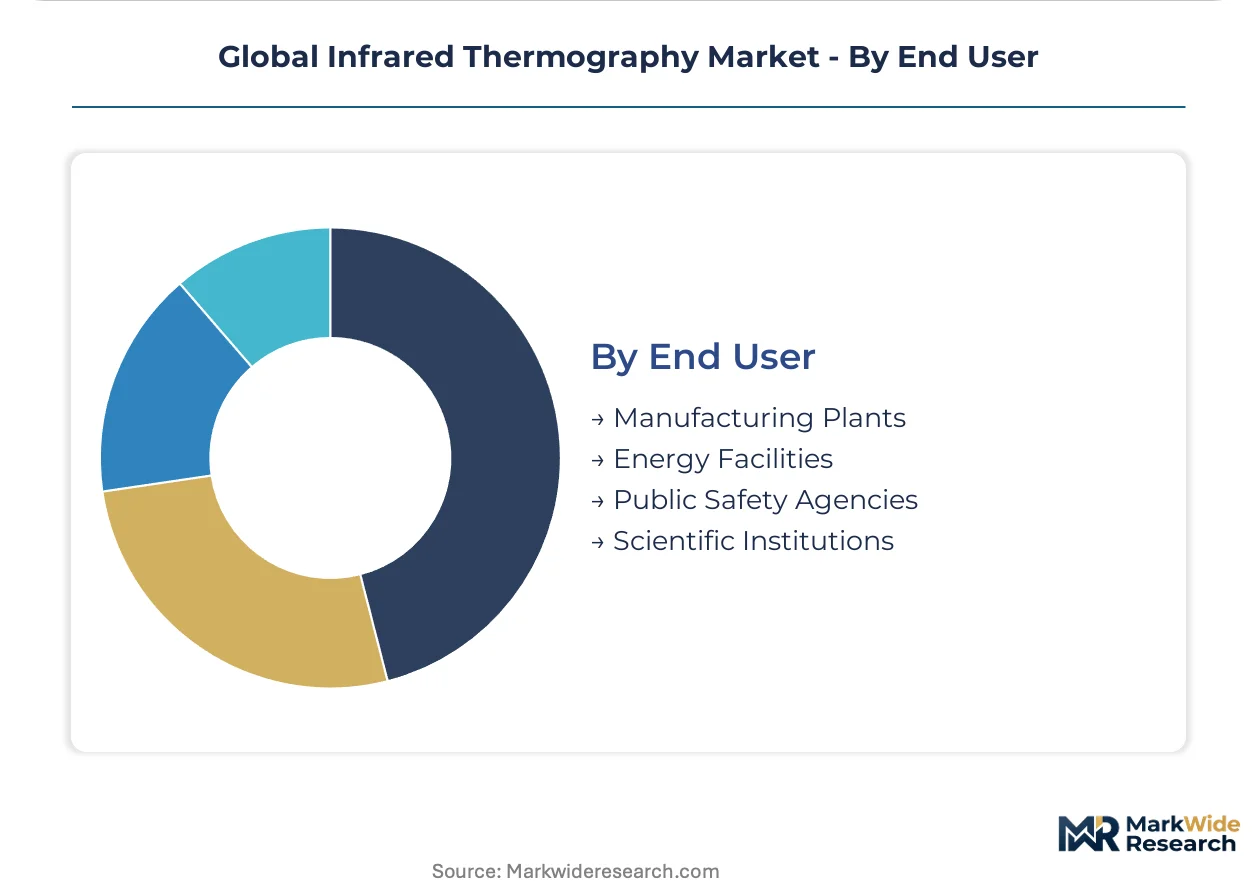
End User:
Geography determines regulatory compliance requirements and procurement channel structures.
- Manufacturing Plants:Automotive, semiconductor, and food processing facilities deploy thermal imaging for quality assurance and safety monitoring. German automotive OEMs and Chinese electronics assemblers represent concentrated demand clusters.
- Energy Facilities:Power generation, transmission, and renewable energy operators inspect electrical infrastructure and monitor battery storage installations. United States utilities and European grid operators expand thermal survey programs under reliability mandates.
- Public Safety Agencies:Fire departments, law enforcement, and search-and-rescue teams use thermal imagers for navigation through smoke and darkness. Municipal procurement cycles in the United States and equipment standardization across European emergency services drive replacement demand.
- Scientific Institutions:Universities, national laboratories, and observatories acquire calibrated systems for research applications. Funding agency priorities in astronomy, climate science, and materials research determine acquisition timing.
Manufacturing Plants dominate current procurement. Energy Facilities represent the fastest-climbing segment as battery storage deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation investments outpace those in China on a per-facility basis, yet China's battery gigafactory buildout generates larger absolute procurement volumes for fixed thermal monitoring systems.
United States
NFPA 70B maintenance standards mandate thermal surveys for critical electrical infrastructure, driving replacement demand among utilities and data center operators. FDA 510(k) pathway clarification accelerates clinical thermography adoption for fever screening in institutional healthcare settings. Texas and California host concentrated demand from oil refineries and semiconductor fabs deploying predictive maintenance programs.
Germany
The Building Energy Act stimulates thermal inspection adoption across commercial real estate portfolios seeking efficiency compliance. CE marking under the EU Machinery Directive and RoHS substance restrictions shape product design requirements for domestic and export-bound equipment. Automotive OEMs in Bavaria and Baden-Württemberg deploy continuous thermal monitoring across stamping and welding lines.
China
GB standards and NMPA oversight govern medical and industrial thermal imaging equipment sold domestically, while dual carbon goals accelerate energy efficiency investments. Battery storage developers require thermal monitoring for lithium-ion installations at gigafactory scale. Yangtze River Delta electronics assemblers and Pearl River Delta automotive plants represent concentrated procurement clusters.
Japan
METI energy efficiency programs stimulate building diagnostic deployments across commercial and industrial facilities. JIS standards certification requirements influence procurement specifications for domestic infrastructure projects. Automotive tier-one suppliers in Aichi Prefecture adopt multispectral sensor fusion modules for battery thermal runaway monitoring and pedestrian detection systems.
India
Bureau of Energy Efficiency programs under national efficiency mandates stimulate first-time thermal inspection adoption in commercial real estate and manufacturing. Maharashtra and Gujarat host expanding automotive and pharmaceutical manufacturing bases deploying predictive maintenance systems. CDSCO oversight governs medical thermography applications as clinical adoption accelerates in tertiary care institutions.
Global Infrared Thermography Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base separates into three strategic archetypes: defense-aerospace heritage players leveraging cooled detector capabilities, industrial maintenance specialists dominating handheld field service equipment, and cost-optimized Asian manufacturers capturing commercial security volumes. M&A activity concentrates on software analytics capabilities, while geographic expansion into India and Southeast Asia represents the dominant competitive move.
Within the defense-aerospace tier, Teledyne FLIR LLC and L3Harris Technologies, Inc. occupy positions anchored by cooled detector heritage and government procurement relationships. Fluke Corporation exemplifies the industrial maintenance specialist archetype with purpose-built handheld thermal imagers for electrical contractors. Zhejiang Dali Technology Co., Ltd. represents the cost-optimized manufacturing model competing aggressively in Asian commercial security markets.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Fluke Corporation |
| L3Harris Technologies, Inc. |
| Leonardo DRS, Inc. |
| BAE Systems |
| Jenoptik AG |
| Axis Communications AB |
| Zhejiang Dali Technology Co., Ltd. |
| InfraTec GmbH |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up detector specialists anchor supply discipline across the infrared thermography value chain, translating semiconductor foundry scarcity into tiered pricing power while constraining margin compression in uncooled microbolometer segments.
Pricing Analysis
Capacity additions in Chinese wafer-level packaging facilities are reshaping price floors for uncooled microbolometer arrays, compressing entry-level hardware margins while sustaining premiums on cooled detector systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical units from CE-marked industrial tools and unbranded security modules. Pricing pressure stems from smartphone attachment commoditization and chalcogenide glass substitution for germanium optics. Electrical contractors exhibit highest price sensitivity, while defense procurement channels absorb premium tiers without volume elasticity.
Supply Chain Analysis
Mercury cadmium telluride epitaxy rests on limited specialty foundries in the United States and Europe, tethering high-performance cooled detector output to defense procurement cycles. Indium antimonide substrates and germanium lens blanks draw from concentrated specialty material suppliers in Germany and Japan. Single-source vulnerability in advanced detector fabrication creates supply chain risk amid export control tightening. Distribution runs through authorized industrial distributors in developed markets and direct OEM relationships in Asian manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infrared thermography market reads as a late-cycle quality story, with procurement shifting toward AI-enabled predictive maintenance platforms that command subscription premiums over transactional hardware sales.
For Market Incumbents: Deploy software analytics capabilities as the primary defensive lever. Integrate machine vision algorithms with thermal data streams to differentiate against emerging pure-play AI entrants. Pursue backward integration into detector fabrication through foundry partnerships or captive supply agreements to secure cooled component access amid export control uncertainty. For New Entrants and Emerging Players: Enter via India's building diagnostic segment, where Bureau of Energy Efficiency mandates create first-mover whitespace absent entrenched vendor relationships. Target commercial real estate portfolios in Maharashtra and Gujarat with handheld camera bundles paired with technician certification programs. Anchor go-to-market strategy through energy audit consultancy partnerships rather than direct equipment distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial maintenance specialists lacking software recurring revenue, presenting consolidation targets for platform-building strategies. Long-term viability hinges on AI-enabled predictive maintenance convergence across the next decade. Monitor FDA 510(k) pathway expansion for fever screening applications as the signal triggering healthcare channel re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Software Analytics Platform Development | Machine vision integration with thermal data streams enables automated anomaly detection for manufacturing clients. |
| Detector Foundry Partnership | Cooled component supply security addresses single-source vulnerability in InSb and MCT epitaxial growth. |
| India Market Entry | Bureau of Energy Efficiency mandates stimulate first-time thermal inspection adoption in commercial real estate. |
| Chalcogenide Glass Qualification | REACH-compliant germanium substitutes maintain CE marking access for European medical device markets. |
| Continuous Monitoring Contract Transition | Subscription revenue models reverse traditional equipment sales economics in food and pharmaceutical plants. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermal imaging OEM product managers, plant maintenance directors at German automotive facilities, electrical contractor procurement leads, and defense aerospace procurement officers with secondary validation against SEC filings, EU Machinery Directive guidance documents, FDA 510(k) clearance databases, and customs trade data for detector and lens imports. Bottom-up unit economics triangulated against top-down market sizing across detector technology tiers.
Segment-weighting approaches applied differential growth assumptions across hardware form factors, detector architectures, and end-user industries throughout the forecast period. Product type splits modeled handheld camera replacement cycles against fixed camera installation acceleration. Technology tiers incorporated uncooled microbolometer maturation curves and cooled detector defense procurement cyclicality. CAGRs derived from installation base expansion rates and average selling price trajectory analysis.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time battery storage developer procurement data introduce uncertainty bands around energy facility segment projections. Forecasts reflect assumptions on AI regulatory clarity and detector export control stability. A small set of triggers—EU AI Act enforcement timing, FDA clinical thermography pathway expansion, and indium antimonide supply disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Laser Scanning Microscopes Market