
 Smart Visor Market | 2026-2036
Smart Visor Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Visor Market Insights
Modular visor configurations that separate display modules from sensor housings are broadening buyer choice across fleet and aftermarket channels. Robert Bosch GmbH leverages its automotive sensor integration expertise to anchor premium positioning in European OEM supply chains. Continental AG sustains R&D intensity across optical waveguide architectures. Gentex Corporation specializes in electrochromic dimming layers that extend its dominance in aviation and military visor applications.
A smart visor is a wearable optical device combining transparent or semi-transparent displays with embedded sensors, microprocessors, and wireless connectivity to overlay digital information onto the user's field of view while preserving environmental awareness. Manufacturing employs precision injection-molded polycarbonate substrates laminated with thin-film transistor backplanes and diffractive optical elements. Augmented reality visors command the dominant value share due to enterprise logistics and surgical navigation deployments, while wearable displays compete on portability for consumer gaming segments. Healthcare applications generate concentrated margin pools from FDA and EMA certification requirements that filter out uncertified entrants.
FDA device classification rules govern clinical smart visor deployments in the United States, while the EU AI Act and MDR frameworks impose algorithmic transparency and biocompatibility standards for European market access. ECHA REACH restrictions on rare earth elements in optical coatings are forcing reformulation of holographic waveguide materials. Stakeholders must monitor convergence between automotive HUD regulations and consumer electronics safety standards as product categories blur.
Market Dynamics
Automotive OEM procurement patterns are compressing development cycles for augmented reality visor platforms as heads-up display integration becomes standard in premium vehicle segments. Tier-1 suppliers must now synchronize optical waveguide roadmaps with platform engineering timelines measured in months rather than years.
Growth Catalysts
- EU Green Deal material mandates:The F-Gas Regulation and REACH restrictions on rare earth optical coatings are accelerating reformulation of holographic waveguide substrates, creating first-mover advantages for compliant suppliers.
- East Asian manufacturing cluster density:Concentrated precision molding and thin-film transistor backplane capacity across South Korea, Japan, and China reduces component lead times for visor assembly.
- Surgical navigation adoption:FDA and EMA certification pathways for clinical smart visors are generating concentrated margin pools that filter out uncertified competitors in healthcare verticals.
Market Restraints
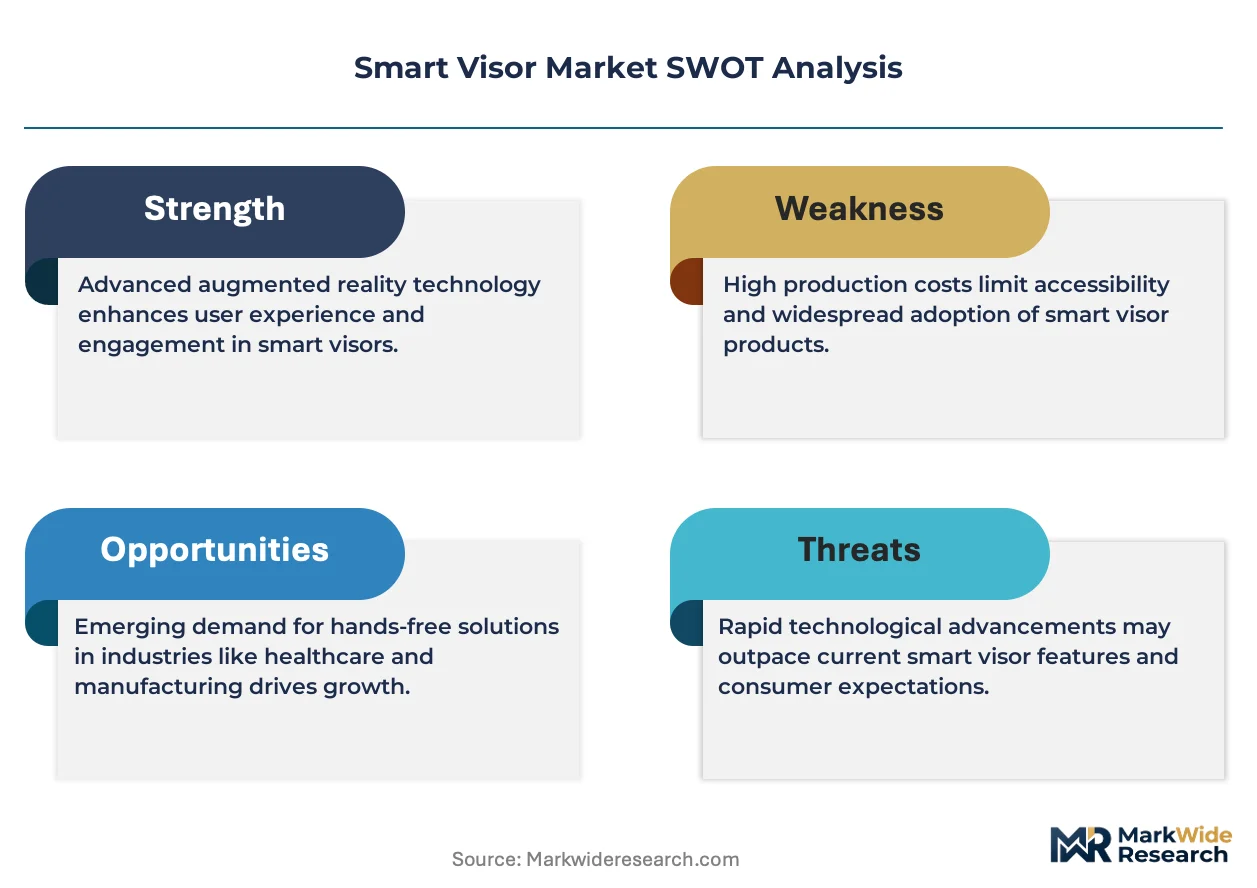
- Optical-grade polycarbonate feedstock volatility:Petrochemical input costs fluctuate with crude price cycles, compressing margin buffers for injection-molded substrate producers.
- Display component supply concentration:Diffractive optical element fabrication depends on specialized cleanroom capacity concentrated in German and Japanese precision optics houses.
- Algorithmic transparency requirements:The EU AI Act imposes documentation burdens on embedded vision processors that extend validation timelines for European market entry.
Strategic Opportunities
- Aftermarket fleet channel expansion:Modular visor configurations separating display modules from sensor housings are broadening buyer choice across commercial vehicle retrofit markets.
- Aviation electrochromic layering:Gentex Corporation's established military visor expertise creates technology transfer potential for civilian aerospace dimming applications.
- Consumer gaming portability segment:Wearable display form factors compete on weight and battery life against tethered augmented reality systems in immersive entertainment.
Industry Challenges
- Cross-functional optical-electronics talent scarcity:Waveguide design requires simultaneous mastery of geometric optics and semiconductor backplane engineering that few training programs produce.
- Automotive HUD-to-consumer electronics standard convergence:Stakeholders must monitor NHTSA safety standards and FCC emissions rules as product category boundaries blur.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Visor Market |
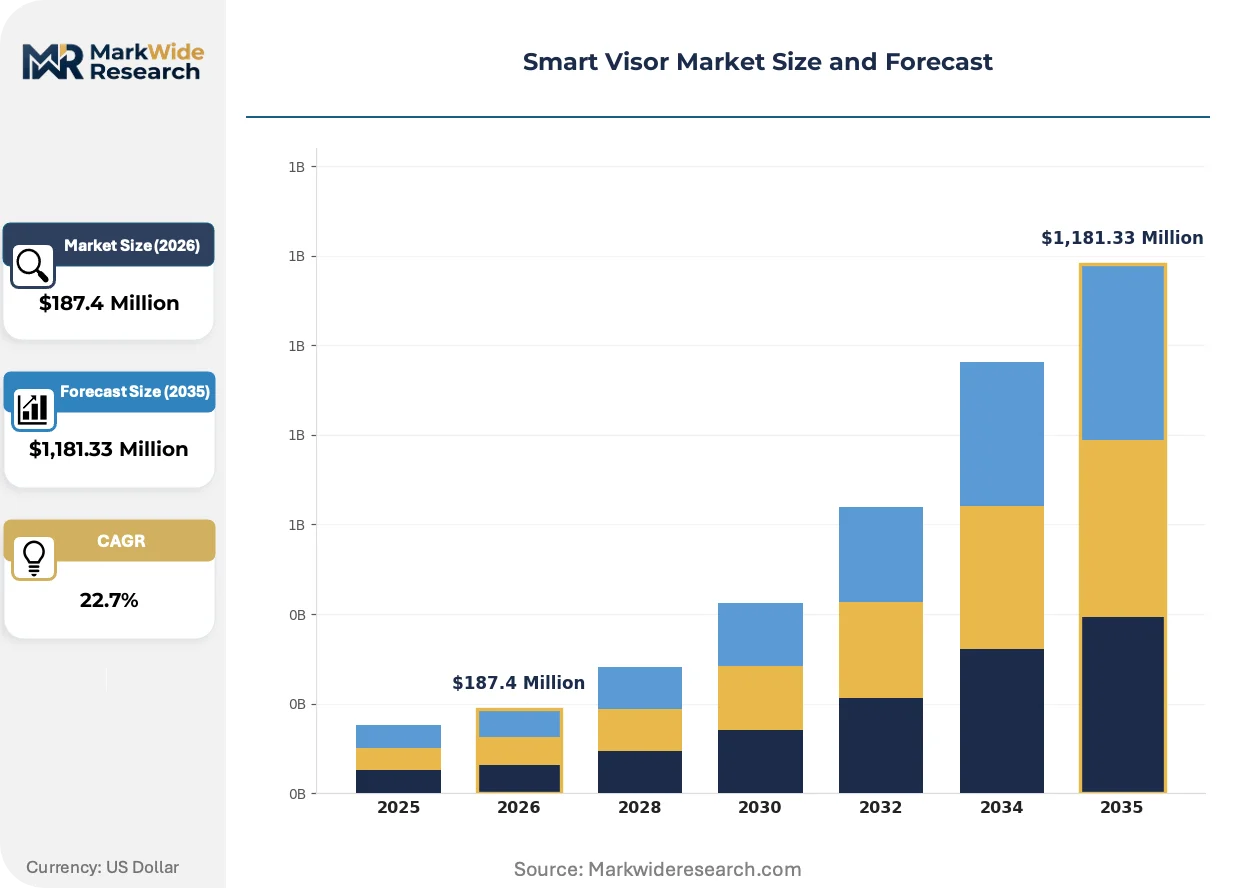
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Augmented Reality, Virtual Reality, Smart Glasses, Wearable Displays Application: Healthcare, Navigation, Gaming, Training End User: Consumers, Enterprises, Military, Education Connectivity: Bluetooth, Wi-Fi, Cellular, NFC |
| Companies Covered | Robert Bosch GmbH, Continental AG, Gentex Corporation, Magna International Inc., Valeo SA, Denso Corporation, Panasonic Holdings Corporation, ZF Friedrichshafen AG, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Visor Market Trends and Innovations
Waveguide architecture and sensor fusion protocols are undergoing rapid recombination as automotive, healthcare, and defense end-uses impose divergent performance requirements on shared component platforms.
Diffractive optical element manufacturing is modularizing across precision injection-molded polycarbonate substrates laminated with thin-film transistor backplanes. Automotive OEMs in Germany and Japan are adopting these stack configurations for heads-up display visors on compressed platform cycles. This modularity is enabling faster customization for fleet versus aftermarket channel specifications without full redesign.
ECHA REACH restrictions on rare earth elements in optical coatings are forcing holographic waveguide material reformulation across European supply chains. Manufacturers must document alternative coating chemistries through extended biocompatibility testing under MDR frameworks. Medical device visor segments face the steepest compliance cost escalation, with certification timelines extending eighteen to twenty-four months.
Enterprise logistics buyers are consolidating vendor relationships around full-stack augmented reality visor platforms rather than sourcing display modules and sensor housings separately. Automotive fleet managers in Japan and Germany now specify integrated solutions with unified warranty coverage. This bundling preference disadvantages component-specialist suppliers without backward integration into optical assembly.
Smart Visor Market Segmentation
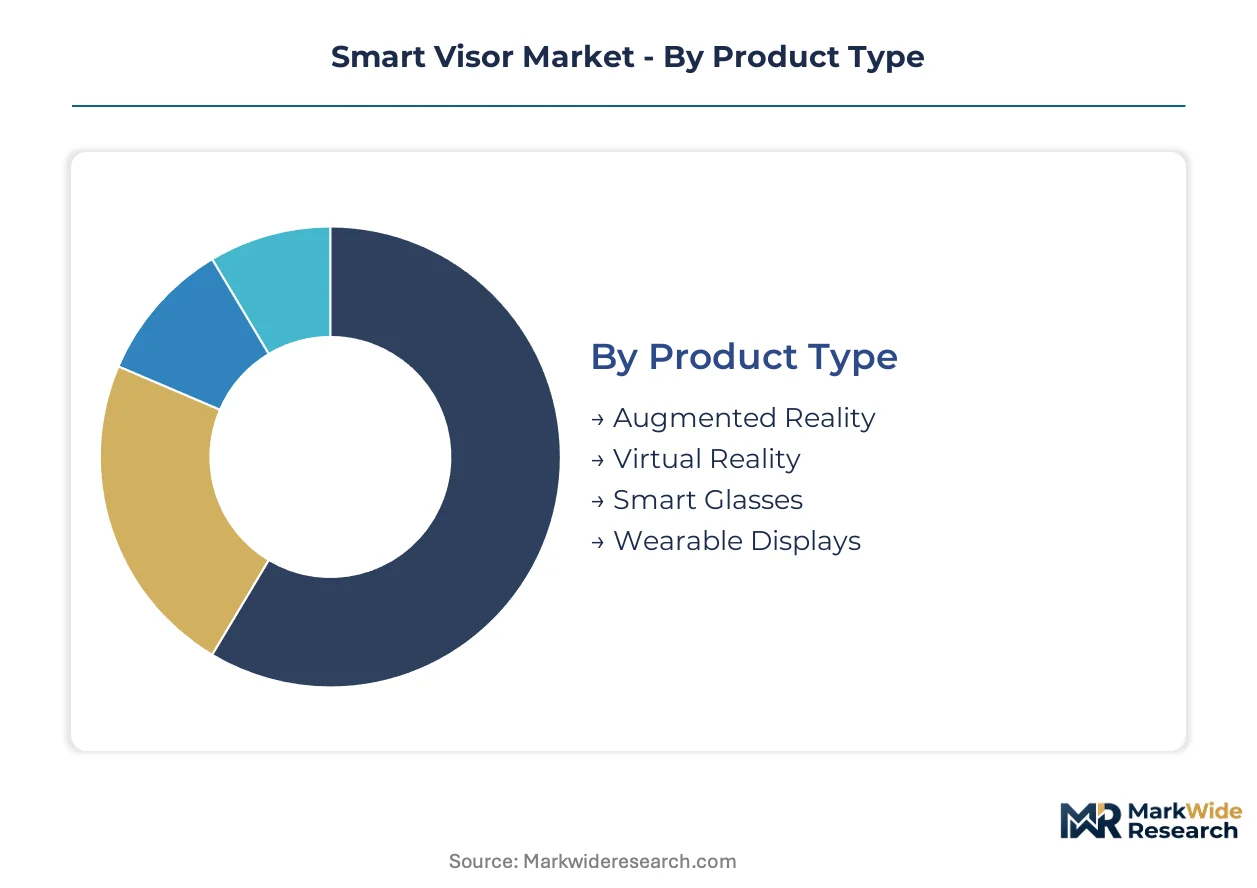
Smart visor segmentation reveals how certification burdens and application requirements fragment the competitive landscape. Product type determines optical architecture choices, while end-use verticals impose divergent regulatory timelines that reshape supplier economics.
Product Type:
FDA device classification rules and EU MDR frameworks impose distinct validation pathways across optical form factors, with clinical deployments facing eighteen-to-twenty-four-month certification windows.
- Augmented Reality:Transparent waveguide displays overlay digital information onto environmental vision while preserving situational awareness. Automotive OEMs in Germany and Japan anchor procurement for heads-up display integration, compressing platform development cycles to months rather than years.
- Virtual Reality:Fully immersive displays block external visual input to generate synthetic environments. Enterprise training programs in aviation and heavy manufacturing drive concentrated demand, with procurement favoring full-stack platforms over modular component sourcing.
- Smart Glasses:Lightweight optical frames with embedded micro-displays and camera modules. Consumer channel distribution concentrates on battery life and weight metrics.
- Wearable Displays:Portable screen devices prioritizing mobility over environmental transparency. Gaming segments compete on untethered operation against tethered AR systems.
Augmented Reality sits at the top of the volume ranking, with Wearable Displays climbing the fastest.
Application:
End-use verticals stratify around margin pools, with regulated healthcare deployments commanding premium pricing against price-sensitive consumer gaming segments.
- Healthcare:Surgical navigation and clinical visualization systems require FDA and EMA certification that filters out uncertified competitors. Biocompatibility testing under MDR frameworks extends material validation timelines for holographic waveguide coatings.
- Navigation:Automotive heads-up displays and enterprise logistics guidance systems. German and Japanese OEM procurement patterns synchronize optical roadmaps with compressed vehicle platform cycles.
- Gaming:Immersive entertainment applications prioritize portability and battery endurance over optical precision.
- Training:Military and industrial simulation deployments leverage full-immersion VR for procedural rehearsal. Defense procurement channels favor established electrochromic layering suppliers.
Healthcare commands the steepest margin tier, with Navigation expanding most quickly on automotive HUD standardization.
End User:
Customer type determines procurement modality, with enterprise and military buyers consolidating around unified warranty coverage while consumer channels fragment across retail and direct distribution.
- Enterprises:Logistics and industrial operators specify integrated AR platforms with consolidated vendor relationships. Fleet managers in East Asian manufacturing clusters now require backward integration into optical assembly capabilities.
- Military:Aviation and tactical visor applications demand electrochromic dimming layers with proven field reliability. Gentex Corporation's established defense supply relationships create technology transfer potential for civilian aerospace.
- Consumers:Individual purchasers prioritize weight reduction and untethered operation in gaming and lifestyle applications.
- Education:Institutional training programs balance cost constraints against durability requirements for shared device deployment.
Enterprises dominate current procurement volume, with Military representing the steepest expansion trajectory on defense modernization budgets.
Connectivity:
Wireless protocol selection shapes sensor fusion architectures and regulatory compliance burdens across electromagnetic emissions frameworks.
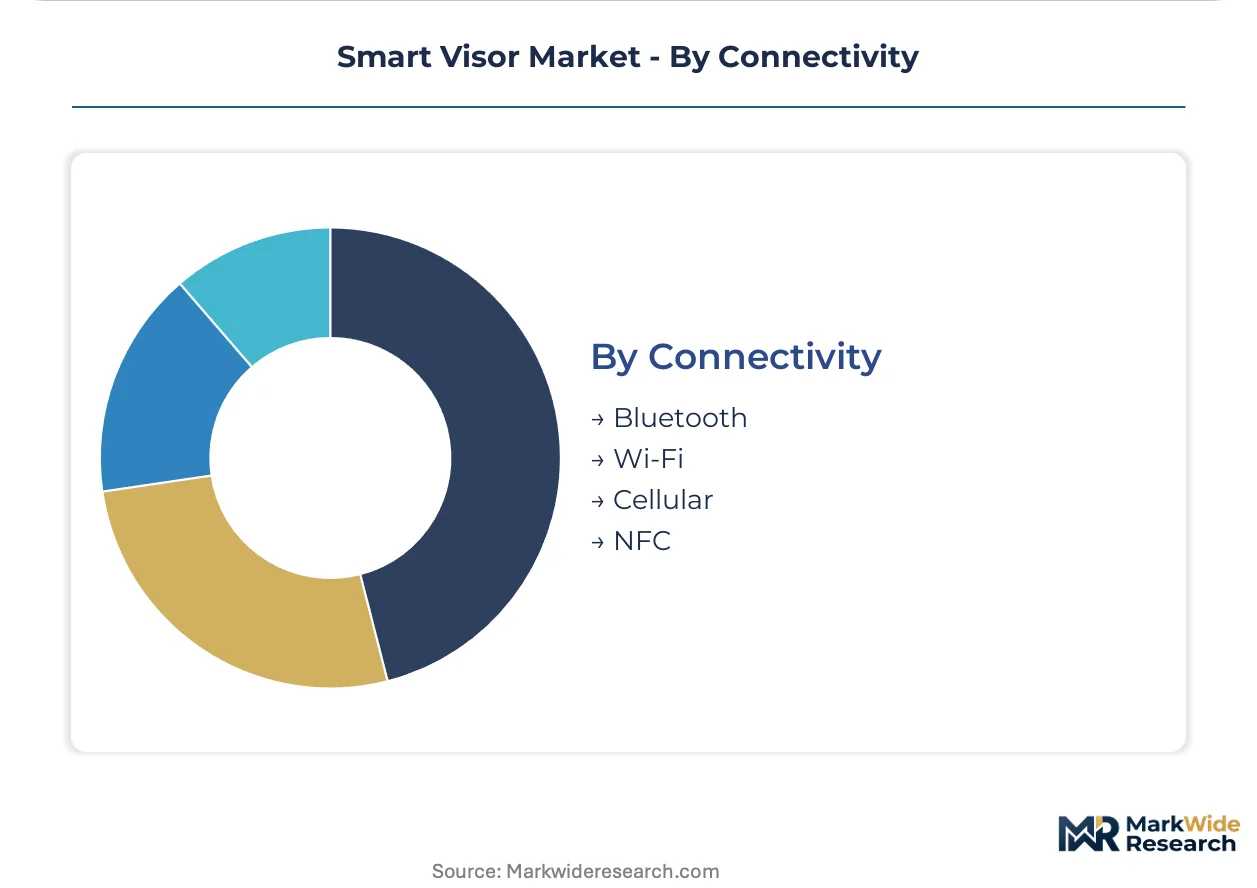
- Bluetooth:Low-energy protocols dominate consumer smart glasses for smartphone tethering. FCC emissions rules govern US market access for embedded radio modules.
- Wi-Fi:High-bandwidth local connectivity supports enterprise AR streaming from edge computing infrastructure.
- Cellular:5G-enabled visors enable standalone operation without smartphone dependency. NTT Docomo and South Korean carriers drive network-dependent feature roadmaps.
- NFC:Proximity authentication for secure enterprise and payment applications. Limited to access control and device pairing use cases.
Bluetooth anchors installed base volume, with Cellular gaining share fastest on standalone device architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing first scaled in German and Japanese industrial clusters during the 1990s, establishing the technical foundations for modern waveguide fabrication. Contemporary demand concentrates in East Asian electronics corridors, European automotive engineering centers, and North American defense-aerospace hubs.
United States
FDA device classification rules and FCC emissions standards govern clinical and consumer visor deployments. Military aviation procurement through defense modernization programs sustains electrochromic dimming technology demand. Greater Boston and Pacific Northwest corridors host precision optics R&D clusters serving surgical navigation applications.
Germany
Automotive OEM procurement from Stuttgart and Munich engineering centers compresses heads-up display development cycles to platform timelines measured in months. KBA vehicle safety standards intersect with EU AI Act algorithmic transparency mandates for embedded vision systems. Bavarian precision optics houses maintain specialized cleanroom capacity for diffractive optical element fabrication.
Japan
METI industrial technology roadmaps prioritize augmented reality integration across automotive and manufacturing sectors. PMDA medical device frameworks impose biocompatibility validation timelines for clinical visor deployments. Nagoya and Osaka manufacturing clusters concentrate thin-film transistor backplane capacity for display module assembly.
China
MIIT standards for wearable electronics and NMPA medical device regulations shape market access requirements. Dual carbon goals under MEE frameworks influence material selection for optical-grade polycarbonate substrates. Yangtze River Delta manufacturing corridors host precision molding capacity serving both domestic OEMs and export supply chains.
South Korea
MFDS medical device certification and national 5G infrastructure deployment enable standalone cellular-enabled visor architectures. Display component supply chains concentrate in Gyeonggi-do and Gwangju regions, reducing lead times for diffractive optical element integration. Domestic automotive groups accelerate procurement for augmented reality heads-up display platforms.
Smart Visor Market Competitive Landscape
The competitive structure tilts toward automotive Tier-1 suppliers with established OEM relationships. Three distinct archetypes populate the vendor landscape: diversified automotive electronics conglomerates with sensor integration capabilities, precision optics specialists with waveguide fabrication expertise, and electrochromic technology providers with defense-aerospace track records. Competitive positioning depends on backward integration into optical assembly and strategic partnerships with display panel manufacturers.
Among German automotive suppliers, Robert Bosch GmbH and Continental AG occupy positions anchored in European OEM supply chains. Gentex Corporation exemplifies the electrochromic specialization archetype with established military visor applications. These three entities represent contrasting strategic vectors: sensor-integrated platform provision, optical waveguide R&D intensity, and dimming layer technology transfer potential.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Gentex Corporation |
| Magna International Inc. |
| Valeo SA |
| Denso Corporation |
| Panasonic Holdings Corporation |
| ZF Friedrichshafen AG |
| Harman International |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both qualified holographic waveguide supply and premium-tier pricing access, as reformulated rare-earth-free optical coatings command material cost premiums that OEMs pass through to certified automotive and medical device buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Premium tiers capture FDA and EMA-certified medical device deployments, while economy tiers serve consumer gaming segments with price erosion running through untethered wearable displays. Fleet procurement managers in Germany and Japan exhibit lowest price sensitivity due to platform integration mandates.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese precision optics houses for diffractive optical element fabrication. Optical-grade polycarbonate substrates draw from South Korean and Chinese petrochemical feedstocks, while thin-film transistor backplanes hinge on Japanese and South Korean display component capacity. Tariff exposure on rare earth alternatives elevates reformulation costs. Distribution runs through Tier-1 automotive suppliers with captive OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Asian manufacturing clusters offer fifteen-to-twenty percent cost arbitrage on precision molding versus European cleanroom capacity, with South Korean and Japanese regulatory pathways compressing certification timelines relative to EU MDR frameworks.
For Market Incumbents: Anchor electrochromic layering expertise in defense-aerospace procurement channels against emerging waveguide specialists threatening premium positioning. Consolidate backward integration into thin-film transistor backplane assembly to defend margin buffers from optical-grade polycarbonate feedstock volatility. Prioritize REACH-compliant coating chemistry R&D to maintain European market access as ECHA restrictions tighten. For New Entrants and Emerging Players: Direct-to-fleet digital channels bypass entrenched Tier-1 supplier relationships in commercial vehicle retrofit markets. Modular visor configurations separating display modules from sensor housings present the most penetrable white-space, with aftermarket logistics operators seeking unified warranty coverage absent from component-specialist incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among precision optics specialists lacking backward integration into optical assembly. Long-term viability across the analysis window favors suppliers with captive cleanroom capacity and dual-use defense-civilian technology transfer potential. Watch automotive HUD platform standardization announcements as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Waveguide Reformulation | First-mover suppliers capture European OEM procurement as ECHA rare earth restrictions harden. |
| Automotive HUD Platform Integration | German and Japanese OEMs compress development cycles to months, favoring sensor-integrated Tier-1 partners. |
| Defense-to-Civilian Technology Transfer | Electrochromic dimming expertise migrates from military aviation to civilian aerospace certification pathways. |
| Aftermarket Fleet Channel Expansion | Modular configurations broaden buyer choice across commercial vehicle retrofit markets seeking unified warranty coverage. |
| Enterprise Logistics Full-Stack Bundling | Consolidated vendor relationships disadvantage component-specialist suppliers without optical assembly integration. |
Research Methodology
Multiple input streams — procurement director interviews at German and Japanese automotive OEMs, regulatory filings with FDA and EMA, and East Asian manufacturing cluster site assessments — were reconciled against secondary validation from customs data, SEC automotive supplier disclosures, and EU regulatory gazettes. Bottom-up and top-down triangulation cross-checked component-level bill-of-materials estimates against platform-level OEM procurement forecasts.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmentation by product type, application vertical, end-user category, and connectivity protocol. CAGRs were derived from fitted growth curves incorporating automotive HUD penetration rates, surgical navigation adoption timelines, and defense modernization budget trajectories as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for diffractive optical element manufacturing would alter the outlook. Forecasts reflect assumptions around REACH compliance timelines and automotive platform cycle compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Thermometer Market