
 Infrared Imaging Market | 2026-2036
Infrared Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Imaging Market Analysis
Aftermarket service revenue is reconfiguring margin capture across the infrared imaging value chain. Teledyne FLIR LLC leverages its installed base of thermal cameras to sustain recurring calibration and firmware upgrade income. L3Harris Technologies, Inc. anchors its defense contracts with long-term maintenance agreements that extend program profitability. Lynred competes through specialized sensor refurbishment services that occupy a niche between OEM replacement and third-party repair.
Infrared imaging captures thermal radiation emitted by objects at wavelengths between 0.75 and 14 micrometers, converting heat signatures into visible images through focal plane arrays fabricated from materials such as vanadium oxide or amorphous silicon. The technology serves industrial inspection, night vision, medical thermography, and autonomous vehicle sensing by detecting temperature differentials invisible to standard cameras. Thermal cameras dominate current revenue owing to mature manufacturing and broad applicability across surveillance and predictive maintenance. Imaging sensors represent the fastest-expanding category as automotive OEMs integrate thermal sensing into advanced driver-assistance systems. Software solutions for thermal analytics are emerging as a distinct margin pool, particularly in healthcare diagnostics where AI-assisted pattern recognition is improving early disease detection.
The US FDA regulates thermal imaging devices marketed for medical diagnostics under 21 CFR 892, while the FCC governs radio-frequency emissions from wireless-enabled thermal cameras. In Europe, the EU AI Act and GDPR impose compliance burdens on automated surveillance systems that process biometric thermal data. The US NHTSA and Germany's KBA are evaluating thermal sensor performance standards for automotive pedestrian detection. Stakeholders must monitor evolving cross-border certification requirements that could fragment product development roadmaps and testing budgets.
Market Dynamics
The uncooled microbolometer transition is collapsing unit economics across portable thermal imaging, forcing price compression that expands addressable demand while eroding legacy cooled-sensor margins.
Growth Catalysts
- Defense Procurement Modernization:US federal security spending prioritizes thermal surveillance for border infrastructure, creating sustained demand for ruggedized camera systems.
- EU AI Act Compliance:Automated surveillance mandates in Europe accelerate biometric thermal data processing requirements, driving sensor sophistication upgrades.
- Amorphous Silicon Fabrication:Advances in thin-film deposition processes reduce focal plane array production costs, enabling volume scaling for automotive integration.
Market Restraints
- Vanadium Oxide Supply Concentration:Limited qualified suppliers of high-purity VOx feedstock create input cost volatility and qualification bottlenecks for uncooled sensor manufacturers.
- Germanium Lens Dependency:Optical component sourcing concentrates among specialized German and Chinese fabricators, exposing downstream assemblers to geographic supply risk.
- Visible-Spectrum Substitution:Low-light CMOS sensors with AI enhancement threaten thermal imaging's cost-position in certain security and monitoring applications.
Strategic Opportunities
- India Industrial Automation:Manufacturing quality-control infrastructure remains underpenetrated by thermal diagnostics, presenting first-mover expansion potential for predictive maintenance systems.
- Healthcare Thermography Convergence:AI-assisted pattern recognition software layered onto thermal imaging creates new diagnostic revenue streams in early disease detection protocols.
- US IRA Clean Energy Incentives:Solar panel inspection and battery thermal monitoring qualify for manufacturing investment tax credits, accelerating utility-scale deployment.
Industry Challenges
- Multi-Domain Certification Complexity:Products serving medical, automotive, and defense end-uses simultaneously face overlapping FDA, NHTSA, and ITAR compliance timelines that extend commercialization cycles.
- Legacy System Integration Friction:Industrial facilities with established SCADA architectures require custom protocol bridges to incorporate thermal analytics, raising deployment engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Imaging Market |
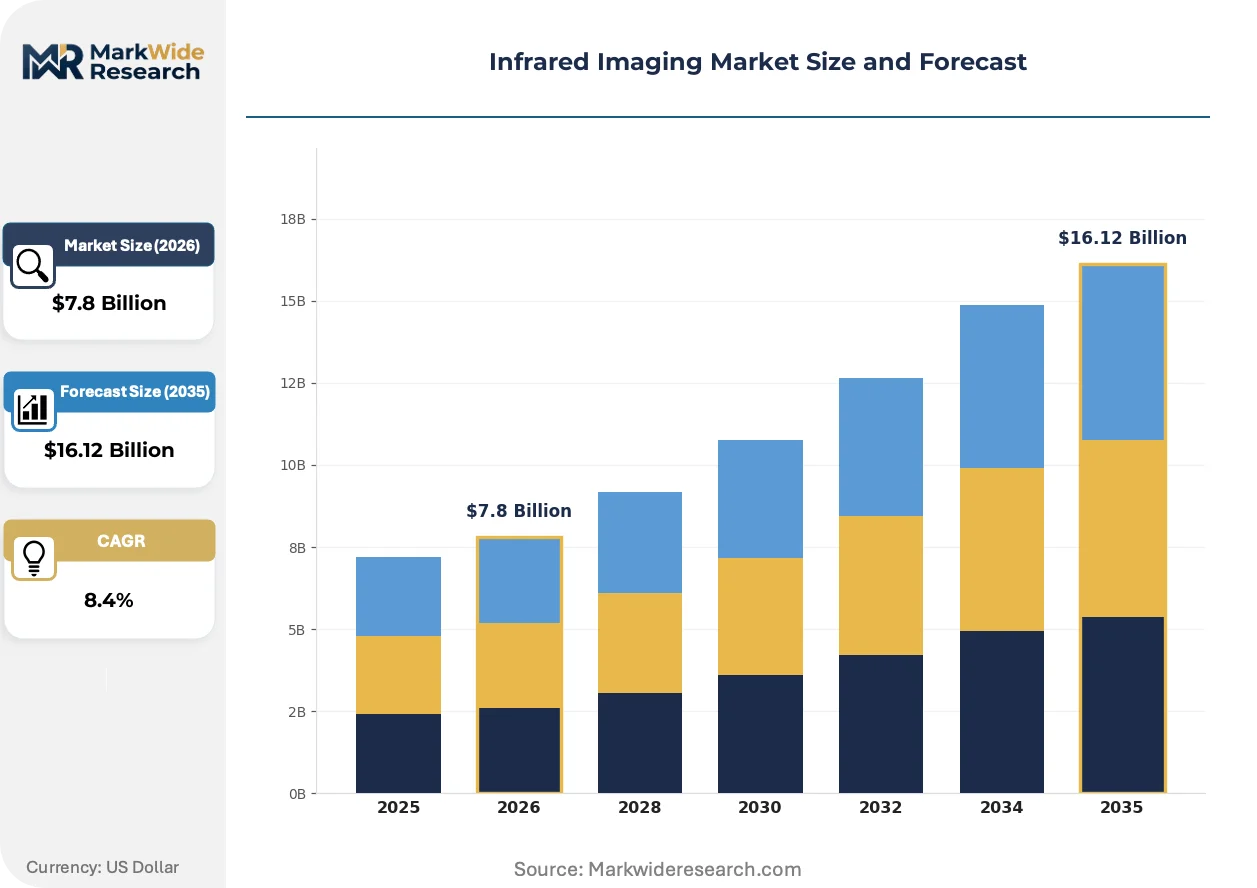
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cameras, Imaging Sensors, Night Vision Devices, Software Solutions Application: Surveillance, Aerospace, Automotive, Medical Diagnostics End User: Government, Healthcare, Manufacturing, Telecommunications Technology: Uncooled, Cooled, InGaAs, Microbolometer |
| Companies Covered | Axis Communications AB, RTX, Teledyne FLIR LLC, Lynred, BAE Systems, Fluke Corporation, L3Harris Technologies, Inc., Jenoptik AG, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Imaging Market Emerging Trajectories
Three intersecting developments are restructuring competitive advantage: sensor material economics, cross-border regulatory fragmentation, and service-model unbundling that separates hardware from analytics revenue.
Wafer-level packaging of amorphous silicon microbolometers is collapsing the cost floor for thermal camera modules. Automotive Tier-1 suppliers are integrating these sensors into pedestrian detection systems at price points previously reserved for premium night-vision equipment. The structural consequence is a bifurcation between commodity thermal hardware and value-captured software analytics.
REACH restrictions on hazardous substances in electronics are forcing reformulation of solder and coating materials used in focal plane array assemblies. German component manufacturers face extended qualification cycles for RoHS-compliant alternatives. Medical device exporters to Europe are absorbing compliance testing costs that divert R&D budgets from next-generation sensor development.
Industrial buyers are unbundling predictive maintenance contracts, separating thermal inspection hardware procurement from cloud-based analytics subscriptions. US manufacturing facilities increasingly lease camera fleets while purchasing AI-driven defect classification software separately. This consumption-pattern shift compresses OEM service revenue and elevates software-native competitors in margin capture.
Infrared Imaging Market Segmentation
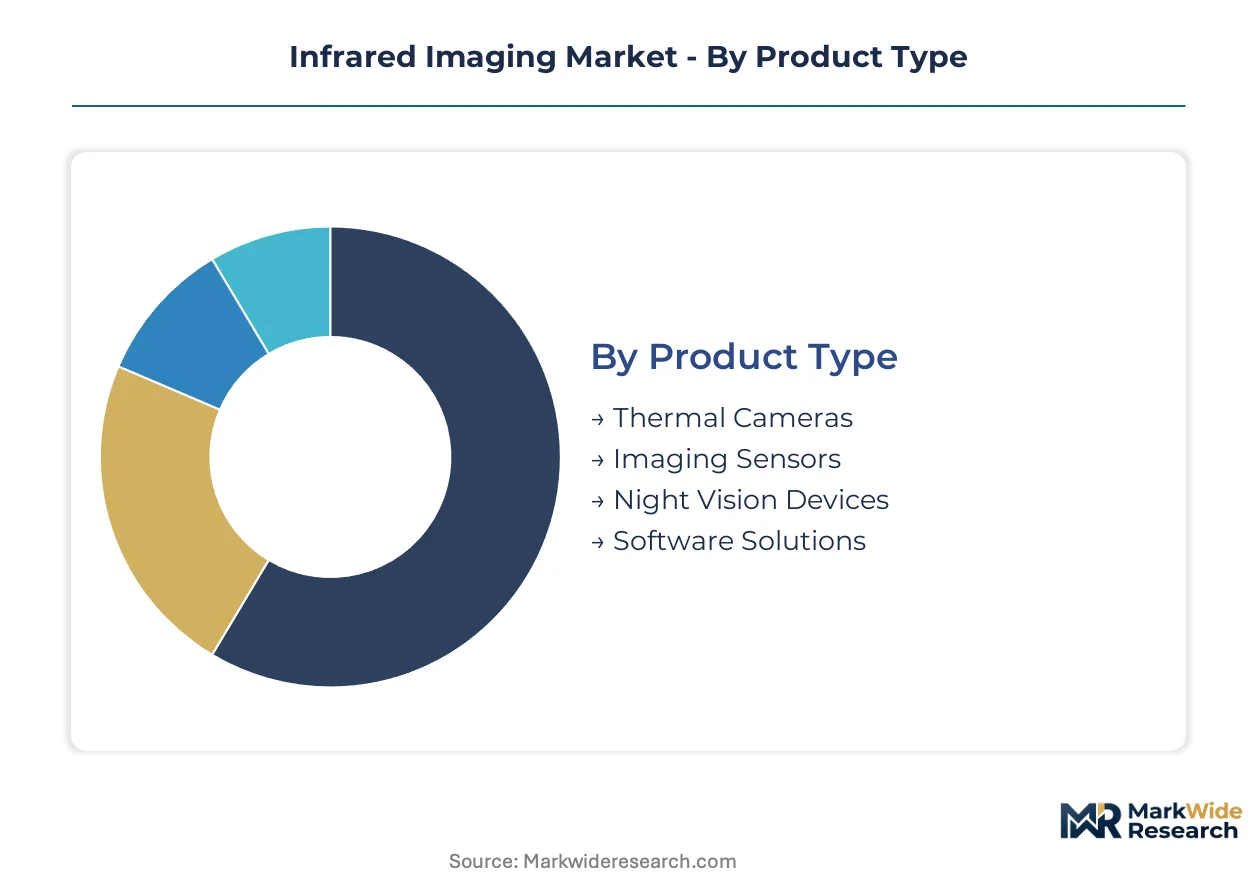
Segmentation in infrared imaging reveals divergent service intensity and margin profiles across hardware and software categories. Aftermarket calibration contracts, firmware subscriptions, and sensor refurbishment programs concentrate in specific product and technology segments, reshaping vendor profitability strategies.
Product Type:
After-sales service intensity varies dramatically across hardware versus software categories, with thermal cameras generating recurring calibration revenue while software solutions capture pure recurring license income.
- Thermal Cameras:These systems convert thermal radiation into visible images through vanadium oxide or amorphous silicon focal plane arrays. Demand concentrates in US federal border surveillance programs and European perimeter security installations, where ruggedized units require annual calibration cycles that lock in vendor service relationships.
- Imaging Sensors:Discrete detector arrays fabricated from microbolometer materials serve as the core sensing element for integration into larger systems. Automotive OEMs in Germany and Japan are embedding these sensors into pedestrian detection modules, driving volume scaling through thin-film deposition advances that reduce unit economics.
- Night Vision Devices:Image intensification systems amplify ambient light for military and law enforcement operators. Procurement runs through defense agencies with multi-year maintenance agreements.
- Software Solutions:Thermal analytics platforms process radiometric data for defect classification and diagnostic pattern recognition. Healthcare systems in the United States are layering AI-assisted detection algorithms onto existing camera infrastructure.
By volume, Thermal Cameras leads. By growth pace, Software Solutions is ahead.
Application:
Cost tier differentiation separates premium defense-specification systems from commercial off-the-shelf alternatives, with surveillance commanding price multiples over industrial predictive maintenance deployments.
- Surveillance:Fixed and portable thermal monitoring systems for perimeter security and law enforcement operations. US Customs and Border Protection deployments and EU critical infrastructure protection mandates sustain demand for weather-resistant, long-range detection capabilities.
- Aerospace:Avionics integration for navigation, landing assistance, and situational awareness in degraded visibility conditions. FAA certification requirements for commercial aircraft thermal systems create qualification barriers that protect incumbent suppliers.
- Automotive:Advanced driver-assistance systems incorporating thermal sensing for nighttime pedestrian and animal detection. NHTSA evaluation of performance standards is accelerating OEM integration timelines.
- Medical Diagnostics:Non-contact temperature measurement and physiological monitoring applications. FDA oversight under 21 CFR 892 governs diagnostic claims, while reimbursement coding determines hospital adoption velocity.
Surveillance captures the largest revenue share. Medical Diagnostics is climbing the fastest.
End User:
Procurement patterns diverge sharply between public-sector defense buyers with multi-year appropriations and private-sector manufacturing operators seeking operational expenditure flexibility through leased equipment.
- Government:Defense, homeland security, and public safety agencies procuring ruggedized thermal systems for tactical and surveillance operations. US federal security spending prioritizes border infrastructure modernization with sustained thermal camera deployments.
- Healthcare:Hospitals, clinics, and diagnostic centers employing thermal imaging for fever screening, vascular assessment, and oncology adjunct diagnostics. Reimbursement pathway clarity determines capital equipment purchase cycles.
- Manufacturing:Industrial facilities implementing predictive maintenance through thermal inspection of electrical panels, rotating machinery, and process equipment. US IRA clean energy incentives are accelerating solar panel and battery thermal monitoring adoption.
- Telecommunications:Network infrastructure operators monitoring equipment thermal loads and fiber optic cable integrity. 5G base station deployment is expanding inspection requirements for heat dissipation verification.
Government spending dominates absolute dollars. Manufacturing is expanding most quickly.
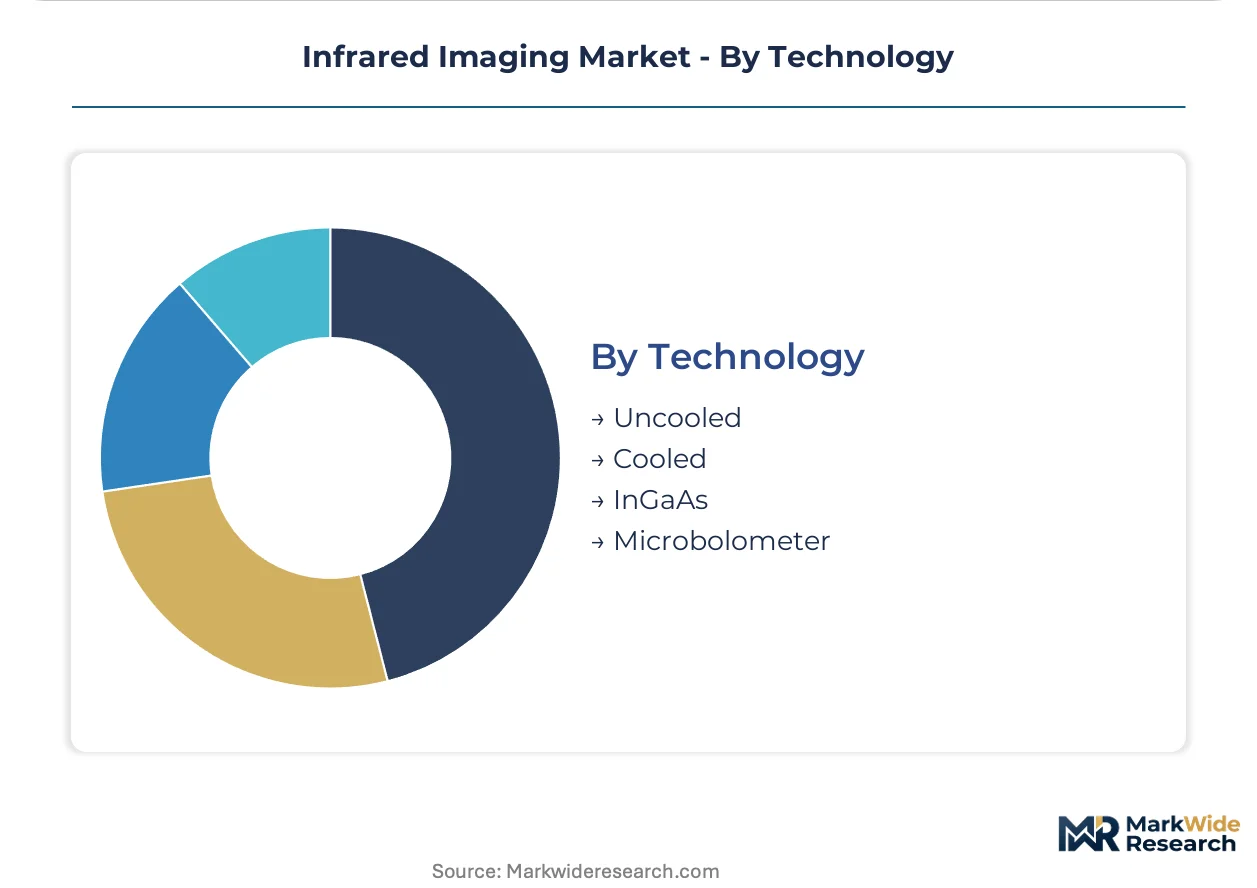
Technology:
Supply concentration in germanium lens fabrication and VOx feedstock qualification creates margin pressure points that differentiate technology tiers.
- Uncooled:Microbolometer arrays operating at ambient temperature without cryogenic cooling, enabling portable and low-power applications. Amorphous silicon fabrication advances are collapsing cost floors for automotive and consumer integration.
- Cooled:Photon detector systems requiring Stirling engine or thermoelectric cooling for enhanced sensitivity and spectral response. Defense and scientific applications in the United States and Europe sustain demand despite higher unit costs and maintenance requirements.
- InGaAs:Indium gallium arsenide detectors optimized for short-wave infrared wavelengths in machine vision and semiconductor inspection. Specialized industrial applications in Japan and Germany drive niche demand.
- Microbolometer:Thermal detector technology utilizing temperature-dependent resistance changes in vanadium oxide or amorphous silicon thin films. Wafer-level packaging advances are enabling volume scaling for cost-sensitive applications.
Uncooled leads by unit volume. Microbolometer is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor fabrication clusters concentrate in Germany, the United States, and Japan, where specialized foundries process vanadium oxide and amorphous silicon for focal plane arrays. This geographic concentration creates qualification bottlenecks for uncooled microbolometer supply chains. Defense procurement patterns and automotive integration timelines diverge sharply across these manufacturing centers.
United States
US Customs and Border Protection sustains demand for ruggedized thermal surveillance systems along southwestern border infrastructure. The FDA regulates medical diagnostic devices under 21 CFR 892, creating compliance barriers for hospital thermography adoption. Greater Boston hosts defense contractors integrating cooled sensors into avionics platforms for FAA-certified aircraft systems.
Germany
Automotive OEMs in Baden-Württemberg embed thermal sensors into pedestrian detection modules for luxury vehicle platforms. The KBA evaluates performance standards for advanced driver-assistance systems, accelerating NHTSA alignment timelines. Munich-area sensor fabricators face REACH compliance costs for RoHS-compliant solder reformulation in focal plane array assemblies.
Japan
Machine vision integrators in the Chubu region deploy InGaAs detectors for semiconductor wafer inspection applications. METI funding supports thin-film deposition advances that reduce amorphous silicon microbolometer costs. Osaka-based industrial automation specialists lease thermal camera fleets with separate cloud analytics subscriptions.
China
Domestic security spending drives thermal camera deployment for smart city surveillance infrastructure. MIIT standards govern wireless-enabled thermal camera radio-frequency emissions alongside FCC-equivalent certification. Shenzhen assembly clusters source germanium lenses from specialized German fabricators, exposing supply chain geographic risk.
India
Manufacturing quality-control infrastructure remains underpenetrated by thermal diagnostics for predictive maintenance applications. The PLI scheme incentivizes domestic electronics manufacturing, including sensor module assembly. Gujarat industrial corridors present first-mover expansion potential for solar panel and battery thermal monitoring systems qualifying under clean energy investment frameworks.
Infrared Imaging Market Vendor Landscape
Defense integrators and commercial sensor specialists split the market along procurement-cycle and volume-manufacturing vectors. Tiered concentration prevails: a handful of US and European contractors capture long-cycle defense programs, while Asian fabricators compete on cost for automotive and industrial volumes. Two archetypes dominate—vertically integrated prime contractors bundling hardware with maintenance agreements, and component-focused suppliers selling discrete detector arrays to system integrators. Consolidation through defense contract consolidation and foundry capacity expansion represents the primary competitive dynamic.
Among defense-anchored primes, Teledyne FLIR LLC and L3Harris Technologies, Inc. exemplify the integrated-service archetype, while Lynred occupies a position within the specialized sensor refurbishment tier. Component suppliers from the Axis Communications AB and Jenoptik AG cohort represent the commercial-industrial vector. RTX and BAE Systems sit within the aerospace-defense conglomerate grouping, leveraging platform integration relationships. Leonardo S.p.A. and Fluke Corporation anchor geographically distinct positions—Italian defense electronics and US industrial test equipment respectively.
| Leading Market Players |
|---|
| Axis Communications AB |
| RTX |
| Teledyne FLIR LLC |
| Lynred |
| BAE Systems |
| Fluke Corporation |
| L3Harris Technologies, Inc. |
| Jenoptik AG |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Vanadium oxide feedstock concentration among limited qualified suppliers creates input cost volatility that simultaneously compresses uncooled sensor margins and widens pricing spreads between defense-specification cooled systems and commoditized portable thermal cameras. This single-source dependency forces manufacturers to absorb qualification bottlenecks or pass through volatility, reshaping procurement relationships across tiered performance segments.
Pricing Analysis
ITAR export controls dictate the pricing tier structure by bifurcating defense-anchored systems with long-term maintenance bundling from commercial off-the-shelf alternatives sold on per-unit transactional terms. Price differentiation hinges on certification grade—FDA 21 CFR 892 compliance for medical diagnostics commands substantial premiums over industrial predictive maintenance units—and volume scale, where automotive OEM procurement of imaging sensors achieves cost compression through wafer-level packaging advances. Pricing pressure stems from amorphous silicon microbolometer cost collapse that erodes legacy cooled-sensor margins. Government defense agencies exhibit lowest price sensitivity due to appropriated multi-year programs, while Indian manufacturing operators seeking leased equipment flexibility demonstrate highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Export control regimes including ITAR and EAR restrictions limit qualified flows of cooled sensor technology and focal plane array fabrication equipment, concentrating advanced manufacturing in the United States, Germany, and Japan. Raw material dependencies center on high-purity vanadium oxide feedstock, germanium lens blanks from specialized German fabricators, and amorphous silicon thin-film deposition equipment. Supply chain risk manifests as single-source vulnerability in germanium optical component sourcing that exposes downstream assemblers to geographic concentration. Distribution runs through defense prime contractors with integrated service agreements for government end-users, alongside component suppliers selling discrete detector arrays to automotive Tier-1 and industrial system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against low-light CMOS sensors with AI enhancement that threaten thermal imaging's cost-position in security and monitoring applications. Incumbents must fortify around performance advantages that visible-spectrum alternatives cannot replicate.
For Market Incumbents: Pre-empt visible-spectrum substitution by deepening performance differentiation in applications where temperature differential detection remains irreplaceable—medical thermography and autonomous vehicle pedestrian detection—while capturing recurring software analytics revenue to offset hardware margin compression. Prioritize backward integration into amorphous silicon wafer-level packaging capacity to defend cost positions in automotive volume segments. Anchor defense contracts with predictive maintenance agreements that extend program profitability beyond initial procurement cycles.
For New Entrants and Emerging Players: Build out predictive maintenance service capabilities targeting India's underpenetrated manufacturing quality-control infrastructure, where first-mover expansion potential exists for solar panel and battery thermal monitoring systems qualifying under clean energy investment frameworks. Pursue white-space in healthcare AI-assisted pattern recognition software layered onto existing camera infrastructure, separating analytics subscriptions from hardware procurement. Position through cloud-based thermal defect classification platforms that industrial buyers increasingly prefer over bundled OEM service contracts.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors component suppliers with captive amorphous silicon fabrication capabilities over legacy cooled-sensor defense primes facing margin erosion. Long-term viability over the next decade hinges on software-native competitors capturing analytics revenue unbundled from hardware. Monitor NHTSA thermal sensor performance standard finalization as the critical inflection signal that will accelerate or delay automotive OEM integration timelines and reshape volume forecasts.
| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Amorphous silicon microbolometer cost collapse enables automotive pedestrian detection integration at mass-market price points. |
| AI-Assisted Diagnostic Software Development | FDA 21 CFR 892-compliant pattern recognition platforms create recurring revenue streams in hospital thermography adoption. |
| Defense Maintenance Agreement Extension | Long-term service contracts with US Customs and Border Protection sustain profitability beyond ruggedized camera procurement cycles. |
| India Manufacturing Partnership | PLI scheme incentives support domestic sensor module assembly for predictive maintenance expansion in Gujarat industrial corridors. |
| REACH Compliance Reformulation | RoHS-compliant solder qualification in German focal plane array assemblies maintains European market access against regulatory restriction. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense procurement databases, automotive Tier-1 supplier disclosures, FDA 510(k) filings, and trade flow records for vanadium oxide and germanium optical components. Primary interviews engaged thermal camera engineering directors, defense contract procurement officers, hospital biomedical equipment managers, and automotive ADAS platform engineers. Secondary validation drew from SEC 10-K segment disclosures, EU public procurement notices for border surveillance infrastructure, and METI-funded thin-film deposition research publications. Bottom-up demand modeling across end-use segments was triangulated against top-down supply-side capacity assessments for focal plane array fabrication.
Forecast inputs incorporate technology transition curves for uncooled microbolometer adoption, defense appropriation trajectories for US federal security spending, and automotive integration timelines pending NHTSA performance standard evaluation. Segmentation dimensions modeled include product type, application, end user, and technology tier, with additional granularity on regulatory compliance requirements across medical, automotive, and defense verticals. CAGRs were derived from volume-price elasticity functions calibrated to historical substitution patterns between cooled and uncooled sensor architectures.
Stress conditions across vanadium oxide supply disruption, REACH restriction expansion, and visible-spectrum AI enhancement performance breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget continuity, automotive OEM thermal sensor adoption curves, and healthcare reimbursement pathway development. Material shifts in ITAR export control scope or NHTSA regulatory finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Photography Ring Flash Market
Imaging
Handheld Imaging Systems Market
Imaging
PET Imaging Systems Market
Imaging
Photoacoustic Imaging Market
Imaging
Thermal Imaging Market
Imaging
Global in Ceiling Camera Market
Imaging
Hyperspectral Imaging Market
Imaging
Pico Projector Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
360-Degree Camera Market
Imaging
Global Whole Slide Imaging Market
Imaging
Europe Machine Vision Systems Market
Imaging
High-Power Objective Lens Market
Imaging
Automotive Compact Camera Module Market
Imaging
Automotive 3D Imaging Market
Imaging
Machine Vision Camera Market