
 ASEAN Cyber Security Market | 2026-2036
ASEAN Cyber Security Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Cyber Security Market Outlook
Mid-sized financial institutions are redrawing the buyer landscape as they displace large enterprises as the fastest-growing procurement segment in ASEAN cyber security. Ensign InfoSecurity anchors its position through deep vertical integration into managed detection and response services across Singapore and Malaysia. IBM Corporation leverages its hybrid cloud security portfolio to compete for multi-country government contracts. Fortinet, Inc. specializes in converged network-firewall appliances that dominate price-sensitive deployments in Indonesia and Vietnam.
ASEAN cyber security encompasses the technologies, services, and governance frameworks that protect digital assets across network, endpoint, application, and cloud layers from unauthorized access, disruption, or data exfiltration. Core functional parameters include real-time threat intelligence ingestion, sub-millisecond anomaly detection thresholds, and automated incident response orchestration that aligns with regionally fragmented data sovereignty requirements. Cloud Security leads solution type investment as ASEAN enterprises migrate workloads to hyperscale providers, while Managed Services captures expanding margin pools by addressing chronic talent shortages in local security operations centers. Endpoint Security remains mature in Singapore and Malaysia but accelerates in Philippines and Vietnam where device proliferation outpaces internal security staffing.
Singapore's Cyber Security Agency, Thailand's National Cyber Security Agency, and Indonesia's BSSN enforce mandatory incident reporting and baseline protection standards that shape vendor product roadmaps and customer procurement specifications. The EU AI Act's extraterritorial reach into ASEAN-based multinationals is forcing alignment of automated threat detection algorithms with emerging transparency requirements. Stakeholders must monitor regulatory divergence between ASEAN member states as compliance fragmentation becomes the primary determinant of regional go-to-market economics.
Market Dynamics
Mid-sized financial institutions across Southeast Asia are redrawing procurement patterns as they displace large enterprises as the fastest-growing buyer segment, forcing vendors to recalibrate pricing and service tiers for smaller deployment footprints.
Growth Catalysts
- Singapore's PDPA Amendments:Mandatory breach notification rules are compelling regional headquarters to upgrade data governance infrastructure, creating pull-through demand for adjacent security services.
- Indonesia's Digital Economy Expansion:E-commerce and fintech transaction volumes are multiplying attack surfaces for critical infrastructure operators facing escalating ransomware exposure.
- Cloud Migration Acceleration:ASEAN enterprises shifting workloads to hyperscale providers require native security controls, expanding addressable market for cloud-native detection platforms.
Market Restraints
- Chronic Talent Scarcity:Certified security operations analysts command premium wages in Singapore and Malaysia, compressing margins for managed service providers.
- Regulatory Fragmentation:Divergent data localization mandates across Thailand's Cybersecurity Act and Vietnam's cybersecurity decree force product customization that dilutes economies of scale.
- Price-Sensitive Procurement:State-owned enterprises in Indonesia and Vietnam prioritize converged network-firewall appliances over best-of-breed solutions, limiting premium vendor penetration.
Strategic Opportunities
- Philippines Endpoint Security Gap:Device proliferation across banking and telecommunications sectors outpaces internal security staffing, creating whitespace for automated endpoint detection and response.
- EU AI Act Extraterritorial Reach:ASEAN-based multinationals must align automated threat detection algorithms with emerging transparency requirements, opening compliance advisory revenue streams.
- Managed Detection and Response Convergence:Integration of threat intelligence platforms with 24/7 SOC outsourcing addresses chronic capability gaps among mid-market buyers.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Vendors must obtain separate approvals from Singapore's Cyber Security Agency, Thailand's National Cyber Security Agency, and Indonesia's BSSN, extending sales cycles.
- Legacy Infrastructure Integration:Established banks in Malaysia and Singapore operate heterogeneous technology stacks that resist standardized security orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Cyber Security Market |
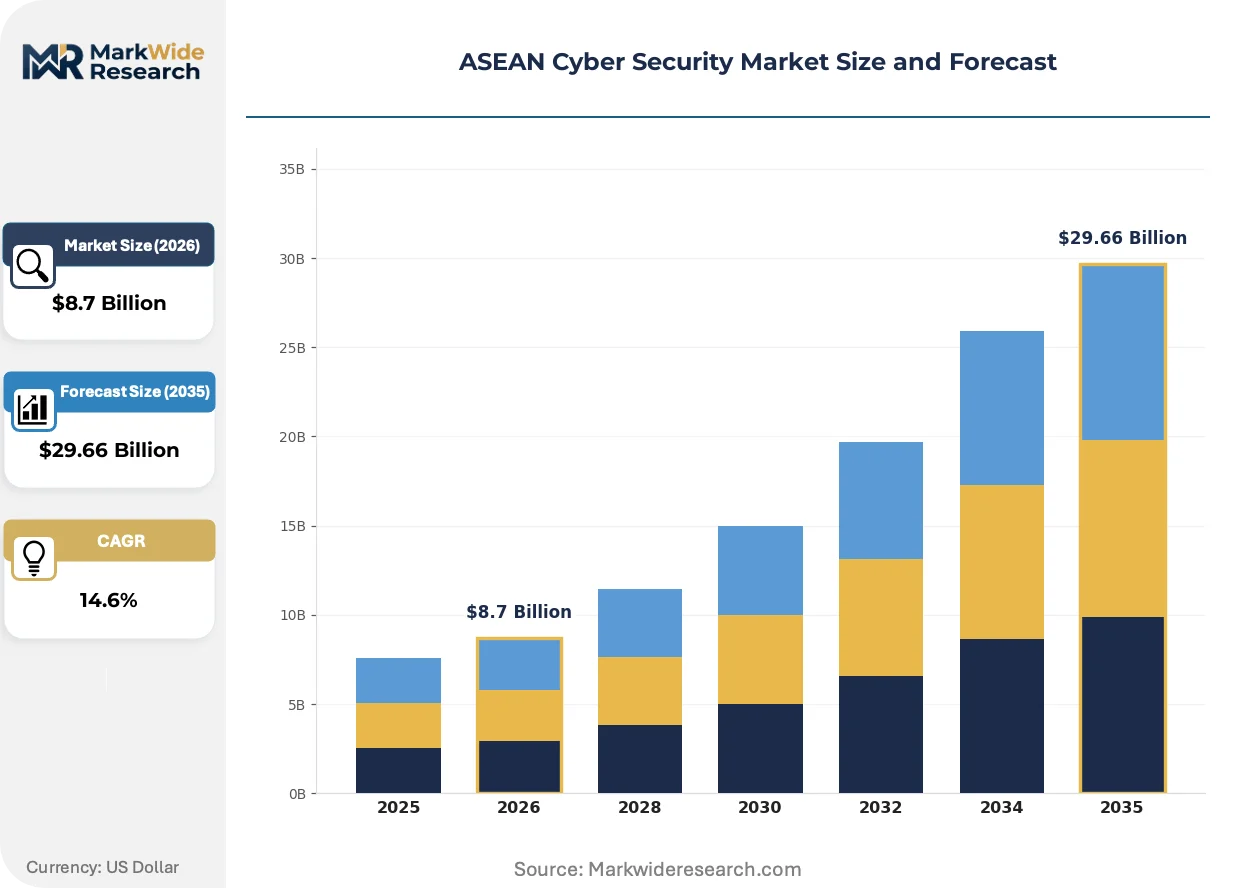
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Endpoint Security, Network Security, Application Security, Cloud Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, BFSI, Government, Education Threat Type: Malware, Phishing, Ransomware, Insider Threats |
| Companies Covered | Fujitsu Thailand Co., Ltd., Info Security Consultants Co., Ltd., IBM Corporation, Vigilant Asia (M) Sdn Bhd, Dell Technologies, Inc., Cisco Systems, Inc., Red Sky Digital Ventures Ltd., Ensign InfoSecurity, Fortinet, Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Cyber Security Market Strategic Shifts
Security architecture across Southeast Asia is pivoting from perimeter defense to zero-trust frameworks, driven by distributed workforces and multi-cloud environments that render traditional network boundaries obsolete.
Extended detection and response platforms are fragmenting the managed security services landscape by embedding automated investigation and remediation directly into endpoint and cloud workloads. Regional banks and telecommunications operators are adopting these capabilities fastest, compressing demand for standalone security information and event management deployments. The technology is fragmenting vendor competitive positions by elevating native integration over point-product superiority.
Thailand's National Cyber Security Agency now mandates baseline protection standards and incident reporting timelines that reshape vendor product roadmaps. Financial institutions and critical infrastructure operators face penalties for non-compliance, accelerating procurement of certified threat detection platforms. The regulation is forcing alignment between local system integrators and international security vendors to meet certification requirements.
Security procurement is consolidating around outcome-based contracts that tie vendor compensation to measurable mean-time-to-detect and mean-time-to-respond metrics. Mid-sized enterprises in Indonesia and Vietnam are displacing traditional perpetual license purchases with subscription models that transfer operational risk to service providers. This shift is most visible in banking and healthcare verticals where regulatory scrutiny of security performance is intensifying.
ASEAN Cyber Security Market Segmentation
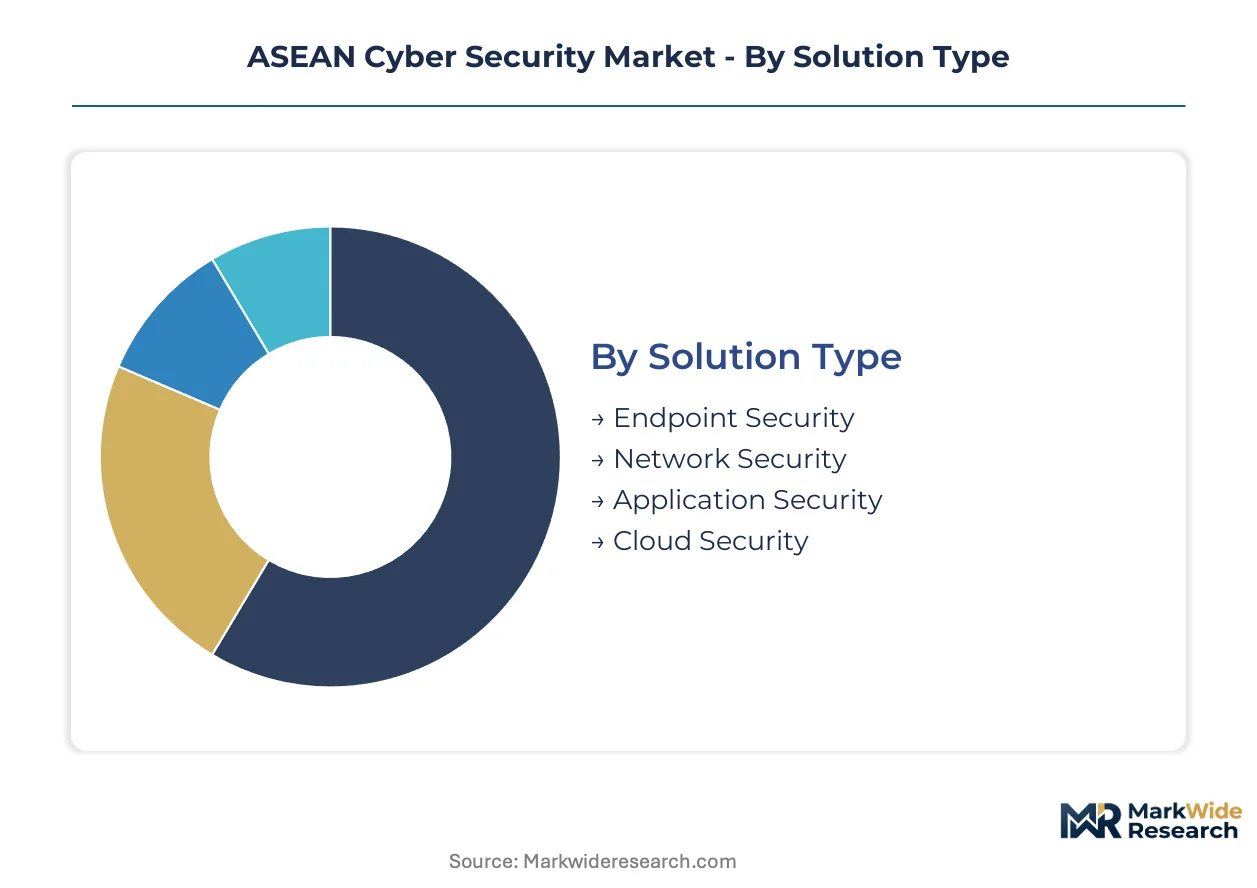
Segmentation reveals how procurement patterns diverge across ASEAN member states. Cloud migration timelines, regulatory maturity, and talent availability create distinct demand profiles that vendors must address through differentiated channel strategies.
Solution Type:
Channel mix varies sharply by solution complexity. Cloud Security and Managed Services flow predominantly through systems integrators and MSSPs, while endpoint and network products reach buyers via direct vendor relationships and value-added distributors.
- Cloud Security:Native controls for hyperscale workloads including container protection, cloud security posture management, and infrastructure-as-code scanning. Demand concentrates in Singapore and Malaysia where enterprise cloud migration has matured, driven by PDPA compliance mandates for data governance infrastructure.
- Endpoint Security:Agent-based protection for laptops, servers, and mobile devices with behavioral analysis and automated remediation. Expansion concentrates in Philippines and Vietnam where device proliferation across banking and telecommunications outpaces internal security staffing.
- Network Security:Perimeter defense through next-generation firewalls, intrusion prevention, and secure access service edge. Indonesia's state-owned enterprises prioritize converged network-firewall appliances for price-sensitive procurement.
- Application Security:Code scanning, runtime protection, and API security for custom and third-party software. Thailand's Cybersecurity Act baseline standards accelerate certified platform adoption.
Network Security dominates installed base. Cloud Security is where expansion concentrates.
Deployment Model:
Cost tier segmentation separates premium managed offerings from economy self-managed deployments. Subscription pricing for cloud and hybrid models displaces perpetual licenses as mid-sized buyers transfer operational risk.
- Managed Services:24/7 security operations center outsourcing with threat hunting, incident response, and compliance reporting. Singapore and Malaysia absorb premium pricing due to chronic certified analyst scarcity compressing in-house operations viability.
- Cloud-Based:SaaS-delivered controls with elastic scaling and vendor-managed infrastructure. Indonesia's fintech sector adopts fastest as digital transaction volumes multiply attack surfaces.
- Hybrid:Split workloads across on-premises and cloud with unified policy orchestration. Thailand's National Cyber Security Agency incident reporting timelines force consistent control deployment.
- On-Premises:Self-managed hardware and software within customer data centers. Legacy banks in Malaysia and Singapore retain substantial footprints due to heterogeneous technology stack integration constraints.
On-Premises retains largest installed base. Managed Services is climbing the fastest.
End User:
Application intensity varies by vertical regulatory exposure. Financial services and government verticals command premium pricing due to mandatory certification requirements and penalty frameworks.
- BFSI:Threat detection, fraud prevention, and regulatory compliance for banks, insurers, and fintech operators. Mid-sized institutions across Southeast Asia are expanding procurement fastest as they displace large enterprises in growth velocity.
- Government:Critical infrastructure protection, citizen data security, and classified systems defense. Singapore's Cyber Security Agency and Indonesia's BSSN shape procurement specifications through mandatory vendor approvals.
- Healthcare:Patient data protection, medical device security, and telehealth platform hardening. Thailand's personal data protection enforcement creates pull-through demand for adjacent security services.
- Education:Campus network protection, research data security, and remote learning platform defense. Philippines universities accelerate endpoint deployment as device-to-staff ratios widen.
BFSI commands premium pricing tiers. Government vertical is gaining share fastest.
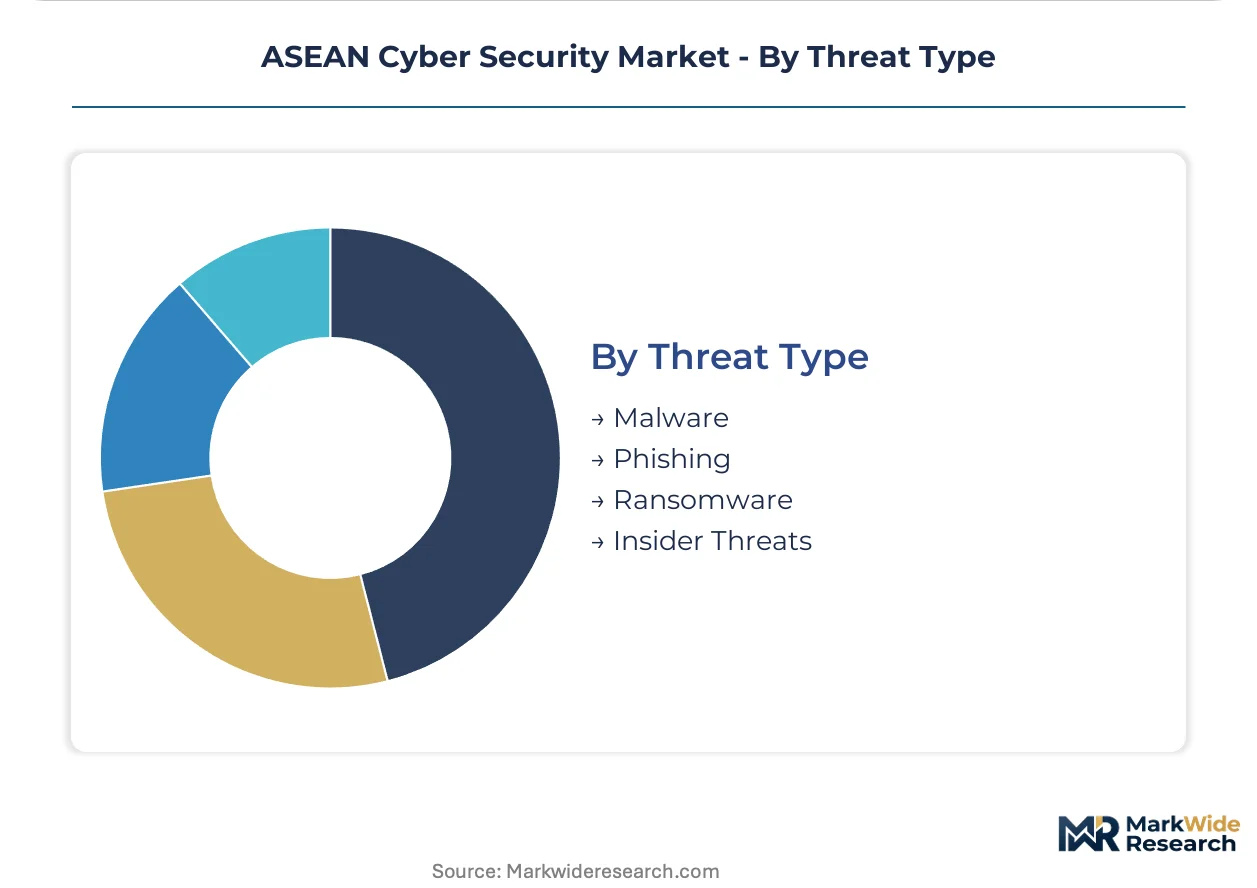
Threat Type:
Geography shapes threat prioritization. Ransomware dominates Indonesian critical infrastructure planning, while phishing drives Singapore financial sector investment.
- Ransomware:Encryption-based extortion targeting operational technology and data assets with double-extortion tactics. Indonesia's critical infrastructure operators face escalating exposure as digital economy expansion outpaces defensive maturity.
- Phishing:Credential harvesting through deceptive communications and fraudulent authentication portals. Singapore's financial institutions upgrade email security and security awareness training following PDPA breach notification rule activation.
- Malware:Viruses, worms, and trojans exploiting software vulnerabilities for persistence and lateral movement. Vietnam's manufacturing sector encounters elevated supply chain contamination risks.
- Insider Threats:Malicious or negligent actions by employees, contractors, and partners with legitimate access. Malaysia's banking sector deploys user behavior analytics following regional fraud incidents.
Malware detection dominates legacy installed base. Ransomware protection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports cyber security services and threat intelligence platforms to Indonesia, Malaysia, and Thailand as regional headquarters operations demand centralized security governance across distributed ASEAN operations.
Singapore
Financial institutions and multinational regional headquarters drive concentrated demand for cloud-native detection platforms and managed detection and response services. Singapore's Cyber Security Agency enforces mandatory incident reporting and vendor certification requirements that shape procurement specifications. The Marina Bay and One-North technology corridors host dense clusters of security operations centers serving cross-border banking and telecommunications clients.
Indonesia
State-owned enterprises and fintech operators generate accelerating procurement of converged network-firewall appliances and ransomware protection as digital transaction volumes expand. Indonesia's BSSN mandates baseline protection standards and vendor approvals for critical infrastructure operators. Jakarta's financial district and Bandung's technology corridor concentrate deployment of endpoint detection platforms across banking and e-commerce sectors.
Thailand
Healthcare providers and telecommunications operators upgrade security infrastructure following tightened personal data protection enforcement. Thailand's National Cyber Security Agency mandates baseline protection standards and incident reporting timelines that reshape vendor product roadmaps. Bangkok's central business district and Chiang Mai's digital innovation zone anchor procurement of certified threat detection platforms.
Malaysia
Established banks with heterogeneous technology stacks drive demand for hybrid security orchestration and legacy infrastructure integration services. Malaysia's central bank and securities commission shape financial sector security requirements through supervisory guidelines. Kuala Lumpur's financial district and Cyberjaya technology corridor concentrate managed security services procurement amid chronic certified analyst scarcity.
Vietnam
Manufacturing supply chains and state-owned enterprises prioritize price-sensitive converged network appliances over best-of-breed solutions. Vietnam's cybersecurity decree imposes data localization mandates that force product customization for foreign vendors. Ho Chi Minh City's industrial zones and Hanoi's government district concentrate procurement of perimeter defense technologies.
ASEAN Cyber Security Market Competitive Environment
Listed leaders compete with private specialists across managed services and appliance manufacturing, creating a tiered structure where scale-driven platform vendors coexist with vertically integrated regional operators. The market fragments across three strategic archetypes: global technology conglomerates with hybrid cloud portfolios, ASEAN-headquartered managed security specialists with deep local compliance expertise, and network-focused appliance manufacturers competing on converged functionality. M&A activity concentrates on managed detection and response capabilities, while strategic partnerships between international vendors and local system integrators accelerate certification compliance across multi-jurisdiction regulatory environments.
Within the managed security tier, Ensign InfoSecurity and Vigilant Asia exemplify ASEAN-headquartered operators leveraging deep vertical integration into 24/7 security operations centers. IBM Corporation anchors the global technology conglomerate archetype, competing for multi-country government contracts through hybrid cloud security positioning. Fortinet, Inc. occupies the converged appliance specialist position, dominating price-sensitive deployments across Indonesia and Vietnam where state-owned enterprises prioritize integrated network-firewall functionality.
| Leading Market Players |
|---|
| Fujitsu Thailand Co., Ltd. |
| Info Security Consultants Co., Ltd. |
| IBM Corporation |
| Vigilant Asia (M) Sdn Bhd |
| Dell Technologies, Inc. |
| Cisco Systems, Inc. |
| Red Sky Digital Ventures Ltd. |
| Ensign InfoSecurity |
| Fortinet, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud capacity utilization in Singapore and Malaysia shapes regional price floors for managed security services, concentrating supply among certified operators while compressing margins for smaller regional players. This scale dynamic forces mid-sized buyers toward subscription models that transfer operational risk, while state-owned enterprises in Indonesia and Vietnam anchor demand for converged appliance pricing.
Pricing Analysis
Next-generation cloud-native detection platforms command 40-60% premiums over prior-generation on-premises security information and event management deployments, while current-generation hybrid orchestration tools occupy a contracting middle tier. Subscription-based SaaS pricing dominates ASEAN cyber security procurement, with differentiation driven by Singapore's Cyber Security Agency certification tier and after-sales service bundling. Pricing pressure intensifies in Indonesia and Vietnam as state-owned enterprises prioritize converged network-firewall functionality over best-of-breed solutions. Mid-sized financial institutions across Southeast Asia demonstrate highest price sensitivity, while Singapore-based multinational regional headquarters absorb premium tiers for centralized governance.
Supply Chain Analysis
Talent pipeline chokepoints in Singapore and Malaysia's certified security analyst pools constrain service delivery capacity for managed detection and response providers. Hardware component supply concentrates in Taiwan, China, and South Korea for semiconductor-dependent security appliances, while threat intelligence feeds rest on data partnerships with US and Israeli research organizations. Single-source vulnerability runs through Singapore's concentrated security operations center infrastructure for cross-border banking clients. Distribution runs through systems integrators and managed security service providers for complex solutions, with direct vendor relationships dominating appliance sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-sized financial institutions displacing large enterprises as the fastest-growing procurement segment, fragmenting vendor pricing power across ASEAN member states.
For Market Incumbents: Fortify market position through backward integration into captive threat intelligence production and certification investment with Indonesia's BSSN and Thailand's National Cyber Security Agency. Defensive moves must address margin compression from chronic certified analyst scarcity in Singapore and Malaysia, while channel control over local system integrators preserves multi-jurisdiction compliance economics. For New Entrants and Emerging Players: Lead with automated endpoint detection and response targeting Philippines banking and telecommunications sectors where device proliferation outpaces internal security staffing. The whitespace concentrates in outcome-based subscription contracts for mid-market buyers, with go-to-market execution through value-added distributors bypassing direct competition with established managed security service providers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ASEAN-headquartered managed security specialists with deep local compliance expertise over global platform vendors facing certification friction. Long-term viability hinges on consolidation of 24/7 security operations center capabilities as talent scarcity intensifies. The signal to watch is regulatory divergence between Singapore's PDPA amendments and Vietnam's data localization mandates reshaping vendor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Detection and Response Acquisition | Consolidates 24/7 SOC capabilities addressing certified analyst scarcity in Singapore and Malaysia. |
| Multi-Jurisdiction Certification Investment | Accelerates vendor approval with Indonesia's BSSN and Thailand's National Cyber Security Agency. |
| Cloud-Native Platform Integration | Aligns with ASEAN enterprise migration to hyperscale providers and PDPA compliance mandates. |
| Outcome-Based Contract Structuring | Transfers operational risk to service providers for mid-sized financial institution buyers. |
| Local System Integrator Partnership | Navigates regulatory fragmentation across Thailand's Cybersecurity Act and Vietnam's cybersecurity decree. |
Study Parameters
A standing panel of chief information security officers, managed security service provider operations directors, regulatory compliance leads at financial institutions, and hyperscaler platform engineers provided ongoing calibration across the research process. Primary interviews combined with secondary validation from Singapore Cyber Security Agency certification databases, Thailand National Cyber Security Agency regulatory filings, Indonesia BSSN vendor approval registries, and ASEAN customs trade data for security appliance imports. Bottom-up deployment modeling and top-down market sizing triangulated through cross-reference with hyperscaler security service revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including regional cloud infrastructure spending patterns and financial sector IT security budget surveys. The analytical framework modeled segmentation across solution type, deployment model, end-user vertical, and threat type over the projection horizon. CAGRs derived from fitted growth curves incorporating cloud migration velocity, regulatory enforcement intensity, and ransomware incident frequency as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained ASEAN digital economy expansion and current regulatory enforcement trajectories would require recalibration. Forecasts reflect documented assumptions regarding talent pipeline development and hyperscaler market entry timing. Practitioners should keep alternative scenarios live as data sovereignty requirements and EU AI Act extraterritorial reach evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Industrial Cybersecurity Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Education Data Security Market
Cybersecurity
Web Application Firewall Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Global Cloud Security Posture Management Market
Cybersecurity
Global Database Security Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Cloud Endpoint Protection Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Portugal Cybersecurity Market