
 Defense IT Spending Market | 2026-2036
Defense IT Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Defense IT Spending Market Intelligence
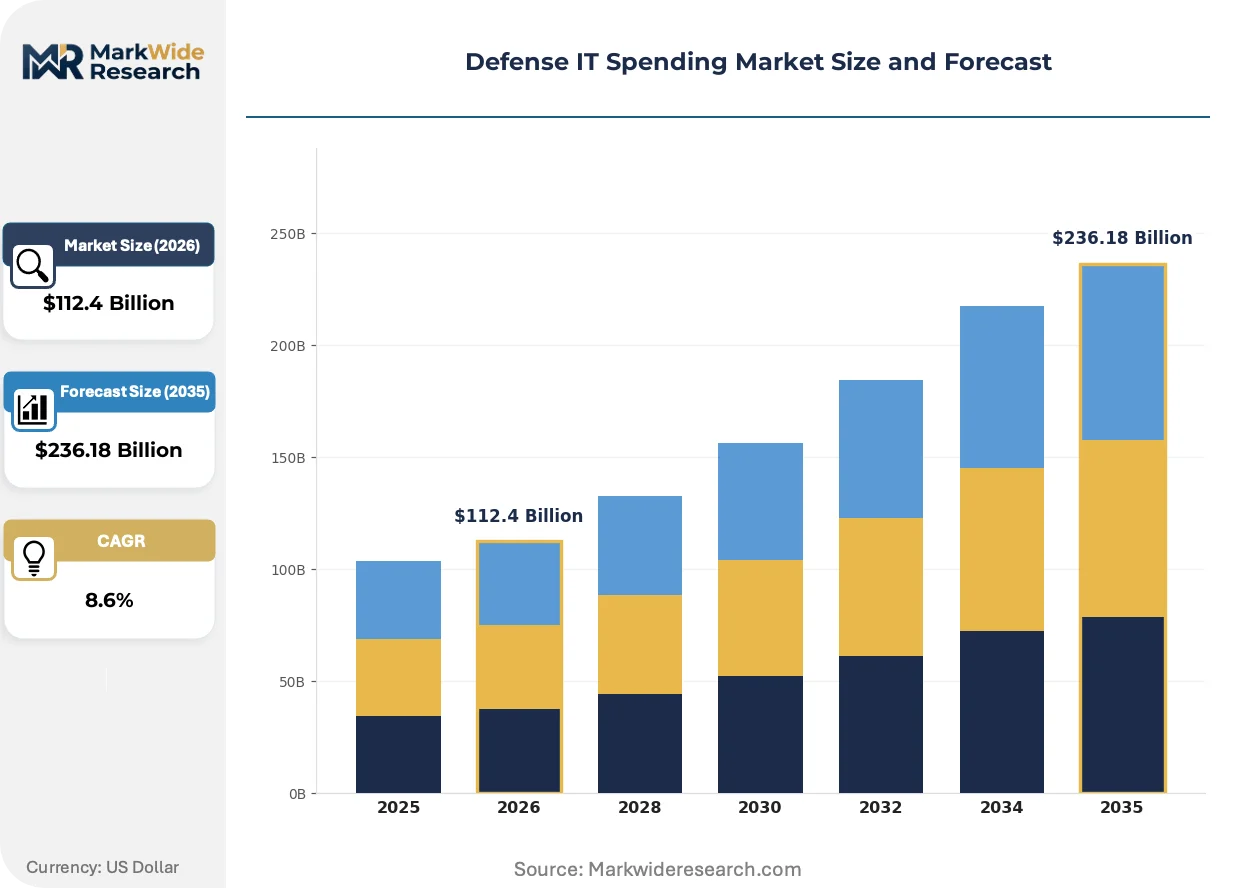
Revenue from cloud services and managed cybersecurity solutions is tilting the market's profit pools away from traditional on-premise hardware and software sales. Microsoft leverages its Azure cloud platform to secure large-scale defense contracts for cloud infrastructure. Palantir Technologies specializes in data analytics platforms tailored for intelligence applications. Leidos positions itself as a key systems integrator, managing complex IT modernization projects for defense agencies.
Defense IT spending encompasses the procurement and lifecycle management of digital infrastructure, software, and services for military operations and intelligence. This includes systems designed to handle classified data up to specific security levels and operate in contested network environments. Within the technology segment, Artificial Intelligence and Edge Computing represent the fastest-growing areas of investment. Command & Control Systems constitute a mature but consistently funded application, forming the backbone of operational infrastructure.
Regulatory frameworks like the U.S. Department of Defense's CMMC program directly mandate cybersecurity standards for contractors. In parallel, data governance rules such as the EU's GDPR and emerging principles in the EU AI Act influence how defense systems handle information and algorithmic decision-making. Navigating these disparate and evolving compliance requirements while integrating next-generation technologies is the central challenge for all market participants.
Market Dynamics
The central dynamic in defense IT spending is the tension between the imperative for rapid technology adoption, particularly in AI and cloud, and the entrenched, slow-moving processes of defense procurement and security accreditation that govern the sector.
Growth Catalysts
- Artificial Intelligence Integration:The application of AI to accelerate real-time data processing and threat identification for Intelligence, Surveillance, and Reconnaissance (ISR) missions is a primary growth vector for new software and infrastructure investment.
- Cybersecurity Mandates:Regulatory frameworks like the U.S. Department of Defense's CMMC program compel the entire defense industrial base to upgrade digital infrastructure and security services, directly driving market expenditure.
- Large-Scale Modernization Programs:National initiatives in countries like the United States to overhaul command and control systems and migrate applications to secure cloud environments create sustained, large-scale demand for integrated IT solutions.
Market Restraints
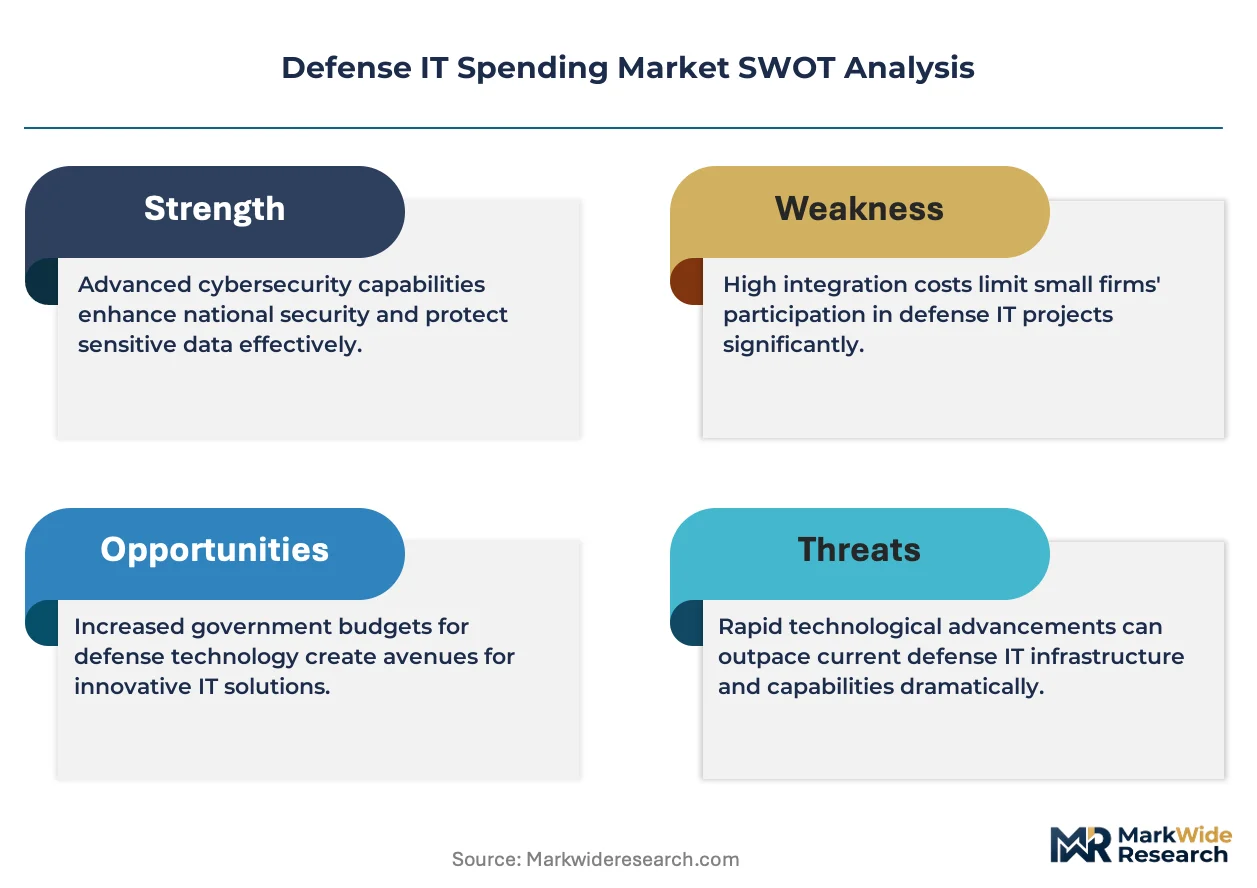
- Legacy System Integration Costs:The high cost and technical complexity of integrating modern IT solutions with decades-old, mission-critical legacy hardware and software platforms constrain the pace and scope of modernization projects.
- Disparate Data Governance Rules:Navigating conflicting data sovereignty and privacy regulations, such as the EU's GDPR versus national security exemptions, creates compliance friction and legal risks for multinational contractors.
- Classified Supply Chain Bottlenecks:A limited number of vendors possess the security clearances and specialized infrastructure required to handle highly classified data, creating supply chain bottlenecks and concentrating risk.
Strategic Opportunities
- Edge Computing and 5G Convergence:The convergence of Edge Computing with private 5G networks offers opportunities to deliver secure, high-bandwidth, low-latency processing for tactical units operating in contested or disconnected environments.
- Digital Twin Environments:Creating digital twins of military assets and operational theaters for advanced simulation, mission rehearsal, and predictive maintenance represents a significant new application for IT investment.
- EU AI Act Alignment:Proactively developing AI systems that align with emerging principles in the EU AI Act for algorithmic transparency can create a competitive advantage in European defense and dual-use technology markets.
Industry Challenges
- Cleared Cybersecurity Talent Scarcity:A persistent shortage of cybersecurity professionals who possess the necessary government security clearances to work on classified defense programs hampers project execution and inflates labor costs.
- Prolonged Accreditation Cycles:The lengthy and complex process for achieving security certification and an Authority to Operate (ATO) for new software and systems significantly delays the deployment of innovative capabilities to end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense IT Spending Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $236.18 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Expenditure Type: Hardware, Software, Cloud Services, Cybersecurity Solutions, Consulting, Maintenance Technology: Artificial Intelligence, Big Data Analytics, Blockchain, Internet of Things, Virtualization, Edge Computing Application: Command & Control Systems, Intelligence Surveillance Reconnaissance, Logistics Management, Simulation Training, Communication Networks, Defense Manufacturing End User: Defense Agencies, Security Contractors, Military Research Centers, Homeland Defense Units, Cyber Defense Groups, Border Security Firms |
| Companies Covered | RTX Corporation, Accenture, Leidos, Microsoft, IBM, General Dynamics, BAE Systems, Palantir Technologies, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense IT Spending Market Strategic Shifts & Innovations
A fundamental reorientation from hardware-centric procurement to service-based and data-centric models is defining the market's evolution. This shift prioritizes continuous capability delivery and software-defined functionalities over traditional five-year hardware refresh cycles, altering the profit pools for vendors.
The adoption of containerization technologies like Kubernetes within classified cloud environments allows for the rapid deployment and scaling of software applications. Defense agencies are increasingly adopting these DevOps practices to accelerate software development and delivery cycles for mission systems. This software-defined approach is collapsing the traditional distinction between development and operations, enabling CI/CD pipelines even within secure networks.
Implementation of the U.S. Department of Defense's Zero Trust Architecture (ZTA) cybersecurity model mandates a significant change in network security posture. This policy shifts the focus from perimeter defense to authenticating and authorizing every user, device, and data flow within the network. It most affects legacy network infrastructure providers, forcing them to re-architect solutions around identity management and micro-segmentation to remain compliant.
Consumption-based pricing for cloud and software services is gaining traction within defense agencies. This model disrupts traditional, fixed-price contracts for perpetual software licenses and on-premise hardware, favoring flexible enterprise agreements instead. The shift is most visible in the United States and the United Kingdom, where large-scale cloud contracts emphasize paying only for the specific compute and storage resources used.
Defense IT Spending Market Segmentation
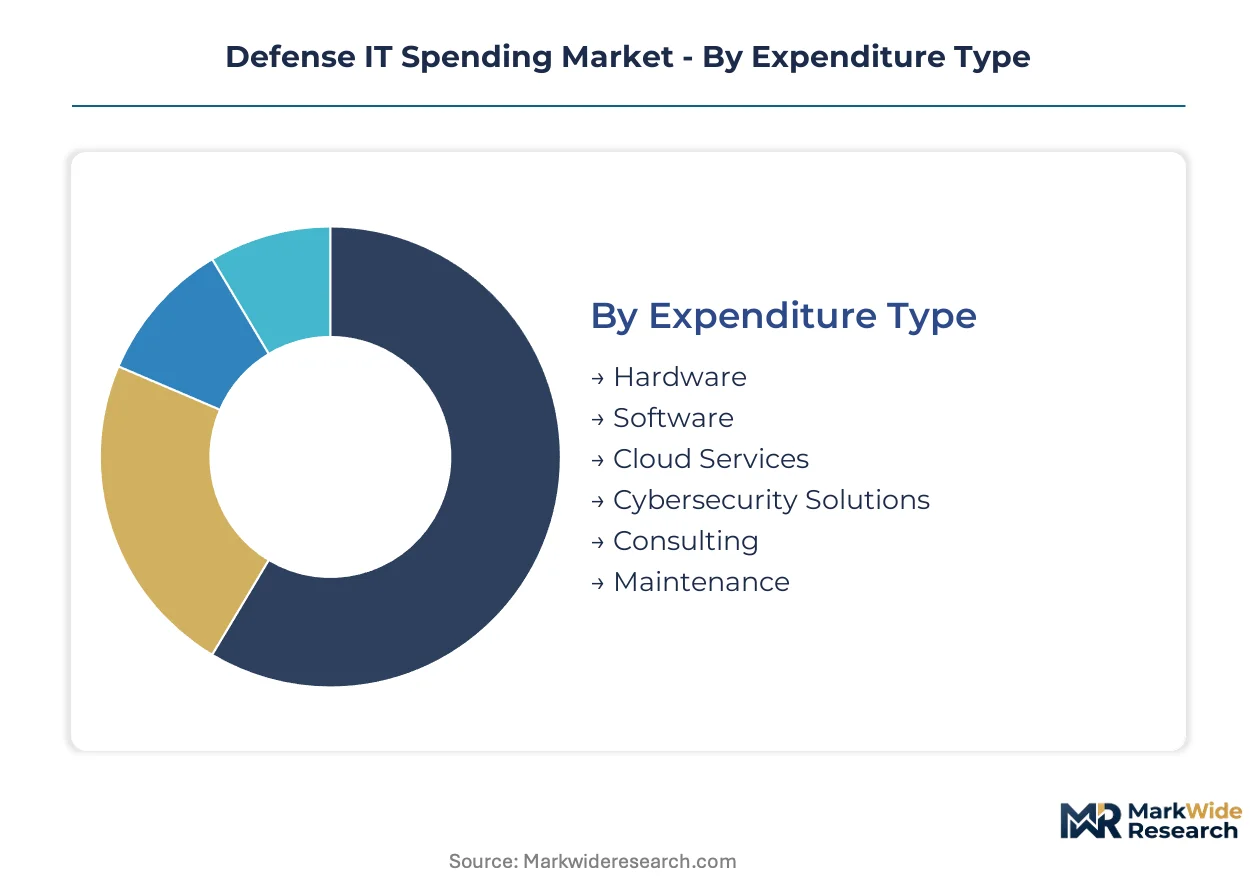
Segmentation analysis provides a granular understanding of the Defense IT Spending Market, revealing distinct expenditure patterns and technological priorities. This detailed breakdown helps identify where investment flows are most concentrated and which areas offer significant growth potential. Understanding these segments is crucial for strategic planning and resource allocation across the defense industrial base.
Expenditure Type:
The market for defense IT expenditure types ranges from mature, established categories to rapidly emerging service models.
- Cloud Services:These encompass scalable, on-demand computing resources delivered over a network, including Infrastructure-as-a-Service (IaaS) and Software-as-a-Service (SaaS). Demand concentrates in the United States, driven by large-scale modernization programs migrating applications to secure cloud environments.
- Cybersecurity Solutions:This segment includes technologies and services designed to protect digital infrastructure, networks, and data from cyber threats, adhering to strict regulatory frameworks. Investment is compelled by the U.S. Department of Defense's CMMC program, mandating enhanced security standards across the defense industrial base.
- Hardware:This includes physical components like servers, networking equipment, and specialized computing devices for defense systems.
- Software:This segment covers operating systems, applications, and custom programs tailored for military operations and intelligence.
- Consulting:Specialized advisory services assist defense agencies with IT strategy, system integration, and compliance with complex regulations.
- Maintenance:Ongoing support, updates, and repair services ensure the continuous operation and longevity of defense IT systems.
Cloud Services retains volume leadership; Cybersecurity Solutions holds the steepest expansion curve.
Technology:
Technology investments in defense IT are increasingly driven by specific operational applications, prioritizing capabilities that enhance real-time decision-making and battlefield advantage.
- Artificial Intelligence:AI involves advanced algorithms and computational models for tasks like real-time data processing, predictive analytics, and autonomous system control. Application in Intelligence, Surveillance, and Reconnaissance (ISR) missions accelerates investment, particularly for threat identification.
- Edge Computing:This technology processes data closer to its source, minimizing latency and bandwidth requirements for tactical units operating in contested or disconnected environments. Its convergence with private 5G networks presents strategic opportunities for secure, low-latency processing at the operational edge.
- Big Data Analytics:Systems and tools analyze vast datasets to extract actionable insights for intelligence and operational planning.
- Blockchain:Distributed ledger technology offers enhanced security and transparency for supply chain management and data integrity within defense networks.
- Internet of Things:Networked sensors and devices collect and exchange data, supporting situational awareness and asset tracking in military contexts.
- Virtualization:This technology creates virtual versions of computing resources, improving efficiency and resource utilization across defense IT infrastructure.
Investment patterns reveal a shift towards Artificial Intelligence for operational advantage, while Edge Computing secures future capabilities.
Application:
Volume concentration in defense IT applications reflects long-standing operational priorities and emerging strategic imperatives.
- Intelligence Surveillance Reconnaissance:ISR applications involve collecting, processing, and disseminating intelligence data to support military operations and national security. This segment is a primary growth vector, driving significant investment in AI for real-time data processing and threat identification.
- Command & Control Systems:These systems provide the framework for military commanders to exercise authority over forces, orchestrating operations and managing resources. Forming the backbone of operational infrastructure, this application remains a mature but consistently funded area within defense IT.
- Logistics Management:IT solutions optimize the supply chain, inventory, and transportation of military assets and personnel.
- Simulation Training:Virtual environments and models prepare military personnel for complex scenarios and improve operational readiness.
- Communication Networks:Secure and resilient communication infrastructure supports data exchange and coordination across military units.
- Defense Manufacturing:Digital technologies enhance efficiency and precision in the production of military equipment and components.
The operational imperative drives demand for Intelligence Surveillance Reconnaissance, with Command & Control Systems seeing accelerated adoption for strategic advantage.
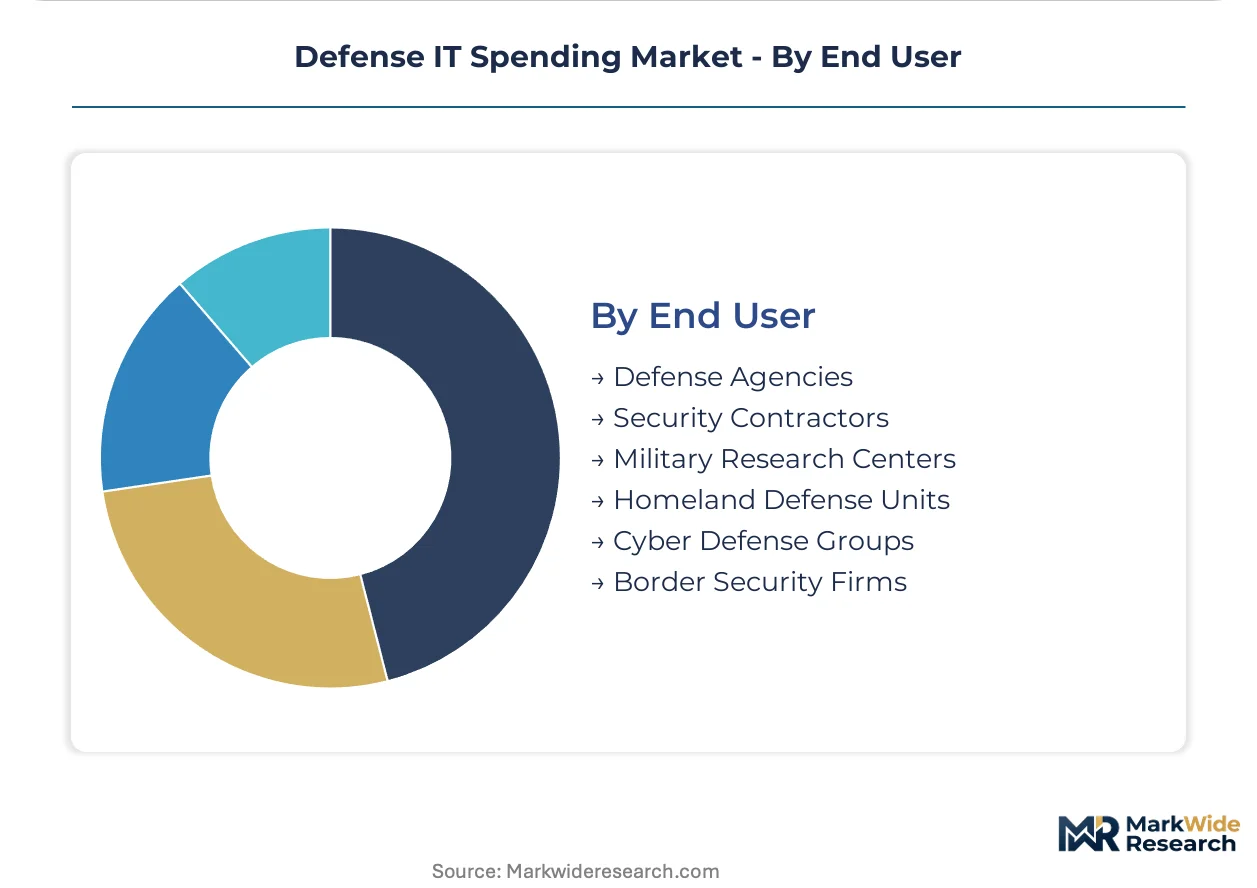
End User:
Distinct customer types within the defense IT market exhibit varying procurement processes and specialized technological requirements.
- Defense Agencies:These government entities, such as the U.S. Department of Defense, are the primary procurers of IT solutions for military operations, intelligence gathering, and national security. Large-scale modernization programs in countries like the United States create sustained demand for integrated IT solutions.
- Cyber Defense Groups:Specialized units within military and government organizations focus on protecting critical digital infrastructure from cyberattacks and conducting cyber warfare operations. Their demand is shaped by the implementation of Zero Trust Architecture and the need for cleared cybersecurity talent.
- Security Contractors:Private firms provide specialized IT services, software, and systems integration to defense and intelligence clients.
- Military Research Centers:These institutions focus on developing cutting-edge technologies and innovative IT solutions for future defense capabilities.
- Homeland Defense Units:Agencies responsible for protecting national borders and domestic security leverage IT for surveillance, data analysis, and threat detection.
- Border Security Firms:Companies specializing in border protection utilize IT for surveillance systems, data management, and operational coordination.
Primary procurement originates from Defense Agencies, with specialized needs driving growth in Cyber Defense Groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense IT spending exhibits a consumption-mix differential across major global markets, with nations like the United States and the United Kingdom rapidly adopting flexible, consumption-based cloud services. This contrasts with more traditional procurement models still prevalent in other regions, which often prioritize fixed-price contracts for on-premise hardware and perpetual software licenses. The shift reflects varying speeds of digital transformation and regulatory alignment across defense industrial bases.
United States
Large-scale modernization programs drive significant investment in cloud infrastructure and integrated IT solutions across the United States. The U.S. Department of Defense's CMMC program mandates stringent cybersecurity standards, compelling widespread digital infrastructure upgrades. Silicon Valley and government contracting hubs in Northern Virginia remain central to developing secure cloud platforms and advanced AI applications for defense agencies.
United Kingdom
The United Kingdom demonstrates strong traction for consumption-based cloud and software services within its defense sector. Cybersecurity mandates and the need for enhanced data protection compel significant expenditure in digital security solutions. London and the M4 corridor serve as vital centers for cybersecurity innovation and defense technology integration, attracting specialized IT service providers.
France
France prioritizes investments in sophisticated Command & Control systems and advanced AI applications to enhance operational capabilities. Compliance with the EU AI Act and GDPR influences data governance and algorithmic decision-making within its defense IT systems. Paris and Toulouse function as key hubs for aerospace and defense IT research, driving innovation in secure communication networks.
Germany
Germany increases its defense IT spending, focusing on modernizing legacy systems and strengthening cyber defense capabilities. Strict data governance under GDPR shapes the development and deployment of new IT solutions for military and intelligence operations. Munich and Berlin are significant centers for defense technology and cybersecurity firms, supporting military research and development efforts.
Defense IT Spending Market Key Industry Players
Capability concentration sits with one tier of specialized technology providers, while scale advantage sits with another tier of large-scale platform and systems integrators. The market exhibits a tiered structure, with a few dominant players alongside numerous niche specialists providing bespoke solutions. Key strategic archetypes include cloud infrastructure providers, data analytics specialists, and complex systems integrators. Competitive moves often involve strategic partnerships to bridge capability gaps and portfolio diversification into emerging technologies like AI and edge computing.
Specialists in data analytics platforms and secure cloud infrastructure, such as Palantir Technologies, offer tailored solutions for intelligence applications. Microsoft, through its Azure platform, secures large-scale defense contracts, exemplifying a major cloud service provider. Leidos occupies a position as a key systems integrator, managing complex IT modernization projects for defense agencies across the globe.
| Leading Market Players |
|---|
| RTX Corporation |
| Accenture |
| Leidos |
| Microsoft |
| IBM |
| General Dynamics |
| BAE Systems |
| Palantir Technologies |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
The secure digital and physical infrastructure corridors for classified defense IT components and data face escalating operational costs. These costs influence supply concentration among cleared vendors and impact price differentiation for specialized services.
Pricing Analysis
Consumption-based pricing models are gaining traction within defense agencies, shifting from traditional fixed-price contracts for perpetual licenses. Price differentiation stems from the level of security clearance required for data handling and the complexity of integrating solutions with legacy systems. Pricing softness emerges from the imperative for rapid technology adoption, favoring flexible enterprise agreements over large upfront investments. Homeland Defense Units exhibit higher price sensitivity for standard IT services, while Cyber Defense Groups prioritize capability over cost for specialized threat intelligence platforms.
Supply Chain Analysis
The upstream supply of highly specialized microprocessors and secure network hardware primarily originates from the United States and select European allies like France and Germany. Defense IT solutions draw from a limited pool of vendors possessing the necessary security clearances and specialized infrastructure. A critical structural risk involves classified supply chain bottlenecks, where a few cleared providers concentrate capabilities. Distribution of these solutions typically occurs via direct procurement contracts with Defense Agencies or through prime systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers significant service-attach opportunities, where managed cybersecurity solutions represent a recurring-revenue layer expanding faster than traditional hardware sales. Vendors should prioritize building long-term relationships through continuous support and capability upgrades.
For Market Incumbents: Entrench existing positions by leveraging deep relationships with Defense Agencies and expanding secure cloud offerings. Invest heavily in AI and Edge Computing R&D to counter the threat from specialized technology firms and maintain competitive relevance. Prioritize certification investment under CMMC to ensure compliance across the defense industrial base. Consolidate market share through strategic acquisitions of agile software development houses.
For New Entrants and Emerging Players: European defense markets, particularly for EU AI Act compliant systems, represent a significant underpenetration opportunity. Target niche applications within Intelligence Surveillance Reconnaissance that leverage advanced AI for real-time data processing. Focus on developing capabilities for secure Edge Computing in tactical environments. A strong go-to-market angle involves strategic partnerships with established systems integrators to navigate complex procurement processes.
For Investors and Strategic Acquirers: Specialized software developers focusing on AI-driven data analytics and robust cybersecurity firms present attractive long-term viability over the next 5-10 years. These targets offer critical intellectual property and cleared talent in a market driven by modernization imperatives. Seek companies with proven capabilities in secure cloud environments and CMMC compliance. The signal to watch for inflection is a sustained acceleration in Authority to Operate (ATO) approvals for innovative technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI/ML R&D for ISR | Enhances real-time threat identification capabilities for defense agencies. |
| Acquire Cleared Cybersecurity Talent | Addresses the persistent shortage of qualified professionals for classified programs. |
| Partner for Secure Cloud Integration | Accelerates application migration to secure cloud environments for military operations. |
| Develop Edge Computing Solutions | Delivers low-latency processing to tactical units in contested network environments. |
| Achieve CMMC Level 3+ Certification | Ensures compliance with U.S. DoD mandates for securing digital infrastructure. |
Research Approach
A spread of perspectives from defense IT procurement officers, cybersecurity architects, systems integrators, and AI solution developers converged on the working assumptions for this study. Primary interviews with these industry stakeholders were rigorously validated through secondary research. Key sources included DoD budget documents, CMMC publications, EU AI Act legislative texts, and defense contractor annual reports. This approach employed both bottom-up data aggregation and top-down market sizing triangulation.
The demand-supply balance over the projection horizon informed the quantitative modeling framework. This analysis segmented the market by expenditure type, technology, application, end-user, and required security clearance level. Compound annual growth rates were derived from historical data analysis and projected technological adoption curves. Key forecast inputs included national defense budget allocations and regulatory compliance timelines for cybersecurity mandates.
Practitioners should monitor geopolitical shifts, rapid technological breakthroughs, and changes in defense procurement policy for early signals of market redirection. Forecasts reflect assumptions documented at the time of publication. Quarterly review of defense budget cycles and major program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Express Digitizer Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Europe API Management Market
Digital Solutions
Graph Technology Market
Digital Solutions
Revops Platform Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Dating Services Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Online Hyper-Local Services Market