
 Middle East and Africa Cybersecurity Market | 2026-2036
Middle East and Africa Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cybersecurity Market Outlook
The UAE's NESA Information Assurance standards is realigning enterprise procurement priorities across energy and banking sectors. IBM Corporation leverages its Watson Security platform to anchor managed detection services across Saudi Aramco-tier deployments. Palo Alto Networks Inc competes through Prisma Cloud specialization in hybrid environments. Check Point Software Technologies Ltd dominates Israeli-developed threat intelligence distribution throughout African telecom networks.
Cybersecurity encompasses hardware, software, and service layers engineered to protect digital infrastructure through encryption protocols, intrusion detection algorithms, and access control matrices operating at throughput thresholds exceeding 100 Gbps in carrier-grade deployments. Its primary purpose spans confidentiality preservation, operational continuity assurance, and regulatory compliance verification across interconnected enterprise systems. Cloud Security within the Application dimension leads growth as Gulf enterprises migrate SAP and Oracle workloads to AWS Riyadh and Azure UAE regions. Managed Services deployment captures expanding margin pools by substituting capital expenditure with subscription-based security operations center provisioning. Firewall product types retain foundational positioning despite gradual displacement by zero-trust network architecture.
Saudi Arabia's National Cybersecurity Authority, the UAE's Telecommunications and Digital Government Regulatory Authority, and South Africa's National Cybersecurity Hub collectively mandate baseline encryption standards and incident reporting timelines that reshape vendor qualification criteria. The EU AI Act's extraterritorial reach into African Union trade corridors additionally pressures multinationals to harmonize governance frameworks. Stakeholders must monitor sovereign cloud localization requirements and cross-border data flow restrictions as determinants of deployment architecture selection.
Market Dynamics
Zero-trust architecture migration is compressing procurement cycles across Gulf banking and energy sectors as Saudi Arabia's NCA mandates harden compliance baselines and force incumbent perimeter-security vendors to requalify under stricter identity-verification protocols.
Growth Catalysts
- Sovereign Cloud Localization:Saudi Arabia's data residency requirements for Aramco-tier enterprises are accelerating AWS Riyadh and Azure UAE region deployments. This forces security stack rebuilds around localized encryption key management.
- NESA Information Assurance Standards:The UAE's energy and banking sectors face mandatory compliance timelines that realign vendor selection criteria toward certified managed detection providers.
- Hybrid Work Infrastructure:Distributed workforce models across Dubai's fintech corridor are expanding demand for secure access service edge architectures that replace traditional VPN concentrators.
Market Restraints
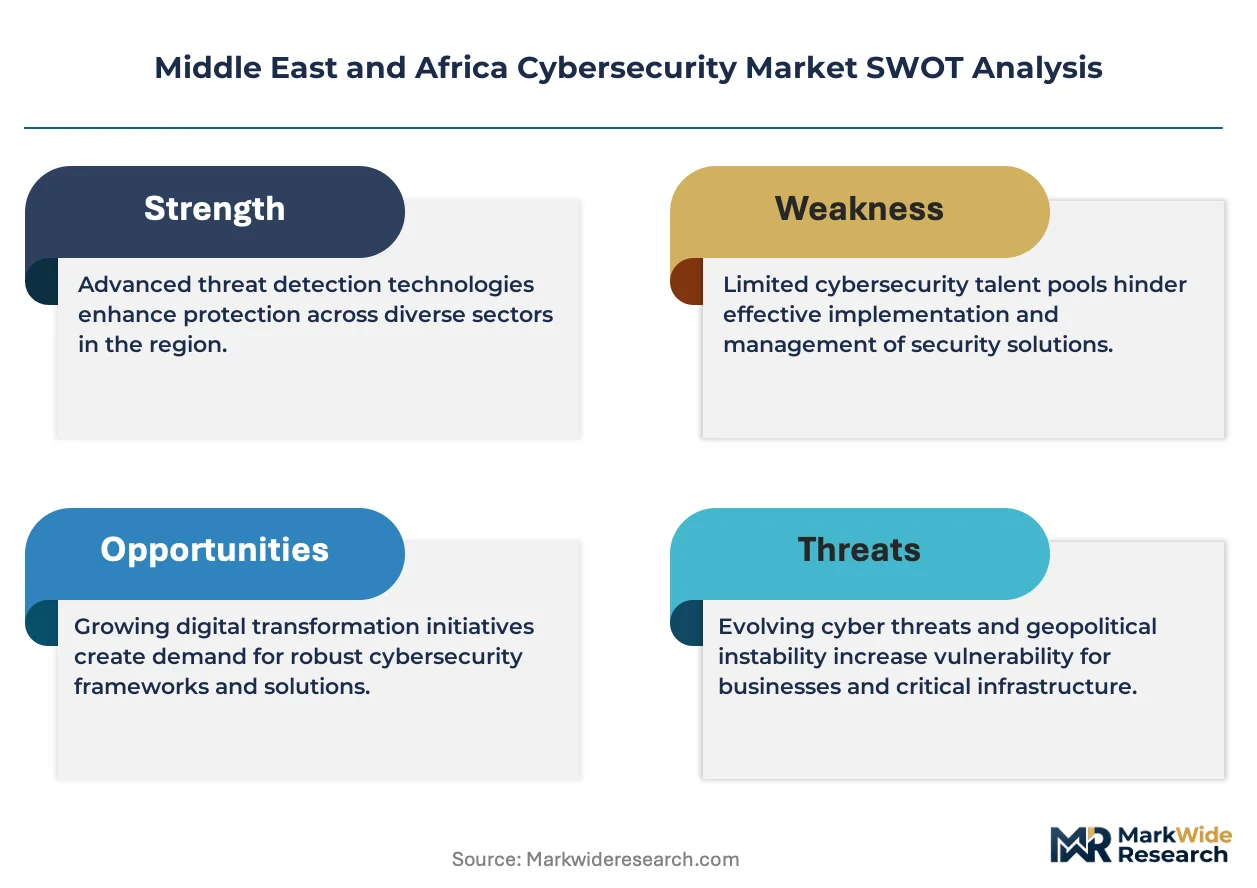
- Skilled Talent Scarcity:The Gulf's shortage of certified security operations analysts inflates SOC-as-a-service pricing and extends implementation timelines for zero-trust rollouts.
- Import Dependency:Hardware security module supply concentrates in East Asian manufacturing clusters, exposing African telecom operators to extended lead times and currency volatility.
- Legacy Integration Friction:Decades-old mainframe systems at South African financial institutions resist API-based security orchestration, forcing expensive parallel infrastructure builds.
Strategic Opportunities
- Underpenetrated East African Markets:Kenya and Ethiopia's banking digitization programs lack mature incident response capabilities, creating openings for regional SOC partnerships.
- AI-Assisted Threat Hunting:Convergence of machine learning inference with edge computing is enabling real-time anomaly detection for Nigerian mobile money platforms.
- EU AI Act Extraterritoriality:Multinationals operating in African Union trade corridors must harmonize governance frameworks, creating advisory and compliance tooling demand.
Industry Challenges
- Certification Timeline Compression:Saudi Arabia's NCA approval windows for critical national infrastructure vendors have narrowed, forcing product localization investments before revenue recognition.
- Fragmented Standards Landscape:Divergent encryption requirements between South Africa's National Cybersecurity Hub and UAE's TDRA complicate pan-regional service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cybersecurity Market |
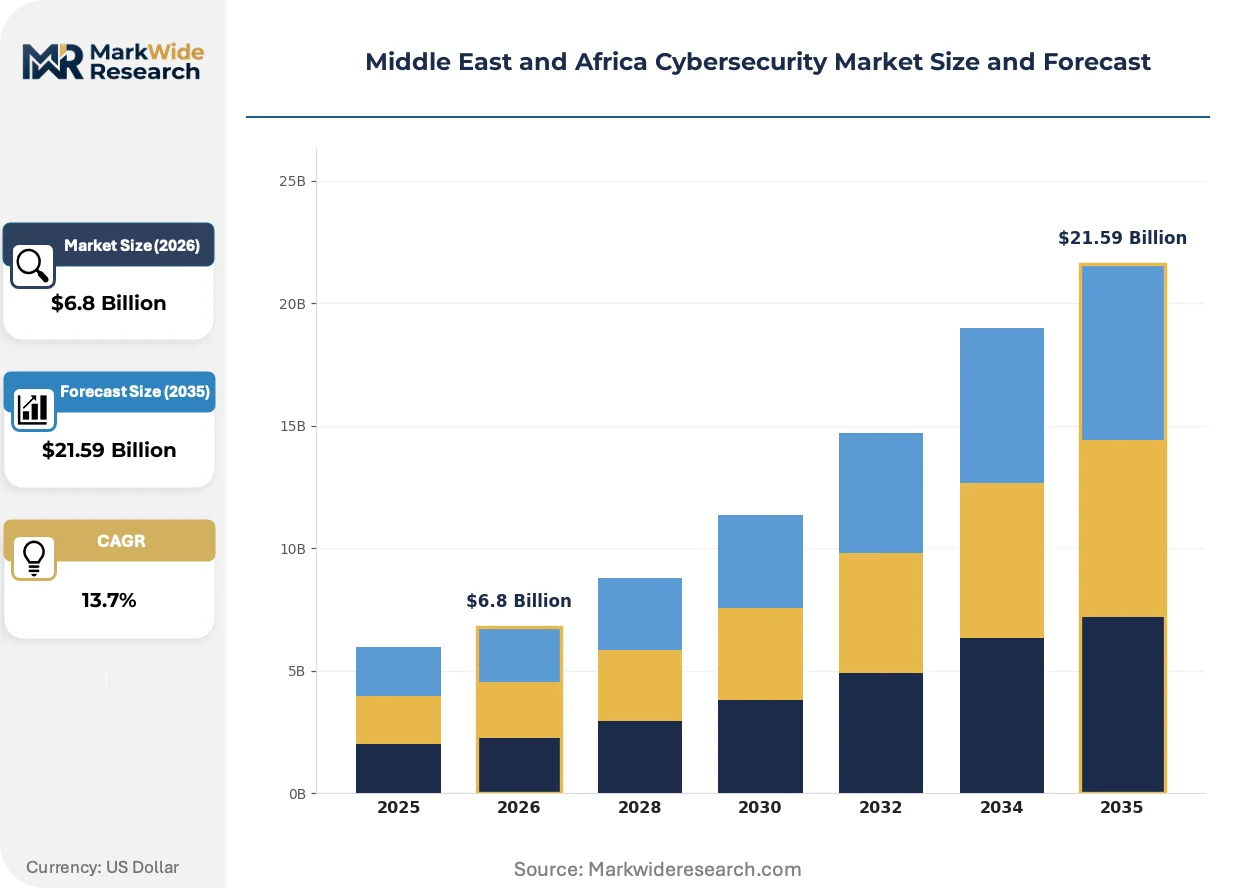
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Antivirus, Intrusion Detection, Encryption End User: Government, BFSI, Healthcare, Retail Deployment: On-Premises, Cloud, Hybrid, Managed Services Application: Network Security, Application Security, Cloud Security, Endpoint Security |
| Companies Covered | IBM Corporation, Cisco Systems Inc, Palo Alto Networks Inc, Check Point Software Technologies Ltd, Fortinet Inc, LoopTech, Digital Security Company (DigiSec), Help AG, EMTECH, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cybersecurity Market Strategic Shifts
Security architecture is pivoting from perimeter defense to identity-centric verification as Gulf enterprises absorb cloud-native workloads and African mobile networks confront ransomware targeting subscriber databases.
Confidential computing is decentralizing trust boundaries by processing encrypted data within hardware-isolated enclaves. Saudi Aramco-tier energy operators are deploying Intel SGX and AMD SEV instances at scale across Riyadh data centers. This architecture eliminates the need for data decryption during analytics, compressing compliance scope for cross-border oil trading operations.
Saudi Arabia's National Cybersecurity Authority has mandated baseline encryption standards and 72-hour incident reporting timelines for critical infrastructure operators. This regulatory pressure disqualifies vendors lacking in-country security operations centers. Banking and energy procurement teams now prioritize local managed detection partners over multinational cloud-native alternatives.
Subscription-based security operations center provisioning is displacing capital-intensive appliance purchases across mid-market UAE enterprises. Dubai's fintech corridor buyers now demand consumption-priced threat detection with guaranteed response SLAs rather than perpetual license models. This shift concentrates margin pools with providers owning regional Tier III facilities.
Middle East and Africa Cybersecurity Market Segmentation
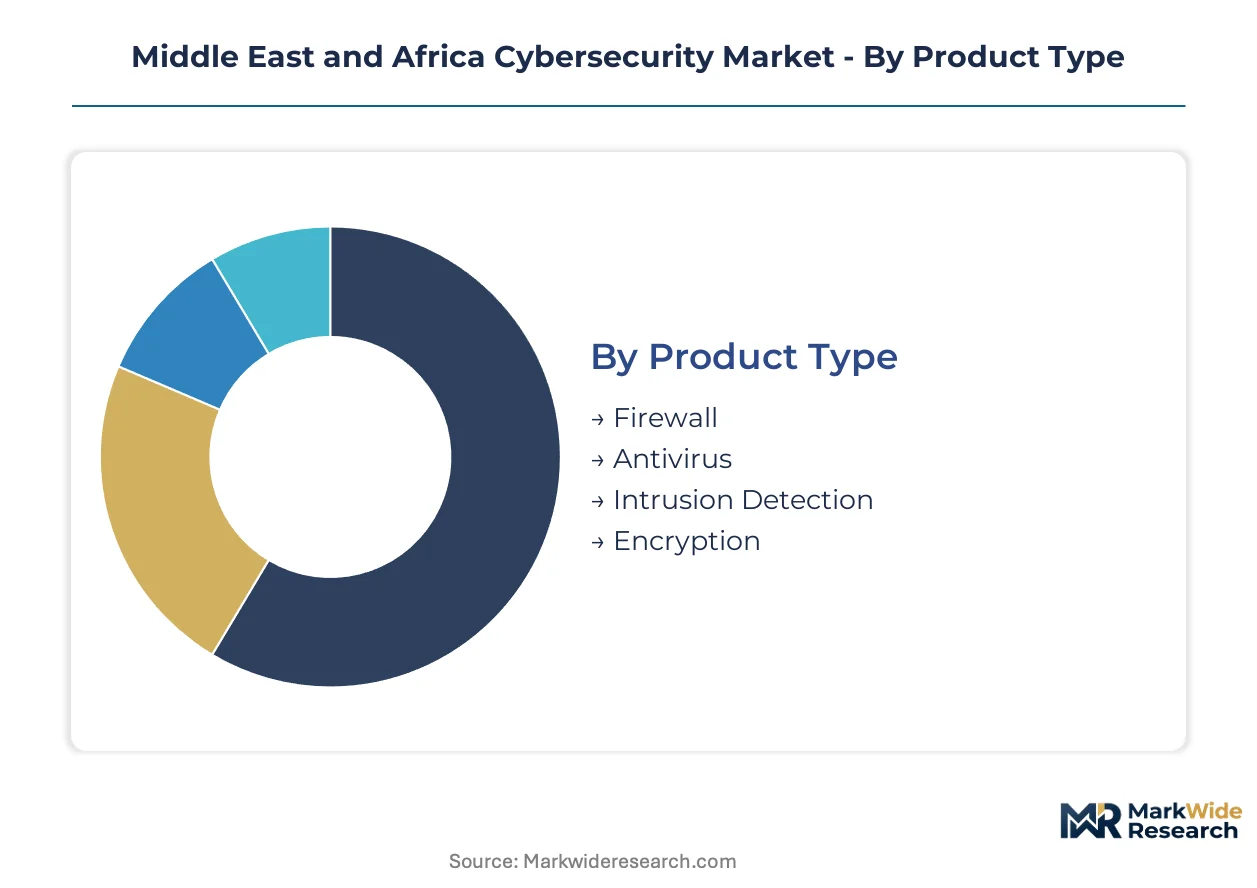
Cybersecurity procurement across the Middle East and Africa fragments across four intersecting dimensions. Buyers weight sovereign data residency mandates, legacy infrastructure compatibility, and cloud migration timelines differently depending on sector and geography.
Product Type:
Procurement cycles compress where compliance mandates force replacement of perimeter-centric tools with identity-verified alternatives.
- Firewall:Stateful packet inspection and next-generation firewall appliances retain foundational positioning in Saudi Aramco-tier energy deployments. South African banking mainframes still route traffic through hardware appliances despite gradual zero-trust displacement.
- Encryption:Hardware security modules and software-defined key management address NCA-mandated data residency for cross-border oil trading and UAE fintech corridors. AWS Riyadh and Azure UAE regions now require localized encryption key custody.
- Antivirus:Endpoint detection and response platforms supplant signature-based tools across Dubai's distributed workforce.
- Intrusion Detection:Network behavior analytics and AI-assisted threat hunting gain traction in Nigerian mobile money platforms.
Encryption leads on scale; intrusion detection leads on momentum.
End User:
Sector-specific regulatory deadlines reshape vendor qualification timelines and localization requirements.
- BFSI:Saudi banking hubs and Dubai's fintech corridor drive managed detection service subscriptions with guaranteed response SLAs. NESA compliance timelines force procurement toward certified regional SOC providers.
- Government:Critical national infrastructure operators face NCA-mandated 72-hour incident reporting and in-country security operations center requirements. This disqualifies cloud-native vendors lacking Saudi-based facilities.
- Healthcare:South African hospital networks and UAE health authorities confront ransomware targeting patient databases.
- Retail:East African e-commerce platforms and Gulf luxury retail chains adopt PCI-DSS aligned payment security.
BFSI leads on scale; government leads on momentum.
Deployment:
Capital expenditure constraints and skills scarcity push buyers toward operational expenditure models with defined service levels.
- Managed Services:Subscription-based SOC provisioning displaces appliance purchases across mid-market UAE enterprises. Tier III facilities in Riyadh and Dubai capture margin pools through consumption-priced threat detection.
- Cloud:SAP and Oracle workload migration to AWS Riyadh and Azure UAE regions forces security stack rebuilds around localized encryption.
- Hybrid:Split architectures accommodate legacy mainframe systems at South African financial institutions alongside cloud-native workloads.
- On-Premises:Air-gapped deployments persist in Saudi energy and defense sectors with sovereign cloud requirements.
Managed services leads on scale; cloud leads on momentum.
Application:
Attack surface expansion through cloud migration and mobile network digitization redirects security spending toward workload protection.
- Cloud Security:Container security, serverless function protection, and SaaS access control dominate procurement as Gulf enterprises migrate core ERP systems. Prisma Cloud and equivalent platforms specialize in multi-cloud governance.
- Endpoint Security:Distributed workforce models across Dubai's fintech corridor expand demand for secure access service edge architectures replacing VPN concentrators.
- Network Security:Zero-trust network access and microsegmentation compress traditional perimeter appliance relevance.
- Application Security:DevSecOps integration and API security orchestration address vulnerability management in agile development pipelines.
Cloud security leads on scale; endpoint security leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cybersecurity demand across the Middle East and Africa traces its modern lineage to Gulf banking digitization in the 2010s and subsequent regulatory hardening following high-profile energy sector intrusions. National cybersecurity authorities now mandate localized infrastructure and compressed compliance timelines that reshape procurement geography.
Saudi Arabia
Aramco-tier energy operators and Riyadh banking hubs drive sovereign cloud deployments with mandatory data residency. The National Cybersecurity Authority enforces 72-hour incident reporting and in-country security operations center requirements that disqualify vendors lacking Saudi-based facilities. Eastern Province energy clusters anchor hardware security module procurement for cross-border oil trading encryption.
United Arab Emirates
Dubai's fintech corridor and Abu Dhabi energy headquarters expand managed detection service subscriptions with guaranteed response SLAs. The Telecommunications and Digital Government Regulatory Authority and NESA Information Assurance standards compress vendor qualification timelines toward certified regional providers. Dubai Internet City clusters concentrate zero-trust architecture migration for distributed workforce models.
Israel
Threat intelligence distribution networks and military-grade encryption research anchor cybersecurity export capacity to African telecom operators. Israeli-developed platforms dominate ransomware defense procurement across Nigerian and Kenyan mobile money infrastructure. Tel Aviv cybersecurity clusters specialize in behavioral analytics for subscriber database protection.
South Africa
Johannesburg banking mainframes and Cape Town healthcare networks confront legacy integration friction alongside ransomware targeting patient databases. The National Cybersecurity Hub mandates baseline encryption standards that diverge from Gulf frameworks, complicating pan-regional service architectures. Gauteng financial institutions drive hybrid deployment models accommodating decades-old mainframe systems.
Nigeria
Lagos mobile money platforms and Abuja government digitization programs expand AI-assisted threat hunting for real-time anomaly detection. Underpenetrated incident response capabilities across East African banking corridors create openings for regional security operations center partnerships. Lagos fintech clusters adopt network behavior analytics for subscriber database protection.
Middle East and Africa Cybersecurity Market Competitive Environment
Capital-heavy infrastructure vendors compete with asset-light cloud-native platforms across Gulf enterprise procurement cycles. Market structure concentrates around three tiers: multinational platform providers with regional data center presence, specialized managed detection services with in-country facilities, and local system integrators bridging compliance gaps. Strategic archetypes include sovereign-cloud specialists, zero-trust migration partners, and threat intelligence distributors. Competitive dynamics center on certification timeline acceleration and strategic partnerships with national cybersecurity authorities.
Within the multinational platform tier, IBM Corporation anchors managed detection services through Watson Security deployments across Saudi Aramco-tier energy infrastructure. Palo Alto Networks Inc occupies a position exemplifying Prisma Cloud specialization for hybrid multi-cloud governance in UAE enterprise migrations. Check Point Software Technologies Ltd represents Israeli-developed threat intelligence distribution throughout African telecom network defense procurement. These three entities illustrate divergent geographic and architectural positioning strategies within the same regulatory-compressed market window.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems Inc |
| Palo Alto Networks Inc |
| Check Point Software Technologies Ltd |
| Fortinet Inc |
| LoopTech |
| Digital Security Company (DigiSec) |
| Help AG |
| EMTECH |
| Others |
Value Chain & Pricing Dynamics
Certified security operations analyst scarcity across Gulf Cooperation Council states widens pricing-tier spreads between premium managed detection services and economy-tier appliance resellers. Labor-cost differentials between Riyadh-based Tier III facilities and Dubai fintech corridor deployments compress margins for mid-market providers lacking sovereign cloud certification.
Pricing Analysis
Subscription-based SOC provisioning with consumption-priced threat detection anchors the dominant pricing structure across mid-market UAE enterprises. Price differentiation hinges on NCA certification tier and guaranteed response SLA thresholds, with Aramco-tier energy operators commanding premium multiples over standard banking deployments. Cost compression in the appliance resale tier intensifies as zero-trust migration displaces perpetual license models. Dubai fintech corridor buyers exhibit highest price sensitivity; Saudi critical national infrastructure operators show least sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Hardware security module fabrication workforce availability concentrates in Taiwan, South Korea, and select Chinese manufacturing clusters. Component dependencies span specialized encryption chipsets, carrier-grade network processors, and tamper-resistant physical enclosures. Single-source vulnerability in East Asian semiconductor foundries exposes African telecom operators to extended procurement timelines and currency volatility. Distribution runs through authorized regional system integrators with NCA or NESA certification rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Middle East and Africa cybersecurity rests on sovereign cloud localization requirements that force security stack rebuilds and displace uncertified competitors. Premium-tier capture concentrates with providers owning in-country Tier III facilities.
For Market Incumbents: Deepen vertical integration into localized encryption key management and in-country security operations center infrastructure to defend against cloud-native challengers lacking Saudi NCA certification. Prioritize Riyadh and Dubai facility expansion ahead of narrowing regulatory approval windows. Certification investment in NESA Information Assurance standards represents the critical lever for UAE energy and banking retention. For New Entrants and Emerging Players: AI-assisted threat hunting capabilities offer the most penetrable wedge against established appliance vendors in Nigerian mobile money platforms and Kenyan banking digitization programs. Target underpenetrated East African incident response markets through regional SOC partnerships with local system integrators. Go-to-market execution should emphasize consumption-priced managed detection with guaranteed response SLAs rather than capital-intensive hardware sales. For Investors and Strategic Acquirers: Gulf sovereign wealth funds and national cybersecurity authorities are the most active acquirer categories in this space, consolidating local managed detection capabilities. Long-term viability favors targets with existing NCA or NESA certification and established Tier III facilities in Riyadh or Dubai. Watch for NCA mandate expansion beyond critical national infrastructure as the inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | NCA-mandated in-country SOC requirements disqualify uncertified multinational competitors from Saudi Aramco-tier procurement. |
| Zero-Trust Architecture Migration | Identity-centric verification replaces perimeter appliances across Dubai fintech corridor distributed workforce deployments. |
| AI-Assisted Threat Hunting | Real-time anomaly detection addresses ransomware targeting Nigerian mobile money subscriber databases. |
| Regional SOC Partnership | East African banking digitization programs lack mature incident response capabilities, creating white-space capture opportunities. |
| Hardware Security Module Localization | AWS Riyadh and Azure UAE regions mandate localized encryption key custody for cross-border oil trading compliance. |
Study Parameters
Coverage spans Saudi Arabia, United Arab Emirates, Israel, South Africa, and Nigeria, with primary inputs from each. The approach combines structured interviews with CISOs at Saudi Aramco-tier energy operators, UAE fintech corridor CTOs, and African telecom network security directors with secondary validation from NCA regulatory filings, NESA compliance documentation, and hyperscaler regional capex disclosures. Bottom-up segmentation triangulation against top-down macroeconomic drivers ensures cross-verified output integrity.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models deployment mode, organization size, vertical sector, and regulatory compliance tier as primary segmentation dimensions. CAGRs derive from regression analysis against cloud migration timelines and compliance deadline clustering. Forecast inputs include sovereign cloud localization mandates and zero-trust architecture adoption curves specific to Gulf banking and energy sectors.
The model holds under stable regulatory enforcement timelines and sustained sovereign cloud investment; deviation in NCA mandate expansion pace or East Asian semiconductor supply disruption would shift trajectory. Forecasts reflect documented assumptions about certification timeline compression and skills scarcity persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Asia-Pacific Software Defined Perimeter Market
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
South Korea Ransomware Protection Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
North America Digital Forensics Market
Cybersecurity
Deception Technology Market
Cybersecurity
Bahrain Cybersecurity Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Virtualization Security Tools Market
Cybersecurity
SOC As a Service Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Morocco Cybersecurity Market