
 Wireless Lan Security Market | 2026-2036
Wireless Lan Security Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Lan Security Market Outlook
Managed security service revenue is tilting toward subscription-based cloud delivery as enterprises abandon capital-intensive on-premises appliance refresh cycles. Cisco Systems leverages its Meraki cloud architecture to capture recurring revenue from mid-market clients transitioning away from hardware ownership. Fortinet anchors its position through integrated SD-WAN and security fabric bundles that reduce vendor fragmentation for distributed enterprises. Check Point Software Technologies specializes in advanced threat prevention appliances that sustain premium pricing in regulated verticals requiring hardware-rooted trust.
Wireless LAN security encompasses the protocols, hardware, and software systems that authenticate users, encrypt traffic, and detect intrusions across Wi-Fi infrastructures operating on unlicensed spectrum in the 2.4 GHz, 5 GHz, and 6 GHz bands. Its primary commercial purpose is to prevent unauthorized network access, data exfiltration, and man-in-the-middle attacks that exploit the broadcast nature of radio-frequency communication. Cloud-based deployment now captures the fastest expansion as organizations prioritize elastic capacity and zero-touch provisioning over fixed appliance footprints. WPA3 technology leads encryption standards adoption as hardware vendors phase out legacy WPA2 implementations vulnerable to offline dictionary attacks. Network monitoring solutions concentrate margin pools through AI-driven behavioral analytics that reduce mean-time-to-detection for lateral movement threats.
The FCC governs spectrum allocation and device certification for wireless security hardware sold in the United States, while ETSI harmonizes interoperability standards across European member states and the EU AI Act increasingly scrutinizes automated threat detection systems. NIST cybersecurity frameworks shape procurement requirements for federal contractors, compelling WPA3-Enterprise deployment with certificate-based authentication. Stakeholders must monitor how quantum-resistant encryption mandates from standards bodies will force premature replacement cycles for current-generation hardware acceleration chipsets.
Market Dynamics
Enterprise migration toward cloud-native security architectures is compressing refresh cycles for on-premises wireless LAN controllers as IT departments prioritize operational expenditure predictability over capital-intensive hardware ownership models.
Growth Catalysts
- WPA3-Enterprise Mandates:NIST cybersecurity frameworks compel federal contractors to deploy certificate-based authentication, forcing infrastructure upgrades across defense and civilian agencies in the United States.
- Critical Infrastructure Operators:Power utilities and transportation authorities in Germany face ETSI harmonized standards that mandate hardened encryption for industrial wireless networks.
- AI-Driven Behavioral Analytics:Machine learning intrusion detection systems reduce mean-time-to-detection for lateral movement threats, compelling security operations centers to augment signature-based tools.
Market Restraints
- Semiconductor Supply Concentration:Hardware acceleration chipsets for WPA3 encryption depend on concentrated Asian foundry capacity, exposing vendors to geopolitical disruption risks.
- Legacy WPA2 Interoperability:Backward compatibility requirements delay full deployment of Simultaneous Authentication of Equals protocols in mixed-device environments.
- Radio Spectrum Fragmentation:Divergent 6 GHz band allocation timelines between the FCC and European national regulators complicate multi-region product certification.
Strategic Opportunities
- Managed Security Service Providers:Mid-market enterprises in Japan seek outsourced wireless security operations, creating recurring revenue pools for platform vendors with zero-touch provisioning capabilities.
- Zero Trust Architecture Convergence:Integration of micro-segmentation with wireless access control enables vendors to bundle identity-aware networking across campus and remote deployments.
- Quantum-Resistant Cryptography:Standards bodies are advancing post-quantum encryption specifications that will force premature replacement cycles for current-generation hardware.
Industry Challenges
- Certificate Lifecycle Management:WPA3-Enterprise deployments require skilled personnel to maintain public key infrastructure, a capability scarce among mid-market IT departments.
- Multi-Vendor Integration Complexity:Enterprises struggle to unify policy enforcement across cloud-managed platforms and legacy on-premises controllers during hybrid transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Lan Security Market |
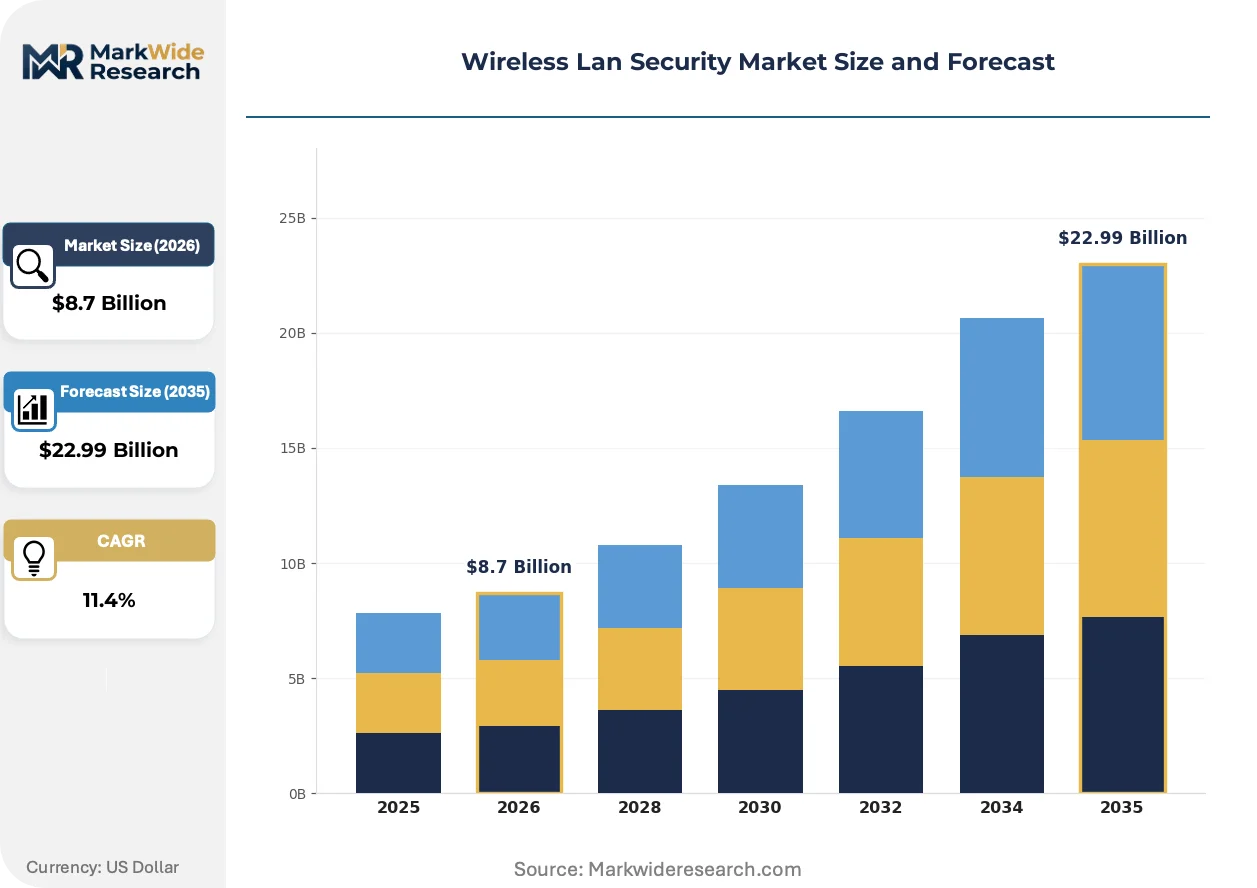
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Access Control, Intrusion Prevention, Encryption, Network Monitoring End User: Enterprises, Educational Institutions, Government, Healthcare Technology: WPA3, VPN, VLAN, Firewalls |
| Companies Covered | Cisco Systems, Aruba Networks, Hewlett Packard Enterprise, Fortinet, Juniper Networks, Palo Alto Networks, Broadcom, Check Point Software Technologies, Ruckus Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Lan Security Market Strategic Shifts
Wireless LAN security is undergoing fundamental restructuring as encryption standards, deployment architectures, and procurement models simultaneously transform vendor competitive dynamics and buyer value expectations.
Cloud-native security service edge platforms are rendering obsolete traditional hardware-bound wireless LAN controllers that require physical appliance deployment at each site. Distributed enterprises with hundreds of branch locations are adopting these architectures fastest, eliminating truck-roll maintenance and enabling centralized policy orchestration. This shift is compressing margins for legacy controller vendors while expanding recurring revenue capture for cloud-first competitors.
The EU AI Act imposes conformity assessment requirements on automated threat detection systems that use machine learning to classify anomalous wireless traffic. Vendors must now document algorithmic transparency and risk management procedures before placing such products on European markets. Security appliance manufacturers are responding by segregating AI-driven analytics modules into separately certifiable software components.
Subscription-based consumption models are displacing perpetual licensing for wireless security software as finance departments prioritize operational expenditure classification. Value-added resellers and systems integrators in the United States are restructuring compensation frameworks to capture recurring service attach rates rather than upfront hardware margins. This transformation is most visible among healthcare and education verticals with constrained capital budgets and stringent compliance requirements.
Wireless Lan Security Market Segmentation
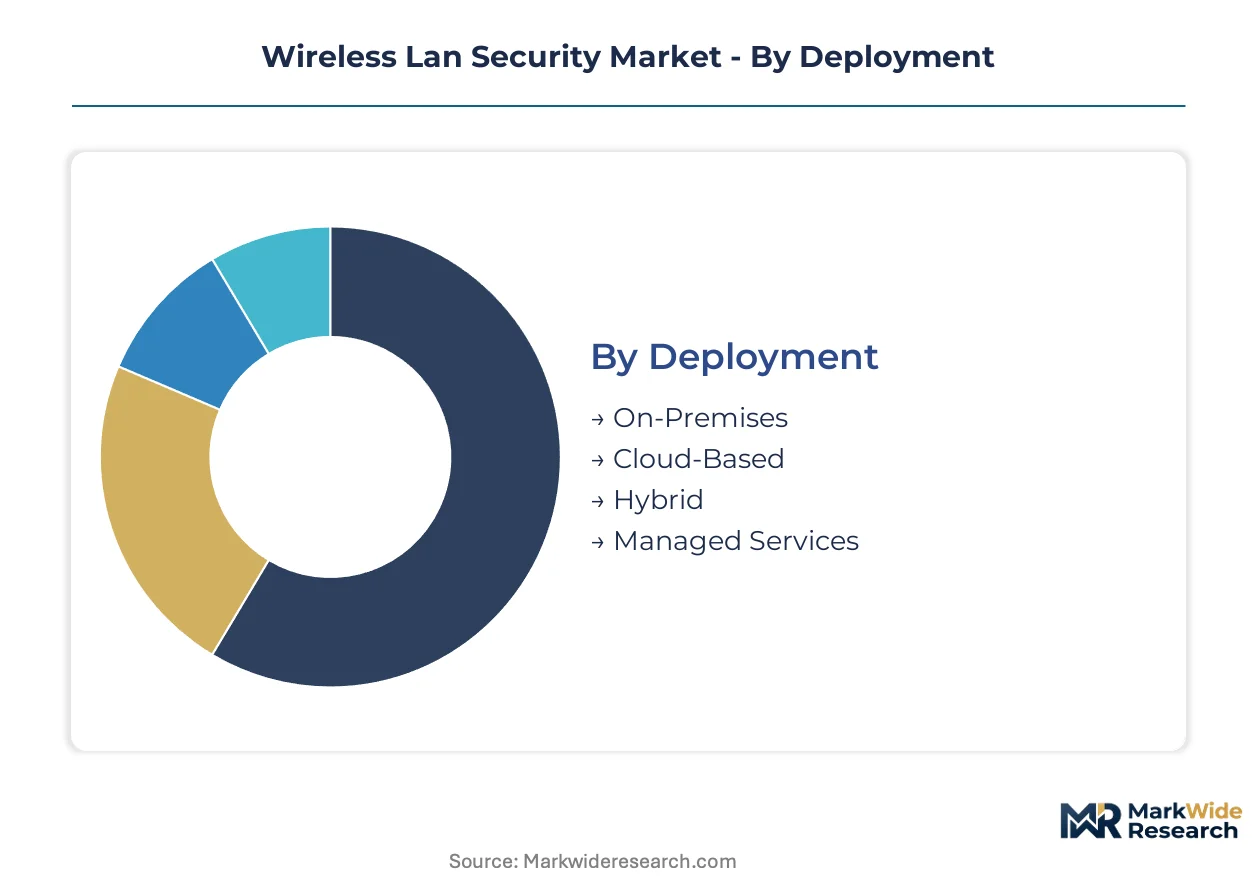
Segmentation in wireless LAN security reveals divergent procurement patterns across deployment architectures, solution types, and compliance-sensitive verticals. Understanding these divisions exposes where vendor margins concentrate and which technology transitions are compressing legacy revenue pools.
Deployment:
Cloud-based architectures turn over fastest as enterprises abandon three-to-five-year appliance refresh cycles, while managed services contracts lock in longest tenure through multi-year operational agreements.
- On-Premises:Hardware controllers and physical appliances deployed at each site require dedicated IT staff for maintenance and certificate management. Defense contractors in the United States maintain these installations to satisfy NIST cybersecurity framework requirements for air-gapped environments where cloud connectivity is prohibited.
- Cloud-Based:Centralized management platforms delivered via subscription enable zero-touch provisioning and elastic capacity scaling. Mid-market enterprises in Germany are migrating fastest to escape capital expenditure constraints and ETSI-mandated encryption upgrade burdens.
- Hybrid:Mixed architectures preserve on-premises controllers at critical sites while extending cloud management to branch locations. Financial services firms in Japan favor this model to segment regulated data flows from general corporate traffic.
- Managed Services:Outsourced security operations where third parties assume full responsibility for monitoring, patching, and incident response. Healthcare systems with limited IT security staffing contract these arrangements to meet HIPAA technical safeguard obligations.
On-premises hardware dominates installed base. Cloud-based deployment is where expansion concentrates.
Solution:
Cost tier stratification separates commodity encryption tools from premium behavioral analytics, with access control solutions commanding widest deployment across budget categories.
- Access Control:Identity verification systems encompassing RADIUS servers, certificate authorities, and multi-factor authentication gateways. Universities in the United States deploy these at scale to manage tens of thousands of transient student devices.
- Intrusion Prevention:Real-time threat detection engines that block malicious traffic through signature matching and anomaly detection. Power utilities in Germany integrate these with industrial control systems under ETSI critical infrastructure mandates.
- Encryption:Protocol implementations securing data in transit across radio frequency channels, now transitioning from WPA2 to WPA3 standards. Hardware acceleration chipsets for AES-256-GCM cipher suites differentiate premium appliance tiers.
- Network Monitoring:Continuous traffic analysis platforms employing machine learning to identify lateral movement and data exfiltration patterns. These solutions face EU AI Act conformity assessment requirements for algorithmic transparency.
Encryption underpins every deployment. Network monitoring is climbing the fastest as AI-driven analytics displace signature-based tools.
End User:
Volume concentration varies sharply by vertical compliance burden, with government and healthcare procurement cycles extending twice as long as commercial enterprise timelines.
- Enterprises:Corporate campuses and distributed branch networks requiring scalable policy orchestration across thousands of access points. Retail chains in Japan prioritize cloud-managed platforms to reduce truck-roll maintenance costs.
- Educational Institutions:K-12 schools and universities managing high-density, high-churn user populations with minimal security staffing. E-Rate funding in the United States subsidizes WPA3 upgrades for public school districts.
- Government:Federal, state, and local agencies subject to NIST cybersecurity framework mandates for certificate-based authentication. Civilian agencies face compressed deployment timelines from FCC spectrum reallocation deadlines.
- Healthcare:Hospitals and clinics protecting patient data under HIPAA technical safeguard requirements. Medical device wireless connectivity introduces unique segmentation challenges for isolated clinical networks.
Enterprises anchor volume demand. Healthcare is gaining share fastest as medical IoT expansion multiplies attack surface exposure.
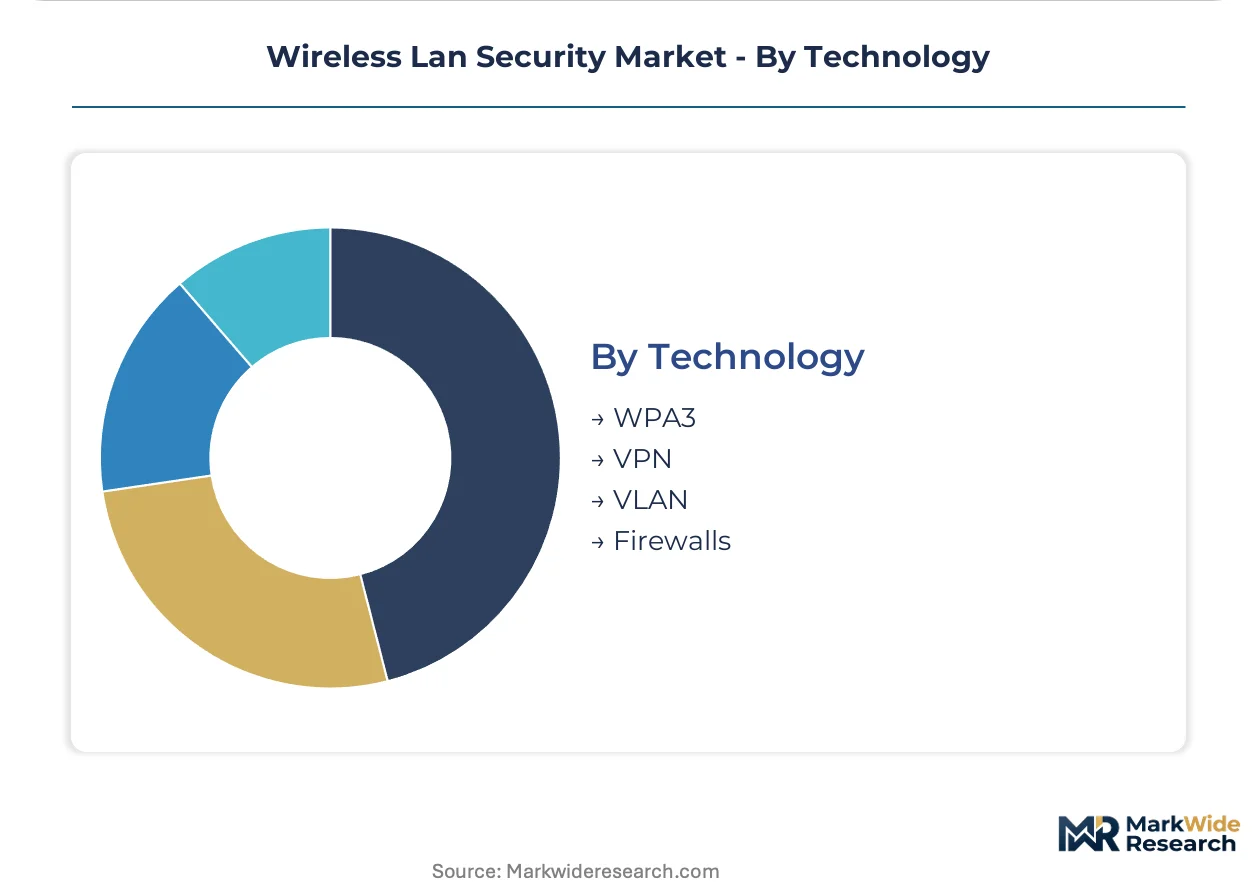
Technology:
Maturity gradients separate established VLAN segmentation from emerging WPA3 implementations, with firewall integration representing the most crowded competitive space.
- WPA3:Latest Wi-Fi Protected Access standard delivering Simultaneous Authentication of Equals and individualized data encryption. FCC device certification requirements are accelerating hardware replacement cycles.
- VPN:Virtual private network tunnels extending encrypted connectivity to remote workers and branch offices. Post-pandemic hybrid work patterns sustain demand for clientless SSL VPN alternatives.
- VLAN:Virtual LAN segmentation isolating traffic across logical network partitions independent of physical topology. Manufacturing facilities in Germany deploy these to separate operational technology from administrative networks.
- Firewalls:Stateful inspection and next-generation firewall appliances filtering traffic between wireless and wired network segments. These face margin compression as cloud-native security service edge platforms absorb functionality.
Firewalls saturate legacy deployments. WPA3 is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian foundries manufacture the bulk of hardware acceleration chipsets for WPA3 encryption, concentrating supply-side exposure in Taiwan and South Korea. FCC device certification timelines in the United States and ETSI harmonization mandates in Germany are accelerating procurement cycles among critical infrastructure operators. Demand concentrates where compliance regimes are strictest.
United States
Federal contractors and defense agencies drive WPA3-Enterprise deployment under NIST cybersecurity framework mandates requiring certificate-based authentication. The FCC governs spectrum allocation and device certification, compressing hardware replacement timelines for civilian agencies facing reallocation deadlines. Security operations concentrate in Washington DC metro and Northern Virginia data center corridors where classified networks demand air-gapped wireless architectures.
Germany
Power utilities and transportation authorities procure hardened encryption under ETSI critical infrastructure standards that harmonize across EU member states. The country's national cybersecurity regulator enforces industrial wireless network segmentation requirements that separate operational technology from administrative traffic. Manufacturing clusters in Bavaria and Baden-Württemberg deploy VLAN isolation for smart factory wireless backbones.
Japan
Mid-market enterprises outsource wireless security operations to managed service providers offering zero-touch provisioning capabilities. METI industrial security guidelines shape procurement for manufacturing networks integrating robotic systems with Wi-Fi connectivity. Tokyo and Osaka financial districts favor hybrid architectures that segment regulated data flows from general corporate traffic across cloud-managed branch locations.
United Kingdom
Financial services firms and government departments align wireless security procurement with NCSC cyber assessment framework requirements. GDPR and emerging EU AI Act conformity pressures shape automated threat detection system selection for cross-border data flows. London's fintech corridor drives demand for identity-aware networking that converges zero trust micro-segmentation with wireless access control.
South Korea
Semiconductor foundries and electronics manufacturers anchor demand for hardware-rooted trust architectures in manufacturing environments. The country's national standards body advances Wi-Fi 6E and 7 certification timelines that outpace regional neighbors, forcing premature infrastructure refresh cycles. Seoul Capital Area enterprise campuses deploy AI-driven behavioral analytics to reduce mean-time-to-detection for lateral movement across dense wireless environments.
Wireless Lan Security Market Competitive Environment
Cloud-native platform specialists and legacy hardware appliance manufacturers split the market along deployment architecture lines. Consolidation pressure intensifies as mid-market enterprises abandon capital-intensive controller refresh cycles in favor of subscription consumption models. Three archetypes dominate: integrated networking-security conglomerates with SD-WAN bundles, pure-play cloud-managed platform vendors, and advanced threat prevention specialists sustaining premium pricing in regulated verticals. Competitive moves center on strategic partnerships for zero-touch provisioning capabilities and portfolio diversification into adjacent security service edge markets.
Within the integrated networking tier, Cisco Systems and Hewlett Packard Enterprise exemplify archetypes spanning cloud-managed and on-premises controller portfolios. Fortinet occupies a position bridging hardware-rooted trust with cloud-delivered service edge convergence. Check Point Software Technologies anchors the specialized threat prevention segment where regulated verticals require hardware-certified encryption modules. Palo Alto Networks and Juniper Networks sit within the platform consolidation wave absorbing legacy controller functionality into broader security fabric architectures.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Hewlett Packard Enterprise |
| Fortinet |
| Juniper Networks |
| Palo Alto Networks |
| Broadcom |
| Check Point Software Technologies |
| Ruckus Wireless |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for WPA3 hardware acceleration chipsets concentrates margin capture upstream, while cloud-managed platform vendors downstream extract recurring revenue through subscription tiers that decouple pricing from physical appliance depreciation cycles.
Pricing Analysis
After-sales service contracts and managed security subscriptions drive lifetime value beyond initial hardware procurement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance certification requirements and AI-driven analytics depth. Cost compression in standard-tier cloud subscriptions is intensifying because hyperscaler infrastructure commoditizes baseline encryption delivery. Mid-market enterprises with constrained IT staffing exhibit highest price sensitivity, while defense contractors facing NIST mandates accept premium hardware-rooted trust pricing.
Supply Chain Analysis
Contract manufacturing for wireless security appliances concentrates with Taiwanese and South Korean EMS providers possessing advanced semiconductor packaging capabilities. Hardware acceleration chipsets draw from concentrated Asian foundry capacity, while RADIUS server appliances and certificate authority modules source from specialized industrial computing assemblers in Germany and Japan. Single-source vulnerability for 6 GHz RF front-end components exposes vendors to FCC certification timeline disruptions. Distribution runs through value-added resellers restructuring compensation around recurring service attach rates rather than upfront hardware margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise wireless LAN security is recovering from pandemic-deferred infrastructure refresh cycles, with WPA3 mandate deadlines from the FCC and ETSI compressing procurement timelines into a concentrated upgrade wave.
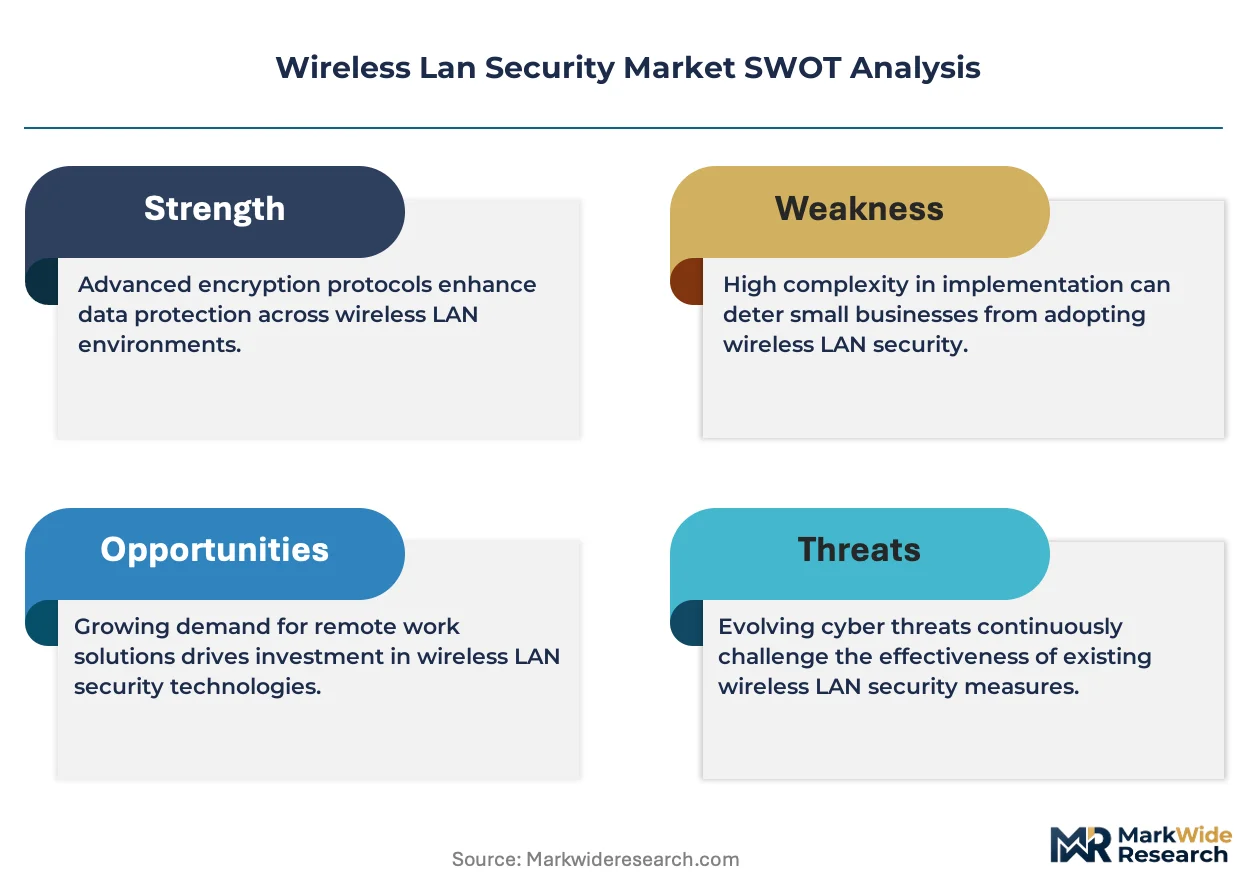
For Market Incumbents: Harden cloud-native platform architectures against margin erosion from open-source encryption libraries threatening proprietary protocol stacks. Prioritize backward integration into hardware acceleration chipset design to reduce foundry dependency exposure. Fortify certificate lifecycle management services to address scarce PKI skills among mid-market buyers. For New Entrants and Emerging Players: Mid-market healthcare systems in the United States represent the most penetrable entry point, given HIPAA technical safeguard obligations and limited in-house security staffing. Japanese manufacturing networks integrating robotic Wi-Fi connectivity offer secondary white-space opportunity. Lead with zero-touch provisioning capabilities that eliminate truck-roll deployment costs for distributed branch architectures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-managed platform vendors possessing recurring revenue bases above seventy percent but lacking SD-WAN integration breadth. Long-term viability hinges on quantum-resistant cryptography readiness forcing premature hardware replacement cycles. Monitor NIST post-quantum encryption standard finalization as inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Zero Trust Architecture Integration | Converges micro-segmentation with wireless access control across campus and remote deployments. |
| Quantum-Resistant Cryptography R&D | Positions vendors ahead of NIST post-quantum standards forcing hardware replacement cycles. |
| Managed Security Service Expansion | Captures recurring revenue from mid-market enterprises abandoning capital-intensive ownership models. |
| AI-Driven Behavioral Analytics Development | Addresses EU AI Act conformity requirements while reducing mean-time-to-detection for lateral threats. |
| Certificate Lifecycle Management Platform | Resolves PKI skills scarcity blocking WPA3-Enterprise adoption among constrained IT departments. |
Study Parameters
A spread of perspectives from enterprise IT procurement officers, managed security service provider executives, hardware vendor product managers, and critical infrastructure cybersecurity directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC device certification databases, ETSI harmonized standards documentation, NIST cybersecurity framework publications, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand projections.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with deployment architecture, solution type, and end-use vertical segmentation driving volume allocations. CAGRs derived from historical trajectory analysis adjusted for regulatory mandate acceleration and technology substitution patterns. Forecast inputs incorporated WPA3 hardware replacement cycle compression and cloud-managed platform adoption curves specific to mid-market enterprise migration patterns.
Macroeconomic conditions sit as an overlay; deviation in enterprise capital expenditure cycles and semiconductor foundry utilization rates would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory timeline adherence and standards body coordination. Quarterly review of FCC certification backlog indicators and ETSI implementation variance across member states is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
North America Software Defined Perimeter Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
Application-Level Encryption Market
Cybersecurity
North America Data Exfiltration Market
Cybersecurity
Belgium Cybersecurity Market
Cybersecurity
Content Delivery Network (CDN) Security Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Spain Cybersecurity Market
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market
Cybersecurity
Big Data Security Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
Global Distributed Denial of Service (Ddos) Protection Market