
 Human Resource (HR) Technology Market | 2026-2036
Human Resource (HR) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Human Resource (HR) Technology Market Intelligence
North American software development is expanding its capacity for AI-native HR platforms. Workday leverages machine learning infrastructure to anchor its position in enterprise workforce planning. SAP sustains R&D intensity across cloud HCM suites that integrate payroll with real-time analytics. Oracle competes through database-layer integration that binds HR data to broader ERP workflows.
Human Resource Technology encompasses software systems, cloud platforms, and analytical tools that automate personnel functions including recruitment, compensation administration, performance tracking, and regulatory compliance, typically deployed through multi-tenant SaaS architectures with API connectivity to enterprise finance and operations systems. Cloud-based deployment now dominates new procurement decisions as organizations retire on-premises legacy systems, while talent management solutions command disproportionate margin attention due to recurring subscription structures and upsell pathways into workforce analytics. Recruitment applications within the broader application layer attract concentrated investment as employers automate candidate sourcing and reduce time-to-hire metrics.
The EU AI Act imposes risk-classification requirements on automated hiring and performance evaluation systems, compelling vendors to document algorithmic transparency and human oversight protocols. In the United States, EEOC guidance and state-level biometric privacy laws in Illinois and Texas constrain facial recognition and sentiment analysis deployments within talent acquisition tools. Stakeholders must monitor how divergent regulatory timelines across jurisdictions fragment product roadmaps and force modular compliance architectures.
Market Dynamics
The HR technology market is undergoing a fundamental restructuring as multi-tenant SaaS architectures displace on-premises legacy systems, with cloud migration now representing the dominant procurement pattern across enterprise and mid-market segments alike.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated hiring systems are compelling employers to upgrade from basic applicant tracking to algorithmically transparent platforms with documented human oversight protocols.
- Healthcare workforce scheduling:North American hospital systems are deploying integrated credentialing and shift-management platforms to address clinical staffing volatility and regulatory audit requirements.
- Real-time payroll analytics:German industrial employers are prioritizing cloud HCM suites that unify compensation administration with live workforce cost visibility across distributed manufacturing operations.
Market Restraints
- Biometric privacy fragmentation:Divergent state-level laws in Illinois and Texas constrain facial recognition deployments within talent acquisition tools, forcing vendors to maintain jurisdiction-specific product variants.
- API integration complexity:Legacy ERP systems in established enterprises resist seamless connectivity with modern HR platforms, extending implementation timelines and inflating professional services costs.
- Algorithmic audit costs:Documentation requirements for EU AI Act compliance impose ongoing compliance expenditures that disproportionately burden mid-market software vendors.
Strategic Opportunities
- Credentialing automation in healthcare:Underpenetrated opportunities exist for platforms that automate license verification and continuing education tracking across multi-state clinical networks.
- Skills-based hiring convergence:Integration of AI-native assessment tools with learning management systems creates white space for vendors linking recruitment to internal mobility pathways.
- GDPR-aligned analytics:Privacy-preserving workforce intelligence tools that embed data minimization by design can capture European employers navigating cross-border data governance.
Industry Challenges
- Machine learning operations talent:Scarce expertise in bias detection and model governance constrains vendor capacity to build compliant algorithmic hiring tools at scale.
- Multi-jurisdiction roadmap fragmentation:Divergent regulatory timelines across the United States, European Union, and Asia-Pacific force modular compliance architectures that complicate product strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Resource (HR) Technology Market |
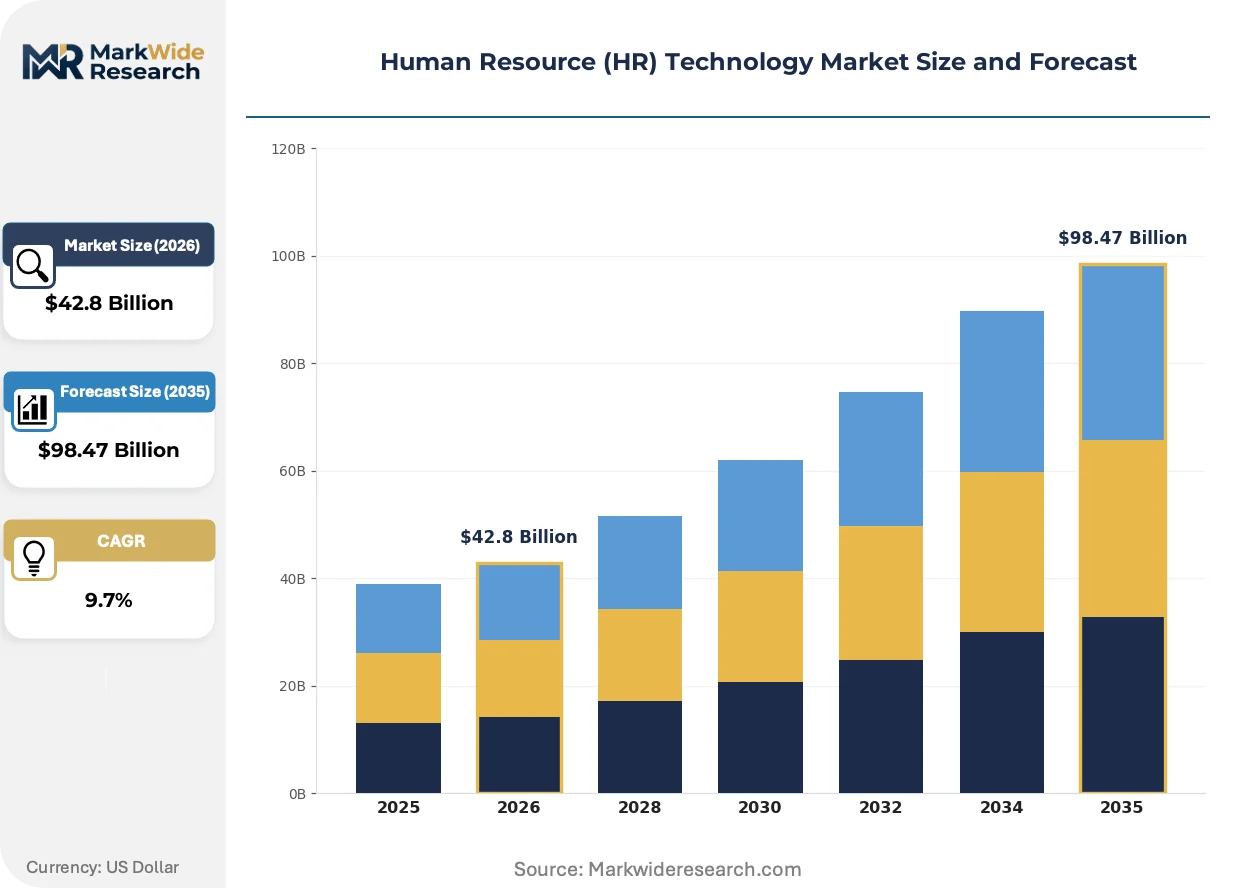
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $98.47 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution/Offering: Talent Management, Payroll Management, Workforce Analytics, Employee Engagement, Compliance Management Application: Recruitment, Performance Management, Learning Development, Compensation Management, Succession Planning End User: Startups, Small & Medium Enterprises, Large Corporations, Recruitment Agencies |
| Companies Covered | Workday, SAP, Oracle, ADP, UKG, Paycom, Paylocity, Cornerstone OnDemand, Ceridian HCM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Resource (HR) Technology Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how organizations acquire, develop, and retain talent, with three distinct forces reshaping competitive positioning across the HR technology stack.
Generative AI is consolidating recruitment workflows by automating job description generation, candidate sourcing, and initial screening communications. Large employers in technology and financial services are deploying these tools to compress time-to-hire metrics while reducing recruiter administrative burden. The structural consequence is consolidation of previously discrete point solutions into unified talent acquisition platforms.
REACH and RoHS compliance frameworks in Europe are extending their influence into HR technology supply chains, particularly affecting hardware-dependent biometric and sentiment analysis tools. Vendors must now document substance restrictions and environmental impact across device manufacturing. German and French employers are responding by prioritizing software-native alternatives that eliminate hardware compliance exposure.
Subscription unbundling is fragmenting traditional HCM suite economics as buyers demand modular procurement of specific functions—recruitment, performance management, compensation planning—rather than monolithic platform commitments. Channel partners and systems integrators are capturing margin by assembling best-of-breed stacks. This pattern is most visible among mid-market employers in the United States seeking to avoid vendor lock-in while maintaining implementation flexibility.
Human Resource (HR) Technology Market Segmentation
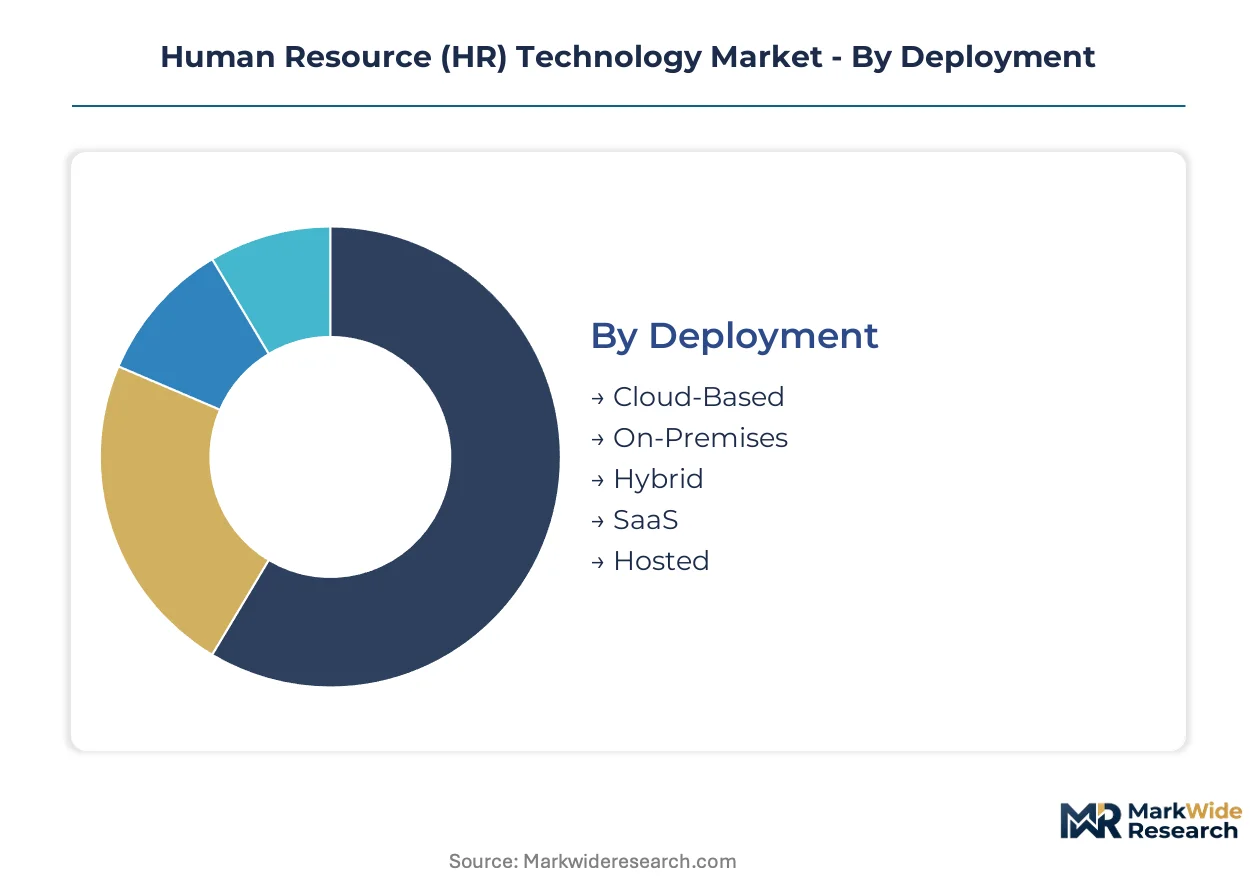
HR technology procurement patterns diverge sharply by organizational scale, regulatory exposure, and IT infrastructure maturity. Deployment preferences cascade through solution selection and end-user targeting, creating distinct competitive arenas that vendors must navigate simultaneously.
Deployment:
Buyers differentiate primarily by IT governance posture and data sovereignty requirements rather than cost alone.
- Cloud-Based:Multi-tenant SaaS architectures dominate new procurement across mid-market employers seeking rapid implementation and automatic updates. German industrial manufacturers and North American hospital systems prioritize these platforms for real-time workforce analytics and clinical credentialing integration.
- SaaS:Subscription-native delivery with API-first design enables modular procurement of specific HR functions without monolithic suite commitments. United States mid-market employers drive concentrated demand as they retire legacy on-premises systems.
- Hybrid:Split deployments maintain sensitive payroll and biometric data on-premises while routing talent acquisition workflows to cloud infrastructure. European employers navigating GDPR cross-border restrictions favor this architecture.
- On-Premises:Single-tenant installations persist among defense contractors and financial institutions with stringent data residency mandates.
- Hosted:Managed private cloud deployments offer dedicated infrastructure without full capital burden, attracting regulated industries in Switzerland and the UAE.
Volume sits with Cloud-Based and SaaS; growth tilts toward Hybrid as data sovereignty concerns intensify.
Solution/Offering:
Margin concentration follows recurring subscription structures and upsell pathways into adjacent modules.
- Talent Management:Integrated platforms spanning recruitment, onboarding, and development command premium pricing due to sticky user adoption and expansion revenue potential. Demand concentrates in Germany where industrial employers prioritize unified workforce planning.
- Payroll Management:Real-time compensation administration with live cost visibility across distributed operations. North American healthcare systems deploy these systems to manage clinical staffing volatility.
- Workforce Analytics:Privacy-preserving intelligence tools embedding data minimization by design capture European employers navigating GDPR complexity.
- Employee Engagement:Pulse survey and sentiment analysis platforms face biometric privacy constraints in Illinois and Texas.
- Compliance Management:Automated credential tracking and audit documentation address multi-state clinical network requirements.
Revenue pools deepest in Talent Management; steepest expansion trajectory belongs to Workforce Analytics as predictive capabilities mature.
Application:
Functional priority reflects organizational lifecycle stage and competitive pressure on specific talent outcomes.
- Recruitment:AI-native sourcing and screening tools compress time-to-hire metrics for technology and financial services employers. EU AI Act risk-classification requirements are compelling upgrades from basic applicant tracking to algorithmically transparent platforms.
- Performance Management:Continuous feedback systems replace annual review cycles in knowledge-intensive sectors. Large corporations drive adoption as they flatten management hierarchies.
- Learning Development:Skills-based pathways linking assessment to internal mobility create white space for vendors integrating with talent acquisition.
- Compensation Management:Pay equity analytics and variable compensation modeling attract regulatory scrutiny in multiple jurisdictions.
- Succession Planning:Leadership pipeline tools see renewed investment as demographic transitions accelerate executive turnover.
Adoption is broadest in Recruitment; investment intensity is climbing fastest in Learning Development as reskilling imperatives mount.
End User:
Organizational scale dictates solution complexity, implementation timeline, and vendor relationship economics.
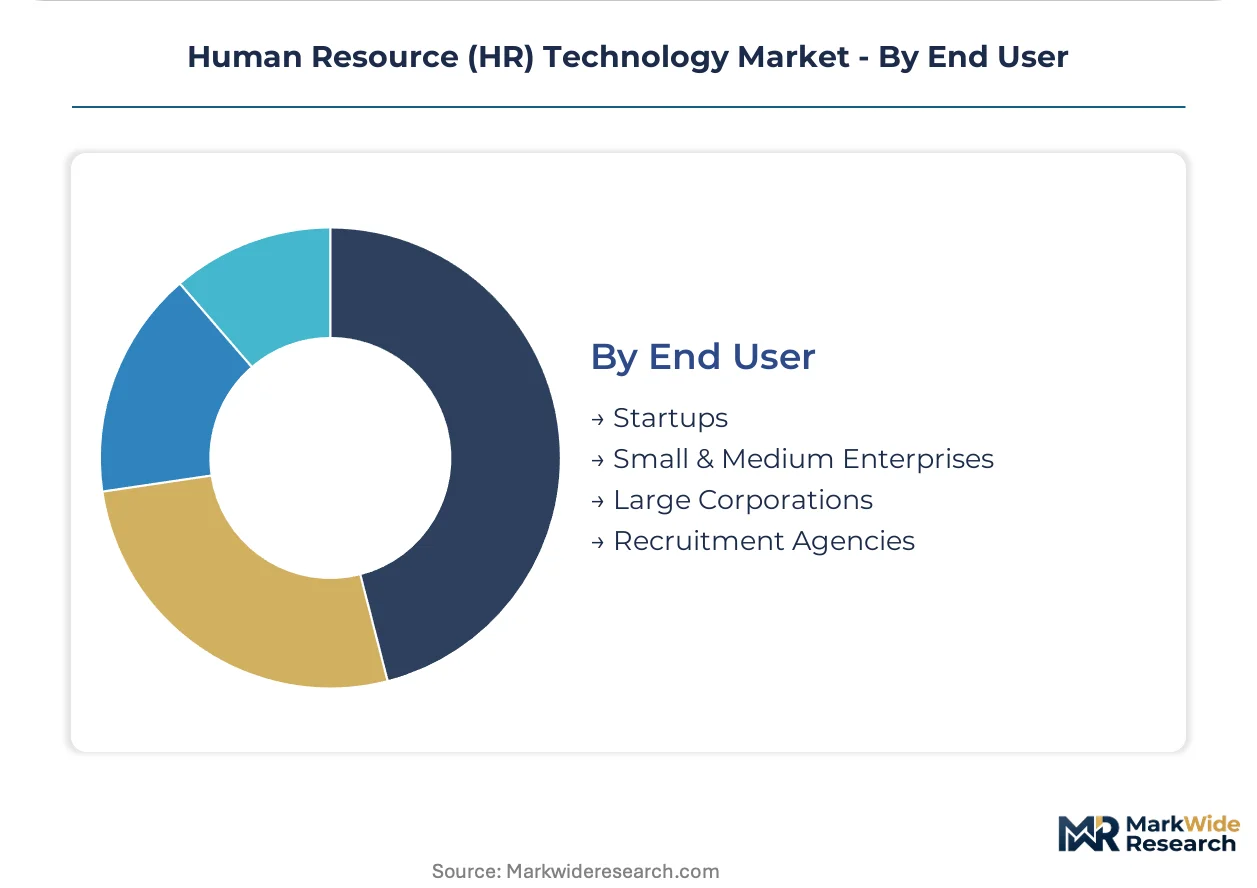
- Large Corporations:Global HCM suite deployments with deep ERP integration and multi-country payroll consolidation. These buyers command dedicated customer success resources and influence product roadmaps.
- Small & Medium Enterprises:Modular best-of-breed procurement assembled through channel partners and systems integrators. United States employers in this segment seek implementation flexibility without vendor lock-in.
- Recruitment Agencies:High-volume candidate processing platforms with white-label client portal capabilities and commission tracking.
- Startups:Lightweight, mobile-first tools with rapid self-service configuration and per-employee pricing that scales with headcount.
Contract value concentrates with Large Corporations; net new customer acquisition expands most quickly among Small & Medium Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American HR technology deployment, while regulatory divergence across jurisdictions fragments vendor compliance architectures and shapes procurement patterns.
United States
Healthcare systems in Texas and Illinois deploy clinical credentialing platforms to manage multi-state nursing licenses and shift volatility. EEOC guidance and state biometric privacy laws constrain facial recognition in talent acquisition tools. Chicago hospital networks integrate payroll analytics with real-time staffing dashboards.
Germany
Industrial employers in Baden-Württemberg prioritize unified talent management platforms linking recruitment to workforce planning. REACH and RoHS compliance frameworks extend into HR technology supply chains, affecting hardware-dependent biometric tools. Munich manufacturing clusters drive demand for cloud HCM suites with live cost visibility.
United Kingdom
Financial services firms in London deploy AI-native assessment tools for skills-based hiring and internal mobility pathways. GDPR cross-border data governance shapes hybrid deployment preferences for sensitive payroll data. The City of London's regulatory technology sector influences compliance management platform specifications.
India
IT services hubs in Bengaluru and Hyderabad drive adoption of modular recruitment automation for high-volume campus hiring. The country's national data protection framework shapes cloud procurement decisions among multinational employers. Mumbai financial services firms invest in workforce analytics for distributed team management.
Japan
Manufacturing employers in the Nagoya industrial corridor integrate performance management systems with seniority-based compensation structures. METI guidelines on AI governance influence algorithmic hiring tool procurement. Tokyo-headquartered corporations demand HCM platforms with multi-language support for regional operations.
Human Resource (HR) Technology Market Key Industry Players
Global majors compete with regional champions across compliance specialization and vertical integration depth. The market structure tilts toward consolidated enterprise suites while mid-market procurement fragments across best-of-breed assemblages. Three archetypes dominate: cloud-native platforms with AI-first architectures, legacy ERP-integrated suites with database-layer advantages, and vertical specialists targeting healthcare or manufacturing workflows. Competitive moves concentrate on strategic partnerships with systems integrators and modular unbundling to capture mid-market flexibility demand.
Within the enterprise suite tier, Workday and SAP exemplify cloud-native and ERP-integrated archetypes respectively, while Oracle occupies a position bridging database infrastructure with HCM applications. These three entities represent contrasting approaches to workforce data architecture—machine learning infrastructure, R&D intensity across cloud suites, and database-layer integration binding HR to broader enterprise workflows.
| Leading Market Players |
|---|
| Workday |
| SAP |
| Oracle |
| ADP |
| UKG |
| Paycom |
| Paylocity |
| Cornerstone OnDemand |
| Ceridian HCM |
| Others |
Cost & Logistics Intelligence
Machine learning operations talent concentration in Silicon Valley and Bengaluru connects labor-cost differentials to pricing-tier spreads across cloud-native and legacy-integrated HR platforms. German industrial buyers absorb premium SaaS rates for real-time workforce analytics, while mid-market employers in the United States negotiate modular unbundling to compress subscription commitments.
Pricing Analysis
Warranty and professional services bundling separates premium-tier deployments from standard self-service configurations in the HR technology market. Three-tier pricing structure across premium, standard, and economy levels reflects integration complexity and dedicated customer success resources. Pricing pressure stems from subscription unbundling demands as mid-market buyers assemble best-of-breed stacks through channel partners. Small and medium enterprises exhibit highest price sensitivity, while large corporations with multi-country payroll consolidation accept premium positioning for roadmap influence.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure and AI model training capacity are becoming standard in enterprise HR technology procurement. Supply concentrates in the United States, Germany, and India for platform development, with Taiwan and South Korea anchoring semiconductor dependencies for hardware-dependent biometric tools. Raw material and component dependencies include advanced GPUs, specialized memory modules, and rare earth elements for sensor manufacturing. Single-source vulnerability in GPU supply chains creates concentration risk for AI-native assessment vendors. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU AI Act compliance costs force mid-market vendors toward acquisition or exit. Algorithmic audit expenditures and multi-jurisdiction roadmap fragmentation disproportionately burden smaller players lacking dedicated governance infrastructure.
For Market Incumbents: Anticipate regulatory divergence by modularizing compliance architectures that isolate jurisdiction-specific variants from core platform code. SAP and Workday should deepen API-first design investments to capture systems integrator margin as channel partners assemble best-of-breed stacks. Oracle's database-layer integration advantage positions it to bind HR data more tightly to broader ERP workflows, defending against cloud-native displacement. For New Entrants and Emerging Players: Enter via credentialing automation in North American healthcare, where license verification and continuing education tracking remain underpenetrated across multi-state clinical networks. Skills-based hiring convergence creates accessible white space for vendors linking AI-native assessment tools to learning management systems. Channel partnership with healthcare-focused systems integrators offers the most penetrable go-to-market angle against entrenched suite vendors. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists targeting healthcare workforce scheduling given clinical staffing volatility and regulatory audit tailwinds. Long-term viability favors vendors with demonstrated EU AI Act compliance documentation and established hospital system referenceability. The signal to watch is acceleration in German industrial cloud HCM procurement, which would validate unified talent management platform economics and trigger consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified talent management suites capture German industrial employers prioritizing workforce planning connectivity. |
| Strategic Partnership | Systems integrator alliances enable mid-market penetration without direct sales infrastructure expansion. |
| Acquisition of Specialist Firm | Healthcare credentialing automation targets address regulatory audit requirements across multi-state clinical networks. |
| Geographic Expansion | GDPR-aligned analytics development captures European employers navigating cross-border data governance complexity. |
| Product Launch | Privacy-preserving workforce intelligence tools embed data minimization by design for EU AI Act compliance. |
Research Approach
Document review covered SEC 10-K filings, EU regulatory submissions, and healthcare procurement databases, complemented by interviews with CHROs, IT procurement officers, and systems integrator partners. Primary fieldwork engaged platform engineers, compliance officers at hospital networks, and channel sales heads across North America and Europe. Secondary validation drew from EEOC guidance documents, GDPR implementation reports, and cloud marketplace transaction data. Bottom-up sizing of vendor revenue streams and top-down cross-reference against employer technology spend surveys ensured triangulation integrity.
Historical growth patterns were cross-referenced against executive panel input regarding procurement intention and budget allocation. The analytical framework modeled deployment model, organization size, vertical industry, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level trajectory blending and macroeconomic sensitivity testing. Forecast inputs included EU AI Act implementation timelines, healthcare workforce shortage projections, and cloud infrastructure capex disclosures from hyperscalers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged GPU supply constraints. Deviation in German industrial cloud HCM adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Shipping Software Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Product As a Service Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Managed File Transfer (MFT) Market