
 Global SMS Firewall Market | 2026-2036
Global SMS Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Global SMS Firewall Market Foresight
GDPR enforcement is consolidating compliance costs for messaging infrastructure vendors entering European markets. Syniverse Technologies leverages its signaling heritage to anchor premium-tier carrier relationships across North America and Western Europe. Infobip competes through cloud-native delivery models that reduce deployment friction for mid-tier mobile operators. Comviva specializes in emerging-market configurations, sustaining price-accessible threat detection for operators in Africa and South Asia.
An SMS firewall is a network security gateway that inspects SS7, SIGTRAN, and Diameter signaling traffic at protocol layers three through seven, applying real-time heuristic and machine-learning classification to block spoofed, spam, or fraudulent message injections before termination. Its primary purpose is preserving signaling channel integrity, revenue assurance for application-to-person traffic, and subscriber trust in operator-mediated communications. Cloud-based deployment represents the fastest-expanding configuration as hyperscaler partnerships allow operators to bypass capital-intensive hardware refresh cycles. Threat detection and fraud prevention solutions command the deepest margin pools because carriers bundle these capabilities into tiered enterprise API offerings rather than standalone licenses. Mobile financial services application demand is displacing traditional telecom-operator-centric procurement as neobanks and payment processors seek direct API access to carrier-grade filtering.
The EU AI Act, GDPR, and the UK's Ofcom codes jointly shape product roadmaps by mandating explainable automated decision-making in content filtering and imposing steep penalties for unlawful interception. India's TRAI and the US FCC impose divergent consent architectures—opt-in versus opt-out—that force vendors to maintain modular policy engines across deployments. Stakeholders must monitor whether emerging SIM swap and artificial sender ID spoofing vectors outpace heuristic signature libraries before regulators mandate predictive rather than reactive compliance standards.
Market Dynamics
Cloud-native SMS firewall architectures are compressing hardware refresh cycles as mobile operators outsource signaling security to hyperscaler partnerships, fundamentally restructuring vendor competitive dynamics toward API-first delivery models.
Growth Catalysts
- India's TRAI mandates:Carrier investment in real-time threat detection systems accelerates as UPI-linked authentication volumes surge across mobile banking networks.
- EU AI Act compliance:European telecom operators upgrade filtering architectures to meet explainable automated decision-making requirements for content interception.
- SIM swap fraud vectors:Mobile financial services providers demand carrier-grade filtering APIs as artificial sender ID spoofing attacks proliferate across payment authentication channels.
Market Restraints
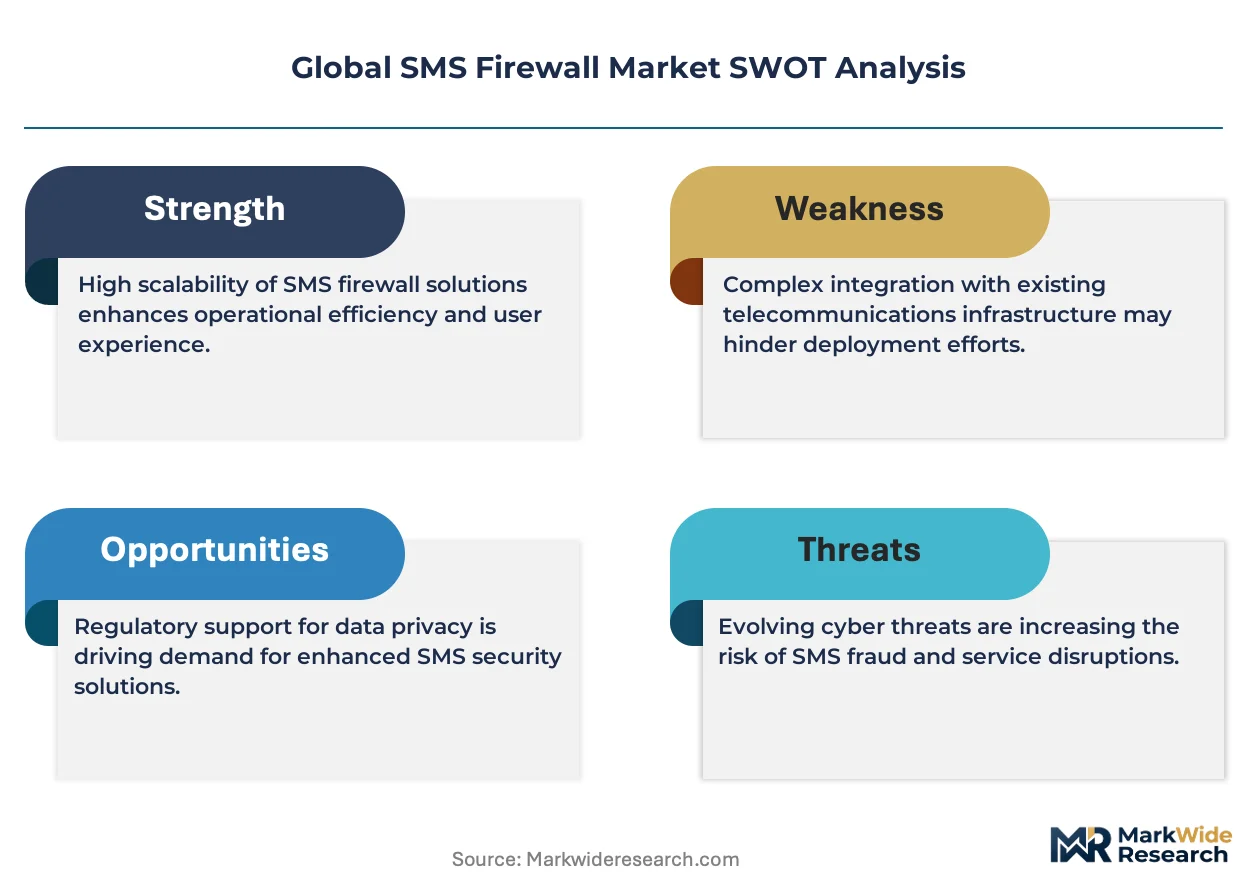
- SS7 protocol vulnerabilities:Legacy signaling infrastructure exposes persistent attack surfaces that cloud overlays cannot fully remediate without core network replacement.
- GDPR penalty exposure:Unlawful message interception carries steep fines that deter aggressive filtering deployments in European markets.
- Hyperscaler dependency:Concentrated cloud infrastructure supply from US-based providers creates geopolitical risk for operators in sanctioned or data-sovereignty jurisdictions.
Strategic Opportunities
- Neobank direct API access:Payment processors in Southeast Asia seek bypass of traditional telecom procurement channels for embedded fraud prevention.
- 5G SA core migration:Convergence of SMS firewall functions with network exposure platforms enables unified signaling security across Diameter and HTTP/2 interfaces.
- Brazil's ANVISA medical messaging rules:Pharmaceutical authentication requirements create regulated demand for tamper-evident A2P delivery verification.
Industry Challenges
- Heuristic signature latency:Machine learning model training cycles lag behind zero-day spoofing techniques, forcing reactive posture against predictive compliance standards.
- Multi-jurisdiction policy engines:Modular consent architectures for opt-in versus opt-out regimes fragment product development roadmaps across deployment regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SMS Firewall Market |
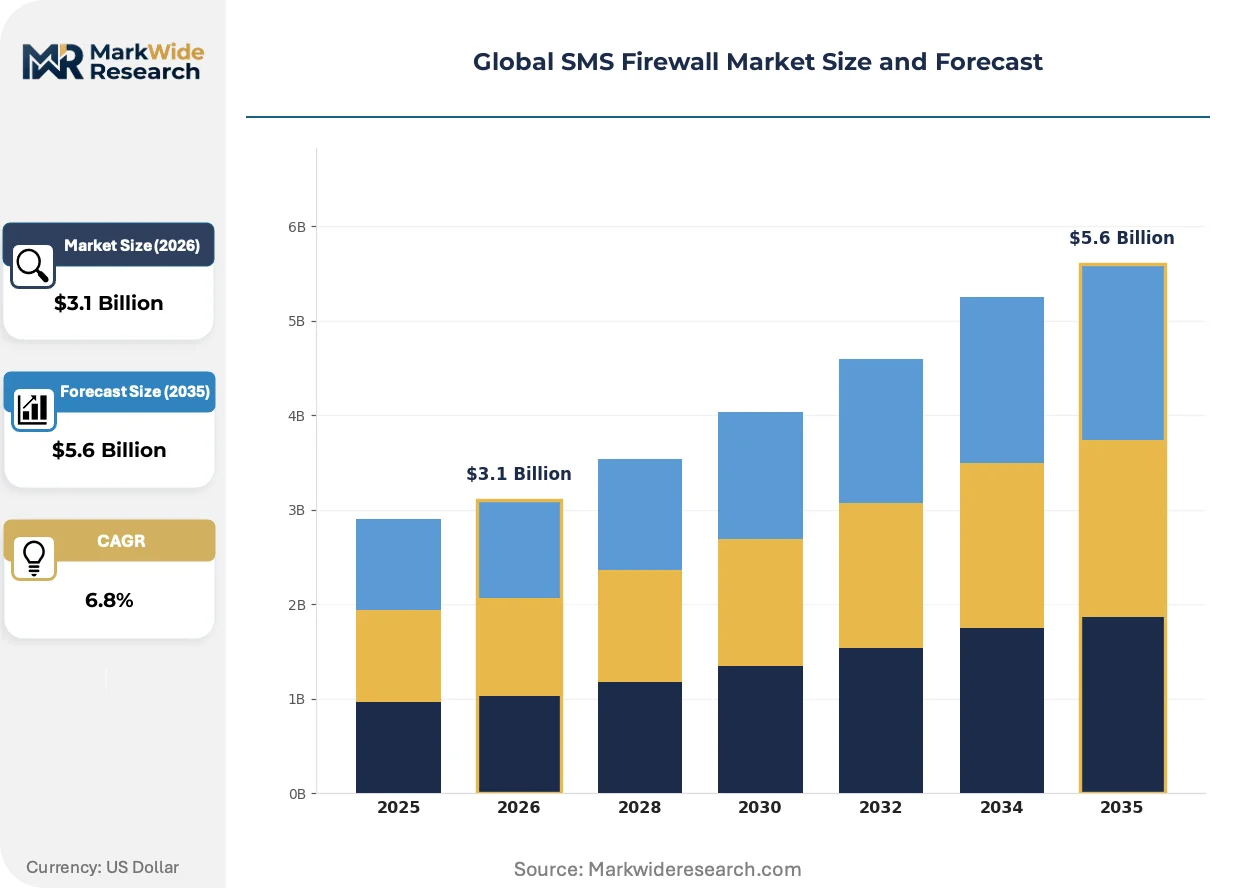
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution Type: Threat Detection, Spam Filtering, Fraud Prevention, Regulatory Compliance, Traffic Monitoring Application: Telecom Operators, Enterprise Messaging, Mobile Financial Services, Government Communications, Marketing Campaigns End User: Mobile Network Providers, Banking Institutions, E-Commerce Companies, Public Safety Organizations, Media Companies |
| Companies Covered | Syniverse Technologies, Infobip, Comviva, BICS, Cellusys, Route Mobile Limited, Tata Communications, SAP SE, Sinch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SMS Firewall Market Shifts & Advancements
Machine learning classification engines are compressing detection latency windows, while regulatory mandates for explainable AI reshape product architecture requirements across major telecom markets.
Real-time behavioral biometrics fused with signaling analysis is rewriting fraud detection capabilities. Mobile banking institutions in Indonesia and the Philippines deploy these hybrid models to flag anomalous SMS patterns before message termination. The technology compresses false-positive rates that previously degraded subscriber trust in operator-mediated authentication flows.
The EU AI Act's explainability mandates force vendors to retrofit black-box ML models with interpretable decision trails. European operators now demand audit-ready filtering logic that satisfies both GDPR interception rules and national telecom regulator scrutiny. This regulatory pressure fragments product roadmaps as vendors maintain separate compliance modules for European versus non-European deployments.
Enterprise buyers now unbundle security filtering from messaging transport, procuring direct API access to carrier-grade threat detection. Neobanks and payment processors in India and Brazil contract with firewall vendors independently of host operator relationships. This channel disintermediation concentrates margin capture with specialized security vendors while commoditizing traditional SMS transit services.
Global SMS Firewall Market Segmentation
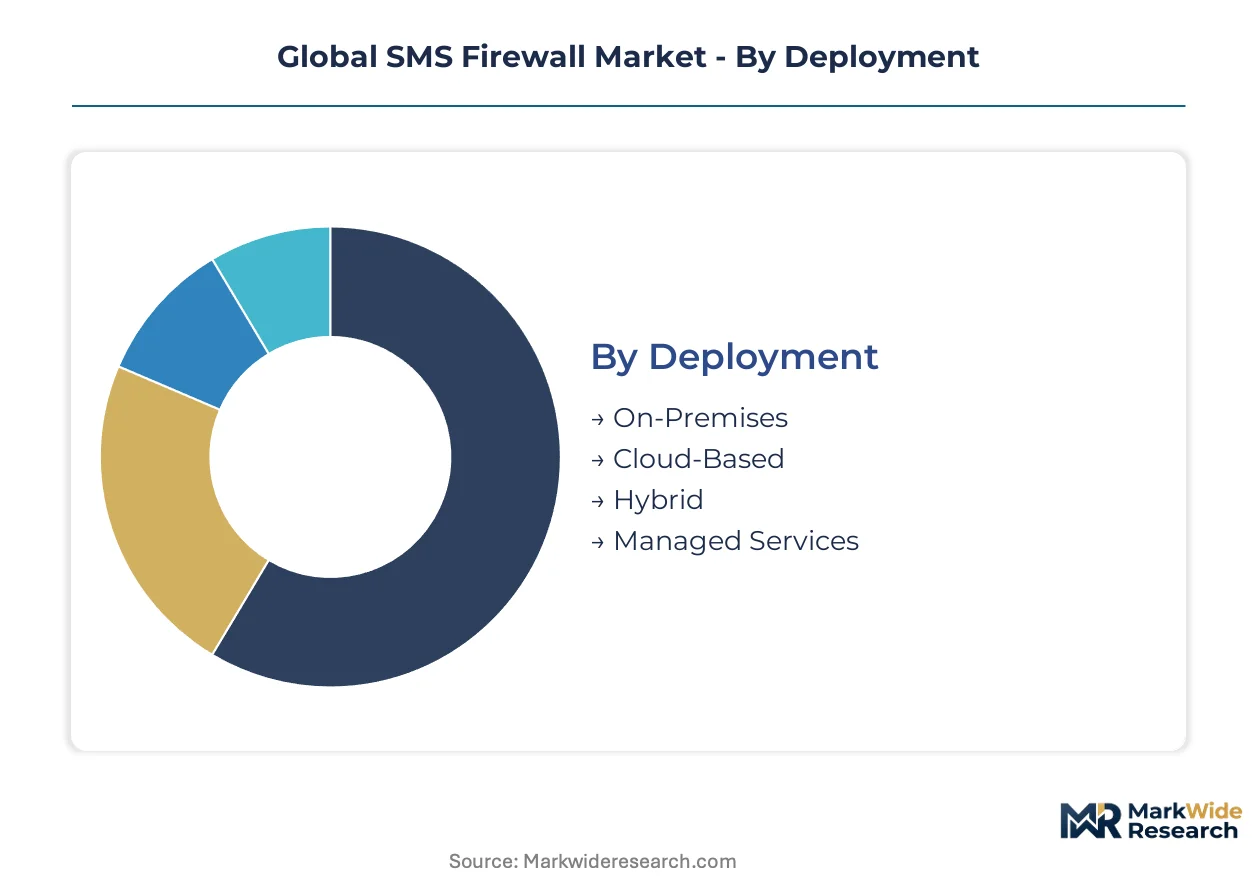
SMS firewall procurement patterns diverge sharply across deployment models, solution architectures, and end-user sophistication levels. Understanding these fault lines reveals where vendor margin pools concentrate and which customer segments drive technology roadmaps.
Deployment:
Customization intensity spans from fully managed outsourcing to rigid on-site hardware, with hybrid configurations occupying the negotiable middle ground.
- On-Premises:Dedicated hardware appliances inspect SS7 and SIGTRAN signaling at carrier core network locations. Tier-1 operators in Germany and Japan maintain these deployments for data sovereignty compliance and sub-millisecond latency requirements in high-frequency trading authentication corridors.
- Cloud-Based:Hyperscaler-hosted filtering layers scale elastically with A2P traffic volumes. Indian and Brazilian mobile operators favor this model to bypass capital-intensive refresh cycles while meeting TRAI and ANATEL audit requirements through API-accessible policy engines.
- Hybrid:Split architectures route sensitive signaling through on-premises inspection while offloading bulk spam filtering to cloud tiers. This configuration balances latency-critical authentication traffic against cost-sensitive promotional messaging volumes.
- Managed Services:Outsourced security operations centers monitor and tune filtering policies on operator behalf. Mid-tier carriers across Southeast Asia contract these arrangements to compensate for internal cybersecurity skills gaps.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Managed Services as skills scarcity deepens across emerging-market operator workforces.
Solution Type:
Margin capture concentrates in capabilities that carriers can bundle into tiered enterprise API offerings rather than standalone license sales.
- Threat Detection:Real-time heuristic and machine-learning classification engines identify zero-day spoofing vectors before message termination. Mobile banking networks in Indonesia and the Philippines embed these APIs directly into payment authentication flows, bypassing traditional telecom procurement channels.
- Spam Filtering:Content-based rules and sender reputation scoring block unsolicited bulk messaging. This capability faces commoditization pressure as regulatory consent frameworks fragment between opt-in and opt-out jurisdictions.
- Fraud Prevention:Behavioral biometrics fused with signaling analysis flag SIM swap and artificial sender ID attacks. EU AI Act explainability mandates force vendors to retrofit black-box models with interpretable decision trails for German and French operator deployments.
- Regulatory Compliance:Modular policy engines automate lawful interception and data retention across GDPR, TRAI, and FCC divergent architectures. Vendors maintain separate code branches for European versus non-European deployments.
- Traffic Monitoring:Signaling intelligence dashboards provide visibility into A2P revenue leakage and gray-route termination. This foundational capability underpins revenue assurance contracts but commands thinner margins than predictive security layers.
Revenue assurance contracts concentrate in Traffic Monitoring. Value capture is climbing fastest in Fraud Prevention as neobanks and payment processors seek direct API access to carrier-grade filtering.
Application:
Demand origination is shifting from traditional telecom-centric procurement toward embedded finance and government security mandates.
- Telecom Operators:Core network protection remains the foundational use case, with carriers upgrading filtering architectures to preserve signaling channel integrity and A2P revenue streams.
- Enterprise Messaging:Large organizations deploy private SMS firewalls to secure customer notification channels against brand-impersonation attacks.
- Mobile Financial Services:Neobanks and payment processors in India and Brazil contract directly with firewall vendors for real-time authentication protection. This segment is gaining share fastest as channel disintermediation concentrates margin capture with specialized security providers.
- Government Communications:Public sector deployments emphasize tamper-evident delivery verification and lawful interception compliance for critical infrastructure alerts.
- Marketing Campaigns:Promotional messaging platforms use filtering to maintain sender reputation scores and avoid carrier blacklisting.
Contract volume flows predominantly through Telecom Operators. Growth is most pronounced in Mobile Financial Services as embedded finance expands across emerging-market payment ecosystems.
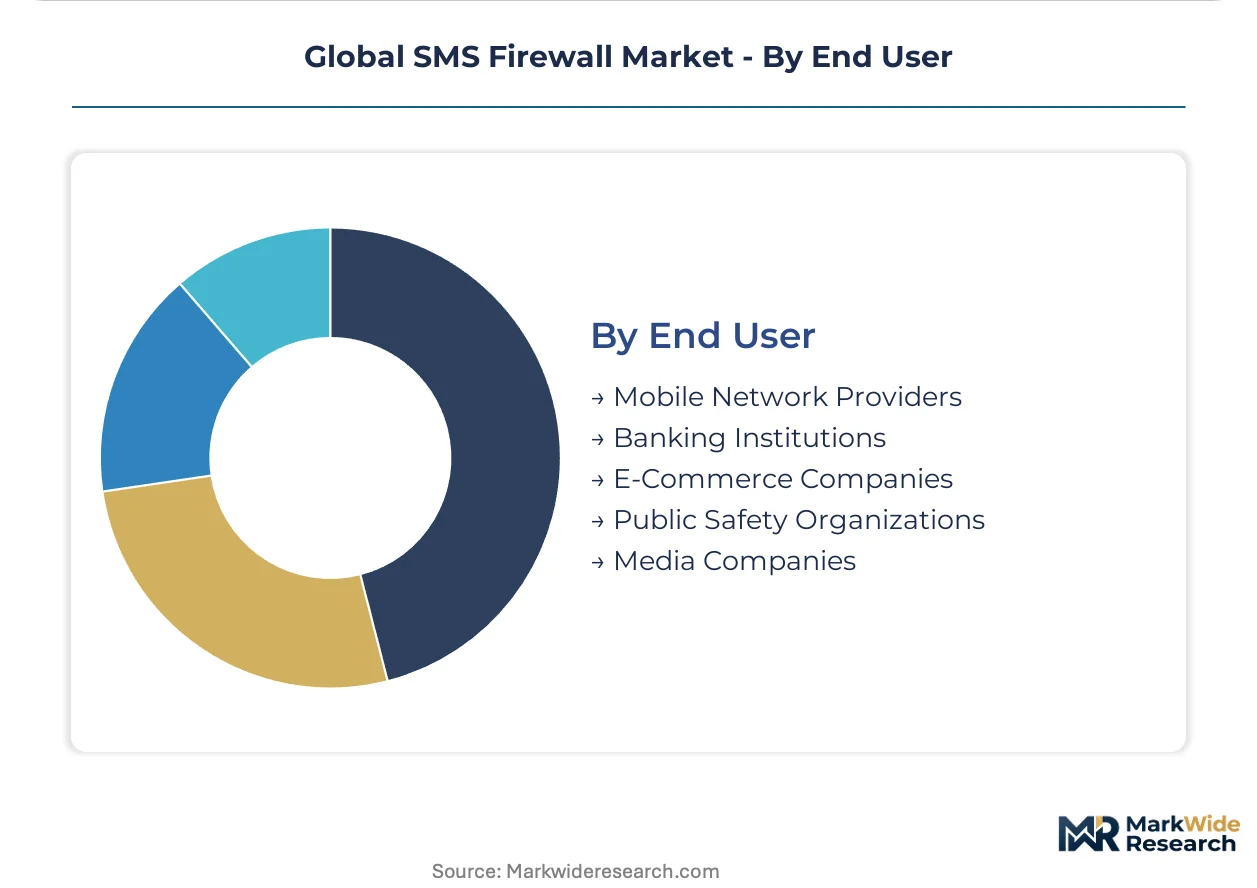
End User:
Procurement sophistication varies from centralized carrier security operations to distributed enterprise IT departments with limited telecommunications expertise.
- Mobile Network Providers:The traditional anchor customer, these entities demand carrier-grade throughput and five-nines reliability for core network deployment.
- Banking Institutions:Regulatory pressure from RBI in India and central bank guidelines across Southeast Asia accelerate investment in real-time threat detection for UPI-linked and comparable instant payment authentication.
- E-Commerce Companies:Transaction notification security and delivery verification drive adoption among marketplace operators with high customer touchpoint volumes.
- Public Safety Organizations:Emergency alert systems require prioritized message routing and spoofing protection to maintain citizen trust in official communications.
- Media Companies:Content distribution platforms use filtering to prevent piracy notification interception and maintain subscriber relationship integrity.
Deployment scale concentrates with Mobile Network Providers. Procurement velocity is accelerating most sharply among Banking Institutions as mobile payment authentication volumes surge across regulated financial networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cybersecurity talent pools in Bangalore, Tel Aviv, and Tallinn anchor regional firewall development clusters across three continents. These concentrations supply machine-learning engineers and signaling protocol specialists to vendor engineering centers. Carrier procurement decisions follow divergent regulatory timelines in each jurisdiction.
United States
Mobile banking authentication volumes from JPMorgan Chase and Bank of America drive enterprise SMS firewall procurement. FCC opt-out consent frameworks shape modular policy engine requirements for domestic deployments. Dallas-Fort Worth hosts carrier security operations centers where AT&T and Verizon maintain real-time threat detection infrastructure.
Germany
Deutsche Telekom and Vodafone Germany upgrade filtering architectures to satisfy GDPR interception rules and EU AI Act explainability mandates. KBA automotive cybersecurity guidelines extend to payment authentication channels in connected vehicle ecosystems. Munich engineering clusters develop audit-ready ML decision trails for carrier-grade deployments.
India
UPI-linked transaction volumes exceeding daily peaks force HDFC Bank and ICICI Bank to contract directly with firewall vendors. TRAI mandates on unsolicited commercial communications accelerate carrier investment in real-time filtering systems. Bangalore's Whitefield technology corridor concentrates vendor development centers serving Asia-Pacific operator procurement.
Brazil
Pix instant payment authentication drives Banco do Brasil and Nubank to seek carrier-grade filtering APIs independent of host operators. ANATEL audit requirements for A2P messaging traceability shape cloud-based deployment preferences. São Paulo's Berrini financial district anchors fintech procurement negotiations with specialized security vendors.
United Kingdom
Revolut and Monzo neobanks demand embedded fraud prevention through direct API access to signaling security layers. Ofcom codes on automated decision-making intersect with GDPR enforcement to filter vendor product roadmaps. London's Canary Wharf hosts banking security procurement teams negotiating independent firewall contracts.
Global SMS Firewall Market Competitive Landscape
The competitive structure tilts toward signaling heritage specialists with deep carrier relationships rather than cloud-native challengers. Tier-1 mobile operators in Western Europe and North America consolidate procurement around vendors with SS7 protocol expertise. Three archetypes dominate: legacy signaling infrastructure providers, cloud-native messaging platforms, and emerging-market configuration specialists. Strategic moves concentrate on hyperscaler partnership formations and direct API channel development with financial services buyers.
Within the signaling heritage tier, Syniverse Technologies occupies a position exemplifying deep carrier integration across North American and Western European markets. Infobip represents the cloud-native delivery model reducing deployment friction for mid-tier operators. Comviva anchors the emerging-market specialization archetype, sustaining price-accessible configurations for operators across Africa and South Asia.
| Leading Market Players |
|---|
| Syniverse Technologies |
| Infobip |
| Comviva |
| BICS |
| Cellusys |
| Route Mobile Limited |
| Tata Communications |
| SAP SE |
| Sinch |
| Others |
Supply & Pricing Matrix
Cloud-native deployment architectures are compressing both capital expenditure cycles and vendor margin structures as hyperscaler partnerships displace dedicated hardware procurement across carrier networks. This technology transition simultaneously fragments pricing power among legacy appliance vendors while concentrating supply leverage with AWS, Azure, and Google Cloud infrastructure layers.
Pricing Analysis
Bundled threat-detection APIs command premium positioning against unbundled spam-filtering licenses that face commoditization pressure from open-source alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GDPR-compliant explainable AI modules carrying surcharge premiums. Price erosion runs through basic traffic monitoring tiers as Indian and Brazilian operators drive volume negotiations. Mobile network providers exhibit lowest price sensitivity due to five-nines reliability requirements, while Southeast Asian neobanks negotiate aggressively for per-transaction API rates.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Telekom and Vodafone Germany mandate multi-supplier qualification for SS7 protocol stacks, preventing single-vendor lock-in across European deployments. Hardware component manufacturing concentrates in Taiwan, South Korea, and Germany, with specialized FPGA signaling processors drawing from TSMC foundry capacity. Machine learning training infrastructure rests on NVIDIA GPU supply chains vulnerable to export control restrictions. Distribution runs through direct carrier procurement channels in developed markets, while emerging-market operators rely on systems integrators for deployment and policy tuning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global SMS Firewall Market functions as a stable compounder anchored by regulatory mandate expansion across financial services authentication corridors. TRAI, EU AI Act, and FCC enforcement timelines create predictable procurement cycles that sustain vendor revenue visibility.
For Market Incumbents: Cement carrier relationships through embedded 5G SA core integration, preventing cloud-native challengers from disintermediating signaling security layers. Invest in explainable AI certification for EU deployments before GDPR penalty exposure hardens procurement criteria. Prioritize backward integration into behavioral biometrics engines to capture neobank API margins that currently leak to fintech specialists.
For New Entrants and Emerging Players: Enter via direct API channels with Brazilian Pix and Indian UPI payment processors, bypassing traditional operator procurement bottlenecks. Target managed services arrangements for mid-tier Southeast Asian carriers facing cybersecurity skills scarcity. Lead with cloud-native deployment velocity against legacy vendors burdened by hardware refresh obligations.
For Investors and Strategic Acquirers: Valuations sit cheapest among emerging-market configuration specialists with Africa and South Asia operator relationships. Long-term viability hinges on 5G convergence positioning and financial services channel penetration rather than core network replacement cycles. Watch SIM swap fraud incident rates as the inflection indicator for predictive compliance mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership Formation | AWS and Azure alliances enable Indian operators to bypass capital-intensive hardware procurement cycles. |
| Direct API Channel Development | Nubank and Revolut contracts disintermediate traditional telecom procurement for embedded fraud prevention. |
| Explainable AI Certification Investment | GDPR and EU AI Act compliance modules secure Deutsche Telekom and Vodafone Germany upgrade contracts. |
| Behavioral Biometrics Acquisition | Indonesian mobile banking deployments fuse signaling analysis with transaction pattern recognition. |
| 5G SA Core Integration | Unified signaling security across Diameter and HTTP/2 interfaces captures Vodafone Germany migration spend. |
Research Methodology
Coverage spans North America, Western Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with carrier security operations directors, fintech platform engineers, regulatory compliance officers, and hyperscaler partnership managers were triangulated against TRAI enforcement circulars, FCC consent framework updates, EU AI Act implementation guidance, and carrier capital expenditure disclosures. Bottom-up deployment volume estimates and top-down market sizing were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window segments growth by deployment model, solution architecture, end-user sophistication, and geographic regulatory cluster. CAGRs were derived from carrier procurement pipeline visibility, neobank API contract velocity, and 5G core migration timelines. Segmentation modeling incorporated cloud adoption curves, GDPR penalty incident rates, and UPI transaction volume trajectories as industry-specific forecast inputs.
Inputs from regulatory filings and carrier earnings calls were available through the study window; gaps in real-time fraud incident reporting introduce uncertainty bands around threat detection demand estimates. Forecasts reflect assumptions regarding TRAI mandate enforcement consistency and EU AI Act audit timeline adherence. Deviation in SIM swap fraud prevalence or predictive compliance standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Ultra-Secure Smartphone Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Security Testing Market
Security Software
Device Vulnerability Management Market
Security Software
Global Network Security Software Market
Security Software
Global Software-Defined Security Market
Security Software
Global Electronic Passports Market
Security Software
Cloud File Security Software Market
Security Software
Global Background Check Software Market
Security Software
Europe User Provisioning Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Global Mobile Identification Market
Security Software
Single Sign-On Market
Security Software
Secaas Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Video Intercom Devices Market