
 Malaysia Cybersecurity Market | 2026-2036
Malaysia Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Cybersecurity Market Foresight
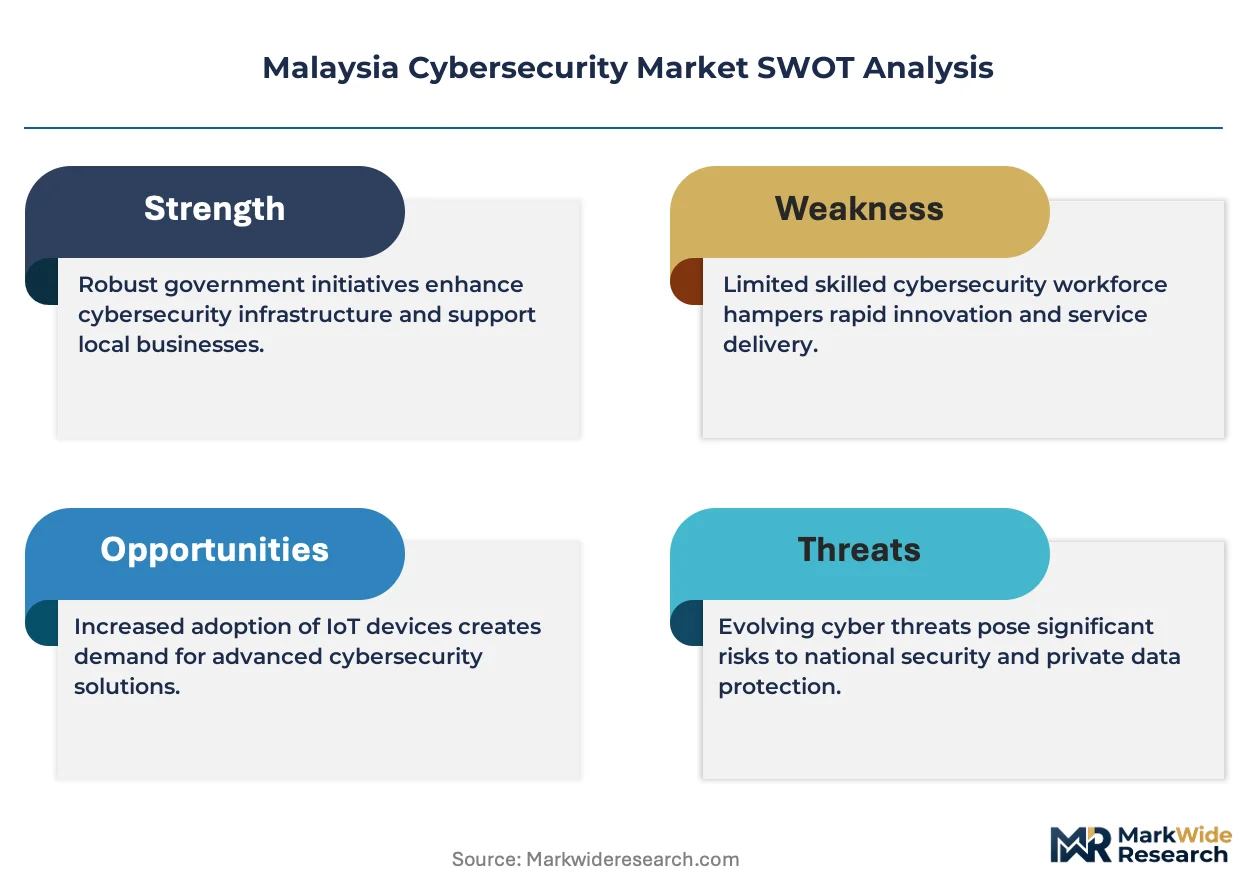
Cloud-native security architecture is broadening the attack surface that traditional perimeter defenses must cover. Cisco Systems Inc. leverages its integrated networking-security stack to dominate enterprise deployments across Malaysian banking infrastructure. LGMS Berhad anchors its position through specialized penetration testing services tailored to local regulatory requirements. Securemetric Bhd differentiates via its homegrown digital identity and public key infrastructure solutions serving government contracts.
Cybersecurity encompasses the technologies, processes, and practices designed to protect networks, devices, programs, and data from attack, damage, or unauthorized access through mechanisms such as encryption protocols, intrusion detection systems, and zero-trust architecture frameworks. Its primary purpose is ensuring confidentiality, integrity, and availability of digital assets across organizational boundaries. The deployment model dimension shows cloud-based and hybrid configurations capturing the fastest expansion as Malaysian enterprises abandon pure on-premises stacks, while managed services commands the deepest margin pools through recurring revenue structures. Within end-user verticals, BFSI and government sectors sustain the highest spending intensity due to regulatory compliance burdens and critical infrastructure protection mandates.
BIS standards alignment, the Personal Data Protection Act enforcement framework, and Bank Negara Malaysia's technology risk management guidelines collectively shape product certification requirements and procurement criteria for cybersecurity vendors. Compliance with these frameworks determines market access eligibility for both domestic suppliers and foreign entrants seeking public-sector contracts. Stakeholders must weigh localization investments against regional hub strategies as Malaysia positions itself as ASEAN's cybersecurity services nucleus.
Market Dynamics
Malaysia's cybersecurity market is being fundamentally restructured by the mandatory cloud migration timelines imposed on financial institutions under Bank Negara Malaysia's technology risk management guidelines, which force legacy infrastructure replacement at unprecedented velocity.
Growth Catalysts
- Digital Banking Licensing:Bank Negara Malaysia's digital bank framework is compelling new entrants to build security-first architectures from inception, creating immediate procurement pipelines for identity management and fraud detection systems.
- Personal Data Protection Act Enforcement:The Personal Data Protection Commission's escalating penalty structures are driving mid-market enterprises toward compliance automation platforms previously affordable only by large corporations.
- Klang Valley Enterprise Clustering:Concentrated cloud migration activity across Selangor and Kuala Lumpur is generating network effects where peer benchmarking accelerates security investment decisions among neighboring firms.
Market Restraints
- Specialized Talent Scarcity:Malaysia's domestic pipeline produces insufficient certified penetration testers and incident response specialists, forcing reliance on Singapore-based contractors at 40-60% cost premiums.
- Foreign Vendor Dominance:Core infrastructure segments remain captive to US and Israeli security appliance suppliers, creating currency exposure and technology transfer restrictions under export control frameworks.
- Legacy System Interoperability:Decades-old core banking platforms in major Malaysian financial institutions resist API-native security integration, prolonging hybrid environment vulnerabilities.
Strategic Opportunities
- Iskandar Malaysia Tech Corridor:Johor's emerging data center zone offers greenfield deployment opportunities for security operations centers serving Singapore overflow demand without city-state real estate costs.
- Operational Technology Convergence:Manufacturing security represents underpenetrated terrain as Malaysian industrial firms connect plant floor systems to enterprise networks, requiring ICS-specific expertise.
- MyDIGITAL Incentive Alignment:The national digital economy blueprint's tax incentives for cybersecurity R&D expenditure create structural advantages for vendors establishing local development centers.
Industry Challenges
- Certification Timeline Compression:Common Criteria and FIPS 140-2 validation cycles for government procurement eligibility often exceed 18 months, misaligning with product development velocities.
- Multi-Cloud Architecture Complexity:Malaysian enterprises averaging 2.7 cloud providers face inconsistent security policy enforcement across AWS, Azure, and domestic cloud environments.
- Incident Response Retainer Economics:Smaller enterprises resist prepaid security retainers despite regulatory nudges, leaving vendors exposed to revenue volatility from event-driven engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Cybersecurity Market |
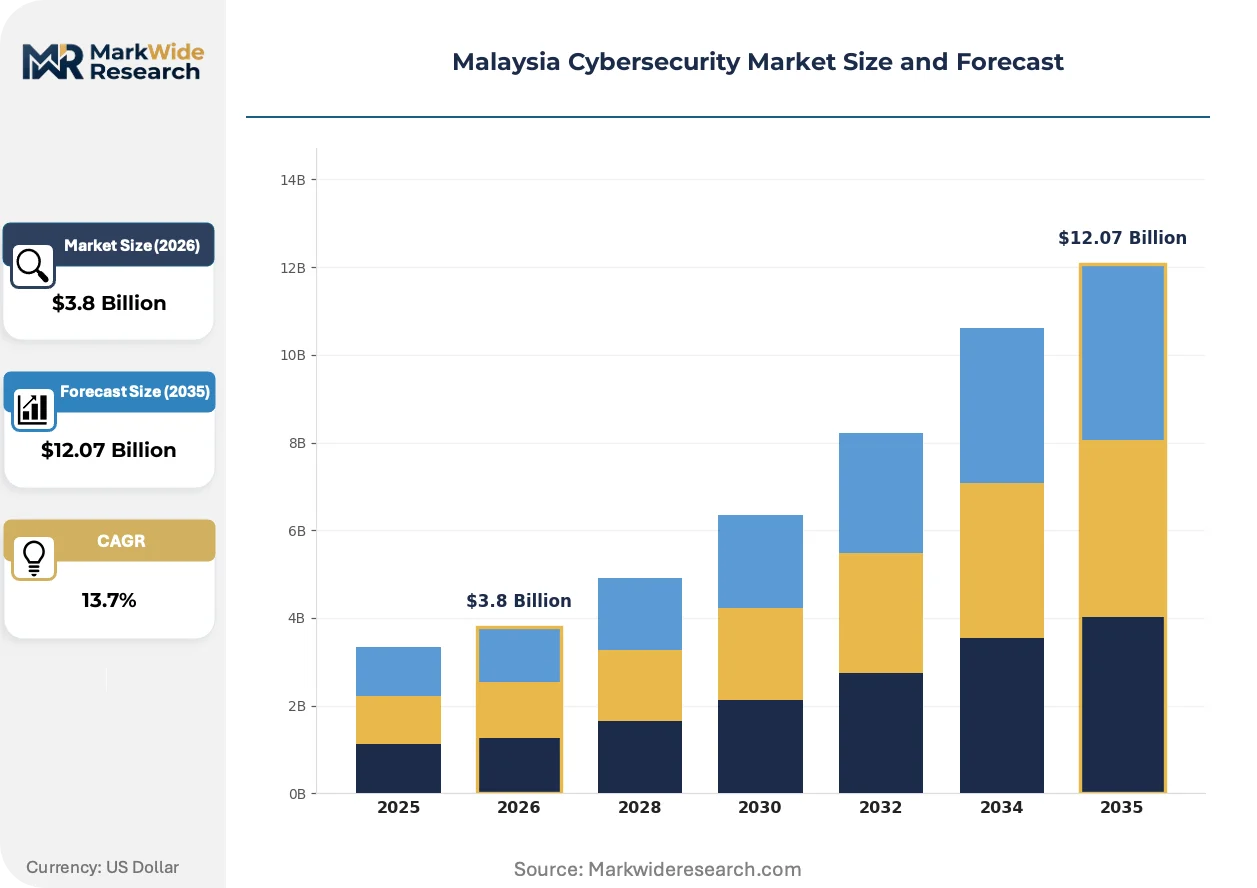
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Antivirus, Intrusion Detection, Encryption Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government, BFSI, Healthcare, Manufacturing Service Type: Consulting, Training, Incident Response, Risk Management |
| Companies Covered | Akati Sekurity, Cisco Systems Inc., LGMS Berhad, Fortinet Inc., Palo Alto Networks, Securemetric Bhd, IBM Corporation, Microsoft Corp., Wizlynx Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Cybersecurity Market Shifts & Advancements
Security architecture in Malaysia is pivoting from perimeter defense toward continuous verification models, with three interconnected developments reshaping vendor positioning and buyer procurement criteria.
Zero-trust network access is converging with software-defined perimeter technology to eliminate implicit trust based on network location. Malaysian banks undergoing digital transformation are deploying these architectures for contractor and third-party access scenarios. The convergence is compressing sales cycles for standalone VPN vendors while elevating platforms offering integrated identity verification and micro-segmentation capabilities.
Bank Negara Malaysia's Technology Risk Management Guidelines are mandating board-level cybersecurity accountability through prescribed risk appetite statements and independent audit requirements. This regulatory architecture is elevating chief information security officers to direct reporting lines and expanding demand for governance, risk, and compliance automation tools. Financial institutions are responding by consolidating vendor relationships around platforms offering integrated audit trails and regulatory reporting modules.
Managed detection and response services are displacing in-house security operations center builds among Malaysian mid-market enterprises. The substitution reflects both cost pressures and the recognition that 24/7 threat monitoring exceeds internal capability development timelines. This pattern is most pronounced in Penang and Johor manufacturing hubs where IT security headcounts remain constrained despite expanding attack surfaces from operational technology integration.
Malaysia Cybersecurity Market Segmentation
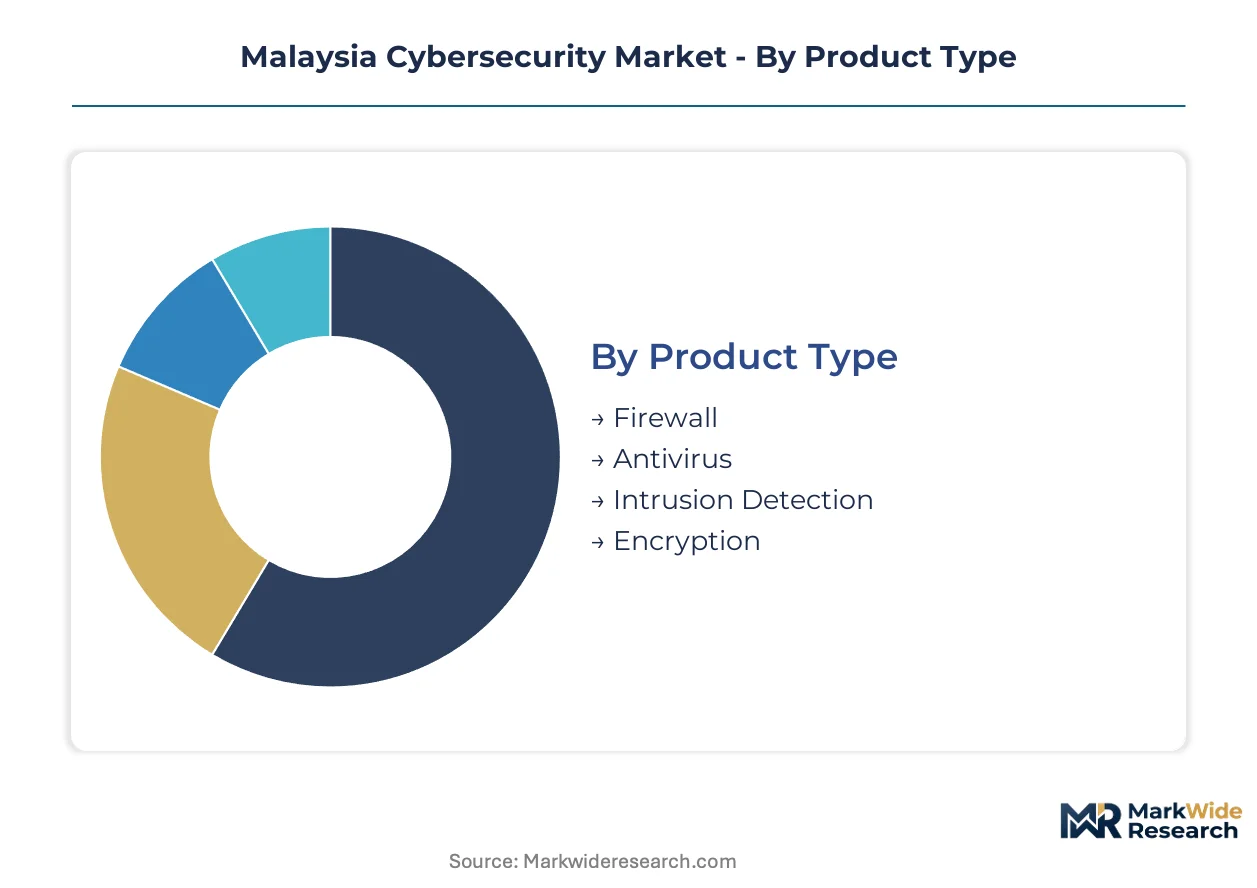
Malaysian cybersecurity procurement patterns diverge sharply between compliance-driven baseline spending and architecture-transforming investments. Understanding these segment boundaries clarifies where vendor margins concentrate versus where volume transactions dominate.
Product Type:
Firewall and encryption solutions command premium pricing through mandatory certification requirements, while antivirus and intrusion detection compete on volume efficiency.
- Firewall:Next-generation platforms integrate application-layer inspection with SD-WAN capabilities. Klang Valley financial institutions drive demand for hardware appliances meeting Bank Negara Malaysia's prescribed security zones architecture.
- Encryption:End-to-end data protection spans data-at-rest, data-in-transit, and emerging data-in-use paradigms. Government contracts under MyDIGITAL mandate FIPS 140-2 validated modules, creating procurement bottlenecks for uncertified suppliers.
- Antivirus:Endpoint protection platforms face commoditization pressure as Microsoft Defender displaces standalone solutions in mid-market enterprise renewals.
- Intrusion Detection:Network-based and host-based variants converge into extended detection and response platforms, compressing standalone sensor deployments.
Today's leader: Firewall. Tomorrow's challenger: Encryption.
Deployment Model:
Cost tier stratification separates capital-intensive infrastructure builds from operational expenditure flexibility, with hybrid architectures capturing transitional enterprise budgets.
- Cloud-Based:Native security controls and third-party cloud workload protection platforms scale with multi-tenant efficiency. Malaysian enterprises averaging multiple cloud providers drive demand for consistent policy enforcement across AWS, Azure, and domestic environments.
- Managed Services:Security operations center-as-a-service and managed detection and response offerings convert capital expenditure to predictable operational spending. Mid-market manufacturers in Penang and Johor adopt these services to bypass talent scarcity constraints.
- Hybrid:Split architectures preserve sensitive data on-premises while extending elastic compute to public cloud, complicating unified threat visibility.
- On-Premises:Legacy appliance deployments persist in classified government networks and core banking infrastructure resisting cloud migration timelines.
Deployment momentum concentrates in cloud-native and managed service configurations, with hybrid installations representing transitional rather than terminal architecture states.
End User:
Application criticality determines spending intensity, with regulated sectors facing penalty structures that internalize security investment returns.
- BFSI:Digital banking licensing and technology risk management guidelines impose security-first architecture mandates. New entrants build identity management and fraud detection from inception, while incumbents retrofit legacy platforms.
- Government:National security classifications and critical infrastructure protection frameworks drive procurement through centralized tender processes. Common Criteria certification requirements filter vendor eligibility.
- Healthcare:Personal Data Protection Act enforcement accelerates compliance automation adoption as patient data breaches attract regulatory scrutiny.
- Manufacturing:Operational technology convergence creates underpenetrated demand as plant floor systems connect to enterprise networks, requiring industrial control system-specific expertise.
Regulatory burden intensity ranks BFSI and government as priority segments, with manufacturing security representing the steepest expansion trajectory as industrial digitization accelerates.
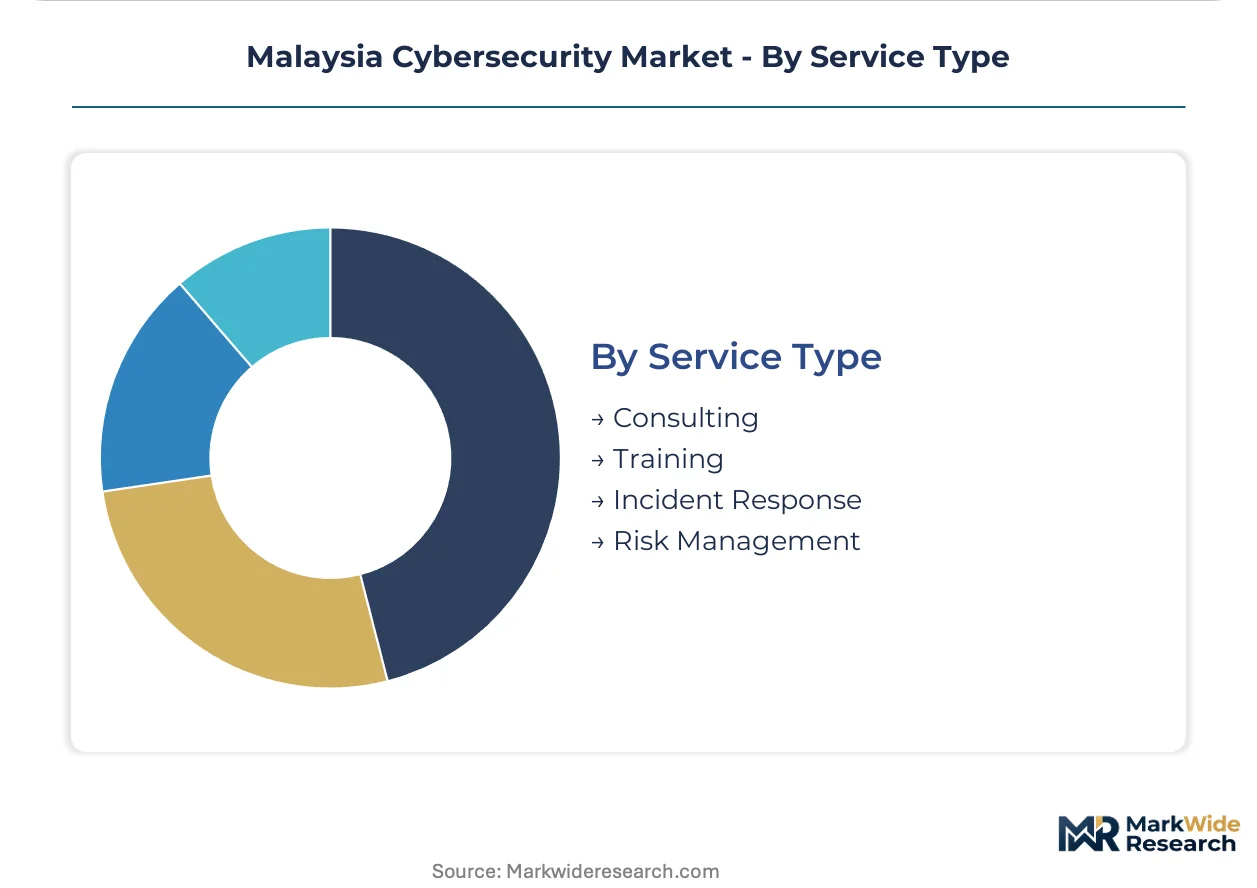
Service Type:
Margin pools deepen with recurring engagement structures, separating transactional project work from retainer-based relationships.
- Incident Response:Retainer models and event-driven engagements address breach containment and forensic investigation. Smaller enterprises resist prepaid structures despite regulatory nudges, leaving vendors exposed to revenue volatility.
- Risk Management:Continuous compliance monitoring and governance automation platforms align with Bank Negara Malaysia's board-level accountability mandates. Financial institutions consolidate vendor relationships around integrated audit trail capabilities.
- Consulting:Architecture design and security transformation advisory services accompany major infrastructure replacement cycles.
- Training:Certification programs and simulated phishing exercises address the domestic talent pipeline gap, though Singapore-based contractors retain premium positioning for specialized penetration testing.
Service value migrates toward risk management automation and incident response retainers, with training commoditizing through self-paced digital delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Klang Valley anchors Malaysian cybersecurity demand through concentrated enterprise digitization and cloud migration activity across Selangor and Kuala Lumpur.
Selangor
Petaling Jaya and Cyberjaya host the densest cluster of financial services headquarters and technology parks. Bank Negara Malaysia's technology risk management guidelines mandate security-first architecture for digital banking entrants. Cyberjaya's status as a multimedia super corridor attracts security operations centers serving regional overflow demand.
Kuala Lumpur
The capital's central business district concentrates headquarters procurement decisions for banking and telecommunications sectors. The Personal Data Protection Commission escalates enforcement against mid-market enterprises headquartered here. KL Sentral and Tun Razak Exchange sub-districts drive premium demand for zero-trust network access deployments.
Penang
George Town's manufacturing belt generates underpenetrated operational technology security demand as industrial firms connect plant floor systems. The state's electronics and semiconductor fabrication clusters require industrial control system-specific expertise. Bayan Lepas industrial zone anchors manufacturing security procurement decisions.
Johor
Iskandar Malaysia's emerging data center zone offers greenfield security operations center deployment opportunities. The tech corridor serves Singapore overflow demand without city-state real estate premiums. Pasir Gudang industrial area drives manufacturing security adoption as operational technology converges with enterprise networks.
Malaysia Cybersecurity Market Competitive Landscape
Strategic partnerships dominate the current landscape as foreign appliance vendors align with domestic service providers to satisfy localization requirements. The market structures around three tiers: global infrastructure suppliers capturing core banking and government contracts, regional specialists penetrating mid-market compliance automation, and domestic pure-plays anchoring penetration testing and digital identity segments. Consolidation pressure intensifies as managed detection and response services convert capital expenditure to recurring operational spending. Technology licensing agreements proliferate as Malaysian vendors seek certified modules for government procurement eligibility.
Within the domestic specialist tier, LGMS Berhad and Securemetric Bhd exemplify archetypes built on regulatory proximity and homegrown certification. Cisco Systems Inc. anchors the integrated platform segment through networking-security stack convergence. These three occupy distinct competitive positions: domestic pure-plays leverage Personal Data Protection Act enforcement timelines, while infrastructure incumbents exploit technology risk management guideline mandates for hardware appliance refreshes.
| Leading Market Players |
|---|
| Akati Sekurity |
| Cisco Systems Inc. |
| LGMS Berhad |
| Fortinet Inc. |
| Palo Alto Networks |
| Securemetric Bhd |
| IBM Corporation |
| Microsoft Corp. |
| Wizlynx Group |
| Others |
Supply & Pricing Matrix
Bank Negara Malaysia's technology risk management guidelines gate qualified supply access and premium-tier pricing eligibility for cybersecurity vendors serving financial institutions. Compliance with these mandates determines procurement eligibility, compressing margins for uncertified suppliers while elevating certified providers to premium positioning.
Pricing Analysis
Input-cost pass-through from specialized talent scarcity shapes vendor pricing structures across Malaysian cybersecurity markets. Subscription-based managed detection and response services command premium positioning against project-based penetration testing, with price differentiation anchored in Common Criteria certification status and 24/7 operational coverage. Pricing pressure stems from Microsoft Defender's displacement of standalone endpoint protection in mid-market renewals. Small enterprises exhibit acute price sensitivity toward prepaid incident response retainers, while BFSI incumbents absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Freight and logistics costs for hardware security appliances draw from concentrated manufacturing bases in the United States, Israel, and Taiwan. Semiconductor components for next-generation firewalls and encryption modules hinge on Taiwan and South Korea fabrication capacity. Single-source vulnerability in FIPS 140-2 validated chip supply creates procurement bottlenecks for government contract eligibility. Distribution runs through authorized channel partners with localization capabilities, bypassing direct vendor engagement for mid-market enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian cybersecurity markets offer margin expansion through compliance automation premiumization and managed service recurring revenue conversion. Cost compression in commoditized endpoint protection is accelerating vendor consolidation toward integrated platform strategies.
For Market Incumbents: Lock in multi-year managed detection and response retainers with BFSI clients before digital banking entrants saturate procurement pipelines. Deepen backward integration into local security operations center infrastructure to offset Singapore-based contractor cost premiums. Cisco Systems Inc. and Fortinet Inc. face substitution pressure from cloud-native workload protection platforms; defend through API-native integration with legacy core banking stacks.
For New Entrants and Emerging Players: Systems integrators with Bank Negara Malaysia compliance credentials represent the most viable channel partnership archetype for rapid market access. Manufacturing security in Penang and Johor offers underpenetrated white-space with minimal incumbent saturation. Target operational technology convergence scenarios with industrial control system-specific expertise, leveraging MyDIGITAL R&D tax incentives for local development center establishment.
For Investors and Strategic Acquirers: Roll-up economics work for managed security service providers because mid-market enterprises are abandoning in-house security operations center builds across the analysis window. Platform consolidation around governance, risk, and compliance automation offers five-to-ten-year viability as regulatory enforcement intensifies. Monitor Bank Negara Malaysia digital banking license issuance velocity as inflection indicator for identity management and fraud detection procurement surge.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Detection and Response Platform Launch | Converts capital expenditure to recurring revenue for mid-market manufacturers in Penang and Johor. |
| Common Criteria Certification Investment | Unlocks government procurement eligibility under MyDIGITAL centralized tender processes. |
| Operational Technology Security Partnership | Captures manufacturing demand as plant floor systems converge with enterprise networks. |
| Iskandar Malaysia Security Operations Center | Serves Singapore overflow demand without city-state real estate cost premiums. |
| Digital Identity Platform Integration | Aligns with digital banking licensing mandates for security-first architecture builds. |
Research Methodology
Bottom-up BFSI and government sector modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with chief information security officers, Bank Negara Malaysia compliance officers, government procurement directors, and managed security service provider executives combined with secondary validation from SEC filings, Personal Data Protection Commission enforcement records, and Bank Negara Malaysia technology risk management guideline amendments. Triangulation across these sources calibrated market sizing and growth trajectory assumptions.
Historical trendline analysis of cybersecurity spending intensity by regulated vertical informed projection framework construction across deployment model, end-user industry, and service type dimensions. CAGRs were derived from regression analysis of procurement pipeline visibility and regulatory mandate implementation timelines. Cloud migration velocity and digital banking licensing cadence served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Bank Negara Malaysia regulatory amendment timing and foreign vendor export control restriction escalation. Forecasts reflect assumptions about compliance automation adoption curves and talent pipeline development rates. A model refresh is warranted upon material change in Personal Data Protection Act penalty structure enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Data Exfiltration Techniques Market
Cybersecurity
South Africa Cybersecurity Market
Cybersecurity
Mainframe Security Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Cyber Security and Big Data Analytics Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Cloud Workload Protection Market
Cybersecurity
Cloud Firewalls Market
Cybersecurity
Asia Pacific Digital Forensics Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
North America Data Exfiltration Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Global Online Fraud Detection and Prevention Market
Cybersecurity
Asia Pacific Cybersecurity Market