
 Private Branch Exchange Market | 2026-2036
Private Branch Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Private Branch Exchange Market Analysis
Software-defined networking is broadening the architectural flexibility of modern PBX systems, reducing dependency on proprietary hardware. Cisco Systems leverages its enterprise routing heritage to dominate on-premise installations. Avaya anchors its position through specialized contact-center integrations. RingCentral competes with cloud-native platforms that extend geographic reach without physical infrastructure.
A private branch exchange is a private telephone network used within an organization that switches calls between enterprise users on local lines while allowing all users to share a certain number of external phone lines, typically supporting SIP trunking protocols and IP telephony standards. Cloud-based deployment is capturing the fastest growth as enterprises abandon capital-intensive hardware refresh cycles. Unified communications as a service type is maturing into the primary margin pool, bundling voice, video, and messaging into subscription revenue. Managed services for SMEs remain fragmented, with providers navigating price pressure through vertical specialization.
FCC regulations govern interconnection and number portability in the United States, while GDPR in Europe shapes how call recordings and customer data are stored and processed. ETSI standards and CE marking requirements influence product certification for equipment deployed across EU member states. Stakeholders must monitor how AI-powered call analytics intersects with evolving data sovereignty rules before committing to multi-tenant cloud architectures.
Market Dynamics
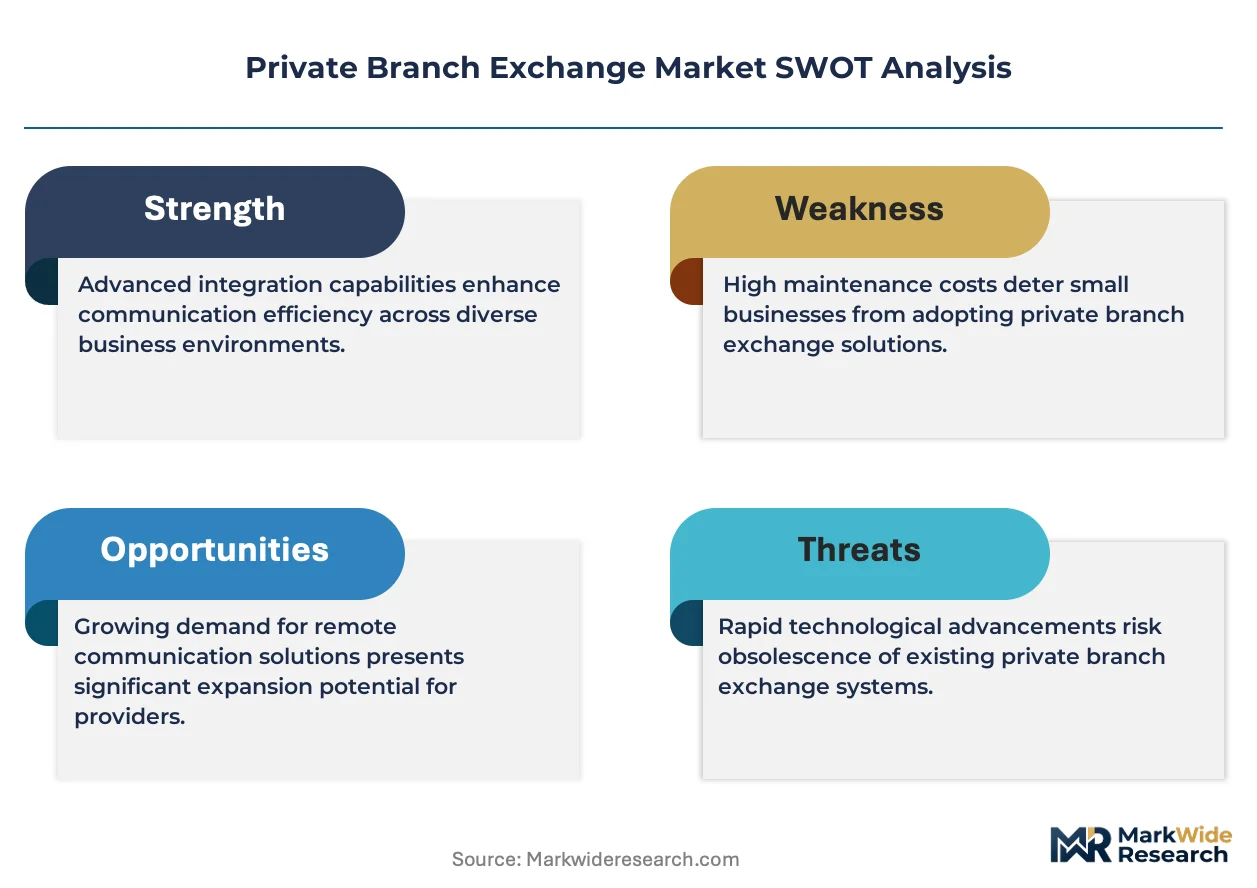
Cloud-native architectures are compressing hardware refresh cycles across enterprise telephony, forcing incumbent vendors to pivot subscription revenue models while SIP trunking protocols displace legacy TDM infrastructure.
Growth Catalysts
- GDPR compliance frameworks:European data residency requirements are accelerating managed service adoption as enterprises seek compliant call recording and storage architectures without building in-house data centers.
- Healthcare digitization:Hospital systems in the United States are consolidating voice, video, and patient communication platforms under unified communications budgets, expanding addressable spend per installation.
- API-first platforms:Integration demands from CRM and ERP ecosystems are pulling cloud PBX deployments into broader enterprise software procurement cycles.
Market Restraints
- Copper network decommissioning:Incumbent carriers in Germany and Japan are sunsetting PSTN infrastructure faster than some enterprises can migrate, creating forced-upgrade cost shocks for budget-constrained IT departments.
- Semiconductor supply concentration:Specialized voice processing chips for on-premise PBX hardware face single-source dependencies from Taiwanese foundries, exposing refresh timelines to geopolitical friction.
- Interoperability limitations:Proprietary signaling protocols from legacy vendors continue fragmenting multi-vendor deployments, raising total cost of ownership for heterogeneous environments.
Strategic Opportunities
- India SME segment:Underpenetrated mid-market enterprises in tier-2 cities represent white space as TRAI's net neutrality rules stabilize cloud voice pricing predictability.
- AI-powered analytics convergence:Real-time transcription and sentiment analysis integration with PBX platforms is opening new SaaS attach rates beyond core telephony.
- Remote work permanence:Distributed workforce models in Japan are sustaining demand for softphone-first architectures that bypass physical handset procurement entirely.
Industry Challenges
- SIP security expertise gaps:Enterprise IT teams lack depth in session border controller configuration and toll fraud prevention, exposing voice networks to credential-based attacks.
- CE marking timeline compression:ETSI certification cycles for new IP telephony equipment are extending as test labs face backlog, delaying product launches for EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Branch Exchange Market |
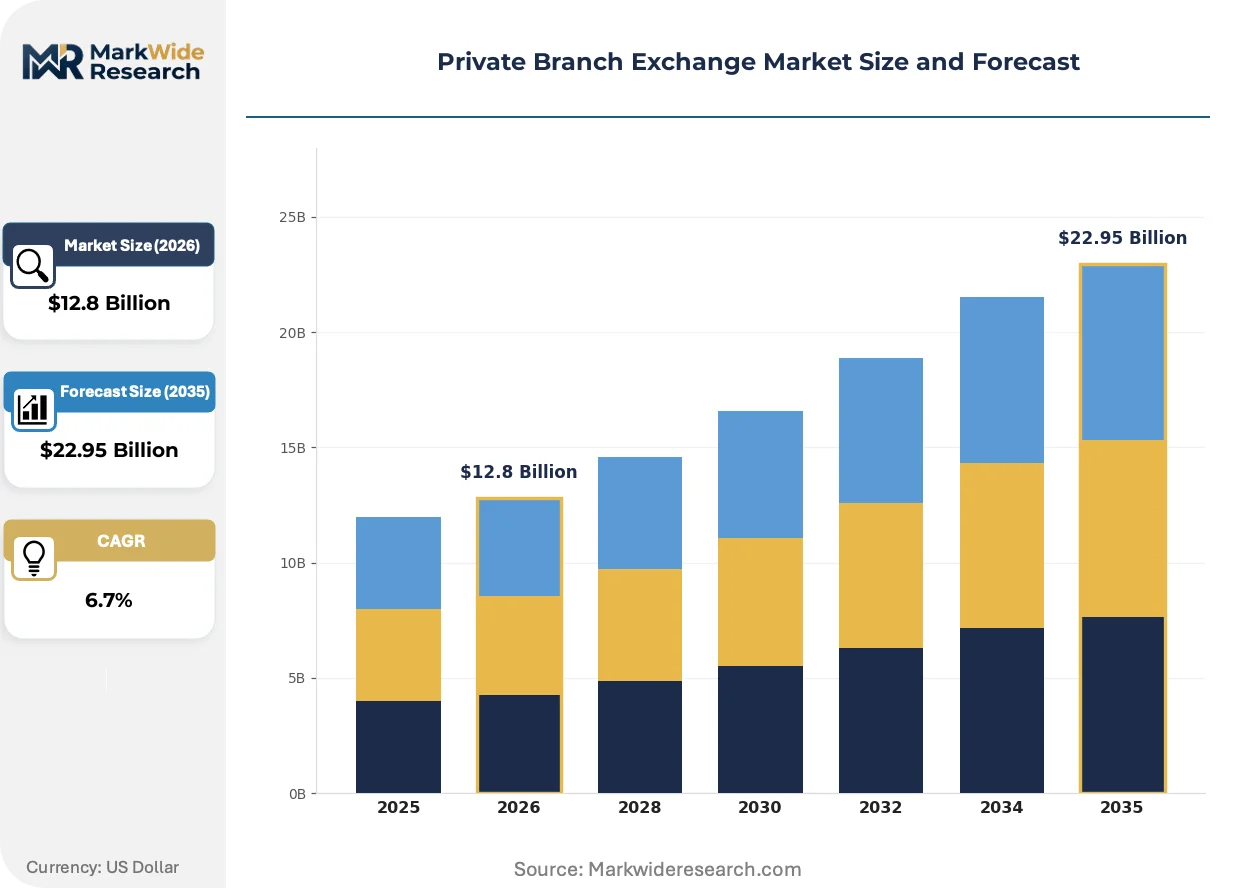
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service Type: VoIP, Traditional Telephony, Unified Communications, Contact Center Solutions End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: IP Telephony, Digital Telephony, VoLTE, SIP Trunking |
| Companies Covered | Cisco Systems, Avaya, Mitel Networks Corporation, RingCentral, Microsoft Corporation, 8x8, Vonage, NEC Corporation, Zoom Video Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Branch Exchange Market Emerging Trajectories
Microservices-based voice architectures are fragmenting monolithic PBX platforms into composable communication stacks, enabling buyers to purchase routing, analytics, and collaboration functions as discrete services rather than bundled suites.
WebRTC protocols are decentralizing real-time communications infrastructure by embedding browser-based voice and video directly into business applications without dedicated client software. Healthcare providers in Germany are deploying WebRTC-enabled patient portals to bypass traditional telephony hardware procurement. This shift is compressing vendor lock-in periods and accelerating replacement cycles for premises-based systems.
FCC net neutrality rollbacks in the United States are permitting traffic prioritization agreements between carriers and cloud PBX providers, altering competitive dynamics for voice quality guarantees. Enterprise buyers are renegotiating SLA terms to reflect differential treatment of real-time traffic. Healthcare and financial services verticals are most affected, with compliance-sensitive organizations demanding written assurances on jitter and latency thresholds.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority across CIO, CMO, and facilities management functions, complicating vendor sales cycles. Unified communications procurement in Japan increasingly routes through departmental budgets rather than centralized IT. This diffusion is favoring vendors with self-service provisioning and usage-based pricing over those requiring enterprise-wide contractual commitments.
Private Branch Exchange Market Segmentation
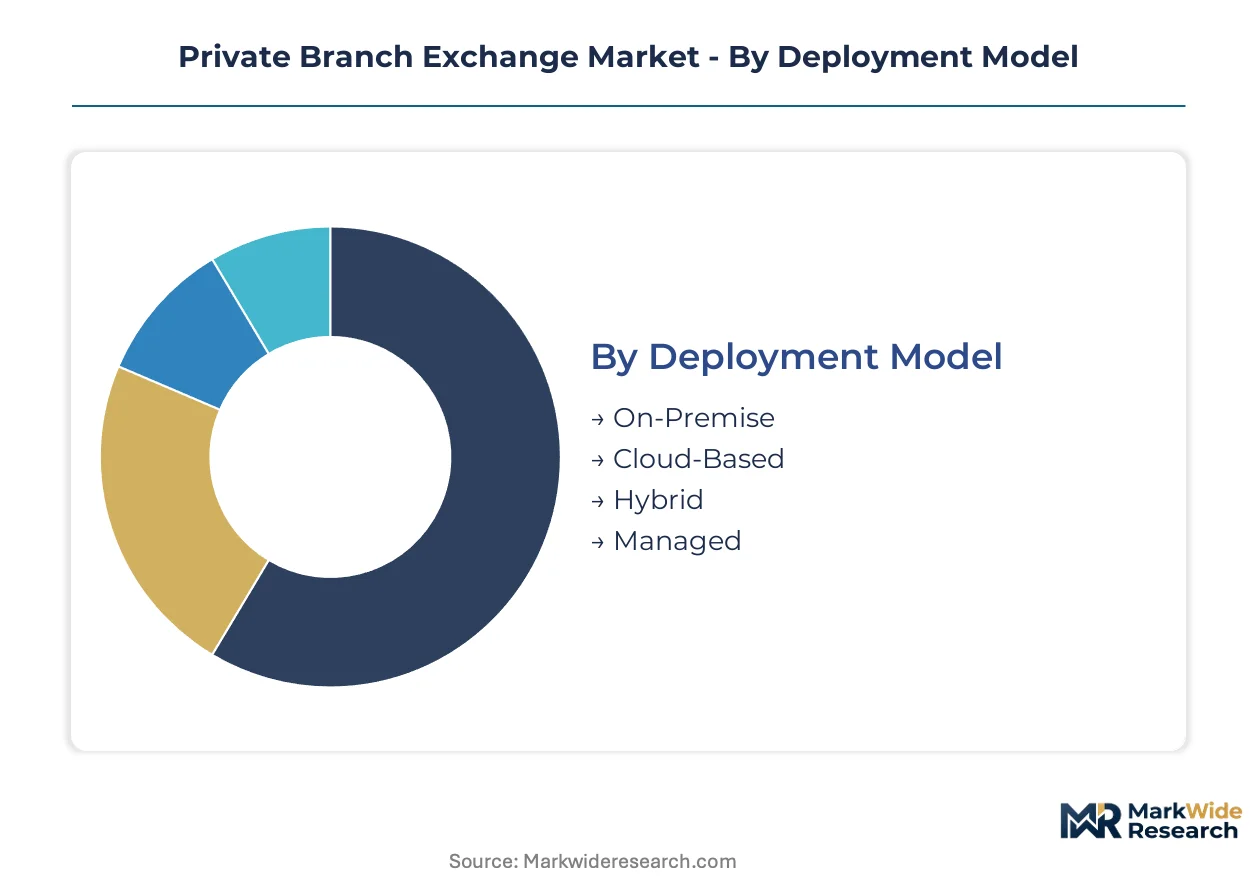
PBX procurement decisions pivot on capital efficiency versus control trade-offs, with deployment architecture determining total cost of ownership and regulatory compliance posture. Service bundling intensity and end-user scale further fragment vendor targeting strategies across healthcare, financial services, and public sector verticals.
Deployment Model:
Capital commitment thresholds and data sovereignty requirements dominate buyer selection between ownership models.
- On-Premise:Hardware-resident systems with dedicated PBX appliances and localized switching infrastructure. Financial institutions in Germany favor this architecture for GDPR-compliant call recording retention under sovereign data mandates.
- Cloud-Based:Multi-tenant platforms delivered via subscription without physical infrastructure. Healthcare providers in the United States are migrating here to consolidate voice, video, and patient portals under unified communications budgets.
- Hybrid:Split architectures preserving on-premise core systems while extending to cloud extensions for remote workers. Offers staged migration paths for enterprises with sunk costs in legacy TDM investments.
- Managed:Outsourced operations where third parties assume maintenance, patching, and capacity scaling. Appeals to SMEs lacking in-house SIP security expertise for session border controller management.
On-Premise leads on scale; Cloud-Based leads on momentum.
Service Type:
Integration depth with adjacent enterprise software stacks determines pricing power and renewal rates.
- VoIP:Packet-switched voice transport over IP networks replacing circuit-switched PSTN. Manufacturing facilities in Japan deploy this for inter-site trunking cost reduction.
- Traditional Telephony:TDM-based systems using ISDN or analog line interfaces. Declining base concentrated in government buildings with extended depreciation schedules.
- Unified Communications:Converged platforms bundling voice, video, messaging, and presence into single subscriptions. API-first architectures here are pulling PBX procurement into broader CRM and ERP purchasing cycles.
- Contact Center Solutions:Specialized routing, IVR, and workforce optimization for customer-facing operations. Avaya anchors competitive position through deep integration with agent desktop environments.
Unified Communications commands margin concentration; Contact Center Solutions exhibits steepest expansion trajectory.
End User:
Procurement authority diffusion and compliance sensitivity shape vendor sales cycle complexity.
- SMEs:Mid-market enterprises with 50-500 employees and limited IT staff. Tier-2 cities in India represent underpenetrated white space as TRAI's net neutrality rules stabilize cloud voice pricing.
- Large Enterprises:Multi-site organizations with centralized procurement and dedicated telecommunications teams. Subscription fatigue here is fragmenting purchasing authority across CIO, CMO, and facilities functions.
- Government:Public sector agencies with stringent security certification and domestic content requirements. FCC regulations govern interconnection and number portability for federal installations in the United States.
- Educational Institutions:Universities and K-12 districts with seasonal usage patterns and grant-dependent budgets. Softphone-first architectures bypass physical handset procurement for distributed faculty.
Large Enterprises lead on scale; SMEs lead on momentum.
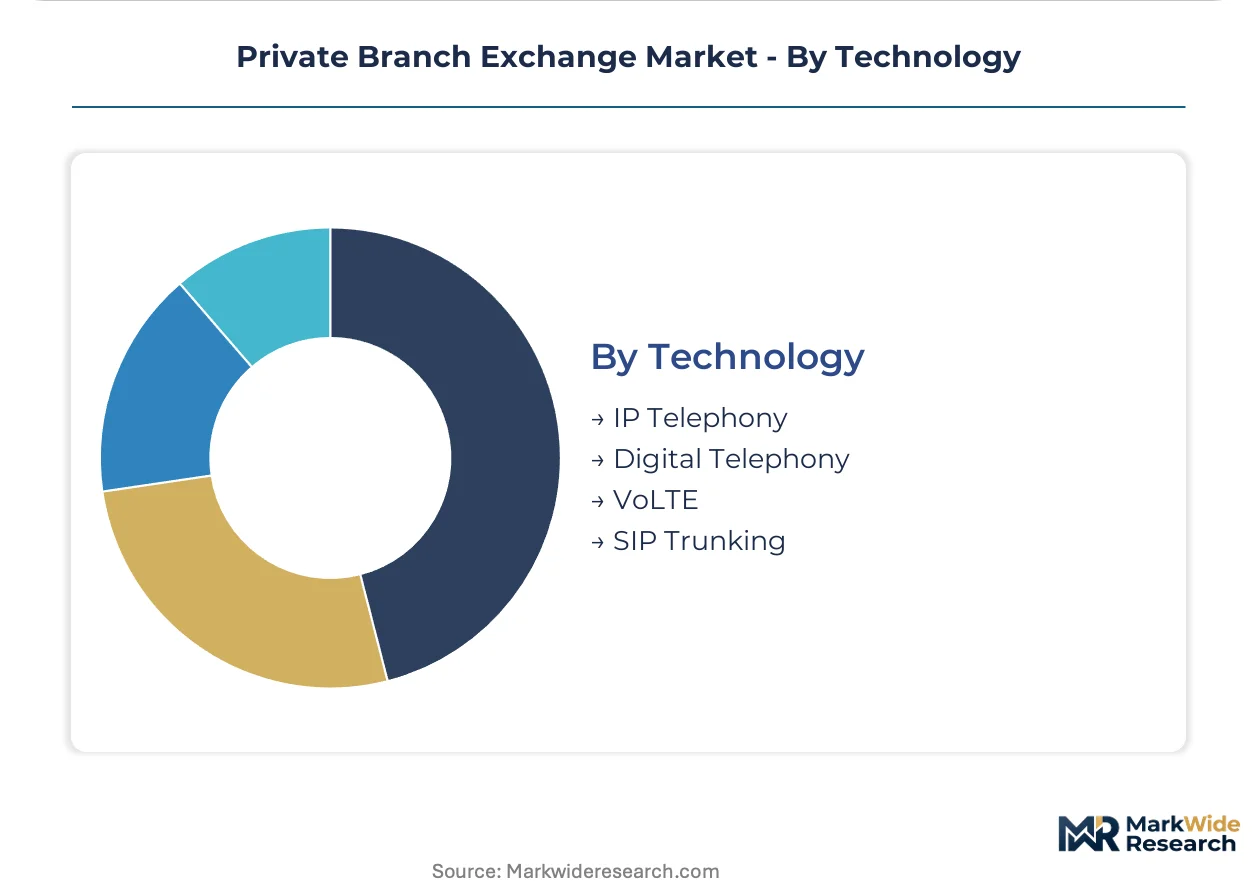
Technology:
Protocol standardization and hardware dependency define upgrade pathway flexibility.
- IP Telephony:Standards-based voice over Internet Protocol with H.323 or SIP signaling. WebRTC protocols are embedding browser-based communications directly into business applications without client software.
- Digital Telephony:ISDN and proprietary digital interfaces from legacy PBX vendors. Copper network decommissioning by incumbent carriers in Germany and Japan is forcing accelerated migration timelines.
- VoLTE:Voice over LTE mobile integration extending PBX reach to cellular endpoints. Healthcare providers deploy this for physician mobility without separate mobile device management.
- SIP Trunking:Session Initiation Protocol connectivity replacing PRI and analog trunk lines. Enterprise IT teams face expertise gaps in session border controller configuration and toll fraud prevention.
IP Telephony leads on scale; SIP Trunking leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise telephony infrastructure concentrates in the United States, Germany, Japan, India, and the United Kingdom, where regulatory frameworks and industrial digitization pace shape deployment preferences across on-premise, cloud, and hybrid architectures.
United States
Healthcare systems in the United States are consolidating voice, video, and patient communication platforms under unified communications budgets. FCC regulations govern interconnection and number portability requirements for federal and enterprise installations. Hospital networks in the Boston-Cambridge corridor are migrating to cloud-native PBX platforms to reduce capital-intensive hardware refresh cycles.
Germany
Financial institutions in Germany favor on-premise architectures for GDPR-compliant call recording retention under sovereign data mandates. ETSI standards and CE marking requirements influence product certification timelines for equipment deployed across EU member states. Industrial manufacturers in Bavaria are navigating copper network decommissioning by incumbent carriers that is forcing accelerated migration from legacy TDM infrastructure.
Japan
Distributed workforce models in Japan are sustaining demand for softphone-first architectures that bypass physical handset procurement entirely. METI guidelines shape domestic content requirements and security certification standards for public sector deployments. Enterprise clusters in the Kanto region around Tokyo are adopting WebRTC-enabled collaboration platforms to embed browser-based communications directly into business applications.
India
Underpenetrated mid-market enterprises in tier-2 cities represent white space as TRAI's net neutrality rules stabilize cloud voice pricing predictability. BIS certification requirements and data localization norms influence vendor selection for government and banking sector installations. Technology service providers in Bangalore and Hyderabad are driving API-first platform adoption that pulls PBX deployments into broader CRM and ERP procurement cycles.
United Kingdom
Educational institutions in the United Kingdom are deploying softphone-first architectures to bypass physical handset procurement for distributed faculty and seasonal usage patterns. GDPR shapes how call recordings and customer data are stored and processed across multi-tenant cloud architectures. Universities in the London-Oxford-Cambridge triangle are consolidating legacy telephony systems under managed service arrangements to address SIP security expertise gaps.
Private Branch Exchange Market Vendor Landscape
Global majors compete with regional champions across deployment architecture preferences, with cloud-native specialists challenging incumbent hardware vendors for enterprise accounts while legacy equipment providers defend installed bases through managed service transitions. Market structure tilts toward consolidation at the premium tier, with fragmentation persisting among mid-market SaaS providers and vertical specialists. Three archetypes dominate: infrastructure-hardware incumbents with enterprise routing heritage, cloud-native platforms with geographic reach without physical infrastructure, and contact-center specialists with deep agent desktop integration. Competitive intensity centers on M&A activity to acquire API-first capabilities and strategic partnerships to embed voice services into adjacent enterprise software stacks.
Within the infrastructure-hardware tier, Cisco Systems and NEC Corporation anchor positions through enterprise routing heritage and localized switching infrastructure respectively. Among cloud-native platforms, RingCentral exemplifies the geographic expansion archetype through multi-tenant subscription delivery. Avaya occupies a specialized position at the intersection of contact-center routing and workforce optimization. These three represent the dominant competitive vectors: on-premise scale, cloud-native reach, and vertical integration into customer-facing operations.
| Leading Market Players |
|---|
| Cisco Systems |
| Avaya |
| Mitel Networks Corporation |
| RingCentral |
| Microsoft Corporation |
| 8x8 |
| Vonage |
| NEC Corporation |
| Zoom Video Communications |
| Others |
Supply Flow & Price Mechanics
Subscription-versus-ownership bifurcation separates cloud-native SaaS tiers from on-premise hardware bundles, with this divergence manifesting in recurring revenue models for managed services and capital-intensive procurement cycles for sovereign-data-compliant installations. Input cost pass-through from Taiwanese semiconductor foundries and German copper network decommissioning timelines compress margins differently across each tier, while buyer archetypes in healthcare and financial services negotiate divergent SLA terms based on jitter guarantees and GDPR retention mandates.
Pricing Analysis
Input cost pass-through from specialized voice processing chips and session border controller hardware compresses margins for on-premise deployments, while cloud-native platforms absorb infrastructure scaling through multi-tenant economics. Three-tier pricing structure across premium, standard, and economy levels reflects API integration depth, GDPR certification grade, and geographic redundancy guarantees. Pricing pressure stems from subscription fatigue fragmenting purchasing authority across departmental budgets in Japanese enterprises. SMEs in Indian tier-2 cities exhibit highest price sensitivity; large German financial institutions demonstrate lowest sensitivity due to sovereign data mandates.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and Germany shape manufacturing capacity for specialized telephony semiconductors and precision switching hardware. Component dependencies center on voice processing ASICs from TSMC-affiliated foundries, SIP trunking gateway chipsets, and ETSI-certified encryption modules. Single-source vulnerability in Taiwanese semiconductor fabrication exposes refresh timelines to geopolitical friction. Distribution runs through carrier-direct channels for enterprise accounts, value-added resellers for mid-market segments, and managed service providers for SME outsourcing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, where FCC net neutrality rollbacks and GDPR data residency mandates accelerate managed service adoption and cloud migration timelines. Compliance-sensitive healthcare and financial verticals drive premium pricing for certified architectures.
For Market Incumbents: Lock in enterprise installed bases through managed service transitions that preserve recurring revenue from legacy TDM migrations, while deepening API-first platform integration to defend against cloud-native challengers. Invest in CE marking pre-certification to compress ETSI test lab backlog delays. Threat of WebRTC-enabled browser communications bypassing traditional telephony hardware demands vertical specialization in contact-center workforce optimization. For New Entrants and Emerging Players: Channel partners specializing in CRM and ERP ecosystem integration represent the most viable entry vector for bypassing entrenched carrier relationships. Target underpenetrated SME segments in Indian tier-2 cities where TRAI net neutrality rules stabilize cloud voice pricing predictability. White-space opportunity sits with AI-powered analytics attach rates beyond core telephony, particularly in healthcare patient communication platforms. Self-service provisioning with usage-based pricing outperforms enterprise-wide contractual commitments in diffused purchasing environments. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms possessing geographic reach without physical infrastructure, particularly those embedding WebRTC protocols into vertical SaaS applications. Long-term viability hinges on API-first architecture durability and multi-tenant margin expansion across the analysis window. Acquisition target archetype: mid-market UCaaS providers with healthcare or financial services certification depth. Signal to watch: AI-powered call analytics intersecting with evolving data sovereignty rules before multi-tenant cloud commitment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Pulls PBX procurement into broader Salesforce and Microsoft ecosystem purchasing cycles. |
| Managed Service Transition | Preserves incumbent revenue streams while addressing SME SIP security expertise gaps. |
| CE Marking Pre-Certification | Compresses ETSI test lab delays for EU market entry before competitor launches. |
| WebRTC Protocol Embedding | Enables browser-based patient portals in German healthcare without hardware procurement. |
| Vertical Specialization | Deepens contact-center integration for Avaya-style agent desktop lock-in against generic cloud. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market informing demand calibration and regulatory pathway mapping. Primary interviews with CTOs, IT procurement officers, telecommunications infrastructure managers, channel partners, and healthcare systems integration specialists combined with secondary validation from FCC filings, ETSI certification databases, TRAI regulatory circulars, and hyperscaler UCaaS revenue disclosures. Bottom-up deployment model sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition separated hardware refresh cycle compression from cloud subscription momentum, with segmentation dimensions spanning deployment architecture, service bundling intensity, end-user scale, and technology protocol standardization. CAGRs derived from installed base migration curves, copper network decommissioning timelines, and API integration adoption rates across the analysis window. Industry-specific inputs included SIP trunking penetration trajectories and WebRTC protocol diffusion in healthcare verticals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration, ETSI certification backlog duration, and FCC net neutrality policy continuity. Forecasts reflect documented assumptions regarding carrier infrastructure decommissioning schedules and enterprise cloud migration elasticity. Material deviation in GDPR enforcement intensity or Taiwanese foundry capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
5G System Integration Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
A2P Messaging Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
DWDM System Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Software Defined Radio Market
Telecommunications
Bahrain Telecom Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Underwater Modems Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Africa Roaming Tariff Market