
 Enterprise Network Firewall Market | 2026-2036
Enterprise Network Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Network Firewall Market Foresight
Managed security service provider channels is tilting toward cloud-delivered firewall platforms as enterprises shed on-premises appliance overhead. Palo Alto Networks leverages integrated threat intelligence to sustain premium positioning across distributed deployments. Fortinet anchors mid-market penetration with consolidated networking-security appliances that compress vendor sprawl. Check Point Software Technologies differentiates through software-defined perimeter capabilities that compete directly with emerging zero-trust network access alternatives.
An enterprise network firewall is a network security system that inspects inbound and outbound traffic against policy rules at throughput rates ranging from 1 Gbps to over 1 Tbps in chassis-based deployments, blocking unauthorized access while permitting legitimate communications. Its primary commercial purpose is to enforce segmentation between trusted internal networks and untrusted external domains, serving as the foundational control point for regulatory compliance and threat containment. Cloud firewall deployments are capturing the fastest expansion as organizations retire data center footprints, while hardware firewall revenue pools remain concentrated in regulated industries with strict data residency mandates. The end user split reveals large enterprises as the mature spending base, with SMBs representing the underpenetrated growth frontier where simplified management interfaces determine vendor selection.
NIST, ISO 27001, and the EU NIS2 Directive collectively shape product certification requirements and procurement eligibility across the United States, Europe, and transatlantic supply chains. Compliance deadlines under NIS2 are forcing critical infrastructure operators to upgrade from stateful inspection to next-generation firewall architectures with application-layer visibility. Stakeholders must monitor how generative AI-driven attack automation reshapes the performance specifications that procurement teams embed in firewall evaluation criteria.
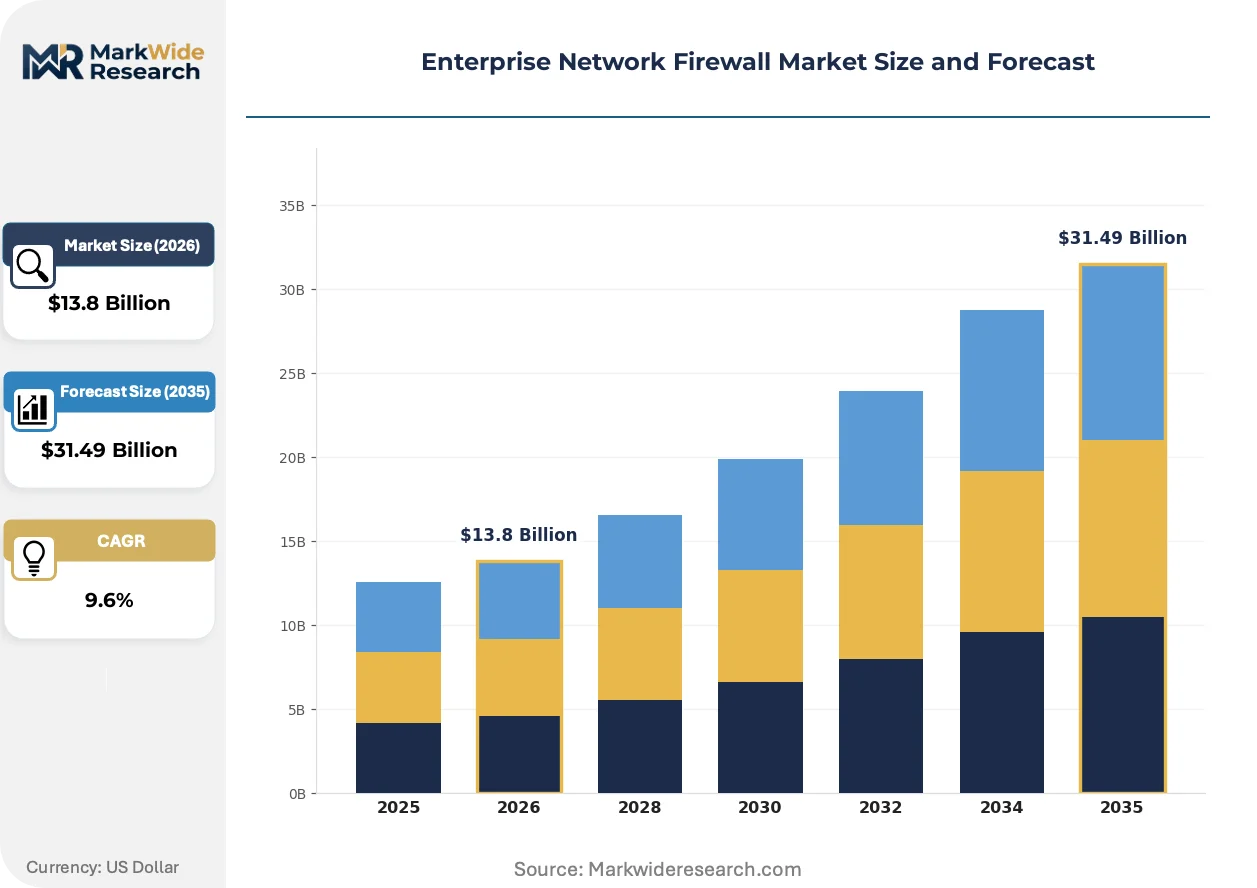
Market Dynamics
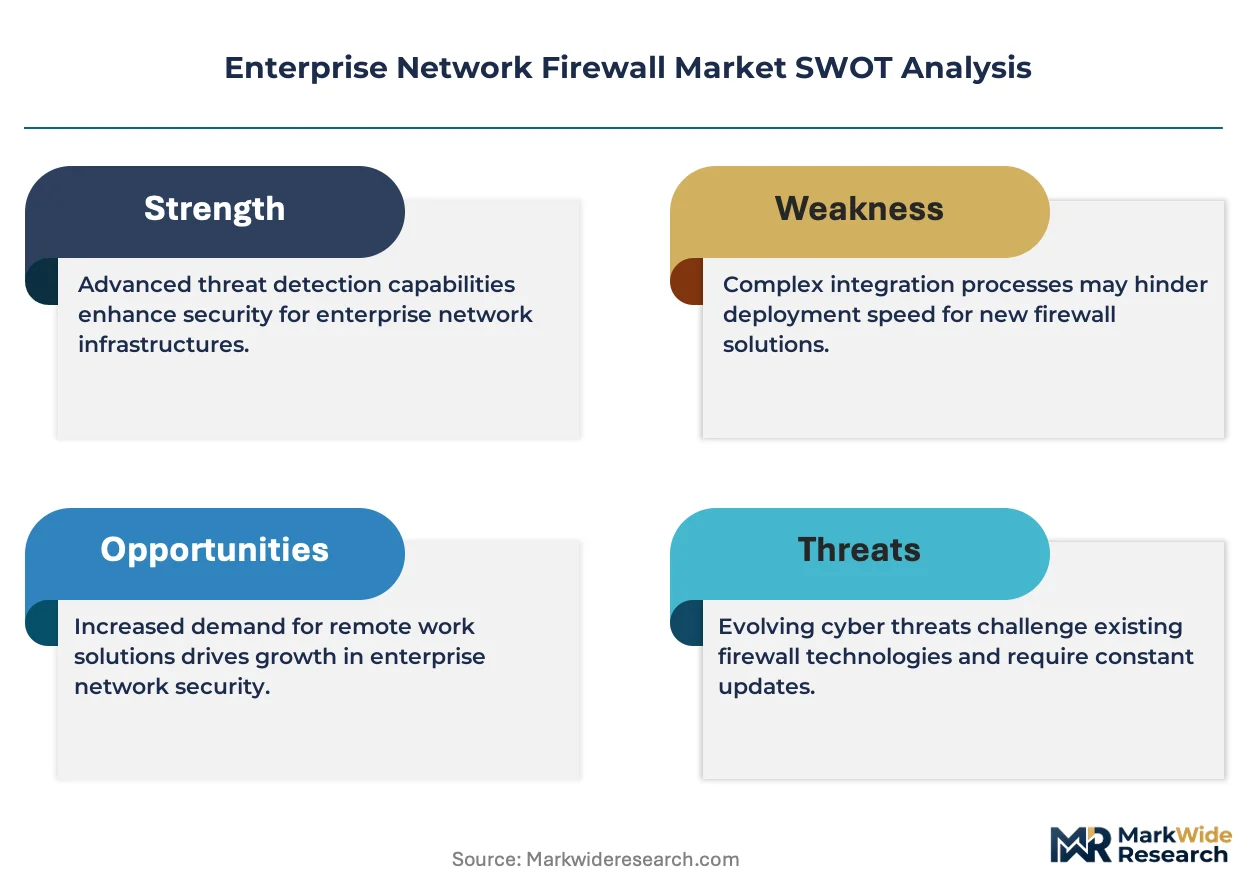
The enterprise network firewall market is undergoing structural compression as zero-trust architecture mandates displace perimeter-centric deployment models, forcing vendors to reengineer product roadmaps around identity-aware segmentation rather than IP-based rule sets.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across European member states must upgrade to next-generation firewall capabilities with application-layer inspection, creating mandatory replacement cycles before enforcement deadlines.
- Operational technology convergence:German automotive and chemical manufacturers are extending firewall coverage to manufacturing execution systems, driving demand for industrial protocol-aware inspection engines.
- Cloud-native payment architectures:Financial services institutions in Singapore and the United States are procuring distributed firewall fabrics to secure containerized transaction processing without performance degradation.
Market Restraints
- Semiconductor supply concentration:Custom ASIC fabrication for high-throughput inspection engines depends on a concentrated foundry base in Taiwan, creating vulnerability to geopolitical disruption.
- Skills scarcity:Enterprise security teams lack personnel proficient in both zero-trust policy engineering and legacy firewall migration, extending deployment timelines.
- Technical debt accumulation:Stateful inspection appliances deployed during the 2015-2020 hardware refresh cycle resist seamless integration with cloud-native management planes.
Strategic Opportunities
- SMB underpenetration:Managed security service providers are developing simplified firewall-as-a-service offerings for mid-market enterprises lacking dedicated security operations centers.
- 5G edge security:Telecommunications carriers require distributed firewall nodes for mobile edge computing deployments, opening new procurement channels beyond traditional enterprise IT.
- India's data localization mandates:The country's central bank and telecommunications regulator are compelling multinational enterprises to deploy in-country firewall infrastructure, creating geographic expansion requirements.
Industry Challenges
- Certificate management complexity:Mutual TLS inspection at scale demands automated certificate lifecycle management that most enterprises have not operationalized.
- Multi-vendor orchestration:Heterogeneous firewall estates resist unified policy enforcement, forcing buyers to choose between vendor consolidation and best-of-breed functional depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Network Firewall Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $31.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Firewall, Software Firewall, Cloud Firewall, Virtual Firewall Installation Type: On-Premises, Hosted, Hybrid, Managed Deployment Model: Standalone, Integrated, Centralized, Distributed End User: Large Enterprises, SMBs, Government, Healthcare |
| Companies Covered | Check Point Software Technologies, Sophos, Palo Alto Networks, SonicWall, WatchGuard, Fortinet, Juniper Networks, Forcepoint, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Network Firewall Market Shifts & Advancements
Firewall technology is virtualizing at the network edge as hardware dependency gives way to software-defined deployment models, with regulatory pressure and procurement transformation accelerating the transition from appliance-centric to cloud-delivered security fabrics.
Firewall-as-a-Service architectures are virtualizing the traditional appliance form factor into elastic cloud-native instances that scale with traffic volume rather than fixed chassis capacity. Large enterprises with distributed branch footprints are adopting these models fastest, compressing capital expenditure cycles into operational subscription structures. The technology is virtualizing perimeter enforcement into identity-bound microsegmentation that follows workloads across hybrid infrastructure.
The EU NIS2 Directive is mandating application-layer visibility and encrypted traffic inspection for critical infrastructure operators, with compliance deadlines forcing architectural upgrades from stateful packet filtering to deep packet inspection capabilities. Energy utilities and healthcare providers face the steepest compliance curves. German and French operators are responding with consolidated procurement of next-generation firewall platforms that unify network and endpoint telemetry.
Security procurement is consolidating through managed service provider channels as enterprises shed operational overhead of on-premises appliance management. Mid-market buyers are displacing direct vendor relationships with subscription-based firewall services bundled with 24/7 monitoring. This channel migration is most pronounced in the United Kingdom and Australia, where labor costs for internal security operations have risen fastest relative to outsourced alternatives.
Enterprise Network Firewall Market Segmentation
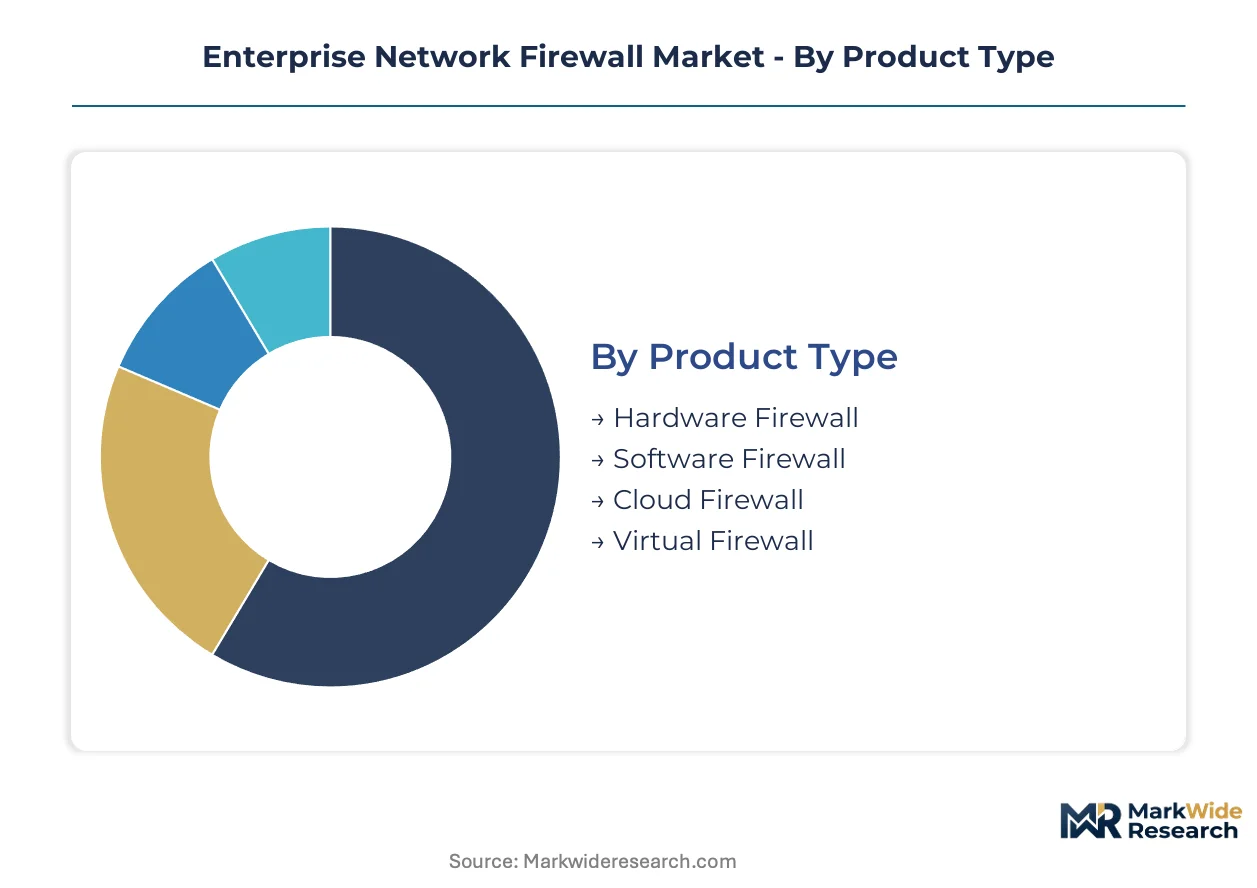
Firewall procurement patterns diverge sharply across organizational scale and infrastructure maturity. Product architecture choices determine whether buyers prioritize capital efficiency, operational control, or elastic scaling against threat volume.
Product Type:
Mature hardware deployments anchor regulated industries while cloud-native alternatives capture emerging demand from digital-first enterprises.
- Hardware Firewall:Purpose-built appliances with dedicated ASIC-based inspection engines deliver deterministic throughput for data centers. Financial services institutions in Frankfurt and Singapore maintain hardware dominance for payment card industry compliance.
- Cloud Firewall:Elastic instances scale inspection capacity with traffic volume rather than fixed chassis limits. Retail and software enterprises retiring data center footprints drive procurement through AWS, Azure, and Google Cloud marketplaces.
- Software Firewall:Virtualized form factors deploy on commodity compute for branch office consolidation.
- Virtual Firewall:Containerized micro-firewalls secure east-west traffic within Kubernetes clusters.
Hardware appliances handle the majority of throughput; cloud firewalls are gaining share fastest among net-new deployments.
Installation Type:
Cost tier stratification separates buyers with internal security operations from those outsourcing management entirely.
- On-Premises:Direct appliance ownership demands capital expenditure and internal expertise for patch management and rule optimization. German automotive manufacturers prefer this model for operational technology network segmentation.
- Managed:Third-party security operations centers assume 24/7 monitoring, threat hunting, and policy tuning. United Kingdom mid-market enterprises adopt managed firewalls fastest where security labor costs exceed outsourced alternatives.
- Hosted:Single-tenant cloud deployments preserve isolation without capital ownership.
- Hybrid:Split architectures maintain on-premises enforcement for legacy systems alongside cloud instances for modern workloads.
On-premises installations retain the largest installed base; managed services climb the fastest as skills scarcity deepens.
Deployment Model:
Application topology dictates whether centralized policy control or distributed enforcement proves operationally superior.
- Distributed:Perimeter nodes at every branch, cloud region, and manufacturing site apply consistent policies without traffic backhaul. Telecommunications carriers in India deploy distributed firewalls for 5G edge computing security.
- Integrated:Firewall functions collapse into SD-WAN appliances or cloud security service edge platforms, compressing vendor relationships.
- Standalone:Discrete appliances operate without platform dependencies for maximum functional isolation.
- Centralized:Single policy engine governs distributed enforcement points through hierarchical rule inheritance.
Distributed architectures absorb the most capital; integrated deployments show the steepest expansion trajectory as platform consolidation accelerates.
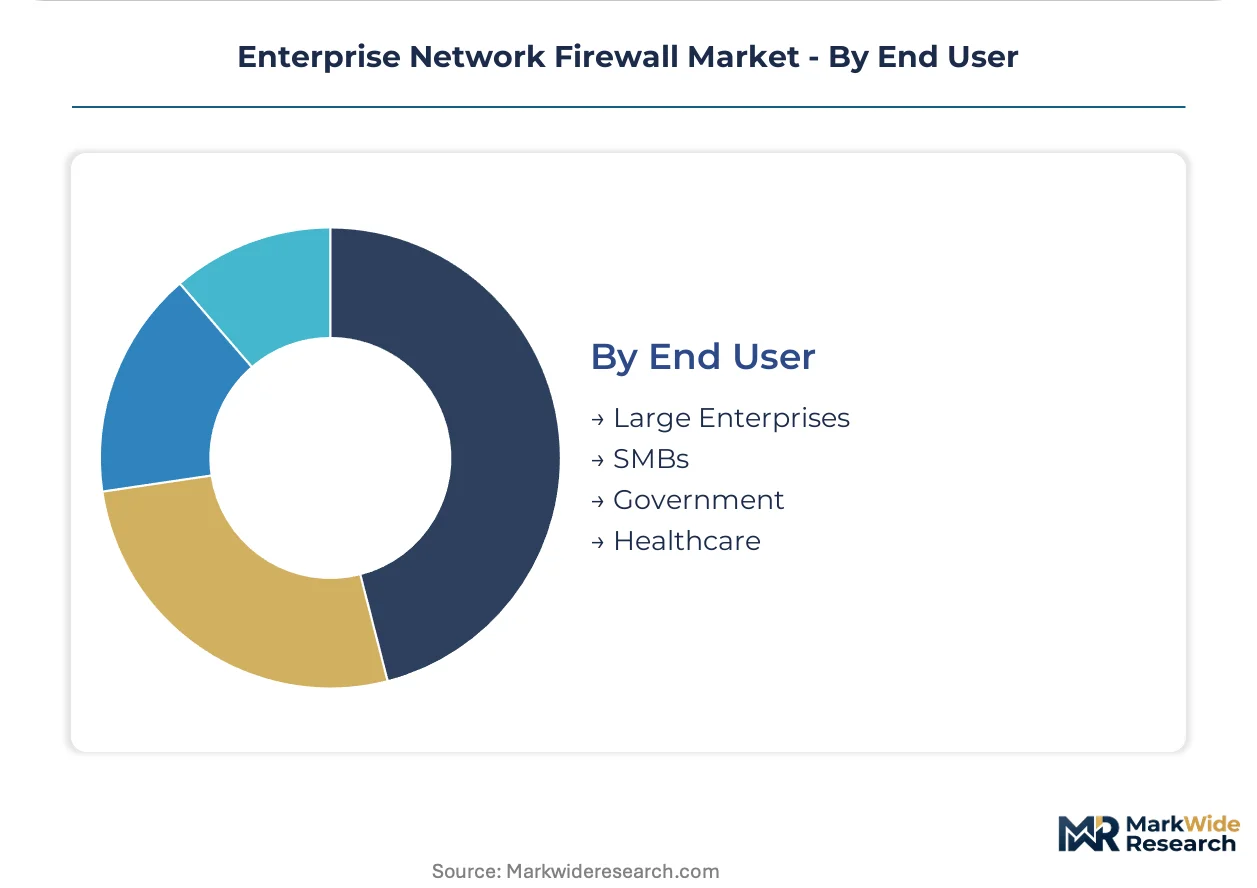
End User:
Customer type determines feature requirements from industrial protocol awareness to simplified management interfaces.
- Large Enterprises:Complex multi-site environments demand granular segmentation, API-driven automation, and threat intelligence integration. United States healthcare systems deploy next-generation firewalls for HIPAA-mandated access controls.
- SMBs:Resource-constrained buyers prioritize wizard-driven configuration and bundled support over advanced features. Australian professional services firms represent an underpenetrated growth pool.
- Government:Classified and unclassified networks require certified encryption and air-gapped management planes.
- Healthcare:Medical device networks and electronic health record systems need application-aware inspection without patient care disruption.
Large enterprises command the deepest per-account revenue; SMBs represent the fastest-expanding addressable market as managed services democratize enterprise-grade protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Singapore's Changi and Tuas anchor Asia-Pacific firewall procurement, channeling intra-Asian financial traffic through security infrastructure that rivals London and New York in transaction density.
United States
Cloud-native payment architectures at New York financial institutions drive distributed firewall fabric deployments. NIST cybersecurity framework updates compel healthcare systems in Boston to replace legacy perimeter defenses with zero-trust-aligned platforms. Silicon Valley technology firms consolidate vendor relationships through integrated SD-WAN security stacks.
Germany
Industrial manufacturers in Stuttgart and Munich extend firewall coverage to manufacturing execution systems for operational technology protection. EU NIS2 Directive compliance deadlines force energy utilities in the Ruhr region toward next-generation architectures with application-layer inspection. Frankfurt's financial data centers maintain hardware firewall dominance for payment card industry compliance.
Singapore
Containerized transaction processing at Marina Bay financial hubs demands distributed firewall fabrics without performance degradation. The Monetary Authority of Singapore's technology risk management guidelines shape procurement specifications for banking infrastructure. Telecommunications carriers deploy edge security nodes for 5G mobile computing across the island-state.
United Kingdom
Mid-market enterprises in London adopt managed firewall services fastest where internal security labor costs exceed outsourced alternatives. The National Cyber Security Centre's guidance influences critical infrastructure operator procurement for encrypted traffic inspection. Manchester's professional services sector represents an underpenetrated growth pool for simplified management interfaces.
India
Data localization mandates from RBI and TRAI compel multinational enterprises to deploy in-country firewall infrastructure. Mumbai's banking corridors and Bangalore's technology parks anchor geographic expansion requirements for hardware and cloud-native deployments. Telecommunications carriers require distributed firewall nodes for 5G edge computing security across Maharashtra and Karnataka.
Enterprise Network Firewall Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying inspection engines and threat intelligence feeds. The vendor base stratifies between consolidated networking-security platforms and best-of-breed functional depth providers. Three archetypes dominate: ASIC-optimized hardware fabricators, cloud-native virtualized stack vendors, and managed security service intermediaries. Competitive moves concentrate on vendor consolidation through strategic partnerships and geographic expansion into data localization-mandated markets.
Within the integrated platform tier, Palo Alto Networks and Fortinet occupy positions exemplifying converged networking-security positioning. Check Point Software Technologies anchors the software-defined perimeter specialization vector. These three vendors represent distinct strategic postures: threat intelligence integration at premium positioning, mid-market consolidation through appliance compression, and zero-trust network access competition respectively.
| Leading Market Players |
|---|
| Check Point Software Technologies |
| Sophos |
| Palo Alto Networks |
| SonicWall |
| WatchGuard |
| Fortinet |
| Juniper Networks |
| Forcepoint |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
Taiwan semiconductor foundry concentration determines both firewall appliance tier spreads and supply chain vulnerability profiles. Custom ASIC fabrication dependency compresses margins at the hardware tier while amplifying premium pricing power for vendors with captive chip design capabilities.
Pricing Analysis
Volume-discount tiering structures separate chassis-based enterprise deployments from virtualized branch-office instances. Three-tier pricing stratifies across premium threat-intelligence-integrated platforms, standard unified threat management appliances, and economy virtual firewall licenses. Cost compression in mid-market hardware stems from Fortinet's ASIC consolidation strategy. SMB buyers exhibit highest price sensitivity, while regulated financial institutions absorb premium positioning for compliance-grade inspection throughput.
Supply Chain Analysis
Extended payment terms from Taiwanese foundry partners strain working capital for hardware-centric vendors. Supply concentration rests on Taiwan for custom silicon, Malaysia for PCB assembly, and China for commodity component sourcing. Rare earth magnet dependencies and DRAM supply volatility constitute persistent procurement risks. Distribution runs through direct enterprise sales teams, managed security service provider channels, and hyperscaler cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firewall procurement power concentrates among managed security service providers consolidating mid-market relationships. This buyer-side aggregation compresses vendor margins while elevating channel partnership terms as competitive battlegrounds.
For Market Incumbents: Entrench zero-trust platform positioning through identity-aware segmentation R&D investment. Acquire containerized micro-firewall specialists to defend against cloud-native entrants. Prioritize NIST compliance certification maintenance as procurement eligibility gatekeeper. For New Entrants and Emerging Players: Pursue Australian and United Kingdom SMB segments where managed service provider bundling remains underdeveloped. Target 5G telecommunications edge security deployments in India and Singapore. Differentiate through automated certificate lifecycle management as mutual TLS inspection complexity intensifies. For Investors and Strategic Acquirers: EU NIS2 Directive reshapes the acquisition landscape toward application-layer inspection capability owners. Favor targets with operational technology protocol awareness and German industrial manufacturing relationships. Monitor generative AI-driven attack automation as inflection signal for next-generation performance specification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Platform Integration | Consolidates identity-aware segmentation with NIST framework alignment for healthcare and financial procurement. |
| ASIC Architecture Consolidation | Compresses hardware costs through captive silicon design, anchoring Fortinet's mid-market penetration strategy. |
| Managed Security Service Partnership | Captures SMB demand in United Kingdom and Australia where internal security labor costs exceed outsourced alternatives. |
| Operational Technology Protocol Development | Secures German automotive and chemical manufacturing firewall procurement for manufacturing execution system protection. |
| Cloud-Native Virtualization Expansion | Scales elastic inspection capacity for AWS, Azure, and Google Cloud marketplace procurement channels. |
Research Methodology
The analysis maps hardware appliance, cloud-native, software-defined, and virtualized micro-firewall sub-sectors, each validated through chief information security officers, network architecture leads, managed security service provider procurement directors, and compliance officers. Primary fieldwork combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, NIST framework documentation, and EU NIS2 Directive regulatory texts. Bottom-up deployment volume estimates triangulated against top-down vendor revenue attribution.
Assumption sets held Taiwan foundry capacity and EU NIS2 enforcement timelines as fixed boundary conditions while varying cloud adoption velocity and zero-trust architecture migration rates. Segmentation dimensions modeled include product architecture, installation type, deployment topology, and organizational scale across the projection horizon. CAGRs derived from deployment volume trajectories, replacement cycle compression, and pricing elasticity responses to competitive positioning shifts.
Sensitivities concentrate around Taiwan geopolitical disruption, generative AI attack automation acceleration, and managed security service provider channel consolidation velocity. Forecasts reflect documented assumptions; semiconductor supply interruption, regulatory deadline extension, or zero-trust architectural standard deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cloud-Based Database Security Market
Cybersecurity
Global Cloud Encryption Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
Asia Pacific Cybersecurity Market
Cybersecurity
Europe Mobile Security Market
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Global Bug Bounty Platforms Market
Cybersecurity
Cloud Workload Protection Market
Cybersecurity
Content Delivery Network (CDN) Security Market
Cybersecurity
Global Mobile Application Security Market
Cybersecurity
Big Data Security Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Micro-Segmentation Solutions Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Cloud Siem Market