
 Infertility Treatment Market | 2026-2036
Infertility Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Infertility Treatment Market Intelligence
Asset-light franchising and managed-service partnerships are reshaping competitive dynamics in infertility services, lowering capital barriers for regional entrants. Nova IVF Fertility leverages a hub-and-spoke clinic model to sustain presence across multiple Indian states. IVI Fertility anchors European operations through centralized laboratory networks in Spain and Portugal. Progyny competes via employer-sponsored fertility benefits that control channel access to commercial patient pools.
Infertility treatment encompasses clinical interventions designed to restore or enable reproductive function through hormonal modulation, surgical correction, laboratory-assisted gamete manipulation, or embryo transfer procedures requiring controlled temperature, pH, and osmolarity parameters. The primary commercial purpose centers on overcoming diagnosed or idiopathic reproductive failure to achieve viable pregnancy outcomes. In Vitro Fertilization commands the dominant margin pool due to medication complexity and laboratory intensity, while Intracytoplasmic Sperm Injection grows fastest among male-factor indications. Telehealth Consultations within the Delivery Mode dimension attract new capital as pre-screening and cycle-monitoring workflows shift outside physical clinic infrastructure.
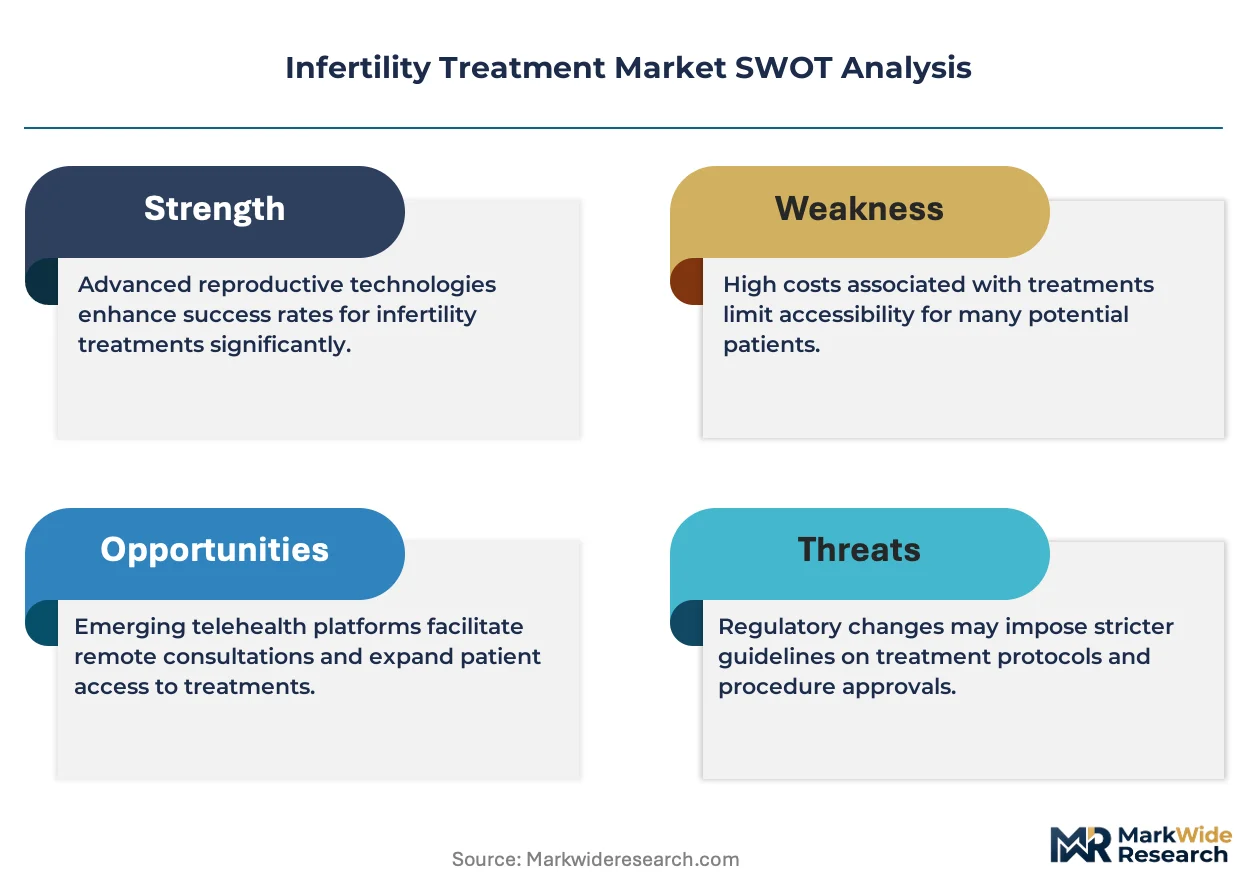
The FDA regulates assisted reproductive technology devices and culture media under 21 CFR requirements, while the EMA oversees gamete and embryo handling standards through MDR classifications that shape product registration burdens for European market access. India's CDSCO and the country's national pharmaceutical regulator enforce labeling and import controls on hormonal stimulation drugs that constrain supply flexibility. Stakeholders must monitor how evolving reimbursement policy across Medicare, commercial payers, and national health schemes reallocates patient flow between hospital systems and standalone fertility clinics.
Market Dynamics
Employer-sponsored fertility benefits are restructuring patient acquisition economics, channeling commercially insured individuals toward designated clinic networks and compressing out-of-pocket sensitivity for high-acuity procedures.
Growth Catalysts
- Delayed family formation:Rising maternal age across developed economies expands the addressable patient pool for assisted reproductive technology interventions.
- MDR harmonization:The European Union's Medical Device Regulation streamlines cross-border certification for embryo culture media and incubation systems, accelerating product launches in Spain, Portugal, and Italy.
- Oocyte vitrification:Flash-freezing protocols improve cryopreservation outcomes and enable elective fertility preservation among oncology patients and career-planning demographics.
Market Restraints
- Gonadotropin supply concentration:Recombinant follicle-stimulating hormone production clusters among three European API manufacturers, exposing clinics to batch shortage risk and price volatility.
- CDSCO import licensing:India's drug controller restricts hormonal stimulation drug shipments through extended labeling review timelines, constraining supply flexibility for domestic fertility chains.
- Laboratory skill scarcity:Embryologist certification programs produce insufficient qualified personnel relative to clinic expansion rates in tier-2 Indian cities.
Strategic Opportunities
- Telehealth pre-screening:Remote ovarian reserve assessment and cycle monitoring reduce physical visit burdens, opening access for patients in Brazil's interior states and India's northeastern corridors.
- Preimplantation genetic testing:Chromosomal screening integration with IVF workflows addresses recurrent implantation failure and expands premium service tiers.
- IRA fertility coverage:United States federal benefit expansions for veterans and federal employees create new reimbursed patient segments for contracted provider networks.
Industry Challenges
- Embryology training pipelines:Accreditation bodies in the United States and Europe cannot scale certification throughput to match clinic construction timelines, creating regional talent deficits.
- Incubator validation protocols:Continuous culture system installations require 18-24 month laboratory renovation cycles, delaying revenue recognition for capital-intensive upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infertility Treatment Market |
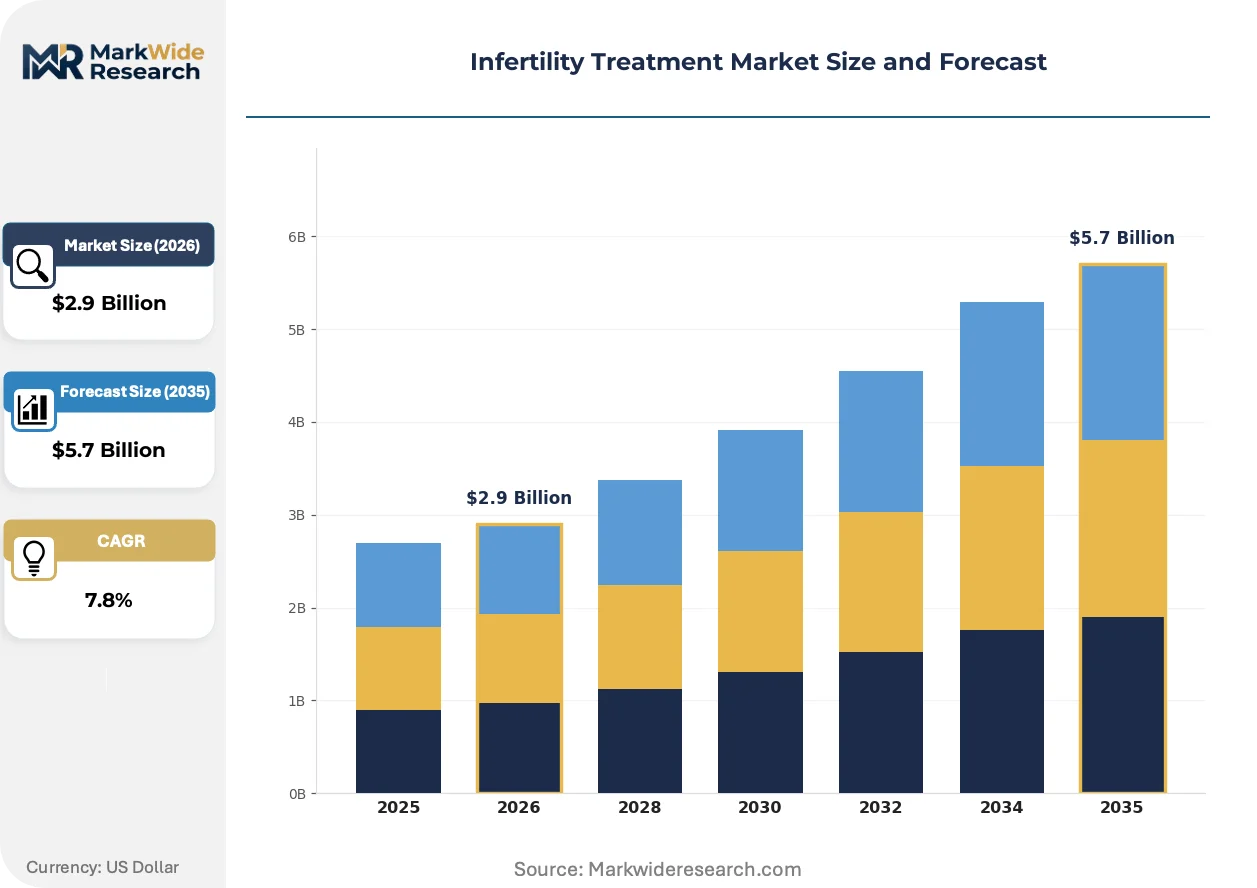
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: In Vitro Fertilization, Intrauterine Insemination, Intracytoplasmic Sperm Injection, Ovulation Induction, Surgery Therapy Area: Male Infertility, Female Infertility, Unexplained Infertility, Recurrent Pregnancy Loss, Endometriosis End User: Fertility Clinics, Hospitals, Diagnostic Centers, Assisted Reproductive Technology Centers Delivery Mode: In-Clinic Procedures, Home-Based Treatments, Telehealth Consultations, Mobile Health Applications |
| Companies Covered | Nova IVF Fertility, IVI Fertility, CCRM Fertility, Progyny, Clínica Tambre, Main Line Fertility, Indira IVF Fertility Centre, Kindbody, Apollo Fertility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infertility Treatment Market Strategic Shifts & Innovations
Time-lapse imaging and artificial intelligence classification are transforming embryo selection protocols, reducing subjective morphological assessment and compressing transfer decision timelines.
Time-lapse incubation systems equipped with computational morphology scoring are rendering obsolete static day-3 and day-5 observational methods that required manual handling and temperature fluctuation exposure. Large fertility clinic networks in Spain and the United States are adopting these platforms at replacement cycle rates exceeding 40% annually. The technology is rendering obsolete traditional embryologist workload structures while concentrating capital expenditure among well-capitalized laboratory operators.
REACH substance restrictions are tightening classification thresholds for phthalates and bisphenol derivatives in plastic cultureware, forcing manufacturers to validate alternative polymer formulations for biocompatibility. European device suppliers face reformulation costs and extended notification timelines that compress margin structures on disposable product lines. Gamete handling consumables destined for EMA-regulated laboratories bear the heaviest compliance burden, with several suppliers accelerating Asian market pivots to offset European revenue drag.
Direct employer contracting is displacing traditional insurance reimbursement pathways for fertility services in the United States commercial sector. Self-insured corporations are negotiating capitated rates with designated clinic networks, bypassing payer intermediaries and compressing price transparency for patients. This channel shift concentrates volume among fertility platforms with national scale and standardized reporting infrastructure, disadvantaging regional standalone operators.
Infertility Treatment Market Segmentation
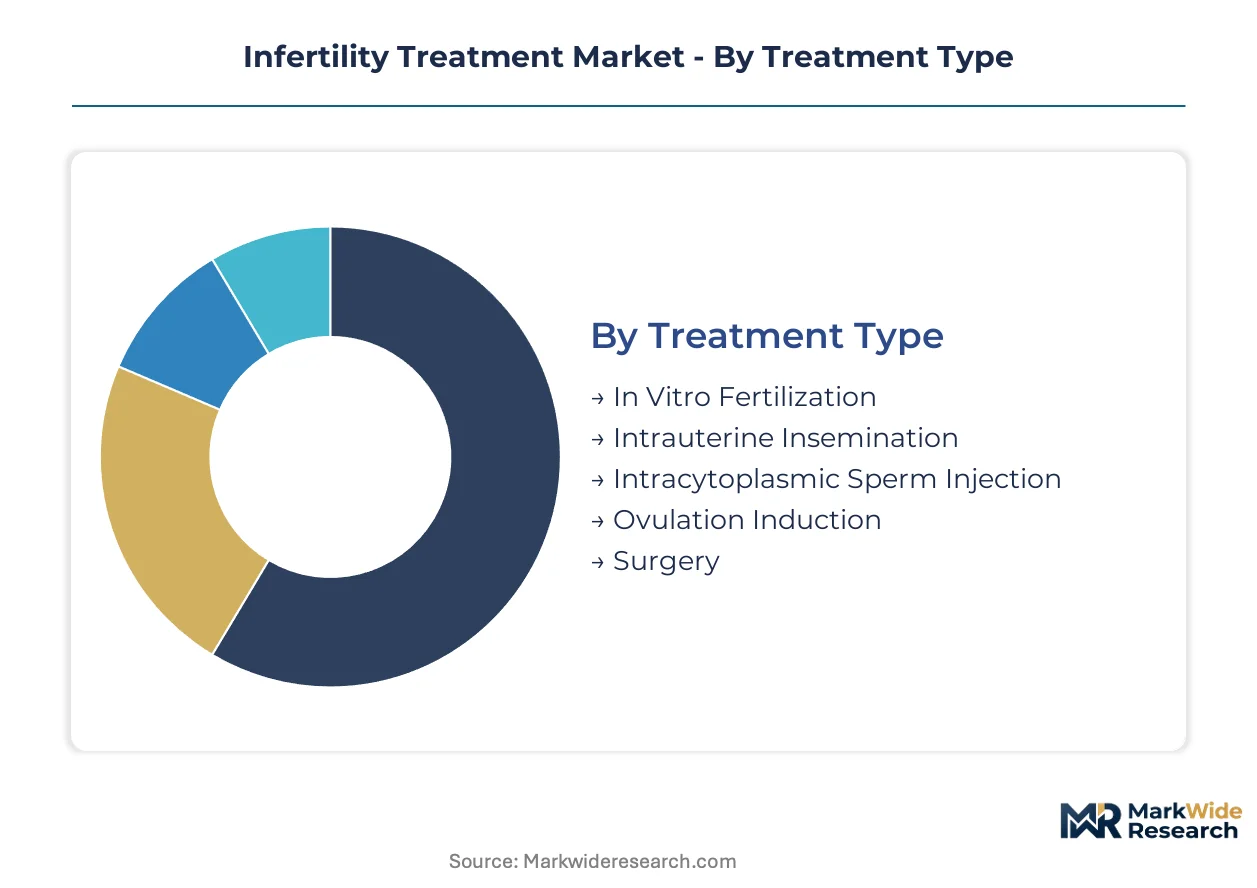
Treatment modality, patient etiology, and care delivery infrastructure each command distinct margin profiles and capital requirements in infertility services. Segment boundaries increasingly blur as fertility networks bundle diagnostic, therapeutic, and remote monitoring capabilities into integrated patient pathways.
Treatment Type:
Cost tier stratification separates laboratory-intensive interventions from hormonal and surgical alternatives, with reimbursement intensity tracking procedural complexity and consumable utilization.
- In Vitro Fertilization:Multi-stage protocol combining ovarian stimulation, oocyte retrieval, laboratory fertilization, and embryo transfer under controlled incubation parameters. Demand concentrates in Spain and the United States where employer-sponsored benefits offset cycle costs, though gonadotropin supply concentration exposes clinics to API shortage risk.
- Intracytoplasmic Sperm Injection:Micromanipulation technique injecting single sperm into ooplasm to address male-factor indications. Male infertility diagnoses are climbing fastest across India and Brazil, channeling patient volume toward specialized andrology laboratories with ICSI capability.
- Intrauterine Insemination:Lower-complexity procedure placing processed sperm into uterine cavity during ovulation window.
- Ovulation Induction:Pharmacological stimulation protocols using clomiphene or gonadotropins to trigger follicular development.
- Surgery:Laparoscopic or hysteroscopic correction of tubal obstruction, fibroids, or endometrial pathology.
In Vitro Fertilization commands the established base. The steepest expansion runs through Intracytoplasmic Sperm Injection.
Therapy Area:
Application focus determines diagnostic workup intensity and treatment sequencing, with male-factor and idiopathic cases requiring divergent laboratory and surgical resource allocation.
- Female Infertility:Encompasses tubal disease, ovulatory dysfunction, and uterine pathology requiring hormonal, surgical, or assisted reproductive technology intervention. India's tier-2 cities are generating fastest patient volume growth as Indira IVF and Apollo Fertility extend network coverage, though embryologist certification bottlenecks constrain service scaling.
- Male Infertility:Addresses azoospermia, oligospermia, and motility disorders through surgical sperm retrieval or ICSI augmentation. Spain's IVI Fertility anchors European andrology volume through centralized laboratory networks in Madrid and Barcelona.
- Unexplained Infertility:Diagnosis of exclusion after standard workup yields no identifiable pathology.
- Recurrent Pregnancy Loss:Specialized segment integrating preimplantation genetic testing and immunological evaluation.
- Endometriosis:Surgical and medical management of ectopic endometrial tissue impacting fertility potential.
Female Infertility retains the dominant patient share. Male Infertility is gaining share fastest as diagnostic sensitivity improves and ICSI penetration deepens.
End User:
Customer type dictates capital intensity, regulatory exposure, and reimbursement pathway structure across delivery infrastructure.
- Fertility Clinics:Dedicated facilities combining clinical consultation, ultrasound monitoring, oocyte retrieval, and embryology laboratory under single organizational control. United States standalone operators face volume pressure as Progyny's employer networks steer commercially insured patients toward designated national platforms.
- Hospitals:Integrated health systems offering fertility services within broader obstetric and gynecologic departments. India's Apollo Hospitals embed fertility centers within tertiary facilities to capture referral flows from internal medicine and oncology pathways.
- Diagnostic Centers:Specialized imaging and laboratory facilities providing semen analysis, ovarian reserve testing, and hysterosalpingography.
- Assisted Reproductive Technology Centers:Laboratory-focused facilities emphasizing cryopreservation, donor gamete management, and research protocols.
Fertility Clinics anchor commercial volume. Hospital-integrated services are expanding most quickly in emerging markets seeking capital efficiency.
Delivery Mode:
Maturity gradient separates established physical infrastructure from emerging remote and digital channels reshaping patient acquisition and monitoring economics.
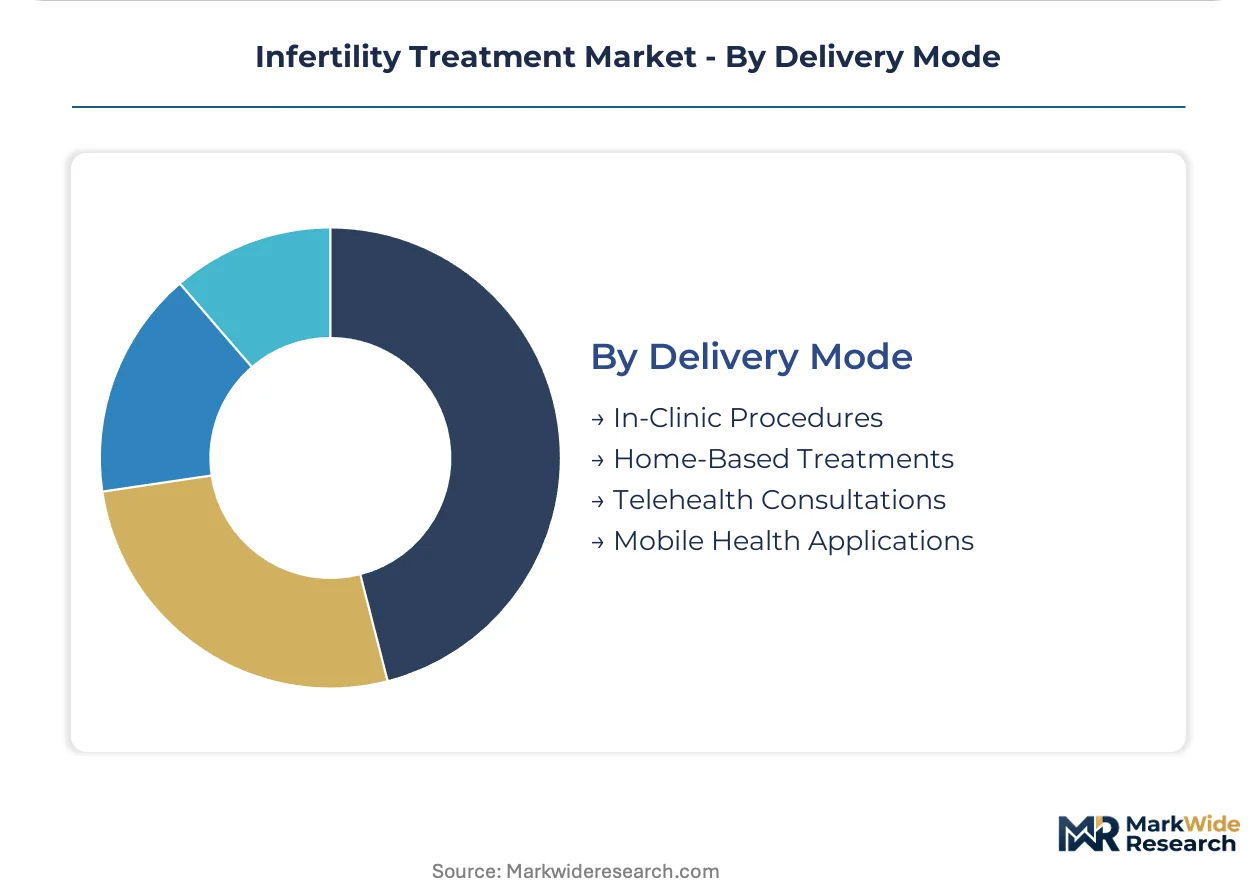
- In-Clinic Procedures:Traditional model requiring physical presence for stimulation monitoring, retrieval, transfer, and pregnancy verification. Spain's time-lapse incubator installations are concentrating among large clinic networks with 18-24 month laboratory renovation cycles, delaying revenue recognition for capital-intensive upgrades.
- Telehealth Consultations:Remote pre-screening, cycle monitoring, and medication instruction via synchronous video and asynchronous messaging. Brazil's interior states and India's northeastern corridors are opening to fertility access as telehealth reduces physical visit burdens for geographically dispersed populations.
- Home-Based Treatments:Self-administered hormonal injections and ovulation predictor kit utilization.
- Mobile Health Applications:Digital platforms for medication adherence, cycle tracking, and patient education.
In-Clinic Procedures retain procedure revenue concentration. Telehealth Consultations are climbing the fastest as pre-screening and monitoring workflows shift outside physical infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal benefit expansions and employer-sponsored coverage are redirecting patient flows toward contracted provider networks in developed economies, while regulatory harmonization accelerates product registration timelines across European laboratories.
United States
Employer-sponsored fertility benefits through Progyny's networks are compressing out-of-pocket costs for commercially insured patients. The FDA's 21 CFR oversight of assisted reproductive technology devices shapes product development pathways for domestic manufacturers. CCRM Fertility anchors national laboratory operations in Colorado and California, deploying standardized reporting infrastructure to capture direct employer contracting volume.
Spain
Time-lapse incubator installations exceeding 40% annual replacement rates are concentrating capital expenditure among large laboratory operators. The EMA's MDR classifications for embryo culture media streamline cross-border certification, accelerating product launches in Madrid and Barcelona. IVI Fertility anchors European andrology volume through centralized laboratory networks in these metropolitan clusters.
India
Indira IVF Fertility Centre and Apollo Fertility are scaling networks to serve underserved metropolitan and tier-2 cities with fastest patient volume growth. The CDSCO's extended labeling review timelines for hormonal stimulation drug imports constrain supply flexibility for domestic fertility chains. Laboratory skill scarcity in embryologist certification programs produces insufficient qualified personnel relative to clinic expansion rates in tier-2 cities.
Portugal
Centralized laboratory networks are capturing cross-border patient flows from European markets seeking cost-competitive IVF cycles. The EMA's gamete and embryo handling standards through MDR classifications shape product registration burdens for laboratory device suppliers. Lisbon and Porto clusters concentrate time-lapse imaging platform installations among well-capitalized fertility operators.
Brazil
Telehealth pre-screening and remote cycle monitoring are opening access for patients in interior states previously underserved by physical clinic infrastructure. The national pharmaceutical regulator enforces import controls on hormonal stimulation drugs that constrain supply flexibility. São Paulo and Rio de Janeiro anchor laboratory-intensive service delivery while telehealth channels extend reach into northeastern corridors.
Infertility Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented regional markets where employer networks and national scale determine patient acquisition economics. The vendor base separates into fertility clinic networks, employer benefit administrators, and laboratory technology suppliers with divergent capital intensity requirements. Three archetypes dominate: national platform operators with standardized infrastructure, regional specialists with hub-and-spoke geographic coverage, and technology-integrated laboratories with AI-enabled embryo selection. Competitive moves concentrate on direct employer contracting bypassing traditional payers and time-lapse incubator platform upgrades requiring 18-24 month renovation cycles.
Among clinic network operators, Nova IVF Fertility exemplifies the hub-and-spoke model sustaining multi-state presence across India, while IVI Fertility anchors European operations through centralized laboratory networks in Iberia. Within employer-sponsored benefit administration, Progyny occupies a position controlling channel access to commercially insured patient pools through capitated rate negotiations with designated clinic networks.
| Leading Market Players |
|---|
| Nova IVF Fertility |
| IVI Fertility |
| CCRM Fertility |
| Progyny |
| Clínica Tambre |
| Main Line Fertility |
| Indira IVF Fertility Centre |
| Kindbody |
| Apollo Fertility |
| Others |
Cost & Logistics Intelligence
Laboratory renovation cycles running 18-24 months for time-lapse incubator installations signal undercapacity in European embryology infrastructure, compressing supplier bargaining power while elevating pricing premiums for expedited equipment delivery and certified technician deployment.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus non-certified) creates the primary spread across culture media and incubation systems, with EMA-regulated laboratories commanding 15-25% premiums over Indian domestic tier. Three-tier pricing structure separates premium time-lapse platforms with AI embryo scoring from standard static incubation and economy-grade open systems. Cost compression in the economy tier is intensifying because REACH substance restrictions force polymer reformulation and extended biocompatibility validation. Employer-sponsored benefit administrators exhibit lowest price sensitivity due to capitated rate structures, while standalone regional clinics in tier-2 Indian cities face acute budget constraints.
Supply Chain Analysis
Recombinant follicle-stimulating hormone API production draws from Denmark, Switzerland, and Italy, with fermentation capacity concentrated among three European manufacturers. Culture media formulations rest on pharmaceutical-grade water, recombinant proteins, and synthetic hormones as critical inputs. Single-source vulnerability runs through gonadotropin batch certification, where any contamination event triggers clinic-wide cycle postponements. Distribution runs through cold-chain logistics partnerships serving fertility clinic networks, with hospital-integrated operators leveraging captive pharmacy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Time-lapse imaging with AI classification constitutes a high-growth disruption reshaping embryo selection economics, with MDR harmonization accelerating platform replacement cycles across Iberian laboratory clusters.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA 510(k) and EMA MDR submissions for embryo culture devices, preempting emerging Asian manufacturers from accessing reimbursed patient pools. Deepen backward integration into gonadotropin API sourcing through long-term offtake agreements with European fermentation facilities, insulating against batch shortage risk. Channel control via direct employer contracting with Progyny-style benefit administrators protects margin structures from price-transparent insurance intermediation. For New Entrants and Emerging Players: Establish a beachhead in telehealth pre-screening workflows for Brazil's interior states and India's northeastern corridors, where physical clinic infrastructure remains sparse and patient acquisition costs run below metropolitan benchmarks. Target male-factor infertility diagnostics as the most penetrable application, with ICSI penetration climbing fastest across India and Brazil. A go-to-market angle anchored in remote ovarian reserve assessment and asynchronous cycle monitoring bypasses capital-intensive laboratory construction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among employer-sponsored benefit administrators with multi-year corporate contracts, positioning these archetypes for sustained cash flow quality across the analysis window. Acquisition targets should concentrate on fertility clinic networks with centralized laboratory infrastructure and standardized reporting capabilities suited to capitated rate negotiations. The signal to watch is CDSCO import licensing timeline compression, which would unlock supply flexibility for domestic Indian chains and revalue their expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Embryo Selection Platform | Time-lapse imaging with computational morphology scoring reduces subjective assessment and compresses transfer timelines in Madrid and Barcelona clusters. |
| Direct Employer Contracting Network | Capitated rate negotiations with self-insured corporations bypass payer intermediaries and concentrate volume among national platform operators. |
| Telehealth Pre-Screening Infrastructure | Remote ovarian reserve assessment opens access for geographically dispersed populations in Brazil's interior states and India's northeastern corridors. |
| Preimplantation Genetic Testing Integration | Chromosomal screening workflows address recurrent implantation failure and expand premium service tiers within IVF protocols. |
| Gonadotropin Supply Security Agreement | Long-term offtake contracts with European API manufacturers mitigate batch shortage exposure and price volatility for domestic fertility chains. |
Research Approach
The analysis maps treatment modalities, patient etiologies, delivery infrastructure, and geographic regulatory clusters, each validated through embryologists, clinic operations directors, employer benefits managers, and CDSCO regulatory consultants. Primary interviews with fertility network executives and biomedical engineers combined with secondary validation against FDA 510(k) filings, EMA MDR submissions, CDSCO import licensing records, and hospital procurement databases. Bottom-up patient volume modeling and top-down expenditure aggregation triangulate market sizing across the projection horizon.
Assumptions held fixed include EMA MDR enforcement timelines, CDSCO labeling review durations, and employer-sponsored benefit penetration rates in the United States commercial sector; variables stress-tested encompass gonadotropin API shortage scenarios, telehealth reimbursement policy shifts, and REACH substance restriction expansion. Segmentation dimensions modeled span treatment type complexity tiers, therapy area diagnostic intensity, end-user capital structure, and delivery mode maturity gradient. CAGRs derive from patient volume growth rates applied to reimbursement-adjusted revenue per cycle, with oocyte vitrification adoption curves and ICSI penetration rates as fertility-specific forecast inputs.
Stress conditions across gonadotropin supply disruption, MDR notification delays, and employer benefit contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with embryologist certification throughput and laboratory renovation cycle duration representing specific risk factors that could revise trajectory. Cross-checking against national health scheme expenditure reports and commercial payer fertility benefit disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Epiglottitis Treatment Market