
 Endometrial Cancer Treatment Market | 2026-2036
Endometrial Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Endometrial Cancer Treatment Market Analysis
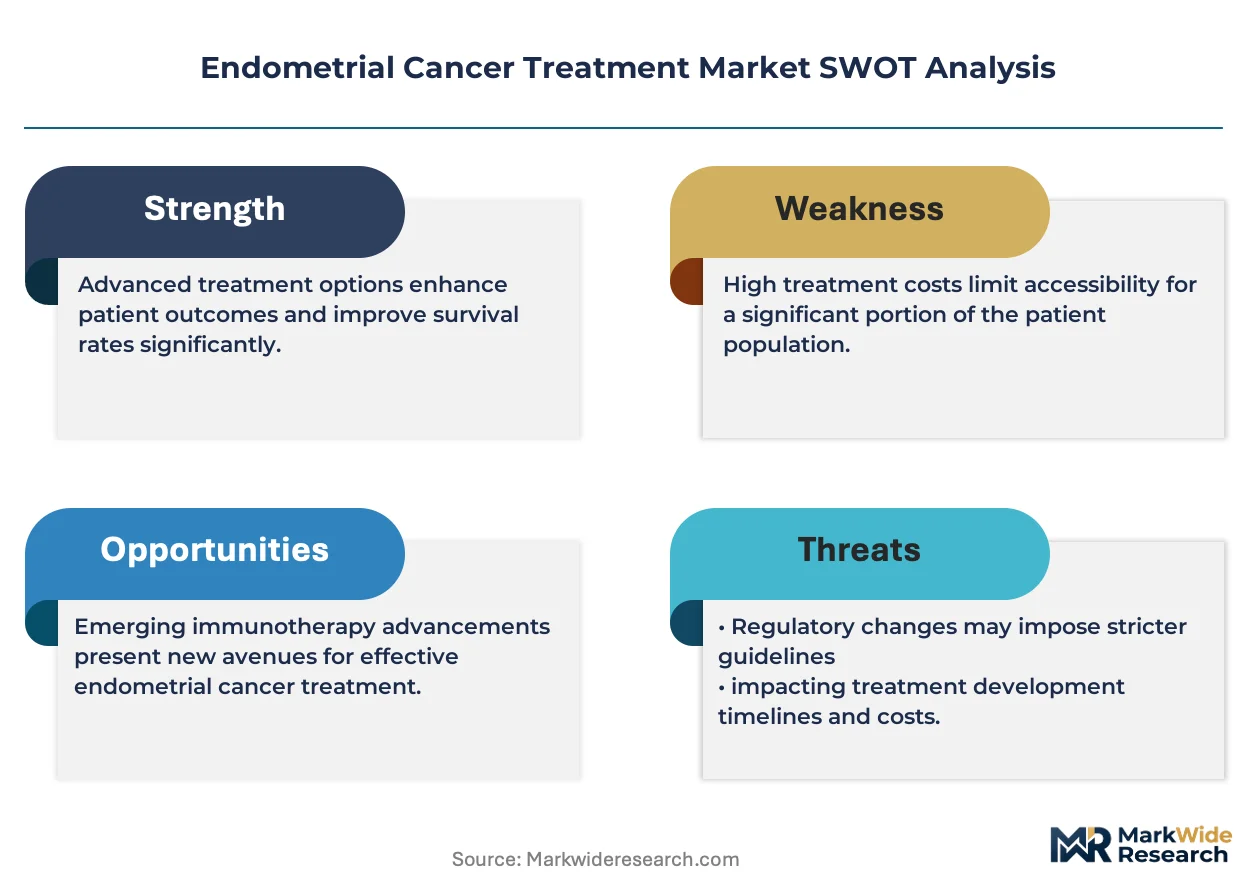
The EU Green Deal's pharmaceutical sustainability criteria is expanding procurement requirements for oncology supply chains across European hospital networks. Merck & Co. leverages its pembrolizumab franchise to dominate immuno-oncology positioning in endometrial cancer. AstraZeneca anchors PARP inhibitor development through sustained R&D intensity in gynecologic malignancies. Roche Holding AG differentiates its diagnostic-treatment integration by controlling companion testing pathways for PIK3CA-mutated tumors.
Endometrial cancer treatment encompasses systemic and locoregional therapeutic interventions targeting malignant epithelial tumors of the uterine lining, with chemotherapy regimens typically combining carboplatin and paclitaxel as first-line standards and immunotherapy agents requiring PD-L1 or microsatellite instability biomarker qualification. Immunotherapy now occupies the fastest-expanding margin pool as checkpoint inhibitors reshape adjuvant and metastatic protocols, while hormonal therapy sustains its niche in progesterone receptor-positive recurrent cases where chemotherapy tolerance is limited. Hospitals remain the dominant healthcare setting for intravenous delivery of cytotoxic and biologic agents, though specialty clinics compete for outpatient immunotherapy administration where monitoring protocols have standardized.
FDA oncology center guidance on real-world evidence integration and EMA's adaptive licensing framework are reshaping trial design and post-market surveillance requirements for novel endometrial cancer agents. Japan's PMDA has accelerated foreign drug approval harmonization, reducing lag times for PD-1 inhibitors in gynecologic indications. Stakeholders must monitor evolving biomarker-driven reimbursement criteria across these three regulatory jurisdictions to anticipate access expansion or restriction for combination regimens.
Market Dynamics
Checkpoint inhibitor approval pathways are compressing development timelines for endometrial cancer therapies while concentrating manufacturing investment in biologics capacity near major oncology hospital networks. This regulatory acceleration is restructuring competitive entry barriers around biomarker qualification capabilities rather than traditional chemotherapeutic manufacturing scale.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Expedited review pathways for PD-1/PD-L1 combinations in mismatch repair-deficient tumors are shortening time-to-market for novel immuno-oncology regimens. Oncology hospital networks in the United States are prioritizing formulary inclusion of designated therapies.
- EMA Adaptive Pathway Reforms:Conditional marketing authorization frameworks enable earlier patient access to PI3K inhibitors and AKT pathway modulators. German hospital procurement coalitions are leveraging these pathways to secure priority supply agreements.
- Companion Diagnostic Convergence:Automated immunohistochemistry platforms for PD-L1 and microsatellite instability testing are standardizing biomarker workflows. Academic medical centers in Japan are integrating these platforms into routine gynecologic oncology pathways.
Market Restraints
- Biologics Manufacturing Concentration:Monoclonal antibody production capacity clusters in Switzerland, Ireland, and Singapore, creating supply vulnerability for checkpoint inhibitor dependent regimens. Single-source dependencies for fill-finish operations amplify disruption risk.
- Reimbursement Fragmentation:Germany's G-BA benefit assessment processes impose 12-18 month delays between EMA approval and statutory health insurance coverage for combination immunotherapies. This creates treatment access gaps for recurrent endometrial cancer patients.
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution for biologics remains underdeveloped in secondary oncology centers across Southern and Eastern Europe, limiting site-of-care expansion for intravenous immunotherapy administration.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered checkpoint inhibitor formulations would shift treatment delivery from infusion centers to home settings. Patient advocacy networks in the United States are pressing manufacturers for injection-device compatibility.
- Real-World Evidence Integration:FDA Oncology Center guidance on external control arms enables accelerated approval for rare molecular subtypes. Flatiron Health and similar oncology data platforms are structuring retrospective cohorts for regulatory submission.
- Academic-Industry Biomarker Consortia:Transatlantic partnerships between Memorial Sloan Kettering and Karolinska Institutet are standardizing tumor mutational burden thresholds for endometrial cancer immunotherapy response prediction.
Industry Challenges
- Immuno-oncology Talent Scarcity:Translational researchers capable of integrating tumor microenvironment biology with clinical trial design command premium compensation. Biopharmaceutical developers in the Boston-Cambridge cluster report 18-month average hiring cycles for senior immuno-oncology directors.
- Legacy Chemotherapy Manufacturing Rationalization:Carboplatin and paclitaxel generic supply chains require sustained investment despite declining revenue per dose. Contract manufacturers face portfolio optimization decisions as immunotherapy volume displaces cytotoxic agent procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endometrial Cancer Treatment Market |
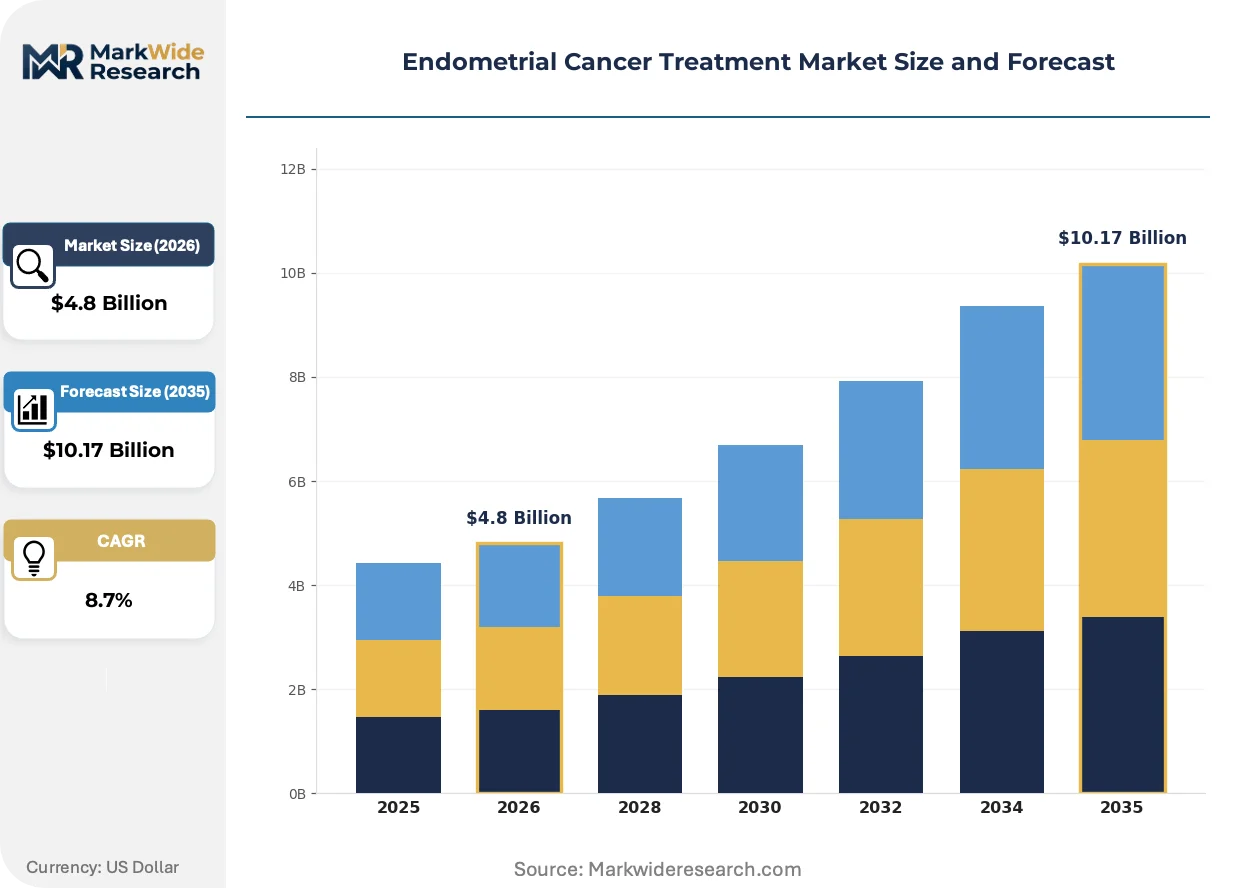
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Hormonal Therapy, Radiation Therapy Delivery Mode: Intravenous, Oral, Topical, Intraperitoneal End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Healthcare Setting: Outpatient, Inpatient, Telehealth, Rehabilitation |
| Companies Covered | Merck & Co., Inc., AstraZeneca, GlaxoSmithKline, Novartis AG, Roche Holding AG, Pfizer Inc., Eisai Co., Ltd., Bristol-Myers Squibb, Karyopharm Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endometrial Cancer Treatment Market Emerging Trajectories
Artificial intelligence is reshaping target identification and patient stratification in endometrial cancer drug development, compressing discovery timelines while raising computational infrastructure requirements across the biopharmaceutical value chain.
Antibody-drug conjugates targeting tissue factor and folate receptor alpha are electrifying the late-stage pipeline for recurrent endometrial cancer. Merck and Seagen are advancing tisotumab vedotin combinations through Phase III trials, while AstraZeneca's datopotamab deruxtecan program targets TROP2-expressing tumors. These conjugates are electrifying the competitive landscape by enabling chemotherapy payload delivery without systemic toxicity exposure, potentially displacing standard carboplatin-paclitaxel regimens in biomarker-selected populations.
EMA's pharmaceutical sustainability criteria under the EU Green Deal are mandating carbon footprint disclosure for oncology supply chains. Active pharmaceutical ingredient manufacturers must now report Scope 3 emissions from solvent-intensive synthetic routes, with German hospital procurement networks incorporating these metrics into tender evaluations. Biologics producers with renewable energy-powered manufacturing facilities in Denmark and the Netherlands are securing preferred supplier status.
Oncology hospital networks are consolidating intravenous therapy administration into specialized infusion centers with standardized nursing protocols. This consolidation is displacing general hospital ward-based chemotherapy delivery in the United States, where Medicare reimbursement differentials favor outpatient department settings. UnitedHealthcare and similar payers are steering patients toward accredited centers with documented immunotherapy adverse event management capabilities.
Endometrial Cancer Treatment Market Segmentation
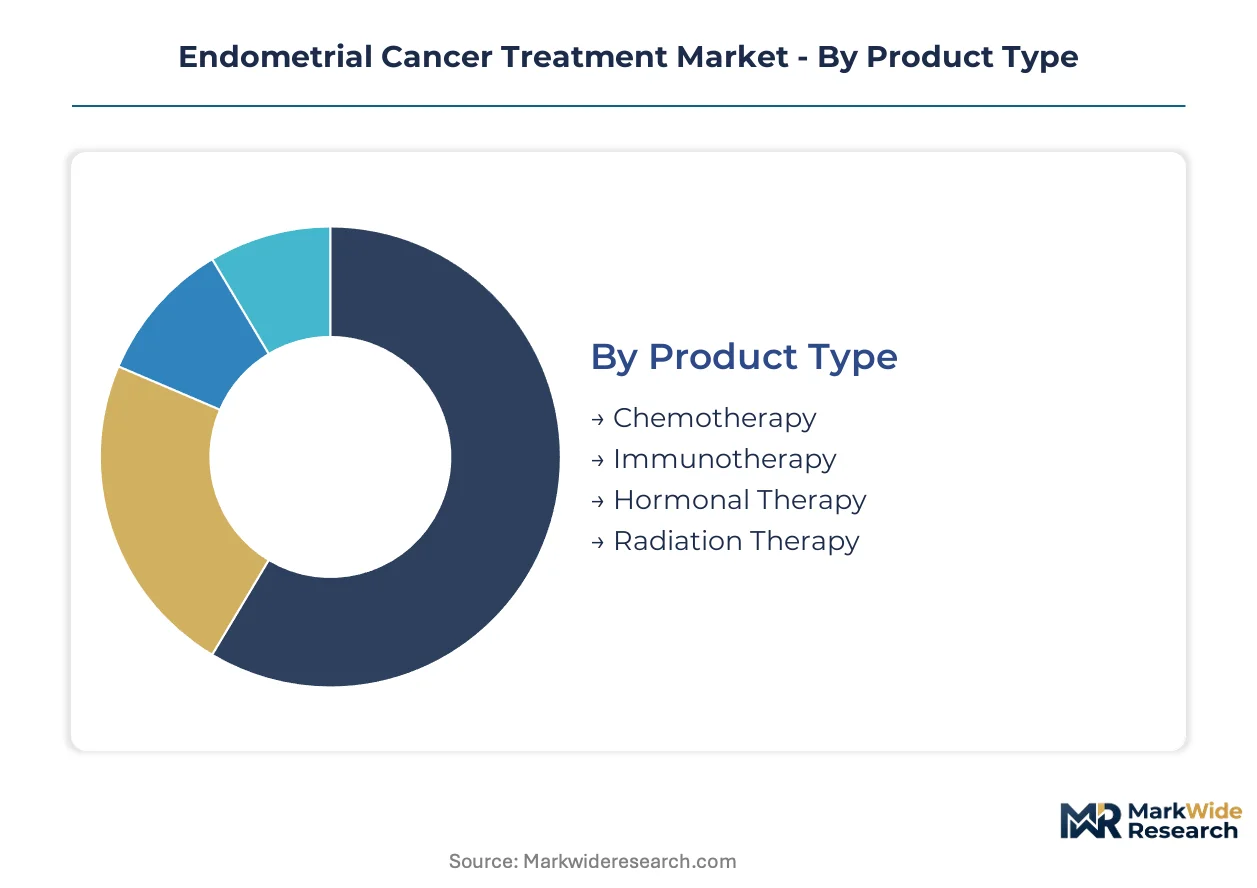
Endometrial cancer treatment modalities span distinct regulatory pathways, manufacturing requirements, and site-of-care economics. Understanding how these segments intersect with FDA, EMA, and PMDA approval frameworks illuminates where commercial investment concentrates and where access barriers persist.
Product Type:
Checkpoint inhibitors require FDA Breakthrough Therapy Designation or EMA PRIME eligibility to accelerate review, while hormonal agents follow established NDA pathways with abbreviated clinical data requirements. Companion diagnostic linkage determines reimbursement velocity across all segments.
- Immunotherapy:PD-1 and PD-L1 inhibitors dominate pipeline investment, with pembrolizumab and dostarlimab establishing first-line standards for mismatch repair-deficient tumors. Oncology hospital networks in the United States prioritize formulary inclusion for designated therapies, though manufacturing concentration in Switzerland and Ireland creates supply vulnerability.
- Chemotherapy:Carboplatin-paclitaxel combinations remain the backbone of adjuvant and metastatic protocols, supported by decades of clinical evidence and generic manufacturing scale. Contract manufacturers face portfolio optimization pressure as immunotherapy volume displaces cytotoxic procurement in German hospital procurement coalitions.
- Hormonal Therapy:Progestin-based regimens serve progesterone receptor-positive recurrent cases where chemotherapy tolerance is limited, requiring no biomarker qualification.
- Radiation Therapy:External beam and brachytherapy approaches address locoregional disease, with reimbursement tied to facility-based technical fees rather than pharmaceutical pathways.
Leading the category by volume: Chemotherapy. Expanding most quickly: Immunotherapy.
Delivery Mode:
Route of administration determines site-of-care economics, cold chain infrastructure requirements, and patient adherence profiles. Intravenous delivery demands infusion center capacity; oral formulations shift cost structures toward pharmacy benefit management.
- Intravenous:Monoclonal antibodies and cytotoxic agents require specialized nursing protocols and adverse event monitoring capabilities. Medicare reimbursement differentials favor outpatient department settings in the United States, consolidating administration into accredited infusion centers.
- Oral:PARP inhibitors and hormonal agents enable home-based administration, though adherence monitoring and drug-drug interaction management fall to community oncology practices.
- Intraperitoneal:Regional chemotherapy delivery for advanced disease requires surgical oncology coordination, limiting adoption to academic medical centers.
- Topical:Minimal role in endometrial cancer, confined to palliative symptom management in terminal cases.
Highest reimbursement capture: Intravenous. Steepest patient preference shift: Oral.
End User:
Institutional purchasing power and clinical trial access determine therapy adoption velocity. Academic medical centers drive biomarker-qualified protocol development; community settings follow evidence translation with lag.
- Hospitals:Dominant setting for intravenous biologics and complex adverse event management, with formulary committees controlling access to combination regimens. UnitedHealthcare and similar payers steer patients toward accredited centers with documented immunotherapy capabilities.
- Specialty Clinics:Outpatient immunotherapy administration competes for volume where monitoring protocols have standardized, capturing margin from lower overhead structures.
- Research Institutions:Phase I-II trial enrollment concentrates at Memorial Sloan Kettering, Karolinska Institutet, and similar academic centers with integrated biobanking and translational platforms.
- Homecare:Limited to oral hormonal therapy and supportive care, with reimbursement fragmentation across pharmacy and medical benefit categories.
Commanding the largest patient volume: Hospitals. Fastest site-of-care migration: Specialty Clinics.
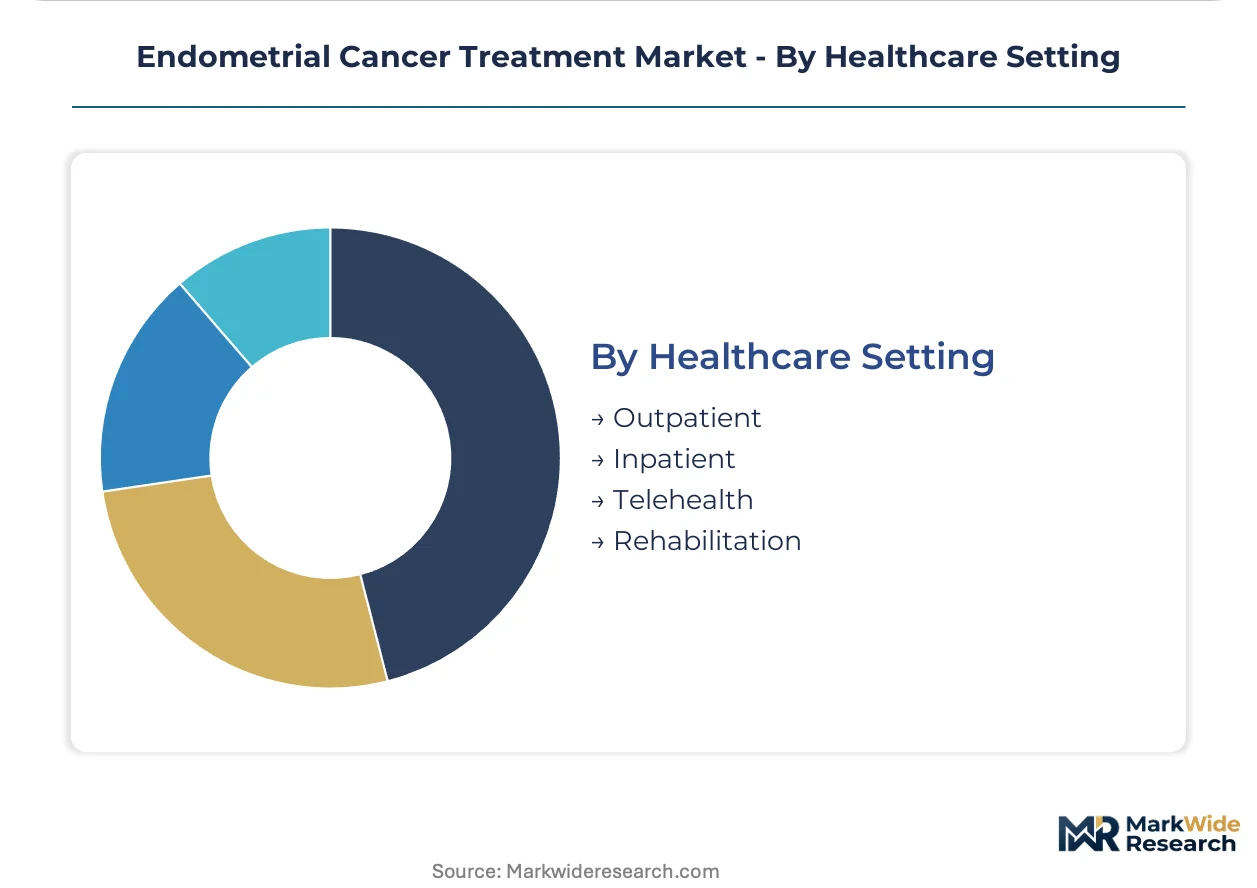
Healthcare Setting:
Care location determines staffing ratios, capital equipment requirements, and episode-based reimbursement calculations. Outpatient migration is reshaping real estate investment and nursing labor allocation across oncology networks.
- Outpatient:Consolidated infusion centers with standardized protocols displace general ward-based delivery, favored by Medicare reimbursement differentials and payer network design.
- Inpatient:Reserved for surgical cytoreduction, complications of advanced disease, and high-acuity adverse event management requiring continuous monitoring.
- Telehealth:Remote symptom monitoring and treatment planning expand access for rural populations, though physical examination limitations constrain adoption for disease assessment.
- Rehabilitation:Post-surgical and post-chemotherapy functional recovery services, typically bundled into episode payments rather than billed separately.
Capturing the dominant share: Outpatient. Gaining share fastest: Telehealth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge anchors the highest concentration of immuno-oncology development infrastructure for endometrial cancer therapies, with Memorial Sloan Kettering, Dana-Farber, and similar academic centers driving biomarker-qualified protocol adoption. FDA Breakthrough Therapy Designations and EMA adaptive pathways are compressing approval timelines across three regulatory jurisdictions. Precision medicine infrastructure and reimbursement frameworks for molecularly guided therapies concentrate demand in specific metropolitan clusters.
United States
Oncology hospital networks in Boston, New York, and Houston prioritize formulary inclusion for FDA-designated checkpoint inhibitors. The FDA Oncology Center's real-world evidence integration guidance enables accelerated approval for rare molecular subtypes. Flatiron Health and similar data platforms in New York are structuring retrospective cohorts for regulatory submission.
Germany
Hospital procurement coalitions in Berlin and Munich leverage EMA conditional marketing authorization to secure priority supply agreements for PI3K inhibitors. Germany's G-BA benefit assessment processes impose statutory health insurance coverage delays for combination immunotherapies. Heidelberg and Hamburg academic centers integrate automated immunohistochemistry platforms into routine gynecologic oncology pathways.
Japan
PMDA accelerated foreign drug approval harmonization reduces lag times for PD-1 inhibitors in gynecologic indications across Tokyo and Osaka medical centers. Academic medical centers in Kobe and Yokohama standardize tumor mutational burden thresholds for immunotherapy response prediction. Biomarker-driven reimbursement criteria determine access expansion for combination regimens.
Switzerland
Monoclonal antibody production capacity clusters in Basel and Zurich create supply concentration for checkpoint inhibitor dependent regimens. Swissmedic maintains alignment with EMA approval pathways while offering earlier access for academic trial enrollment. The Basel biopharmaceutical corridor houses fill-finish operations for multiple immuno-oncology franchises.
United Kingdom
NHS England's specialized commissioning frameworks concentrate endometrial cancer treatment delivery in London, Manchester, and Birmingham cancer centers. The MHRA's post-Brexit recognition routes with FDA and EMA maintain regulatory alignment for novel agent access. Cambridge and Oxford academic networks drive translational research partnerships with transatlantic biomarker consortia.
Endometrial Cancer Treatment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across biomarker qualification capabilities and companion diagnostic integration. Checkpoint inhibitor approval pathways have restructured competitive entry barriers around molecular testing infrastructure rather than traditional chemotherapeutic manufacturing scale. Three archetypes dominate: integrated diagnostic-treatment developers controlling companion testing pathways, immuno-oncology specialists leveraging pembrolizumab-class franchises, and PARP inhibitor anchors with sustained R&D intensity in gynecologic malignancies. Dominant competitive moves include academic-industry biomarker consortia formation and subcutaneous formulation development to shift site-of-care economics.
Within the integrated diagnostic-treatment tier, Roche Holding AG and AstraZeneca occupy positions defined by companion testing pathway control and PARP inhibitor development intensity respectively. Merck & Co., Inc. anchors the immuno-oncology specialist archetype through checkpoint inhibitor franchise dominance. These three companies exemplify how biomarker-linked therapeutic development concentrates competitive advantage in endometrial cancer treatment markets.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca |
| GlaxoSmithKline |
| Novartis AG |
| Roche Holding AG |
| Pfizer Inc. |
| Eisai Co., Ltd. |
| Bristol-Myers Squibb |
| Karyopharm Therapeutics Inc. |
| Others |
Supply Flow & Price Mechanics
Captive biologics manufacturing in Basel, Zurich, and Singapore anchors supply positioning for checkpoint inhibitor dependent regimens while concentrating pricing power with integrated diagnostic-treatment developers. This vertical integration into fill-finish operations and companion diagnostic control enables premium capture for biomarker-qualified therapies across oncology hospital networks.
Pricing Analysis
Value-based pricing tied to progression-free survival outcomes anchors reimbursement negotiations for PD-1 inhibitors in mismatch repair-deficient tumors. Pricing stratifies across premium, standard, and economy tiers based on biomarker qualification requirements and companion diagnostic bundling. Cost compression in chemotherapy generics intensifies as immunotherapy volume displaces cytotoxic procurement. Community oncology practices exhibit highest price sensitivity; academic medical centers with trial access demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics remain underdeveloped in secondary oncology centers across Southern and Eastern Europe, limiting site-of-care expansion. Monoclonal antibody production draws from Switzerland, Ireland, and Singapore, creating single-source vulnerability for fill-finish operations. Supply chain risk centers on cold chain infrastructure gaps for intravenous immunotherapy distribution. Distribution runs through specialized infusion centers with standardized nursing protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint inhibitors are displacing carboplatin-paclitaxel combinations as first-line standards, compressing development timelines and restructuring competitive entry barriers around biomarker qualification capabilities.
For Market Incumbents: To counter manufacturing concentration risk in Swiss and Irish biologics facilities, secure dual-source fill-finish agreements and deepen backward integration into automated immunohistochemistry platform development. Prioritize subcutaneous formulation R&D to shift site-of-care economics away from infusion center dependency. For New Entrants and Emerging Players: Digital-channel partnerships with Flatiron Health and similar oncology data platforms enable accelerated regulatory submission through real-world evidence integration. Target community oncology practices in the United States with oral PARP inhibitor programs, leveraging pharmacy benefit management pathways for formulary access. For Investors and Strategic Acquirers: Exit pathways concentrate in diagnostic-treatment integration plays controlling companion testing pathways for PIK3CA-mutated and TROP2-expressing tumors. Long-term viability favors developers with biomarker consortia partnerships spanning Memorial Sloan Kettering and Karolinska Institutet. Monitor FDA Oncology Center guidance evolution on external control arms as inflection signal for rare molecular subtype approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Convergence | Automated immunohistochemistry platforms for PD-L1 testing standardize biomarker workflows across academic medical centers. |
| Subcutaneous Formulation Development | Self-administered checkpoint inhibitor programs shift treatment delivery from infusion centers to home settings. |
| Academic-Industry Biomarker Consortia | Transatlantic partnerships between Memorial Sloan Kettering and Karolinska Institutet standardize tumor mutational burden thresholds. |
| Real-World Evidence Integration | FDA Oncology Center guidance on external control arms enables accelerated approval for rare molecular subtypes. |
| EMA Adaptive Pathway Engagement | Conditional marketing authorization frameworks enable earlier patient access to PI3K inhibitors and AKT pathway modulators. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this endometrial cancer treatment market analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation validated segment-level outputs.
Reconciliation of prescription volume data, reimbursement claim patterns, and manufacturer shipment records informed the analytical framework across the projection horizon. Segmentation dimensions encompassed treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derived from biomarker penetration curves and therapy adoption velocity in oncology hospital networks. Forecast inputs included FDA Breakthrough Therapy Designation timelines and EMA adaptive pathway enrollment rates.
The model holds under stable regulatory harmonization between FDA, EMA, and PMDA; deviation in reimbursement fragmentation or manufacturing disruption would shift access expansion trajectories. Practitioners should monitor evolving biomarker-driven reimbursement criteria and cold chain infrastructure investment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Global Plasma Therapeutics Market