
 Infertility Devices Market | 2026-2036
Infertility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Infertility Devices Market Foresight
Buyer concentration among fertility clinics is hardening as independent practices consolidate into multi-site networks and hospital-affiliated centers. CooperSurgical leverages its integrated portfolio spanning media, devices, and diagnostics to secure long-term supply contracts with these expanding clinic chains. Vitrolife anchors its position through specialized consumables for embryo culture and cryopreservation workflows. Thermo Fisher Scientific competes by extending its laboratory infrastructure reach into reproductive testing laboratories.
Infertility devices comprise engineered instrumentation and disposables designed to manipulate gametes, embryos, and reproductive tissues under controlled laboratory or clinical conditions, typically operating within temperature ranges of 37°C and requiring ISO 5 cleanroom equivalence for embryo handling. Their primary purpose centers on supporting fertilization, embryo development, implantation, and related diagnostic assessment in assisted reproduction programs. IVF systems generate the dominant revenue pool given their capital intensity and recurring media consumption, while genetic testing segments capture expanding margin contributions as preimplantation screening becomes standard protocol. Sperm retrieval devices occupy a mature niche with slower replacement cycles but stable procedural attachment rates.
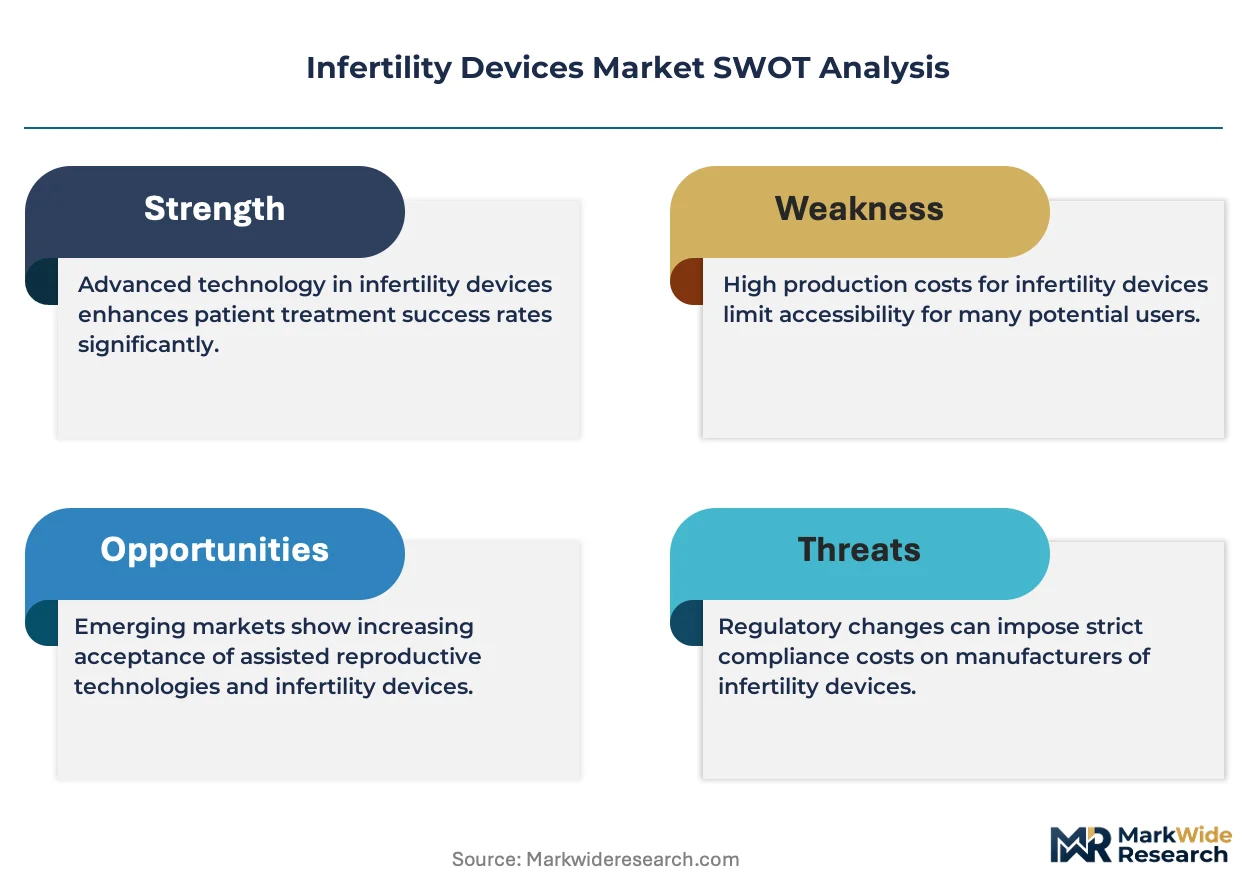
The FDA governs device classification and premarket pathways for infertility products in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements and notified body oversight across European markets. Japan's PMDA maintains distinct quality management system certifications that shape market access timelines for foreign manufacturers. Stakeholders must monitor evolving premarket submission requirements and reimbursement coding decisions that determine commercial viability in each major jurisdiction.
Market Dynamics
Consolidation among fertility clinic networks is compressing vendor margins while amplifying purchasing power, forcing device manufacturers to restructure contract terms around multi-year consumable commitments rather than standalone capital sales.
Growth Catalysts
- EU Medical Device Regulation:Stricter conformity assessments for implantable reproductive devices are accelerating replacement cycles as clinics upgrade to certified systems.
- Preimplantation genetic testing:Standardization of embryo screening protocols is expanding consumable volumes in high-throughput laboratory workflows.
- Japan and Germany:Reimbursement frameworks in these markets are institutionalizing assisted reproduction as covered care, stabilizing procurement budgets.
Market Restraints
- Specialized polymer and culture media inputs:Concentrated supply of medical-grade formulations creates cost volatility and qualification delays for secondary suppliers.
- Cleanroom infrastructure requirements:ISO 5 equivalence mandates for embryo handling impose capital barriers on new laboratory entrants.
- Notified body capacity constraints in Europe:Bottlenecks in EU MDR certification timelines extend product launch windows by 12-18 months.
Strategic Opportunities
- India's assisted reproduction sector:Underpenetrated clinic density relative to population need creates whitespace for affordable device platforms.
- Remote monitoring integration:Convergence of wearable hormone sensors with cloud-based cycle tracking opens direct-to-patient channels outside traditional fertility centers.
- US IRA fertility coverage provisions:Expanded insurance mandates for IVF services are unlocking employer-sponsored benefit programs as new procurement anchors.
Industry Challenges
- Embryologist training pipelines:Shortage of certified laboratory specialists constrains clinic expansion and device utilization rates.
- Legacy equipment interoperability:Integration of new digital embryo imaging systems with incumbent incubator platforms requires custom validation protocols.
- PMDA quality management certification:Foreign manufacturers face extended audit timelines for Japan market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infertility Devices Market |
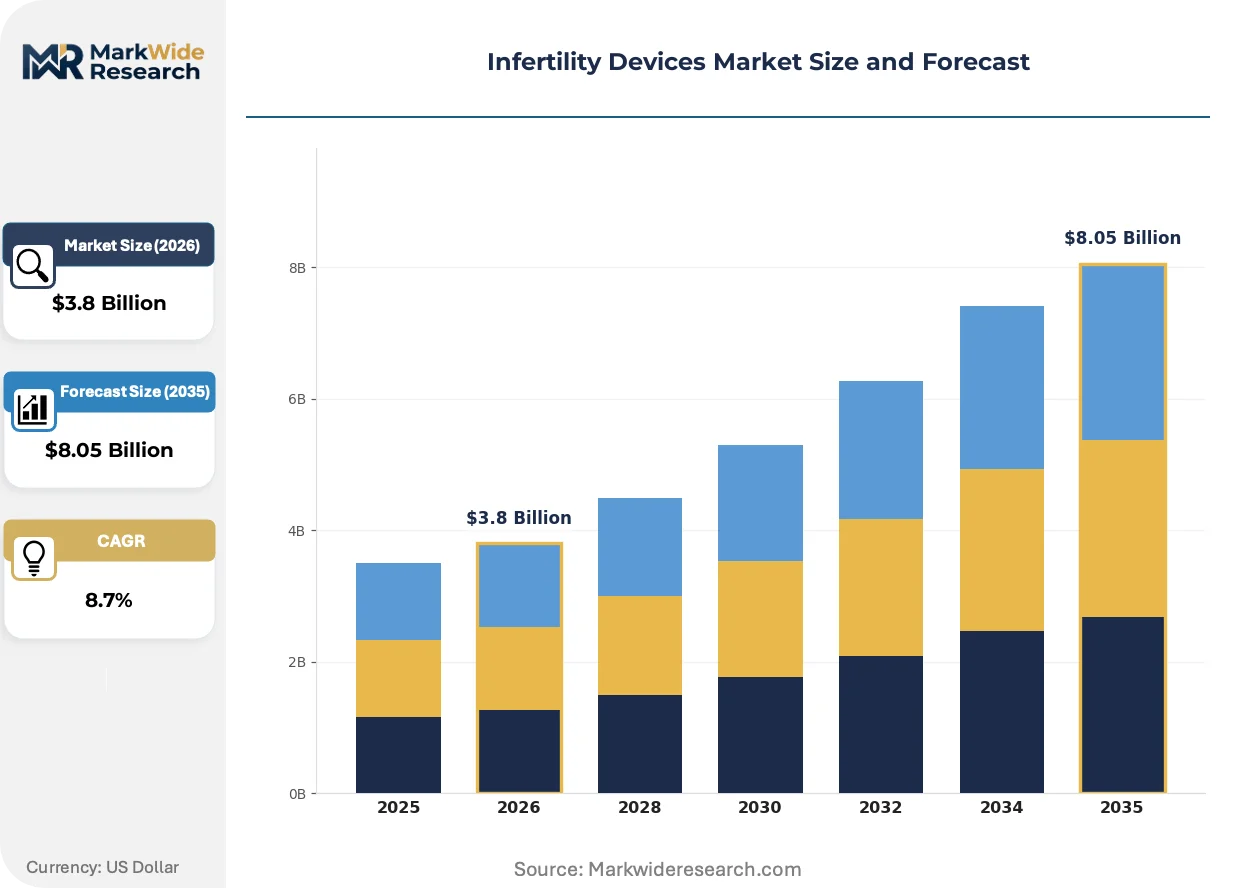
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: IVF Systems, Ovulation Monitors, Sperm Retrieval Devices, Insemination Devices Technology: Assisted Reproductive Technology, Hormone Therapy, Surgical Techniques, Genetic Testing End User: Fertility Clinics, Hospitals, Research Institutions, Home Users Application: IVF Treatments, Hormonal Therapies, Diagnostic Procedures, Sperm Analysis |
| Companies Covered | CooperSurgical Inc, Vitrolife AB, Cook Medical Inc, Thermo Fisher Scientific Inc, Merck KGaA, Hamilton Thorne Inc, Eppendorf AG, Rocket Medical Plc, Irvine Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infertility Devices Market Shifts & Advancements
Artificial intelligence is penetrating embryo assessment workflows, time-lapse incubation systems are displacing static culture environments, and clinic procurement committees are consolidating vendor relationships to secure volume pricing.
Time-lapse morphokinetic imaging is rewriting how laboratories select viable embryos for transfer. Multi-site fertility networks in the United States and Germany are adopting these systems at replacement-cycle pace. The technology is compressing reliance on subjective manual grading and enabling standardized decision protocols across distributed clinic operations.
The EU Medical Device Regulation's strengthened clinical evidence requirements are reshaping product development budgets. Manufacturers must now generate prospective data for Class IIb and III reproductive devices before CE marking. High-complexity embryo culture systems face the steepest compliance burden, with notified bodies demanding extended follow-up studies.
Buyer committees at consolidated clinic networks are unbundling after-sales service from capital equipment contracts. Independent service organizations are capturing maintenance revenue previously retained by original manufacturers. This pattern is most visible in the United States, where hospital-affiliated fertility centers leverage existing biomedical engineering infrastructure.
Infertility Devices Market Segmentation
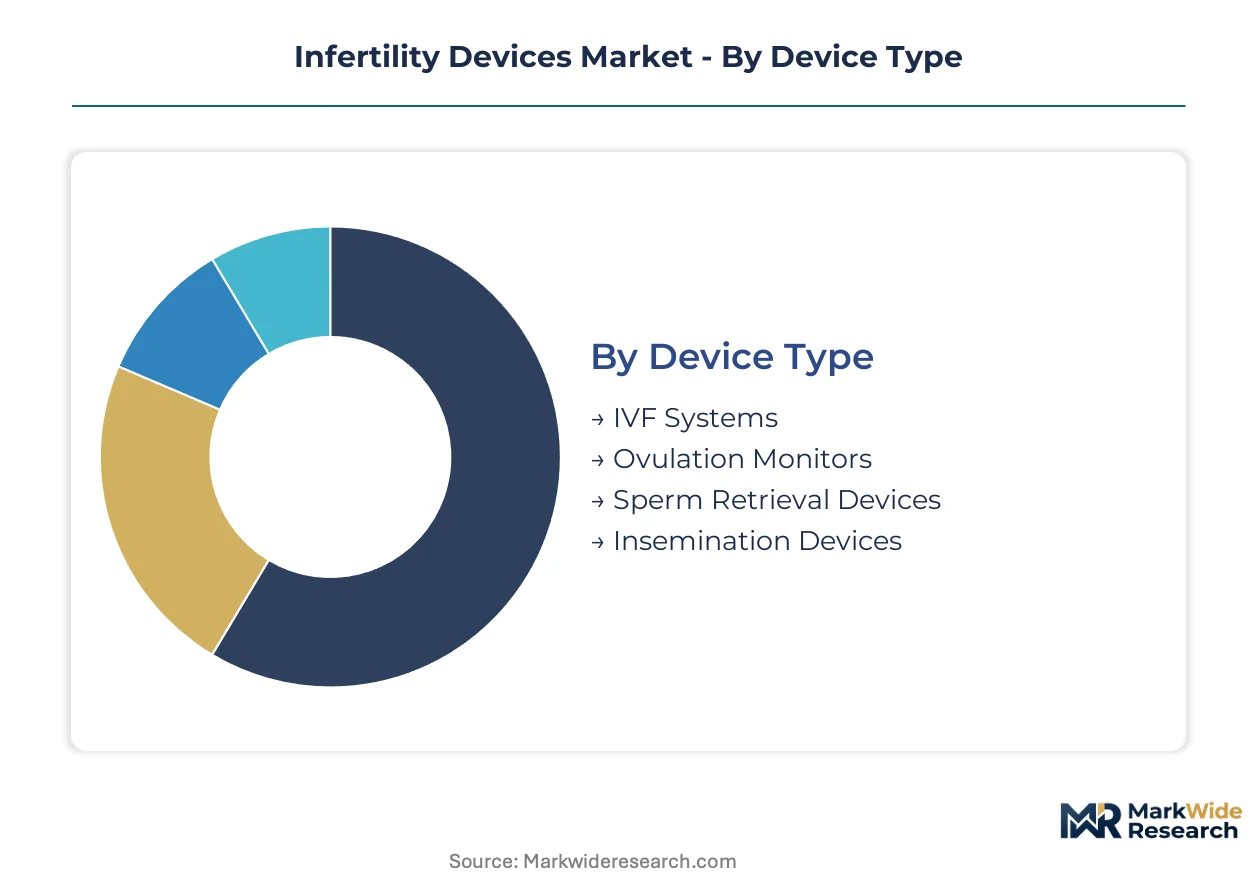
Infertility device procurement varies sharply by clinical setting and technical complexity. Capital equipment decisions at fertility networks diverge fundamentally from home-use monitoring purchases, while regulatory pathways split across implantable, active, and diagnostic categories.
Device Type:
Capital intensity separates segments most dramatically, with incubator platforms requiring seven-figure infrastructure commitments while disposables turn on consumable economics.
- IVF Systems:Multi-chamber incubators, micromanipulation workstations, and cryopreservation units operate at 37°C with ISO 5 cleanroom equivalence. Demand concentrates in United States and Germany where hospital-affiliated fertility centers consolidate procurement through multi-year service contracts.
- Ovulation Monitors:Wearable hormone sensors and connected cycle-tracking hardware penetrate direct-to-patient channels outside traditional clinical settings. Japan's reimbursement framework institutionalizes these as covered diagnostics, stabilizing procurement volumes for precision sensor manufacturers.
- Sperm Retrieval Devices:Surgical aspiration and electroejaculation systems occupy mature replacement cycles with stable procedural attachment rates.
- Insemination Devices:Intrauterine insemination catheters and specimen collection vessels operate at lower price points with commoditized supply chains.
IVF systems absorb the bulk of installed capacity; ovulation monitors are expanding most quickly.
Technology:
Margin structure distinguishes segments, with genetic testing commanding premium pricing while hormone therapy faces generic substitution pressure.
- Assisted Reproductive Technology:Embryo culture media, vitrification solutions, and time-lapse imaging systems require specialized polymer formulations and extended stability validation. EU Medical Device Regulation conformity assessments now demand prospective clinical evidence for Class IIb incubator platforms, extending development timelines.
- Genetic Testing:Preimplantation screening consumables and NGS workflows capture expanding margin contributions as embryo biopsy becomes standard protocol. United States fertility networks drive standardization of PGT-A and PGT-M testing menus.
- Hormone Therapy:Injectable gonadotropins and oral ovulation induction agents face biosimilar competition and concentrated pharmacy benefit management control.
- Surgical Techniques:Laparoscopic and hysteroscopic instrumentation for tubal and uterine pathology correction ties to general gynecology device supply chains.
Assisted reproductive technology commands the largest revenue pool; genetic testing shows the steepest margin expansion trajectory.
End User:
Customer concentration patterns reshape contract structures, with consolidated clinic networks extracting volume pricing unavailable to fragmented purchasers.
- Fertility Clinics:Multi-site networks in the United States and Germany now dominate procurement for capital equipment and high-volume consumables. These buyers unbundle after-sales service from equipment contracts, shifting maintenance revenue to independent service organizations.
- Hospitals:Academic medical centers leverage existing biomedical engineering infrastructure and capital budgeting processes for reproductive medicine program expansion.
- Research Institutions:Embryology laboratories and stem cell facilities purchase specialized culture platforms outside clinical regulatory pathways.
- Home Users:Direct-to-consumer hormone monitoring and cycle-tracking applications bypass traditional fertility center distribution.
Fertility clinics concentrate the majority of device procurement; home users are gaining share fastest in monitoring segments.
Application:
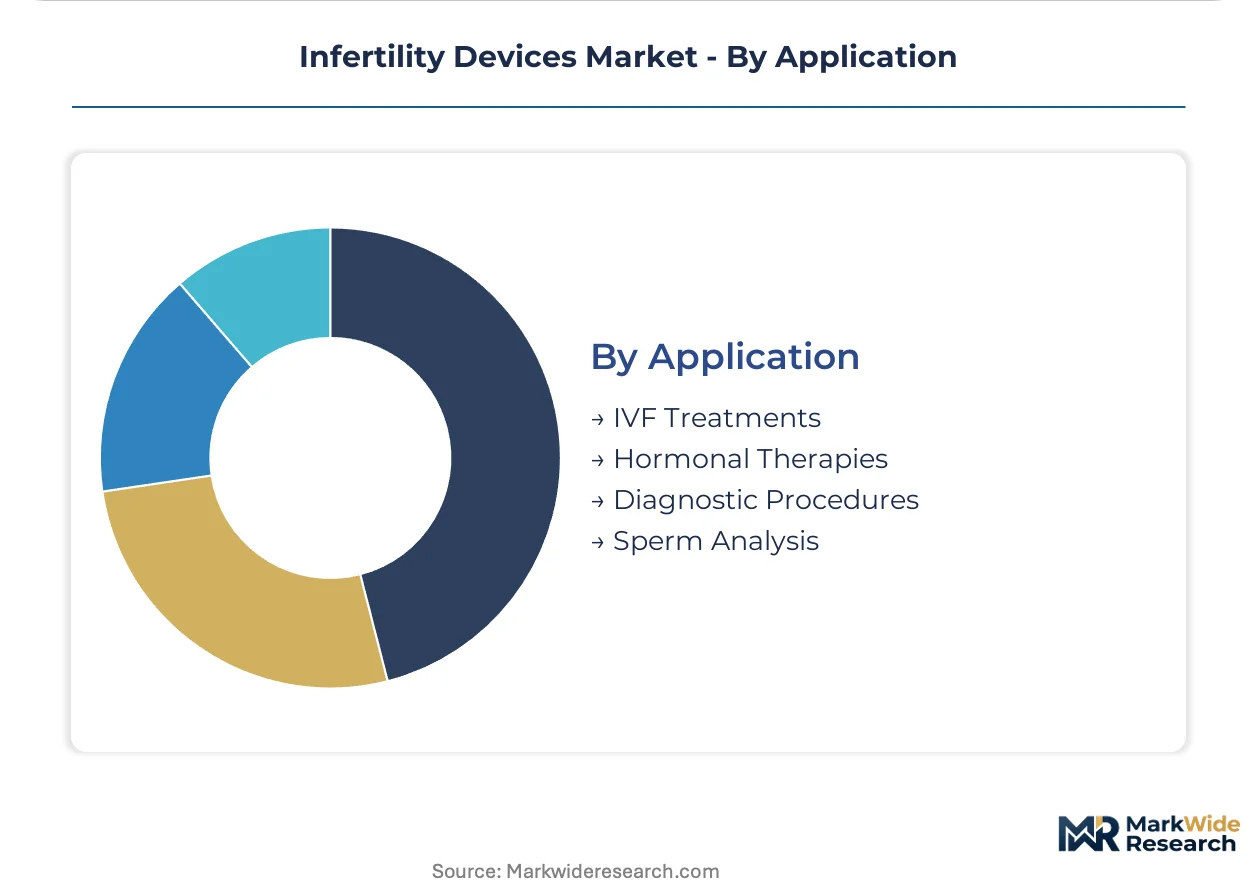
Procedure volume and reimbursement stability determine segment attractiveness, with IVF treatments anchoring commercial planning while diagnostic applications diversify revenue.
- IVF Treatments:Controlled ovarian stimulation, oocyte retrieval, fertilization, embryo culture, and transfer procedures generate recurring media consumption and instrument utilization. Japan's PMDA and Germany's notified bodies impose distinct quality management certifications that shape market access timelines.
- Hormonal Therapies:Ovulation induction protocols and luteal phase support drive pharmaceutical device combination purchases.
- Diagnostic Procedures:Hysterosalpingography, sonohysterography, and laparoscopic evaluation connect to broader gynecology imaging supply chains.
- Sperm Analysis:Computer-assisted semen analysis systems and manual counting chambers serve andrology laboratories with slower replacement cycles.
IVF treatments anchor the installed base; diagnostic procedures show the fastest volume growth as screening protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertility clinic procurement concentrates in the United States, Germany, and Japan, where reimbursement frameworks and specialized center networks are most developed. These three markets absorb the majority of capital equipment and high-volume consumable demand. Regulatory pathways diverge sharply across jurisdictions, shaping market access timelines and commercial viability.
United States
Hospital-affiliated fertility networks and multi-site clinic chains dominate equipment procurement through consolidated purchasing committees. The FDA governs device classification and premarket submission pathways, with 510(k) clearances and PMA processes determining launch timelines. The Boston and New York metropolitan corridors anchor the highest clinic density, with academic medical centers driving adoption of time-lapse imaging platforms.
Germany
Notified bodies under the EU Medical Device Regulation impose strengthened clinical evidence requirements for Class IIb and III reproductive devices. The country's statutory health insurance framework institutionalizes assisted reproduction as covered care, stabilizing procurement budgets. The Rhine-Ruhr and Bavarian clusters concentrate fertility center networks, with Munich and Düsseldorf serving as hubs for embryology laboratory expansion.
Japan
PMDA quality management system certifications create extended audit timelines for foreign manufacturers seeking market entry. The country's reimbursement framework covers ovulation monitors and IVF procedures, sustaining demand for precision sensor platforms. The Kanto region around Tokyo and the Kansai corridor anchored by Osaka concentrate the highest clinic density and capital investment.
India
Underpenetrated clinic density relative to population need creates whitespace for affordable device platforms and localized manufacturing partnerships. CDSCO regulates medical device imports and domestic production, with recent streamlining of registration pathways for reproductive technologies. Maharashtra and Karnataka host emerging fertility center networks in Mumbai and Bangalore, with Gujarat developing as a manufacturing base for disposables.
United Kingdom
The Human Fertilisation and Embryology Authority oversees clinic licensing and quality standards, with NHS funding constraints shaping private-pay demand. London and the Southeast corridor concentrate private fertility center investment and premium service positioning. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for device market access.
Infertility Devices Market Competitive Landscape
United States producers anchor the premium-tier equipment segment; European specialists hold dominant positions in consumables and culture media. The vendor base splits between integrated platform providers and focused component specialists, with consolidation pressure intensifying as clinic networks centralize procurement. Three archetypes define competitive positioning: diversified laboratory infrastructure conglomerates, reproductive-focused consumable specialists, and precision instrumentation developers. M&A activity targets consumable portfolio expansion, while strategic partnerships address interoperability requirements between imaging systems and incumbent incubator platforms.
Within the integrated platform tier, CooperSurgical Inc and Thermo Fisher Scientific Inc exemplify diversified laboratory infrastructure reach extending into reproductive medicine. Vitrolife AB occupies a specialized position representing focused consumable expertise in embryo culture workflows. These three anchors demonstrate how geographic origin and corporate structure shape strategic archetype alignment, with US-based conglomerates leveraging scale against European specialists emphasizing formulation depth.
| Leading Market Players |
|---|
| CooperSurgical Inc |
| Vitrolife AB |
| Cook Medical Inc |
| Thermo Fisher Scientific Inc |
| Merck KGaA |
| Hamilton Thorne Inc |
| Eppendorf AG |
| Rocket Medical Plc |
| Irvine Scientific |
| Others |
Supply & Pricing Matrix
Multi-site fertility network procurement committees now dictate pricing architecture across IVF systems and consumables, compressing vendor margins through consolidated volume contracts that bundle multi-year media commitments with capital equipment placements. This buyer concentration forces manufacturers to absorb service costs into upfront pricing while ceding maintenance revenue to independent service organizations.
Pricing Analysis
Capital equipment transactions sacrifice margin for installed base lock-in while recurring consumables generate sustainable returns. Three-tier pricing structure across premium, standard, and economy levels separates time-lapse imaging platforms from conventional incubators and refurbished secondary-market units. Cost compression in standard-tier consumables is intensifying because clinic networks are unbundling after-sales support and qualifying secondary media suppliers. Independent fertility practices exhibit highest price sensitivity; hospital-affiliated centers prioritize interoperability and service integration over unit cost.
Supply Chain Analysis
India's phased domestic manufacturing mandates for medical devices are redirecting disposable sourcing toward Gujarat-based production partnerships and away from concentrated European polymer formulations. Medical-grade culture media formulations, precision sensor components, and cryopreservation vessel polymers draw from Germany, Japan, and United States supply bases. Single-source vulnerability concentrates in specialized embryo culture medium formulations where secondary qualification cycles extend twelve to eighteen months. Distribution runs through authorized dealer networks serving consolidated clinic chains, with direct procurement emerging for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Time-lapse morphokinetic imaging systems are displacing static embryo assessment protocols, forcing incumbents and challengers to recalibrate R&D allocation toward AI-integrated platforms and away from legacy incubator architectures.
For Market Incumbents: Acquire independent service organization capabilities to recapture maintenance revenue streams that clinic networks have unbundled from capital contracts. Integrate backward into specialized polymer formulation production to insulate margin from medical-grade culture media supply volatility. Prioritize CE marking pathway investments for Class IIb incubator platforms ahead of EU MDR notified body bottlenecks. Lock in multi-year consumable commitments with expanding United States fertility networks before generic media suppliers achieve qualification. For New Entrants and Emerging Players: Standalone diagnostic laboratories in India's Maharashtra and Karnataka corridors present the most penetrable entry point for affordable embryo culture platforms priced below European premium tiers. Bypass capital equipment barriers by targeting remote patient monitoring through wearable hormone sensors and cloud-based cycle tracking applications outside traditional fertility center distribution. Pursue CDSCO registration pathway partnerships with established Indian distributors to accelerate market access timelines. For Investors and Strategic Acquirers: The window for entry favors consumable specialists with proprietary polymer formulations and extended stability validation protocols over capital equipment manufacturers facing replacement cycle compression. Focus acquisition screening on embryology laboratory software developers with AI embryo assessment algorithms compatible with incumbent incubator platforms. Monitor PMDA quality management certification completion rates among European manufacturers as signal of Japan market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend development timelines for Class IIb reproductive devices. |
| Hospital System Partnership | Academic medical centers in Boston and New York corridors drive time-lapse imaging adoption. |
| Software Companion Development | AI embryo assessment algorithms integrate with incumbent incubator platforms to bypass validation barriers. |
| Reimbursement Strategy | United States IRA fertility coverage provisions unlock employer-sponsored benefit procurement channels. |
| Backward Integration | In-house polymer formulation production insulates margin from medical-grade culture media supply volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this infertility devices market assessment. Primary interviews with embryology laboratory directors, fertility clinic procurement managers, biomedical engineers, and GPO contracts specialists combined with FDA 510(k) databases, EU MDR notified body registries, PMDA quality management certifications, and CDSCO import records. Bottom-up equipment installation tracking and top-down media consumption modeling were triangulated against reimbursement claims data.
Segmentation dimensions were modeled at device type, technology platform, end-user category, and application level across the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle compression, and consumable attach rates. Forecast inputs incorporated clinic network consolidation trajectories, EU MDR certification timeline bottlenecks, and Japan reimbursement framework stability.
Revisions become necessary when notified body capacity constraints extend beyond current estimates, when PMDA audit timelines for foreign manufacturers compress, or when United States fertility coverage mandates shift employer-sponsored benefit structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Breast Implant Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Enteral Stents Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Allografts Market
Medical Devices
Global Disability Devices Market
Medical Devices
Global Voice Prosthesis Devices Market