
 Epiglottitis Treatment Market | 2026-2036
Epiglottitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Epiglottitis Treatment Market Foresight
Hospital procurement channels is rewriting how epiglottitis therapeutics reach acute care settings, with group purchasing organizations consolidating formulary decisions across integrated delivery networks. Pfizer Inc. leverages its established hospital antibiotic portfolio to sustain access in emergency department formularies, while Merck & Co., Inc. anchors its position through broad-spectrum coverage options for polymicrobial infections. GlaxoSmithKline Plc. competes via differentiated respiratory combination therapies that address concurrent airway inflammation.
Epiglottitis treatment encompasses the pharmacological and procedural interventions targeting acute supraglottic inflammation, typically involving third-generation cephalosporins or ampicillin-sulbactam administered intravenously at weight-based dosing to achieve rapid tissue penetration and airway stabilization. The primary purpose centers on preventing fatal airway obstruction while eradicating inciting bacterial pathogens, principally Haemophilus influenzae type b and Streptococcus species. Antibiotics dominate current product type revenue given their non-negotiable role in empiric sepsis protocols, whereas intravenous administration routes capture the majority of value due to severity-mandated inpatient management. Emergency rooms represent the most concentrated care setting for initial presentation and stabilization, though urgent care centers are expanding their triage role for stable adult presentations.
FDA antimicrobial stewardship requirements and CDC vaccination schedule enforcement jointly constrain empiric prescribing patterns while sustaining prophylactic Hib immunoglobulin demand in under-vaccinated cohorts. The Joint Commission's airway safety standards further shape clinical training investments and emergency cart configuration across accredited facilities. Stakeholders must monitor evolving resistance profiles in Streptococcus pyogenes and track regional vaccination compliance gaps that alter pediatric versus adult case mix.
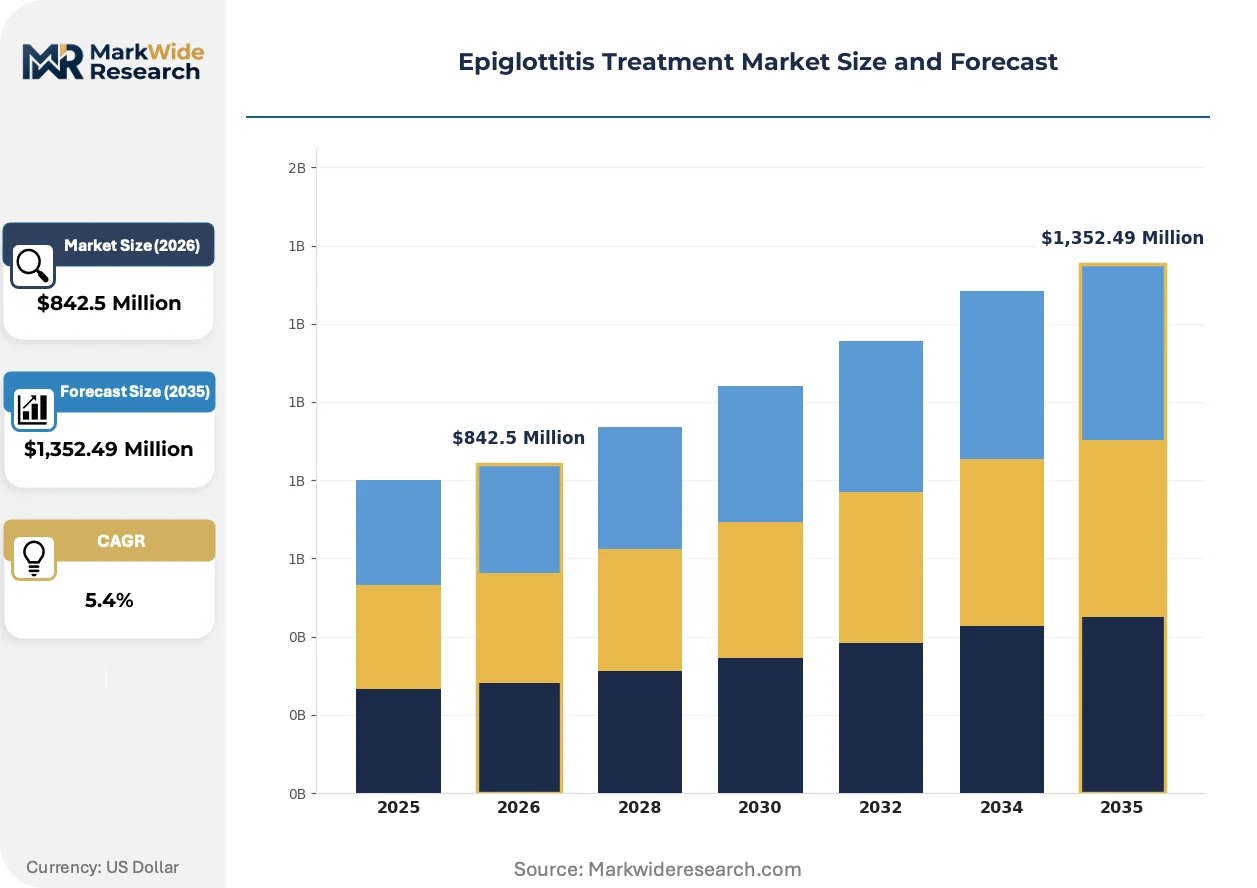
Market Dynamics
Hospital emergency departments are consolidating acute airway management protocols under antimicrobial stewardship mandates, forcing rapid formulary standardization across integrated delivery networks while Hib vaccination gaps sustain adult admission volumes.
Growth Catalysts
- CDC Vaccination Schedule Enforcement:Prophylactic Hib immunoglobulin protocols in under-vaccinated cohorts sustain demand for pediatric emergency interventions. The Joint Commission's airway safety standards drive clinical training investments across accredited facilities.
- Intravenous Cephalosporin Formulary Dominance:Third-generation cephalosporins remain non-negotiable in empiric sepsis protocols, cementing hospital procurement of weight-based dosing regimens for rapid tissue penetration.
- Polymicrobial Infection Prevalence:Streptococcus pyogenes and Haemophilus influenzae type b co-infections necessitate broad-spectrum coverage, expanding ampicillin-sulbactam utilization in intensive care settings.
Market Restraints
- Antimicrobial Resistance Surveillance:FDA's strengthened stewardship programs constrain empiric prescribing latitude, requiring culture-directed therapy that delays optimal antibiotic selection in critical airway cases.
- Generic Intravenous Antibiotic Commoditization:Patent expirations on core cephalosporin molecules compress manufacturer margins and reduce incentive for novel formulation development.
- Diagnostic Substitution by Laryngoscopy:Fiber-optic nasopharyngoscopy protocols in emergency settings reduce reliance on empiric clinical diagnosis, narrowing the window for presumptive antibiotic initiation.
Strategic Opportunities
- Urgent Care Triage Expansion:Stable adult presentations with milder epiglottitis grades are migrating to urgent care centers, creating demand for oral step-down therapy protocols and rapid airway assessment tools.
- Respiratory Combination Therapy Convergence:Integration of corticosteroid-nebulized delivery with antibiotic regimens addresses concurrent airway inflammation, opening differentiated product positioning.
- Regional Vaccination Compliance Gaps:Persistent Hib under-immunization in specific US counties sustains pediatric case incidence, supporting targeted prophylactic immunoglobulin distribution networks.
Industry Challenges
- Airway Management Skill Stratification:Emergency medicine residents demonstrate variable competency in awake fiber-optic intubation, the gold standard for epiglottitis airway control, necessitating simulation-based credentialing investments.
- Formulary Harmonization Across IDNs:Group purchasing organization consolidation demands standardized antibiotic protocols that may conflict with individualized patient severity stratification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epiglottitis Treatment Market |
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,352.49 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Corticosteroids, Antiseptics, Immunoglobulins Administration Route: Oral, Intravenous, Inhalation, Topical Patient Demographics: Pediatrics, Adults, Geriatrics, Immunocompromised Care Setting: Emergency Rooms, Outpatient Clinics, Hospitals, Urgent Care Centers |
| Companies Covered | Abbott, Merck & Co., Inc., AstraZeneca, Boehringer Ingelheim International GmbH, Pfizer Inc., Sanofi, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline Plc., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epiglottitis Treatment Market Shifts & Advancements
Acute airway management is undergoing protocol compression as point-of-care diagnostics and stewardship mandates reshape how emergency departments initiate empiric therapy.
Point-of-care rapid pathogen identification is collapsing the window between presentation and targeted antibiotic selection. Emergency departments in high-volume academic centers are deploying multiplex PCR panels for Haemophilus influenzae and Streptococcus species within thirty minutes of triage. This technology is collapsing the historical reliance on broad-spectrum empiric coverage, forcing manufacturers to demonstrate superior pharmacokinetic profiles against culture-confirmed pathogens rather than speculative polymicrobial spectra.
FDA antimicrobial stewardship requirements are mandating indication-specific justification for intravenous antibiotic continuation beyond forty-eight hours. Hospital pharmacy and therapeutics committees are responding by embedding automatic stop orders in electronic health record systems, triggering mandatory reassessment for step-down to oral agents. This regulatory pressure most acutely affects emergency department formularies, where clinicians must now document sepsis protocol adherence alongside airway severity stratification.
Integrated delivery networks are centralizing high-acuity airway cases to flagship emergency departments, concentrating epiglottitis volume in tertiary referral centers with twenty-four-hour otolaryngology and anesthesiology coverage. Smaller community hospitals are losing procedural experience and transferring stable cases before airway intervention, fragmenting the traditional emergency department revenue capture. This geographic demand rotation is most visible in the United States, where rural hospital closures and network consolidation have compressed the map of competent acute airway management.
Epiglottitis Treatment Market Segmentation
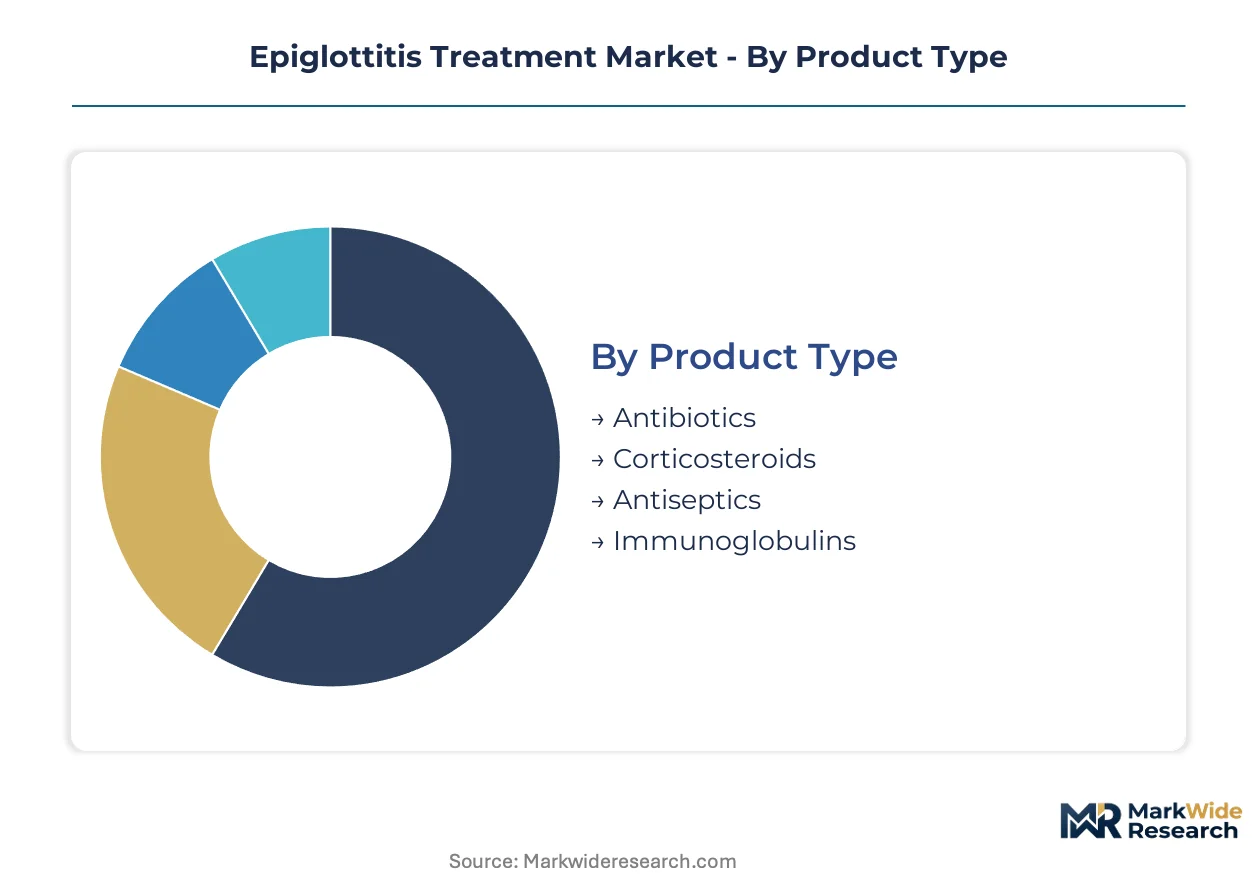
Treatment pathways for acute epiglottitis fragment across pharmacological classes, delivery modalities, and care settings. Segmentation reveals where procurement budgets concentrate and which patient cohorts sustain volume.
Product Type:
Mature intravenous antibiotics anchor hospital formularies while emerging immunoglobulin protocols address vaccination gaps in specific pediatric populations.
- Antibiotics:Third-generation cephalosporins and ampicillin-sulbactam dominate empiric sepsis protocols through rapid tissue penetration and broad-spectrum coverage against Haemophilus influenzae type b and Streptococcus species. Hospital emergency departments in the United States drive the majority of demand through weight-based intravenous dosing regimens mandated by severity.
- Corticosteroids:Systemic and nebulized formulations address concurrent airway inflammation alongside antimicrobial therapy, with academic medical centers piloting combination delivery protocols that reduce intubation rates. Demand concentrates in tertiary referral centers with twenty-four-hour otolaryngology coverage.
- Antiseptics:Adjunctive topical agents support airway decontamination during fiber-optic procedures, with limited standalone revenue contribution.
- Immunoglobulins:Prophylactic Hib immunoglobulin sustains niche demand in under-vaccinated cohorts, distributed through pediatric emergency networks in counties with compliance gaps.
Antibiotics handle the majority of throughput; immunoglobulins are gaining share fastest among prophylactic interventions.
Administration Route:
Cost tier stratification separates acute inpatient management from step-down and prophylactic modalities.
- Intravenous:Severity-mandated inpatient protocols cement this route's formulary dominance, with weight-based dosing achieving rapid tissue penetration in emergency departments. The Joint Commission's airway safety standards reinforce continuous infusion capabilities across accredited facilities.
- Oral:Step-down therapy following clinical stabilization supports urgent care center expansion for mild adult presentations. FDA antimicrobial stewardship programs accelerate transitions to oral agents after forty-eight hours of intravenous coverage.
- Inhalation:Nebulized corticosteroid delivery addresses localized airway inflammation with reduced systemic exposure, piloted in academic centers with advanced respiratory therapy infrastructure.
- Topical:Limited to procedural adjuncts during awake fiber-optic intubation, with minimal standalone market presence.
Intravenous administration captures the highest acuity spend; oral routes are expanding most quickly through urgent care channel development.
Patient Demographics:
Application urgency varies sharply across age and immune competence, with adult presentations now exceeding pediatric volumes in the United States.
- Adults:Hib vaccination success in pediatric populations has shifted case mix toward adult presentations, with Streptococcus pyogenes as the predominant pathogen. Emergency departments manage these cases through polymicrobial coverage protocols.
- Pediatrics:Residual incidence in under-vaccinated cohorts sustains pediatric emergency volume, concentrated in specific US counties with immunization compliance gaps. Prophylactic immunoglobulin protocols address exposure management.
- Geriatrics:Comorbidity burden extends inpatient length of stay, with aspiration risk complicating airway management decisions in this cohort.
- Immunocompromised:Atypical pathogen spectra and delayed presentation necessitate broader empiric coverage and prolonged intensive care monitoring.
Adult cases generate the majority of current emergency department encounters; pediatric segments retain targeted prophylactic product demand.
Care Setting:
Geographic consolidation of high-acuity capability is reshaping where epiglottitis revenue materializes across the United States.
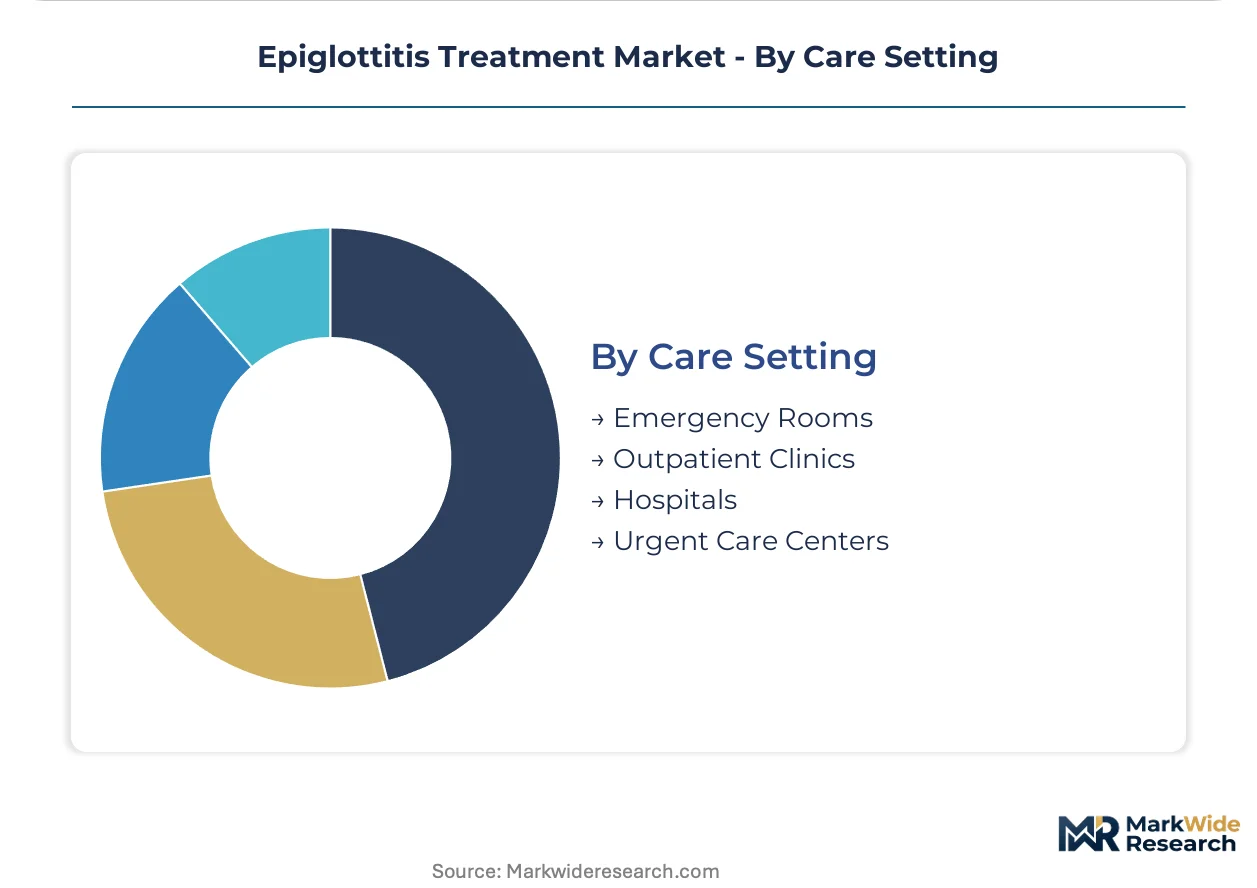
- Emergency Rooms:Initial presentation, airway stabilization, and empiric therapy initiation concentrate in hospital emergency departments with otolaryngology and anesthesiology coverage. Integrated delivery networks are centralizing these cases to flagship facilities.
- Hospitals:Inpatient admission for observation and completion of intravenous antibiotic courses sustains pharmacy and therapeutics committee formulary decisions. Rural hospital closures fragment traditional revenue capture.
- Urgent Care Centers:Stable adult presentations with milder epiglottitis grades are migrating to this channel, creating demand for oral step-down protocols and rapid airway assessment tools.
- Outpatient Clinics:Limited role in follow-up and vaccination compliance monitoring rather than acute intervention.
Emergency rooms capture the critical intervention window; urgent care centers are climbing the fastest as triage destinations for stable presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Hib vaccination gaps and adult presentation rates sustain premium inpatient admission volumes, while European markets face reimbursement compression under centralized procurement regimes.
United States
Hospital emergency departments anchor acute airway management volume, with integrated delivery networks consolidating high-acuity cases to flagship facilities. FDA antimicrobial stewardship mandates reshape empiric prescribing patterns across emergency formularies. Tertiary referral centers in Boston, New York, and Los Angeles concentrate the majority of awake fiber-optic intubation procedures.
Germany
EMA centralized procurement frameworks compress antibiotic margins while sustaining demand for broad-spectrum sepsis protocols in university hospitals. The country's national pharmaceutical regulator enforces strict indication-specific justification for intravenous continuation beyond forty-eight hours. Industrial pharmaceutical clusters in Baden-Württemberg and Bavaria manufacture core cephalosporin formulations for hospital distribution.
United Kingdom
NHS England's antimicrobial resistance strategy constrains empiric prescribing latitude in emergency departments while expanding rapid diagnostic deployment. NICE guidelines mandate culture-directed therapy initiation where point-of-care testing is available. London's academic medical centers pilot multiplex PCR panels for Haemophilus influenzae and Streptococcus species identification.
Japan
PMDA post-approval surveillance requirements sustain rigorous pharmacovigilance for intravenous antibiotic adverse events in elderly populations. METI industrial policy supports domestic manufacturing of critical antimicrobial agents. The Kanto region's emergency medicine networks concentrate pediatric epiglottitis cases in Tokyo's specialized children's hospitals.
India
CDSCO regulatory frameworks govern import and distribution of third-generation cephalosporins for hospital emergency use. The country's national pharmaceutical regulator mandates adverse event reporting for all intravenous antibiotic administrations. Maharashtra and Karnataka's tertiary care hospitals in Mumbai and Bangalore manage the majority of severe adult presentations requiring airway intervention.
Epiglottitis Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in antibiotic formulation and delivery technology. The epiglottitis treatment market structures around hospital formulary dominance, with procurement consolidation through group purchasing organizations creating tiered access barriers. Three archetypes define competitive positioning: diversified pharmaceutical conglomerates with established hospital antibiotic portfolios, respiratory-focused specialists with differentiated inflammation management capabilities, and generic manufacturers competing on intravenous cephalosporin commoditization. M&A activity targets point-of-care diagnostic capabilities, while strategic partnerships with integrated delivery networks secure formulary placement.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. anchor hospital emergency department access through broad-spectrum coverage portfolios, while GlaxoSmithKline Plc. occupies a differentiated position via respiratory combination therapy development. These three entities exemplify the platform-integrator archetype, leveraging scale and therapeutic breadth to maintain procurement channel presence.
| Leading Market Players |
|---|
| Abbott |
| Merck & Co., Inc. |
| AstraZeneca |
| Boehringer Ingelheim International GmbH |
| Pfizer Inc. |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline Plc. |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Air freight corridors linking Indian API manufacturing clusters to US hospital distribution centers concentrate cost dynamics for intravenous cephalosporin formulations, with temperature-controlled logistics premiums separating origin pricing from landed emergency department costs. This geographic asymmetry forces manufacturers to absorb cold-chain escalation or push differentiation through Joint Commission-certified packaging tiers.
Pricing Analysis
The customization-premium spread between weight-based dosing protocols and standard vial configurations anchors hospital formulary negotiations, with FDA-validated sterility assurance commanding measurable uplifts against commodity cephalosporin alternatives. Price differentiation hinges on antimicrobial stewardship compliance bundling and rapid-infusion compatibility certifications. Pricing pressure stems from generic intravenous antibiotic commoditization compressing manufacturer margins. Community hospital systems exhibit highest price sensitivity; tertiary academic centers prioritize pharmacokinetic performance over unit cost.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk for third-generation cephalosporin active pharmaceutical ingredients, with CDSCO export documentation delays amplifying inventory volatility. Manufacturing concentrates in Maharashtra and Gujarat for API synthesis, with sterile finishing distributed across Germany and the United States. Supply chain risk centers on single-source vulnerability for Hib immunoglobulin plasma fractionation. Distribution runs through group purchasing organization networks with consolidated formulary gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care diagnostic platform economics are displacing empiric prescribing workflows, with multiplex PCR integration creating interoperability dependencies between antibiotic manufacturers and emergency department technology vendors.
For Market Incumbents: Harden hospital formulary positions through antimicrobial stewardship compliance bundling that embeds automatic stop-order protocols within electronic health record architectures. Deepen backward integration into sterile cephalosporin finishing capacity in Baden-Württemberg manufacturing clusters to offset Indian API tariff exposure. Counter generic commoditization threat with pharmacokinetic differentiation validated against culture-directed therapy outcomes. For New Entrants and Emerging Players: Urgent care center oral step-down protocols for stable adult epiglottitis presentations represent the most penetrable entry point, with corticosteroid-antibiotic combination formulations enabling differentiated positioning against intravenous-centric incumbents. Target counties with persistent Hib vaccination compliance gaps for prophylactic immunoglobulin distribution partnerships. Pursue group purchasing organization carve-out contracts for rapid diagnostic co-development rather than standalone antibiotic entry. For Investors and Strategic Acquirers: FDA's strengthened antimicrobial stewardship program mandates reshape the acquisition landscape toward point-of-care diagnostic capabilities with emergency department workflow integration. Long-term viability favors platform plays spanning pathogen identification through targeted therapy selection over standalone pharmaceutical assets. Monitor multiplex PCR panel adoption rates in high-volume academic emergency departments as the critical inflection signal for antibiotic manufacturer margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostic Integration | Multiplex PCR deployment in emergency departments collapses empiric prescribing windows and reshapes antibiotic procurement criteria. |
| Antimicrobial Stewardship Compliance Bundling | FDA-mandated automatic stop-order protocols embedded in EHR systems create formulary stickiness for compliant manufacturers. |
| Regional Immunoglobulin Distribution Networks | Targeted prophylactic Hib immunoglobulin channels in under-vaccinated US counties sustain niche pediatric demand. |
| Respiratory Combination Therapy Development | Corticosteroid-nebulized delivery integration with antibiotic regimens addresses concurrent airway inflammation in tertiary centers. |
| Backward Integration into Sterile Finishing | Captive cephalosporin manufacturing in EMA-regulated clusters mitigates tariff exposure and supply concentration risk. |
Research Methodology
The analysis maps intravenous antibiotic formulations, point-of-care diagnostics, and prophylactic immunoglobulin distribution networks, each validated through emergency medicine physicians, hospital pharmacy and therapeutics committee chairs, group purchasing organization contract managers, and pediatric infectious disease specialists. Primary fieldwork combined with secondary validation from FDA antimicrobial stewardship guidance documents, CDC vaccination compliance surveillance, hospital procurement databases, and Joint Commission accreditation records established baseline market sizing. Bottom-up demand modeling across administration routes and patient demographics triangulated against top-down pharmaceutical manufacturer revenue attribution.
Assumptions held fixed include current FDA stewardship enforcement intensity and Hib vaccination schedule adherence trajectories, while variables tested encompass point-of-care diagnostic adoption velocity and rural hospital closure rates. The analytical framework segments by product type, administration route, patient demographics, and care setting across the projection horizon. CAGRs derived from log-linear trend extrapolation moderated by antimicrobial resistance surveillance data and formulary standardization patterns within integrated delivery networks. Modeled inputs incorporated Streptococcus pyogenes resistance profile evolution and urgent care center triage capacity expansion.
Stress conditions across generic antibiotic pricing compression, diagnostic substitution acceleration, and regional vaccination compliance volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and hospital consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Scabies Treatment Market