
 Global Medical Radiation Shielding Market | 2026-2036
Global Medical Radiation Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Radiation Shielding Market Foresight
Multi-source procurement for radiation attenuation materials is broadening as hospital systems diversify vendor relationships beyond legacy lead suppliers. ETS-Lindgren leverages its electromagnetic compatibility heritage to extend into diagnostic imaging shielding. NELCO anchors North American project-based contracts for vault construction and modular shielding systems. MarShield specializes in custom-fabricated lead and lead-free barriers for veterinary and dental clinic installations.
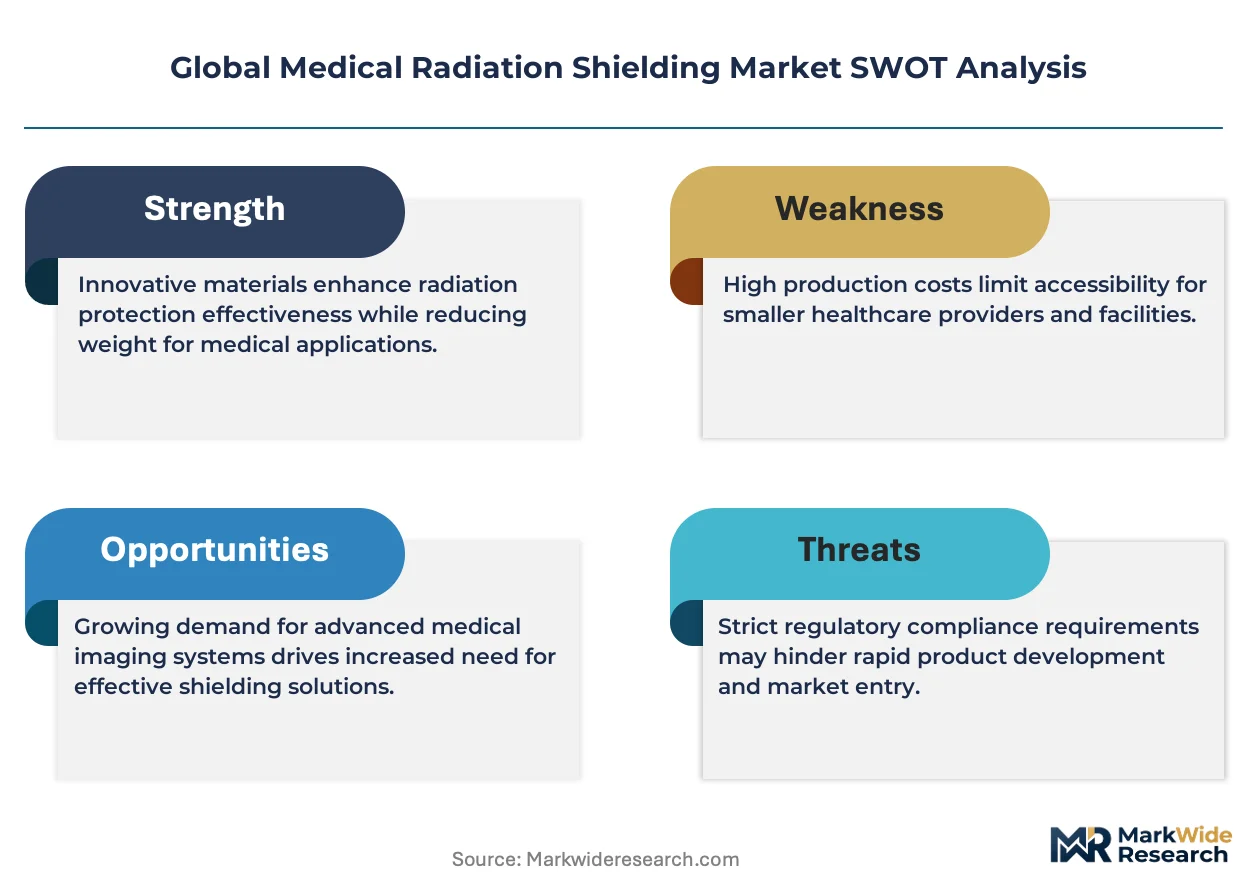
Medical radiation shielding encompasses barriers, garments, and architectural elements engineered to attenuate ionizing radiation exposure in clinical environments, typically incorporating lead, tungsten, or bismuth composites at specified thicknesses measured in half-value layers. The primary commercial purpose centers on protecting healthcare workers, patients, and adjacent populations from stochastic and deterministic radiation effects during diagnostic and therapeutic procedures. Lead-free shields represent the fastest-expanding product category as facilities phase out toxic materials under REACH and OSHA hazard communication mandates. Diagnostic radiology applications command the largest installed base, while interventional radiology generates premium pricing due to procedural intensity and prolonged staff exposure times. Fixed shield installations dominate capital expenditure budgets, though mobile shields gain traction in hybrid operating rooms requiring rapid reconfiguration.
FDA 21 CFR Part 1020 governs diagnostic x-ray equipment performance and leakage limits in the United States, while the EU MDR reclassifies certain shielding garments as Class I medical devices with heightened conformity requirements. ECHA REACH restrictions on lead compounds accelerate material substitution toward tungsten-polymer and bismuth-silicate formulations across European manufacturing. ISO 13485 quality management systems increasingly serve as de facto market access prerequisites for shielding vendors supplying hospital procurement consortiums. Stakeholders must monitor evolving alloy raw material costs and regulatory substance restrictions when selecting between lead-based legacy supply chains and next-generation attenuation platforms.
Market Dynamics
Material substitution away from lead-based attenuation compounds is compressing legacy supply chains while forcing capital retooling across European and North American manufacturing bases. REACH substance restrictions and OSHA hazard communication mandates are accelerating tungsten-polymer and bismuth-silicate adoption timelines.
Growth Catalysts
- EU MDR reclassification:Shielding garments now face Class I medical device conformity requirements, creating certified product premiums and formalizing quality barriers that favor incumbent manufacturers with ISO 13485 systems.
- Interventional radiology procedural intensity:Prolonged fluoroscopy exposure times in cardiac catheterization and electrophysiology suites drive repeat purchasing of mobile shields and personnel protective equipment.
- German hospital network consolidation:MAVIG GmbH and NELCO anchor regional supply chains serving centralized procurement frameworks across Bavaria and North Rhine-Westphalia.
Market Restraints
- Tungsten raw material volatility:Concentrated mining operations in China and Russia expose polymer-composite shielding margins to geopolitical supply disruptions and export quota fluctuations.
- Lead waste disposal liability:EPA RCRA hazardous waste regulations impose cradle-to-grave tracking costs on decommissioned radiology vaults and retired protective garments.
- Attenuation performance gaps:Lead-free alternatives at equivalent half-value layer specifications require 15-30% greater material thickness, increasing weight and ergonomic burden for mobile applications.
Strategic Opportunities
- Veterinary diagnostic imaging:Companion animal CT and dental radiology installations in the United States and United Kingdom remain undersupplied relative to human healthcare saturation levels.
- Hybrid operating room shielding:Rapidly reconfigurable mobile barrier systems address surgical workflow demands in Japan and South Korea where multi-disciplinary suite utilization rates exceed 80%.
- ECHA REACH authorization sunset dates:Accelerated lead compound phase-out timelines create captive conversion demand for certified alternative attenuation platforms through 2030.
Industry Challenges
- Radiation safety officer certification bottlenecks:Qualified personnel shortages delay commissioning of new interventional suites in Brazil and Mexico despite installed equipment capacity.
- Vault construction lead times:Modular shielding system integration with existing HVAC and electrical infrastructure extends project timelines 4-6 months beyond equipment delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Radiation Shielding Market |
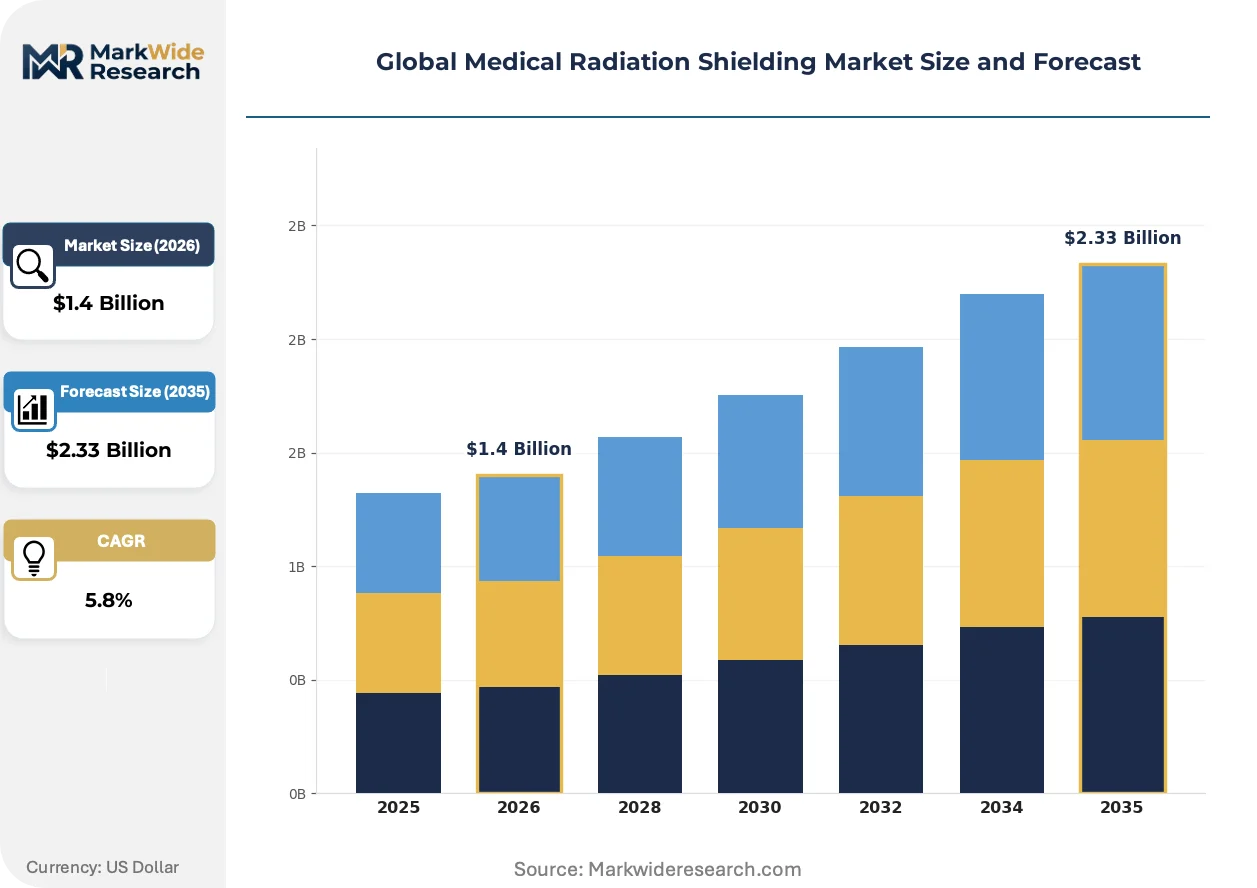
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
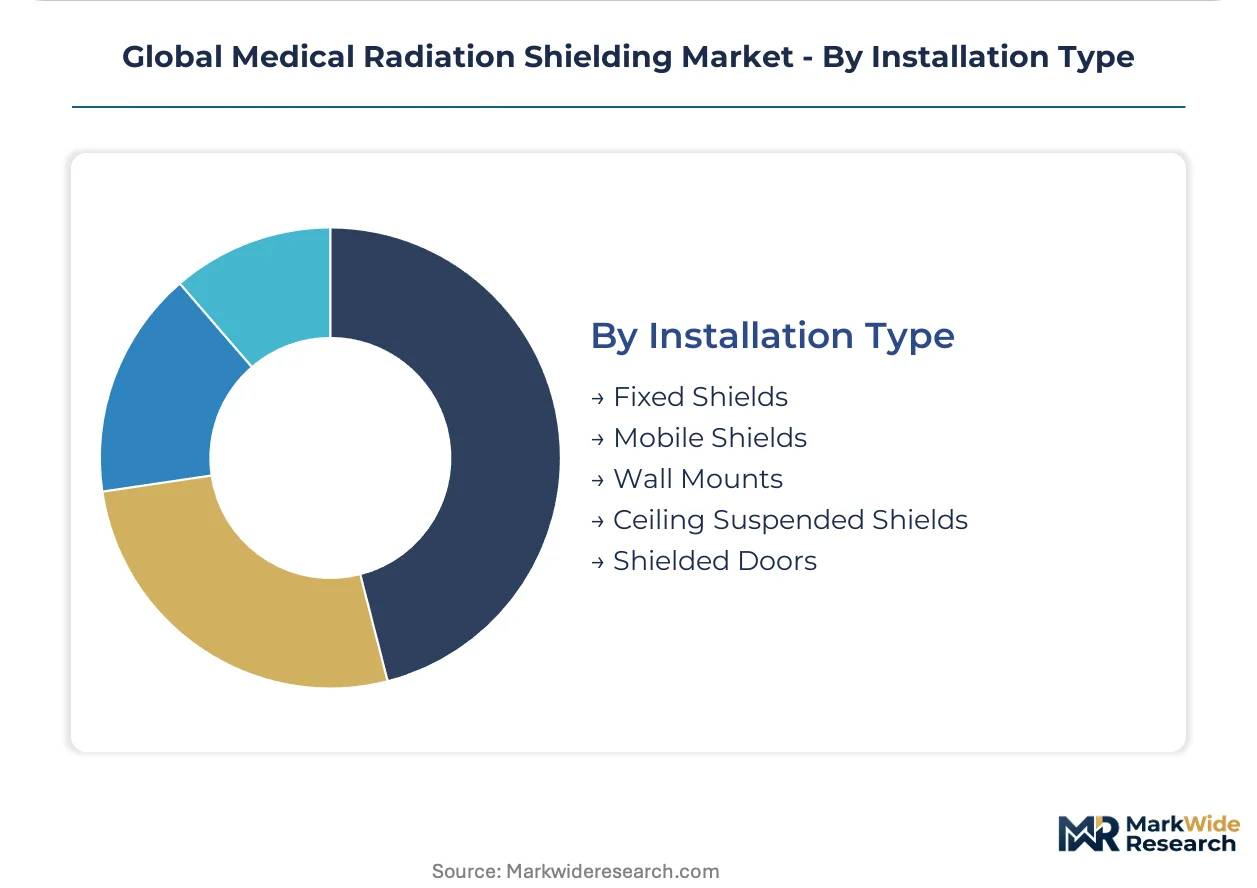
| Segmentation | Product Type: Lead Aprons, Thyroid Collars, Lead Glasses, Protective Curtains, Lead-Free Shields Application: Diagnostic Radiology, Interventional Radiology, Nuclear Medicine, Radiotherapy, Dental Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Dental Clinics, Veterinary Clinics Installation Type: Fixed Shields, Mobile Shields, Wall Mounts, Ceiling Suspended Shields, Shielded Doors |
| Companies Covered | ETS-Lindgren, Radiation Protection Products, Inc., Gaven Industries Inc., NELCO, MarShield, Veritas Medical Solutions LLC, RAY-BAR Engineering Corp., Amray Group, MAVIG GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Radiation Shielding Market Shifts & Advancements
Attenuation material science is bifurcating between high-performance heavy metal composites and lightweight polymer matrices, with manufacturing process innovation determining competitive positioning. Regulatory substance restrictions and end-user ergonomic demands are converging to reshape product development priorities.
Tungsten-polymer nanocomposites are electrifying portable shielding applications through injection-molded manufacturing that achieves consistent dispersion at 50-60% loading ratios. Interventional cardiologists and electrophysiologists in Germany and the United States are adopting these garments for procedures exceeding two hours fluoroscopy time. The technology is electrifying premium pricing tiers while compressing traditional lead apron refurbishment cycles.
ECHA REACH Annex XVII restrictions on lead compounds are forcing reformulation commitments across European manufacturing bases with 2025-2027 sunset enforcement windows. Industrial consequence includes accelerated R&D allocation toward bismuth-silicate and rare-earth oxide alternatives with comparable photon attenuation coefficients. Shielding garment assemblers in Italy and Spain face compressed certification timelines under notified body backlogs for EU MDR technical documentation review.
Hospital procurement consortiums are consolidating vendor relationships from fragmented local fabricators toward integrated shielding system providers with in-house testing laboratories. Group purchasing organizations in France and the Netherlands are unbundling after-sales attenuation verification services from initial capital contracts. This concentration is most visible in academic medical centers where centralized biomedical engineering departments demand single-source accountability for vault design, installation, and annual leakage survey compliance.
Global Medical Radiation Shielding Market Segmentation
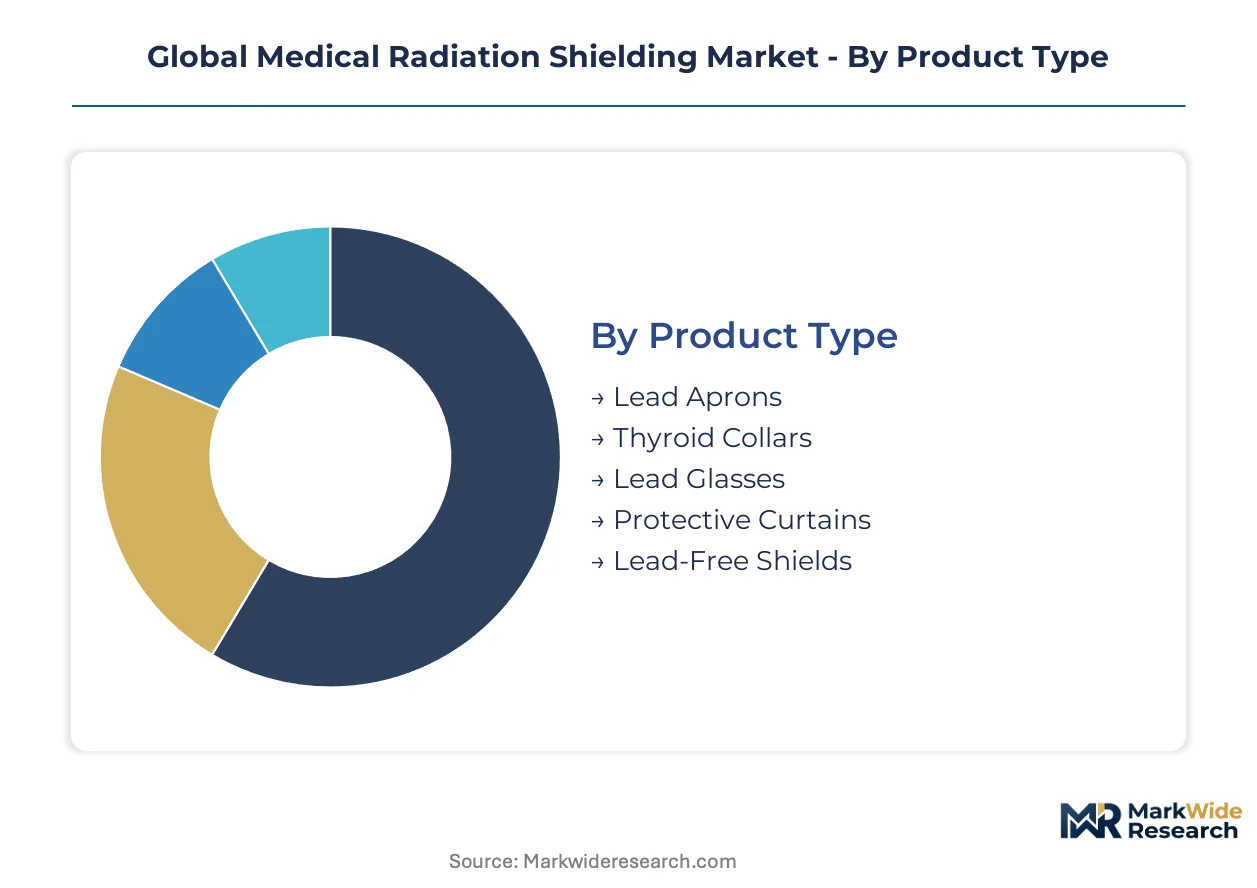
Medical radiation shielding segments carry divergent regulatory loads that reshape vendor economics. EU MDR Class I reclassification for garments and FDA 21 CFR Part 1020 equipment standards create tiered compliance costs across product categories.
Product Type:
Lead-free shields and lead aprons face the steepest certification burden under EU MDR and REACH substance restrictions, while thyroid collars and protective curtains navigate lighter conformity pathways.
- Lead Aprons:Traditional lead-vinyl composite garments dominate refurbishment cycles in United States hospital systems. Prolonged fluoroscopy procedures in German interventional suites sustain replacement demand despite ergonomic limitations.
- Lead-Free Shields:Tungsten-polymer nanocomposites achieve 50-60% loading ratios through injection molding. Bavarian cardiac catheterization labs in Germany are converting apron fleets ahead of ECHA REACH sunset enforcement.
- Thyroid Collars:Neck-specific attenuation accessories attach to primary garments in Japanese radiation safety protocols.
- Lead Glasses:Eye protection with 0.75mm lead-equivalent lenses serves interventional staff in United States academic medical centers.
- Protective Curtains:Hanging barriers suspend from ceiling tracks in United Kingdom hybrid operating rooms.
Leading the category by volume: Lead Aprons. Expanding most quickly: Lead-Free Shields.
Application:
Capital intensity and procedural duration separate high-margin interventional radiology from high-volume diagnostic radiology procurement patterns.
- Diagnostic Radiology:Chest and extremity x-ray suites generate baseline shielding demand across mid-tier hospital networks. United States outpatient imaging chains standardize on modular vault configurations with rapid installation timelines.
- Interventional Radiology:Cardiac catheterization and electrophysiology procedures demand mobile shields and personnel garments for exposures exceeding two hours. Premium pricing reflects procedural intensity in South Korean multi-disciplinary suites.
- Nuclear Medicine:PET-CT and SPECT facilities require high-attenuation barriers for isotope handling in French university hospitals.
- Radiotherapy:Linear accelerator vaults incorporate concrete and steel composite shielding in German oncology centers.
- Dental Imaging:Panoramic and cone-beam CT installations in United Kingdom private practices drive compact barrier demand.
Highest revenue concentration: Interventional Radiology. Steepest expansion trajectory: Dental Imaging.
End User:
Procurement sophistication varies from centralized biomedical engineering departments in hospital networks to fragmented purchasing in independent veterinary practices.
- Hospitals:Academic medical centers in the Netherlands consolidate vendor relationships through group purchasing organizations demanding single-source accountability for vault design and annual leakage surveys.
- Diagnostic Centers:Outpatient imaging chains in the United States prioritize rapid-install modular shielding to minimize revenue disruption during suite upgrades.
- Research Institutions:Preclinical imaging facilities in Switzerland require specialized attenuation for small-anid PET and SPECT systems.
- Dental Clinics:Independent practices in Spain source custom-fabricated barriers from regional fabricators with shorter lead times.
- Veterinary Clinics:Companion animal CT installations in the United Kingdom remain undersupplied relative to human healthcare saturation.
Dominant procurement volume: Hospitals. Gaining share fastest: Veterinary Clinics.
Installation Type:
Fixed infrastructure commitments contrast with mobile systems that address workflow reconfiguration demands in hybrid surgical environments.
- Fixed Shields:Concrete and lead-lined vault walls anchor capital expenditure budgets in German hospital construction projects. Integration with HVAC and electrical infrastructure extends commissioning timelines.
- Mobile Shields:Rapidly repositionable barriers on castor systems serve Japan's hybrid operating rooms where multi-disciplinary utilization exceeds 80%. Tungsten-polymer composites reduce transport burden.
- Wall Mounts:Permanent panel installations protect control areas in United States diagnostic centers.
- Ceiling Suspended Shields:Overhead tracking systems enable flexible positioning in interventional suites.
- Shielded Doors:Lead-lined entry systems with automated closers seal radiotherapy bunkers in French oncology facilities.
Top category by installed value: Fixed Shields. Climbing the fastest: Mobile Shields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten mining concentration in China and Russia shapes raw material security calculations for shielding manufacturers worldwide. German industrial clusters anchor European conversion capacity. United States hospital procurement drives premium product specifications.
United States
Academic medical centers in Boston and Houston consolidate vendor relationships through group purchasing organizations demanding single-source accountability. FDA 21 CFR Part 1020 governs diagnostic x-ray equipment performance and leakage limits. Outpatient imaging chains in Texas and Florida standardize on modular vault configurations with rapid installation timelines.
Germany
Interventional cardiology suites in Munich and Berlin sustain replacement demand for mobile shields despite ergonomic limitations. EU MDR reclassifies shielding garments as Class I medical devices with heightened conformity requirements. Bavarian cardiac catheterization labs are converting apron fleets ahead of ECHA REACH sunset enforcement.
China
Domestic PET-CT installation growth in Shanghai and Beijing generates demand for high-attenuation barriers. The national pharmaceutical regulator enforces equipment registration for radiation-emitting devices. Tungsten concentrate processing in Jiangxi Province supplies polymer-composite shielding manufacturers.
Japan
Hybrid operating rooms in Tokyo and Osaka achieve multi-disciplinary utilization rates exceeding 80 percent. METI oversees industrial standards for medical device manufacturing. Rapidly reconfigurable mobile barrier systems address surgical workflow demands in Kansai region facilities.
United Kingdom
Private dental practices in London and Manchester source custom-fabricated barriers from regional fabricators. Health and Safety Executive regulations govern occupational radiation exposure in clinical settings. Companion animal CT installations in Southeast England remain undersupplied relative to human healthcare saturation.
Global Medical Radiation Shielding Market Competitive Landscape
Global majors compete with regional champions across certification capabilities and project execution scale. The vendor base spans integrated shielding system providers, specialized garment assemblers, and regional vault contractors. Three archetypes dominate: electromagnetic heritage companies extending into diagnostic imaging, project-based construction specialists, and custom fabrication shops serving veterinary and dental niches. Competitive moves concentrate on ISO 13485 quality system implementation and strategic partnerships with hospital procurement consortiums.
Among North American project-based specialists, NELCO anchors large-scale vault construction and modular shielding systems. MAVIG GmbH represents German engineering-focused manufacturing with regional supply chain concentration. ETS-Lindgren occupies a position leveraging electromagnetic compatibility heritage into diagnostic imaging shielding applications. MarShield exemplifies the custom-fabrication archetype serving veterinary and dental clinic installations.
| Leading Market Players |
|---|
| ETS-Lindgren |
| Radiation Protection Products, Inc. |
| Gaven Industries Inc. |
| NELCO |
| MarShield |
| Veritas Medical Solutions LLC |
| RAY-BAR Engineering Corp. |
| Amray Group |
| MAVIG GmbH |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Germany and Italy anchor regional supply chains, converting legacy lead-based production toward tungsten-polymer alternatives while maintaining pricing discipline through ISO 13485 certification premiums. Their concentrated ownership structures enable long-term capital commitments that transnational conglomerates struggle to match, insulating margin structures against raw material volatility.
Pricing Analysis
Warranty and attenuation verification services are increasingly unbundled from initial capital contracts, particularly in Dutch and French group purchasing organization frameworks. Three-tier pricing structure across premium, standard, and economy levels separates certified lead-free garments with EU MDR technical documentation from refurbished lead aprons and unbranded regional imports. Pricing pressure stems from ECHA REACH compliance costs compressing margins for legacy lead assemblers without certified alternative platforms. Price sensitivity concentrates in independent veterinary and dental practices, while academic medical centers absorb premium tiers for single-source accountability.
Supply Chain Analysis
ISO 13485 quality system certification gates market access for garment assemblers supplying hospital procurement consortiums, creating formal barriers that favor incumbent manufacturers over regional fabricators. Tungsten concentrate processing in Jiangxi Province, China, and secondary refining in Russia feed polymer-composite shielding manufacturers in Germany and the United States. Bismuth mining in Peru and rare-earth oxide processing in Inner Mongolia provide alternative attenuation material streams. Single-source vulnerability in Chinese tungsten supply exposes margins to export quota fluctuations. Distribution runs through integrated shielding system providers with in-house testing laboratories, consolidating fragmented local fabricator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR reclassification and REACH substance restrictions are forcing capital retooling that weaker regional fabricators cannot finance, consolidating vendor relationships toward ISO 13485-certified incumbents with alternative material platforms.
For Market Incumbents: Deepen backward integration into tungsten-polymer nanocomposite formulation to capture margin compression from raw material volatility. Secure captive supply agreements with Jiangxi Province processors before export quota tightening. Expand in-house attenuation testing laboratory capacity to unbundle verification services from capital contracts, mirroring Dutch group purchasing organization demands. For New Entrants and Emerging Players: Begin with veterinary diagnostic imaging installations in the United Kingdom and companion animal CT suites in Southeast England, where human healthcare saturation has left persistent undersupply. Target independent dental practices in Spain seeking custom-fabricated barriers with shorter lead times than German incumbents provide. Lead with rapid-install modular vault configurations to minimize revenue disruption during suite upgrades. For Investors and Strategic Acquirers: Bavarian cardiac catheterization lab conversion timelines are the leading indicator that tungsten-polymer penetration rates are accelerating beyond replacement-cycle projections. The five-to-ten year viability window favors acquisition targets with certified lead-free platforms and existing EU MDR technical documentation. Watch for ECHA REACH enforcement actions against non-compliant legacy manufacturers as the inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Class I medical device conformity creates certified product premiums that ISO 13485 systems capture. |
| Tungsten-Polymer Formulation Partnership | Jiangxi Province concentrate supply agreements insulate margins against Chinese export quota volatility. |
| Attenuation Testing Laboratory Expansion | In-house verification capabilities enable unbundled service contracts that Dutch GPOs increasingly demand. |
| Veterinary Diagnostic Imaging Entry | Companion animal CT undersupply in United Kingdom private practices offers white-space penetration. |
| Modular Vault System Development | Rapid-install configurations address outpatient imaging chain priorities in Texas and Florida markets. |
Research Methodology
Document review covered FDA 21 CFR Part 1020 equipment performance standards, ECHA REACH Annex XVII substance restrictions, and EU MDR technical documentation requirements, complemented by interviews with radiation safety officers, hospital biomedical engineering directors, group purchasing organization contract managers, and shielding garment procurement leads. Secondary validation drew from hospital procurement databases, GPO contract disclosures, and customs trade data for tungsten and bismuth concentrate flows. Bottom-up installation tracking across diagnostic and interventional radiology suites triangulated against top-down manufacturer revenue segmentation.
Cross-referencing historical lead-apron replacement cycles with panel input from interventional cardiologists and electrophysiologists informed penetration assumptions for tungsten-polymer alternatives across the analysis window. Segmentation dimensions modeled include product type, application intensity, end-user procurement sophistication, and installation mobility requirements. CAGRs were derived from installed base expansion and average selling price trajectories, incorporating fluoroscopy procedure volume growth and ECHA REACH sunset enforcement timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; interventional radiology shielding procurement carries tighter precision than veterinary diagnostic imaging due to centralized contract visibility. Forecasts reflect assumptions regarding regulatory enforcement consistency and raw material supply continuity. A model refresh is warranted upon material change in Chinese tungsten export policy or EU MDR notified body backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Asthma Device Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
TMJ Implants Market
Medical Devices
Extremity Tissue Expanders Market