
 Embryo Transfer Catheters Market | 2026-2036
Embryo Transfer Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Embryo Transfer Catheters Market Foresight
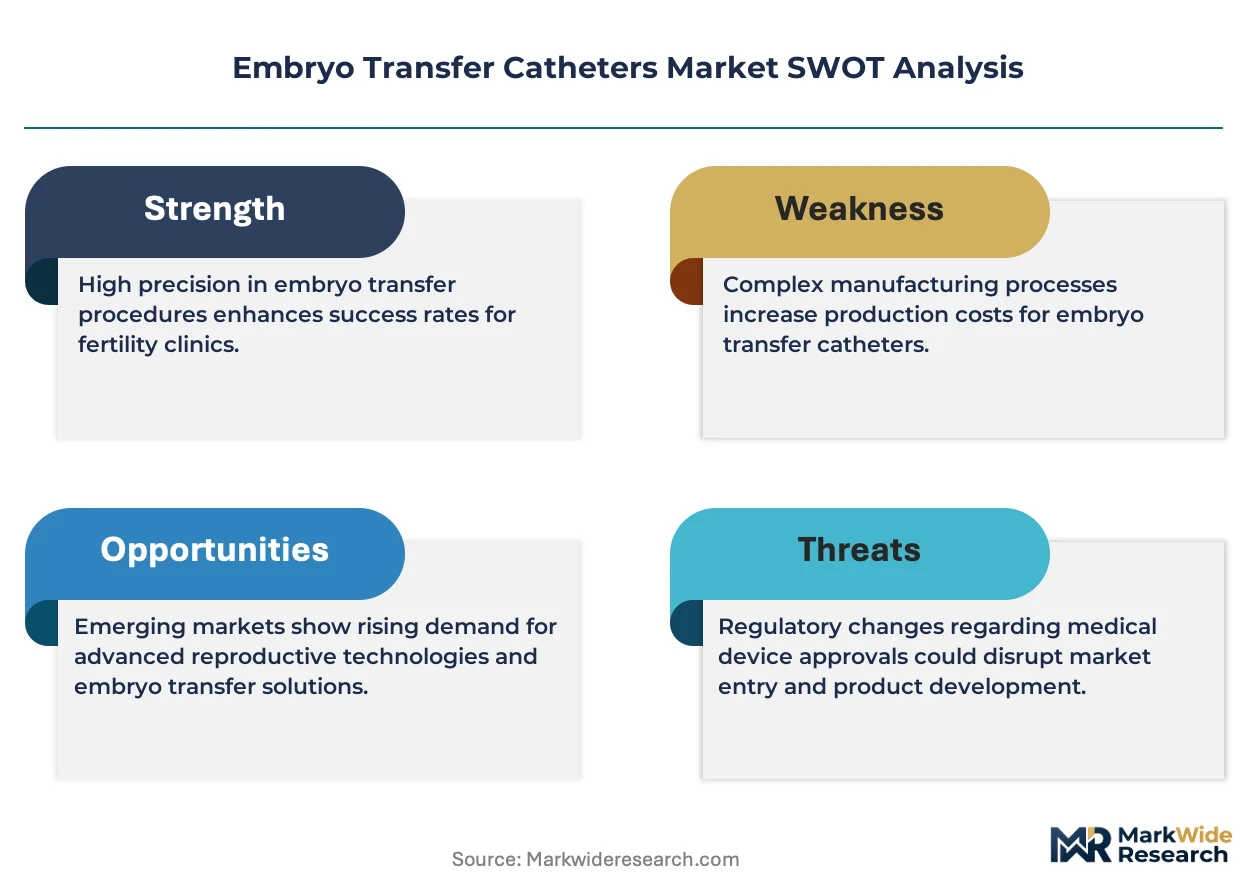
Polyethylene is decoupling from premium catheter lines as polyurethane and silicone gain share in embryo transfer applications. CooperSurgical, Inc. leverages its integrated fertility portfolio to control distribution across North American IVF networks. Cook Medical anchors its position through deep specialization in rigid catheter geometries for complex uterine anatomies. Vitrolife AB competes on cell-culture-to-transfer workflow integration, reducing clinic vendor fragmentation.
Embryo transfer catheters are sterile, single-use instruments engineered from medical-grade polymers with outer diameters typically ranging from 1.0 mm to 1.5 mm, designed to deposit embryos into the uterine cavity with minimal endometrial disruption during assisted reproductive technology procedures. Flexible catheters dominate clinical preference due to reduced patient discomfort and lower perforation risk, while double-lumen configurations command margin premiums by enabling simultaneous embryo and medium delivery. Research applications represent the fastest-expanding end-user segment as preclinical toxicology and genetic screening protocols multiply.
The FDA regulates embryo transfer catheters as Class II medical devices under 510(k) premarket notification pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reproductive device manufacturers seeking CE marking. ISO 10993 biocompatibility testing and USP Class VI certification form baseline material qualification standards across both jurisdictions. Stakeholders must monitor evolving FDA guidance on 510(k) predicate device equivalence as novel catheter coatings and surface modifications proliferate.
Market Dynamics
Polyethylene-to-polyurethane material transitions are compressing legacy supply relationships while fertility clinic procurement consolidates around integrated workflow vendors capable of spanning culture media through transfer instrumentation.
Growth Catalysts
- Public Reimbursement Expansion:India's Ayushman Bharat scheme and Brazil's SUS fertility coverage extensions are broadening patient access to IVF procedures, directly expanding catheter volumes in high-population markets.
- Material Flexibility Gains:Polyurethane and silicone formulations are reducing embryo trauma rates compared to legacy polyethylene constructions, driving clinical preference shifts in premium catheter segments.
- IVF Network Consolidation:Large fertility clinic chains in the United States are standardizing catheter procurement at scale, creating volume concentration effects that favor suppliers with integrated fertility portfolios.
Market Restraints
- Specialized Polymer Supply Concentration:Medical-grade polyurethane feedstock production clusters in Germany and Japan, exposing catheter manufacturers to input cost volatility and geographic supply risk.
- Regulatory Evidence Burden:The EU Medical Device Regulation imposes stricter clinical evidence requirements for reproductive device CE marking, extending approval timelines and compliance costs relative to prior directives.
- Single-Use Cost Structure:Sterile, disposable catheter economics face pressure from high-volume clinic procurement teams seeking per-procedure cost compression without quality compromise.
Strategic Opportunities
- Preclinical Research Applications:Toxicology and genetic screening protocol expansion is creating demand for specialized embryo transfer catheters in pharmaceutical and academic research settings outside clinical IVF.
- Workflow Integration:Cell-culture-to-transfer system convergence offers white space for vendors reducing clinic vendor fragmentation through coordinated media, cultureware, and catheter offerings.
- Complex Anatomy Specialization:Rigid catheter geometries for challenging uterine anatomies represent underserved segments where deep specialization commands sustainable margin premiums.
Industry Challenges
- ISO 10993 Biocompatibility Testing Timelines:Material qualification protocols for novel catheter coatings and surface modifications are extending product development cycles and delaying market entry.
- FDA 510(k) Predicate Equivalence:Evolving agency guidance on substantial equivalence for modified catheter designs is creating regulatory uncertainty for manufacturers with innovation pipelines.
- Legacy System Integration:Clinic electronic medical record and imaging system interoperability requirements are complicating catheter-ancillary equipment coordination for integrated workflow vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embryo Transfer Catheters Market |
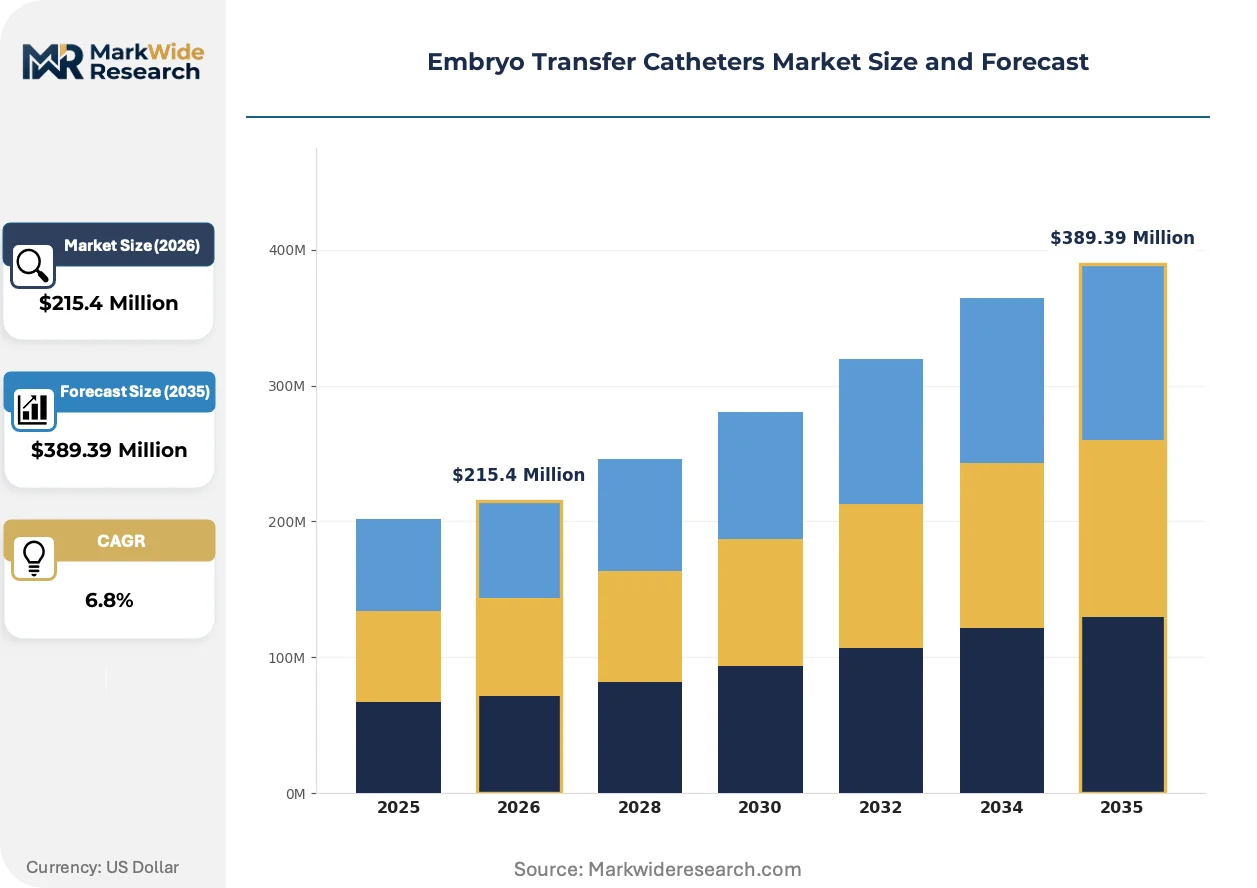
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Catheters, Rigid Catheters, Double-Lumen Catheters, Single-Lumen Catheters Application: In Vitro Fertilization, Surrogacy, Research, Artificial Insemination End User: Fertility Clinics, Hospitals, Research Laboratories, Animal Clinics Material: Polyethylene, Polyurethane, Silicone, PVC |
| Companies Covered | CooperSurgical, Inc., Cook Medical, Thermo Fisher Scientific, Inc., Vitrolife AB, LABOTECT GmbH, Gynétics Medical Products N.V., Rocket Medical plc, Fujifilm Irvine Scientific, MedGyn Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embryo Transfer Catheters Market Shifts & Advancements
Digital imaging integration and surface engineering advances are redefining precision thresholds in embryo placement, while regulatory frameworks tighten evidence standards for novel reproductive device introductions.
Soft-tip catheter designs with echogenic markers are decentralizing ultrasound-guided transfer protocols from specialized academic centers to community fertility clinics. Mid-tier IVF networks in Spain and Australia are adopting these configurations at accelerated pace. The technology is decentralizing expertise requirements and compressing referral concentration around high-complexity cases.
The EU Medical Device Regulation's clinical evidence requirements for reproductive device CE marking are elevating documentation burdens for catheter manufacturers seeking European market access. Smaller specialized suppliers without legacy clinical data repositories face disproportionate compliance cost absorption. Flexible catheter segments with established predicate histories are adapting through post-market clinical follow-up investments, while novel coating technologies navigate extended approval pathways.
Consolidated procurement by large United States fertility networks is compressing vendor counts and unbundling after-sales service from device pricing. Independent clinics in Texas and Florida are responding through group purchasing organization membership to recover scale-equivalent terms. The shift is most visible in standardized flexible catheter categories where specification homogenization enables volume-based contracting.
Embryo Transfer Catheters Market Segmentation
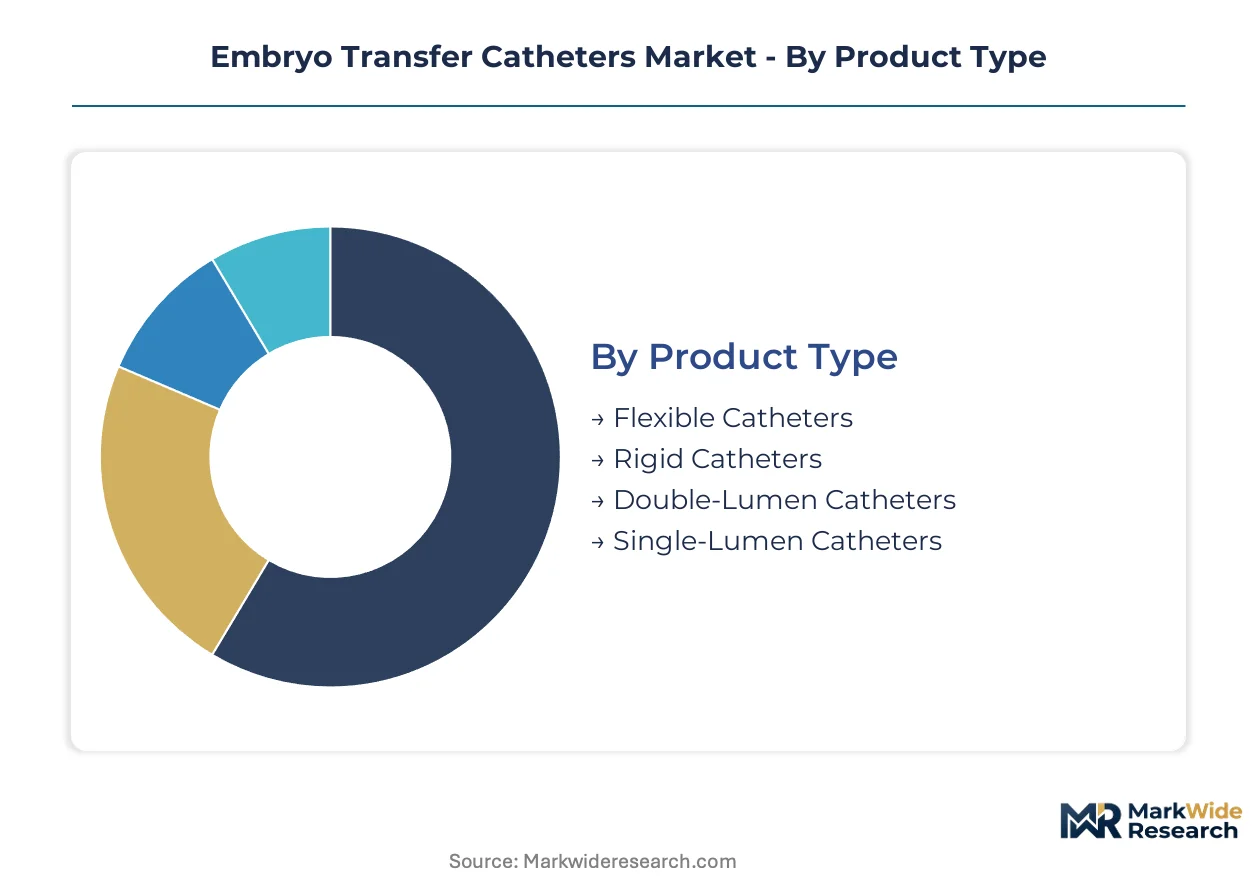
Catheter specification choices directly influence embryo viability outcomes and procedural efficiency across fertility networks. Procurement patterns in this market diverge sharply between high-volume standardized configurations and specialized anatomical solutions. Understanding segment boundaries clarifies where technology investments concentrate versus where cost compression dominates purchasing decisions.
Product Type:
Replacement cycles for legacy polyethylene-based instruments are accelerating as clinics modernize toward trauma-reducing material platforms. The upgrade momentum favors configurations integrating echogenic markers and soft-tip geometries.
- Flexible Catheters:Polyurethane and silicone constructions dominate new procurement, with outer diameters of 1.0–1.5 mm engineered to minimize endometrial disruption. Demand clusters in United States fertility networks standardizing procurement across multi-site IVF chains, driven by patient comfort metrics and reduced perforation risk.
- Double-Lumen Catheters:Simultaneous embryo and medium delivery capability commands margin premiums in premium clinic tiers. Adoption concentrates in academic medical centers and high-complexity referral hubs where procedure time compression justifies per-unit cost elevation.
- Rigid Catheters:Specialized stainless-reinforced geometries address complex uterine anatomies including severe anteversion or cervical stenosis. Niche positioning sustains pricing power despite lower procedure volumes.
- Single-Lumen Catheters:Cost-optimized construction for high-throughput clinics prioritizing per-procedure economics over advanced feature sets. Volume leadership in price-sensitive emerging markets.
Volume placements concentrate in flexible configurations; the faster expansion belongs to double-lumen systems.
Application:
Cost tier stratification separates reimbursed clinical procedures from self-pay research protocols, with divergent specification requirements and vendor qualification standards.
- In Vitro Fertilization:Standard-of-care embryo deposition procedures account for the dominant procedure volume across fertility clinic networks. Regulatory compliance burden heaviest in this segment due to direct patient outcome liability.
- Research:Preclinical toxicology and genetic screening applications are expanding most quickly, with pharmaceutical sponsors driving demand for catheter configurations compatible with automated imaging platforms and high-throughput screening protocols.
- Surrogacy:Gestational carrier procedures require identical catheter specifications to standard IVF but concentrate in specialized legal jurisdictions with established surrogacy frameworks.
- Artificial Insemination:Lower-complexity intrauterine insemination procedures utilize simplified catheter geometries with reduced material specification requirements and corresponding price points.
Clinical IVF generates absolute volume dominance; research applications are climbing the fastest.
End User:
Customer type determines procurement modality, with consolidated network purchasing diverging sharply from independent clinic acquisition patterns.
- Fertility Clinics:Dedicated reproductive medicine facilities execute the majority of embryo transfer procedures, with procurement increasingly centralized through group purchasing organizations or corporate parent entities.
- Hospitals:Academic medical centers and integrated delivery networks maintain catheter inventories for both routine IVF and complex maternal-fetal medicine referrals, with higher regulatory documentation requirements.
- Research Laboratories:Pharmaceutical and biotechnology entities source specialized configurations for toxicology studies, with specification demands driven by protocol standardization rather than clinical outcome optimization.
- Animal Clinics:Veterinary reproductive services represent emerging demand for scaled-down catheter geometries adapted to bovine and equine embryo transfer applications.
Procurement volume concentrates in fertility clinics; steepest expansion trajectory belongs to research laboratories.
Material:
Supply concentration for medical-grade polymers in Germany and Japan shapes material selection economics and geographic sourcing risk exposure.
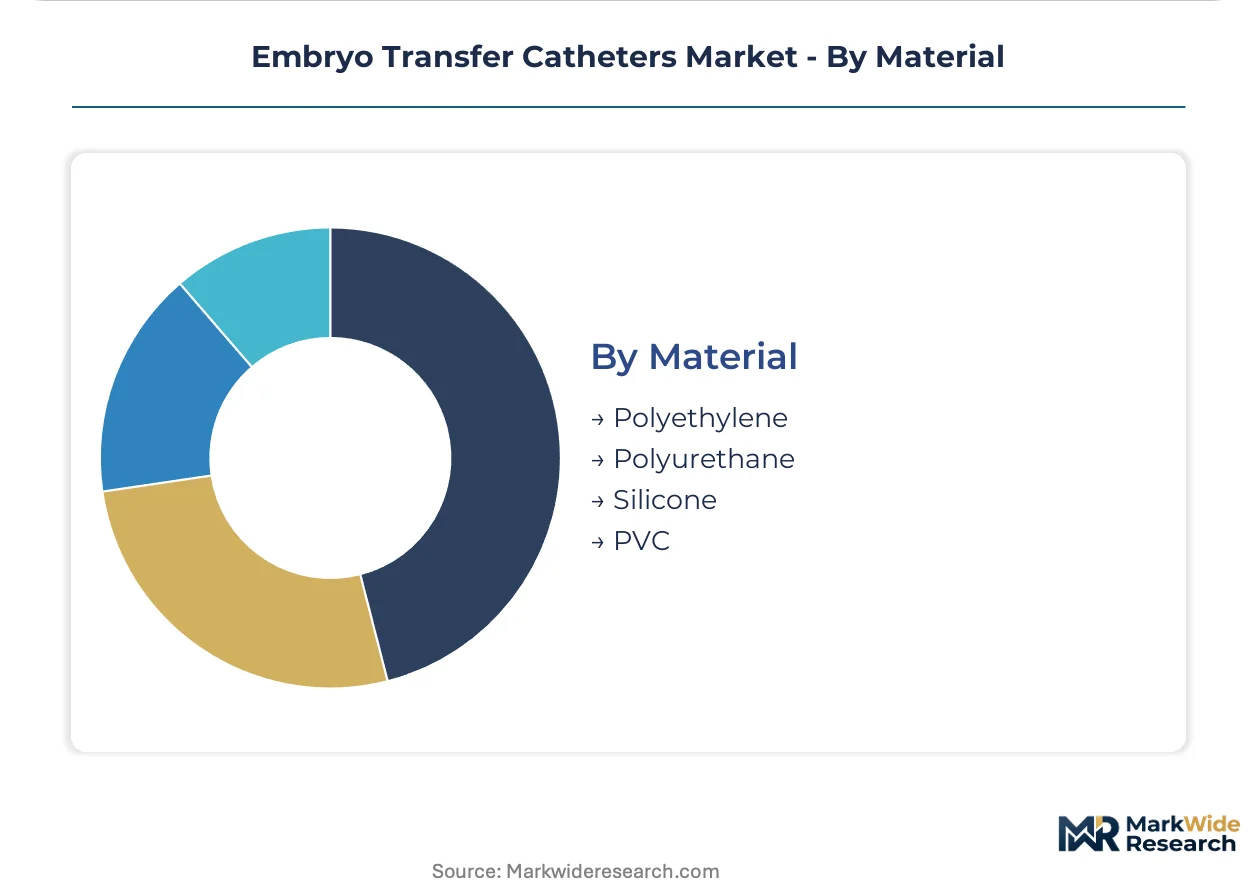
- Polyurethane:Advanced elastomer formulations deliver superior flexibility and biocompatibility profiles, displacing legacy polyethylene in premium catheter lines. Feedstock production clusters expose manufacturers to input cost volatility.
- Silicone:Platinum-cured medical-grade constructions offer lowest thrombogenicity and surface energy characteristics, preferred for research applications requiring minimal cellular adhesion.
- Polyethylene:Legacy material platform facing accelerated displacement despite cost advantages, with remaining demand concentrated in price-sensitive emerging markets and high-volume disposable economics.
- PVC:Lowest-cost alternative restricted to non-clinical research applications and veterinary procedures where regulatory biocompatibility requirements are less stringent.
Polyurethane captures fastest share gains; polyethylene retains residual volume in cost-optimized procurement tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Malaysia and Costa Rica are redirecting catheter production investment away from traditional European centers. Tax holidays and streamlined customs processing in these zones accelerate facility commissioning timelines.
United States
Large fertility network consolidation in Texas and Florida is standardizing catheter procurement through centralized purchasing entities. The FDA's 510(k) premarket notification pathway governs device clearance timelines. The Boston-Cambridge corridor anchors research catheter demand from pharmaceutical toxicology programs.
Germany
Medical-grade polyurethane feedstock production clusters around Leverkusen and Ludwigshafen expose catheter manufacturers to input cost volatility. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking reproductive devices. The Baden-Württemberg precision manufacturing belt hosts specialized catheter tooling suppliers.
India
Ayushman Bharat scheme reimbursement expansion is broadening IVF access and accelerating embryo transfer volumes in Mumbai and Delhi fertility networks. The Central Drugs Standard Control Organization regulates device import and local manufacturing licensing. The Maharashtra medical device park in Aurangabad is attracting catheter assembly operations through production-linked incentive schemes.
Brazil
SUS fertility coverage extensions in São Paulo and Rio de Janeiro state networks are expanding procedure accessibility. ANVISA governs medical device registration with evolving post-market surveillance requirements. The Campinas biotechnology cluster is emerging as a Latin American hub for fertility clinic equipment distribution.
Japan
Aging demographics and delayed childbearing are sustaining IVF demand in Tokyo and Osaka metropolitan fertility centers. The Pharmaceuticals and Medical Devices Agency maintains stringent quality management system inspections for reproductive device manufacturers. The Kansai medical technology corridor in Osaka Prefecture concentrates catheter trading company headquarters.
Embryo Transfer Catheters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fertility portfolio vendors commanding procurement consolidation benefits in United States networks. The vendor base organizes into three tiers: multinational device conglomerates with reproductive divisions, pure-play catheter specialists, and regional distributors with private-label manufacturing relationships. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure polyurethane feedstock agreements.
Within the integrated fertility portfolio tier, CooperSurgical, Inc. and Vitrolife AB represent archetypes of vendors spanning culture media through transfer instrumentation to reduce clinic vendor fragmentation. Cook Medical occupies a position among deep specialization players focused on rigid catheter geometries. These three companies exemplify contrasting strategic postures: workflow integration versus anatomical specialization versus materials science depth.
| Leading Market Players |
|---|
| CooperSurgical, Inc. |
| Cook Medical |
| Thermo Fisher Scientific, Inc. |
| Vitrolife AB |
| LABOTECT GmbH |
| Gynétics Medical Products N.V. |
| Rocket Medical plc |
| Fujifilm Irvine Scientific |
| MedGyn Products, Inc. |
| Others |
Supply & Pricing Matrix
United States fertility network procurement consolidation compresses vendor counts and unbundles after-sales service from device pricing, establishing contract-based long-term offtake as the dominant pricing structure across multi-site IVF chains.
Pricing Analysis
Short lead-time premiums for medical-grade polyurethane formulations command elevation over spot inventory discounts in flexible catheter categories. Three-tier pricing structure across premium, standard, and economy levels separates double-lumen configurations with echogenic markers from basic single-lumen constructions. Cost compression in high-throughput clinic tiers intensifies because group purchasing organizations recover scale-equivalent terms. Independent fertility clinics in price-sensitive emerging markets exhibit highest price sensitivity; academic medical centers with complex anatomy referral loads demonstrate lowest.
Supply Chain Analysis
Direct-to-fertility-clinic channels handle high-volume network demand while specialized distributors serve independent clinic and research laboratory segments. Medical-grade polyurethane feedstock production clusters in Germany and Japan, with catheter assembly operations redirecting toward Malaysia and Costa Rica special economic zones. Raw material dependencies center on thermoplastic elastomer formulations, stainless-steel reinforcement wire, and platinum-cured silicone. Single-source vulnerability for polyurethane feedstock exposes manufacturers to input cost volatility. Distribution runs through integrated fertility portfolio vendors, regional distributors with private-label relationships, and direct research laboratory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large fertility network procurement consolidation forces weaker catheter manufacturers out as integrated workflow vendors capture volume concentration benefits.
For Market Incumbents: Deploy workflow integration levers spanning culture media through transfer instrumentation to lock in multi-year supply agreements with consolidating United States networks. Backward integration into medical-grade polyurethane feedstock agreements mitigates single-source supply risk from German and Japanese production clusters. Capacity addition in Malaysian special economic zones captures tax holiday benefits while positioning for Asia-Pacific demand expansion. For New Entrants and Emerging Players: Echogenic marker and soft-tip catheter designs offer white-space entry points as mid-tier IVF networks in Spain and Australia accelerate adoption. Preclinical research applications present the most penetrable segment, with pharmaceutical toxicology sponsors driving demand for configurations compatible with automated imaging platforms. Direct research laboratory contracts bypass entrenched fertility network procurement consolidation. For Investors and Strategic Acquirers: The window for entry favors specialized catheter tooling suppliers in the Baden-Württemberg precision manufacturing belt with established ISO 10993 qualification protocols. Long-term viability concentrates in vendors with demonstrated EU MDR CE marking pathways and post-market clinical follow-up investments. Watch FDA 510(k) predicate equivalence guidance evolution as inflection indicator for novel coating technology commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements elevate documentation burdens for European market access. |
| Hospital System Partnership | Academic medical center alliances secure high-complexity referral hub catheter procurement volumes. |
| Backward Integration into Polyurethane Feedstock | Captive supply agreements with German and Japanese producers reduce input cost volatility exposure. |
| Software Companion Development | Digital imaging integration protocols decentralize ultrasound-guided transfer expertise requirements. |
| Reimbursement Strategy Alignment | Ayushman Bharat and SUS fertility coverage extensions unlock high-population market catheter volumes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this embryo transfer catheters analysis. Primary interviews with fertility clinic procurement directors, biomedical engineers, GPO contracts managers, and reproductive endocrinologists combined with FDA 510(k) databases, EU MDR submission repositories, and CDSCO import licensing records. Bottom-up catheter volume modeling triangulated against top-down fertility procedure forecasts.
Data-stream reconciliation across product type, material formulation, application setting, and end-user procurement modality informed the analytical framework. CAGRs derived from segmented volume projections and average selling price trajectories across the analysis window. Industry-specific forecast inputs incorporated IVF network consolidation pace and public reimbursement expansion timelines in India and Brazil.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory approval delays for novel catheter coatings and polyurethane feedstock supply disruptions. Forecasts reflect assumptions regarding fertility clinic network consolidation continuity and research application protocol standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Gum Grafting Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Germany Aesthetic Devices Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Peak Flow Meters Market