
 Asia Pacific Veterinary Equipment and Disposables Market | 2026-2036
Asia Pacific Veterinary Equipment and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Veterinary Equipment and Disposables Market Outlook
Stainless steel is broadening its displacement of conventional chrome-plated instruments across surgical instrument lines, reducing corrosion rates and extending sterilization cycle tolerance. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. leverages its domestic manufacturing scale to anchor pricing power in diagnostic imaging across tier-two Chinese cities. IDEXX Laboratories sustains R&D intensity in point-of-care analyzers, while B. Braun Melsungen AG competes through vertical control over suture and infusion product supply chains.
Asia Pacific veterinary equipment and disposables encompass instruments, diagnostic systems, anesthesia delivery platforms, and single-use treatment supplies engineered for species-specific physiology and clinic throughput requirements. Diagnostic equipment incorporates digital sensor arrays with resolution thresholds calibrated for small-animal orthopedics and large-animal reproductive imaging. Surgical instruments command the largest revenue pool among product type segments, though anesthesia equipment registers the fastest expansion as companion animal surgery volumes rise. Within applications, pet care dominates absolute spend while livestock management segments retain margin density through government-subsidized herd health programs.
China's NMPA veterinary device standards, Japan's PMDA animal health product frameworks, and Australia's TGA medical device classifications collectively shape product registration timelines and clinical evidence requirements across the region. Japan's METI energy-efficiency mandates for electronic diagnostic equipment additionally influence procurement specifications in metropolitan animal hospitals. Stakeholders must weigh regulatory divergence against manufacturing consolidation as they allocate capital between localized assembly and centralized export hubs.
Market Dynamics
Companion animal surgery volumes across Southeast Asia are compressing equipment replacement cycles while China's NMPA streamlines veterinary device registrations, creating dual momentum for diagnostic imaging and anesthesia platform upgrades.
Growth Catalysts
- Japan's METI energy-efficiency mandates:Metropolitan animal hospitals in Tokyo and Osaka face procurement specifications favoring low-power digital radiography systems, accelerating fleet modernization.
- Companion animal surgery volumes:Specialist referral centers in Australia and South Korea are driving premium anesthesia equipment installations as minimally invasive procedures expand.
- NMPA registration pathway streamlining:China's consolidated veterinary device approval process reduces time-to-market for diagnostic imaging platforms targeting tier-two city clinics.
Market Restraints
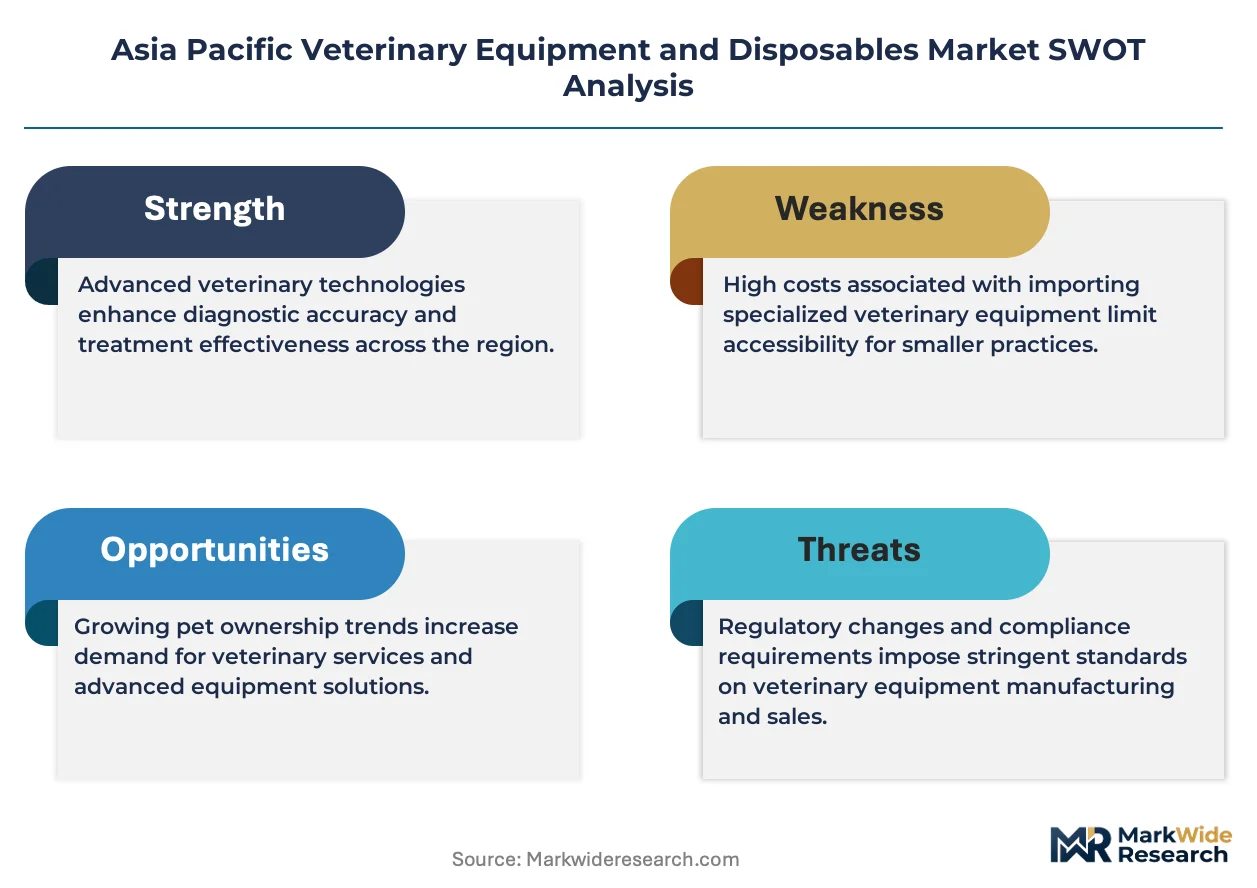
- Stainless steel input cost volatility:Surgical instrument manufacturers face margin pressure from fluctuating nickel and chromium prices, compressing economies of scale for mid-tier suppliers.
- Technical limitation in large-animal imaging:Current digital sensor arrays lack resolution thresholds calibrated for equine orthopedics and bovine reproductive applications, restricting product line extensions.
- Regulatory friction from Australia's TGA:Medical device classification overlaps with veterinary equipment create dual compliance burdens for anesthesia delivery platforms entering the market.
Strategic Opportunities
- Underpenetrated tier-two Chinese cities:Diagnostic imaging equipment deployment remains sparse in Chengdu, Wuhan, and Xi'an veterinary networks, offering first-mover positioning for domestic-scale suppliers.
- Point-of-care analyzer convergence:Integration of hematology and chemistry testing into single-platform devices creates white space in companion animal clinic workflows across South Korea.
- Japan's PMDA animal health product frameworks:Streamlined clinical evidence requirements for Class II veterinary devices reduce registration timelines, enabling faster market entry for anesthesia monitoring systems.
Industry Challenges
- Veterinary anesthesia technician skill gaps:Southeast Asia lacks certified professionals capable of operating advanced delivery platforms, constraining equipment utilization rates in Bangkok and Jakarta clinics.
- Capex intensity for digital radiography:Specialist referral centers in Australia require substantial upfront investment for detector array upgrades, elongating sales cycles.
- Integration complexity with legacy PACS:Metropolitan veterinary hospital networks face interoperability failures when connecting new imaging systems to existing archival infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Veterinary Equipment and Disposables Market |
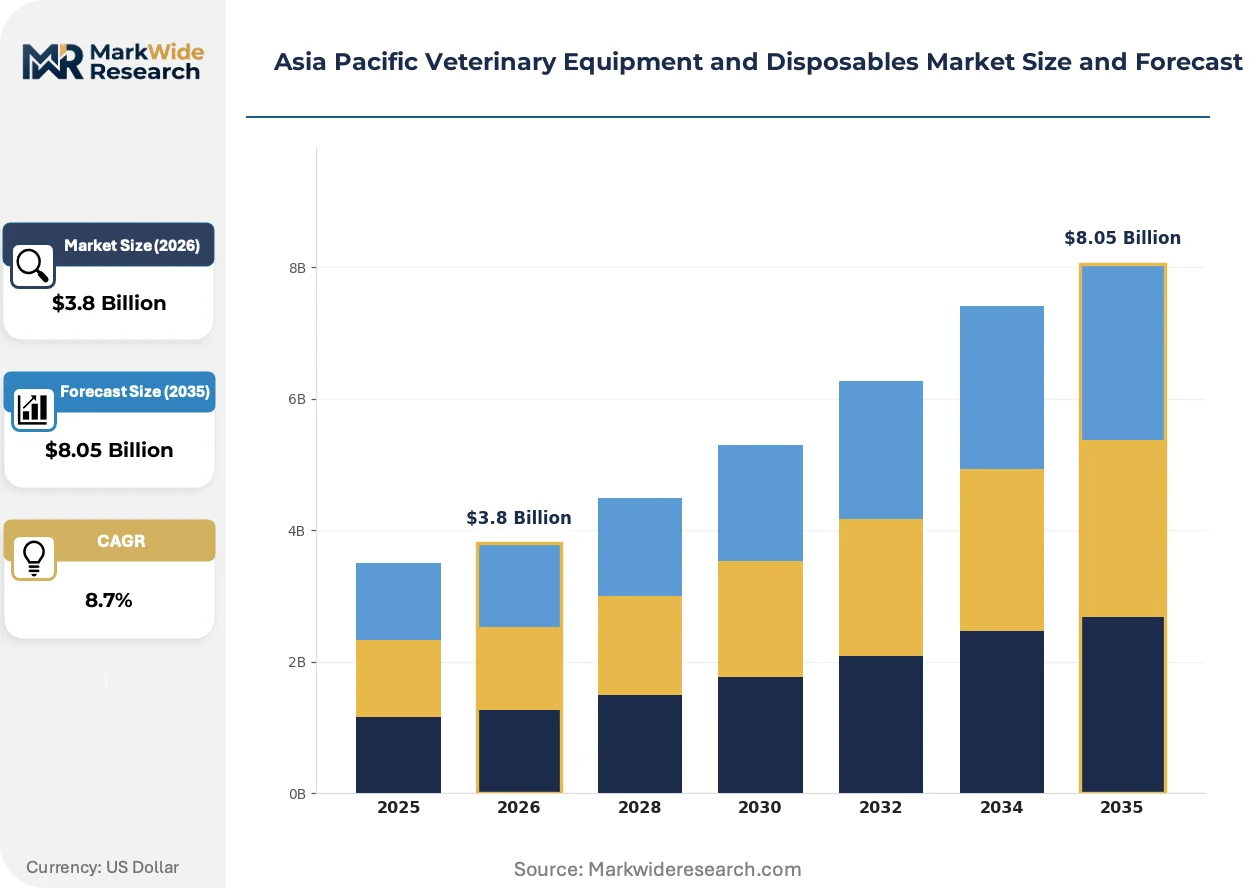
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Anesthesia Equipment, Treatment Supplies Application: Pet Care, Livestock Management, Equine Care, Wildlife Conservation End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Zoos Distribution Channel: Direct Sales, Online Retail, Veterinary Distributors, Specialty Stores |
| Companies Covered | Zoetis Inc., IDEXX Laboratories, B. Braun Melsungen AG, Medtronic PLC, Midmark Corporation, Covetrus, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Elanco Animal Health, Patterson Companies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Veterinary Equipment and Disposables Market Strategic Shifts
Digital sensor technology and regulatory harmonization are compressing product development timelines while procurement centralization reshapes vendor relationships across Asia Pacific veterinary networks.
Wireless-capable digital radiography detectors are expanding into companion animal orthopedics and dental imaging applications. Specialist referral centers in Australia's metropolitan networks are adopting these systems at accelerated replacement cycles. The technology is expanding into mobile veterinary service models, enabling field-deployable imaging that challenges fixed-installation revenue structures.
China's NMPA veterinary device standards are converging with human medical device technical requirements, reducing documentation duplication for multinational suppliers. This harmonization compresses registration preparation costs for diagnostic imaging platforms. Japanese and Australian regulators are observing this convergence, with PMDA and TGA evaluating similar alignment for Class II equipment categories.
Metropolitan veterinary hospital networks are consolidating procurement decisions through centralized purchasing cooperatives, displacing individual clinic autonomy. This buyer concentration shifts vendor sales strategies toward multi-site contract negotiations in Sydney, Melbourne, and Brisbane. South Korea's Seoul metropolitan area exhibits comparable consolidation, with university-affiliated referral centers dominating anesthesia equipment specification authority.
Asia Pacific Veterinary Equipment and Disposables Market Segmentation
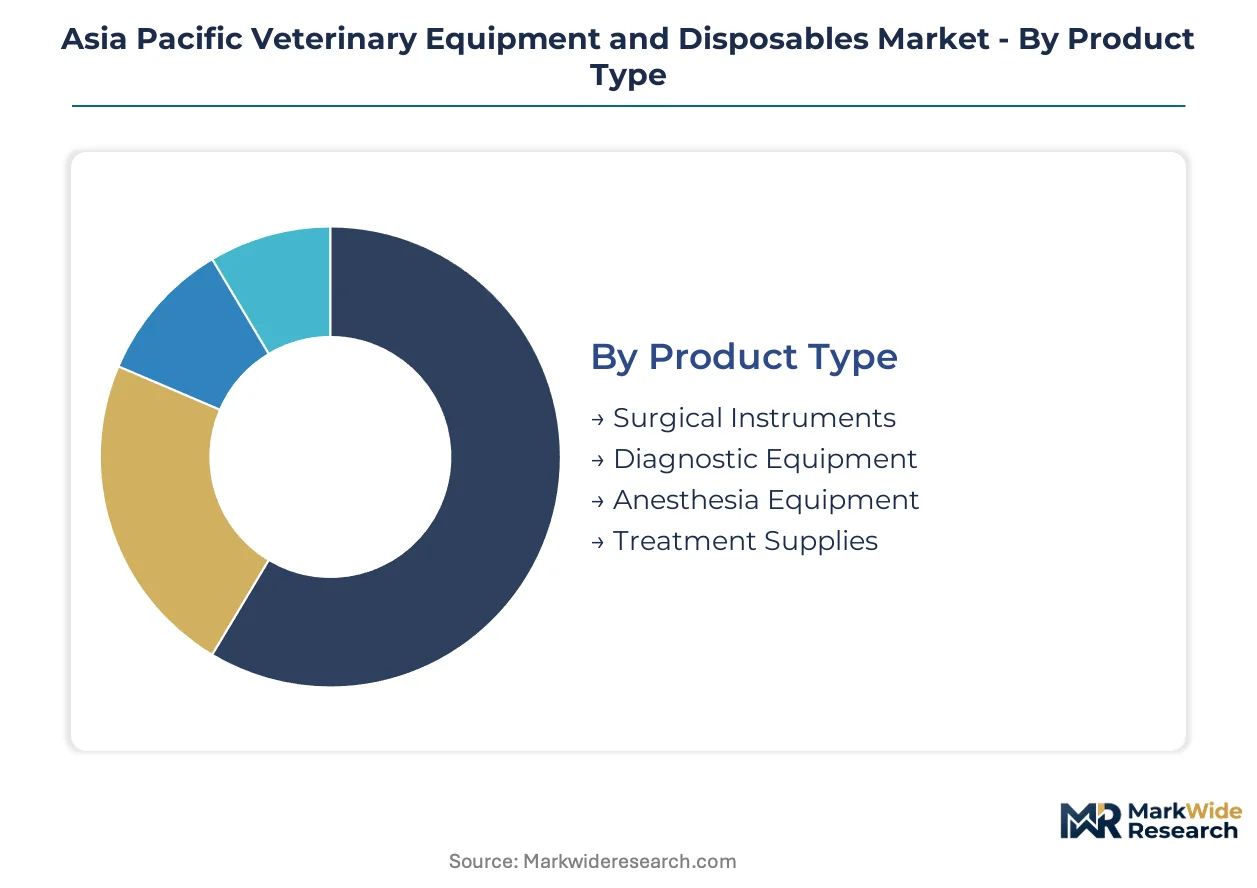
Veterinary equipment purchasing decisions diverge sharply by clinical setting and species served, with capital deployment patterns varying from high-volume livestock operations to precision-driven companion animal surgery. Understanding these segment boundaries enables suppliers to align product specifications with distinct throughput, regulatory, and reimbursement environments.
Product Type:
Surgical instruments demand the heaviest upfront capital commitment due to stainless steel forging requirements and sterilization infrastructure, while anesthesia platforms require integrated gas delivery engineering that elevates R&D amortization.
- Surgical Instruments:Comprising scalpels, forceps, retractors, and needle holders forged from medical-grade stainless steel with Rockwell hardness ratings optimized for repeated autoclave cycles. Australia's metropolitan veterinary hospital networks concentrate procurement of premium instrument sets as specialist referral centers expand orthopedic and soft-tissue surgery volumes. Capital intensity limits viable suppliers to manufacturers with captive metallurgy capabilities.
- Diagnostic Equipment:Digital radiography systems, ultrasound platforms, and point-of-care analyzers incorporating sensor arrays calibrated for species-specific imaging resolution. Tier-two Chinese cities including Chengdu and Wuhan exhibit sparse deployment, creating first-mover positioning for domestic-scale manufacturers with NMPA registration advantages.
- Anesthesia Equipment:Inhalation and injectable delivery systems with precision vaporizer controls.
- Treatment Supplies:Single-use consumables including sutures, catheters, and wound dressings.
Surgical instruments absorb the bulk of installed capacity; anesthesia equipment is expanding most quickly as companion animal surgery volumes rise across Southeast Asia.
Application:
Margin structures vary by species complexity, with equine and wildlife applications commanding premium pricing despite lower volumes due to specialized equipment requirements and limited supplier competition.
- Pet Care:Companion animal diagnostics and surgery dominating absolute equipment spend. South Korea's Seoul metropolitan area concentrates demand for advanced imaging as pet humanization trends elevate owner willingness to fund specialist procedures. Digital radiography detector upgrades accelerate replacement cycles in university-affiliated referral centers.
- Livestock Management:Herd health monitoring and reproductive imaging systems deployed across government-subsidized programs. Australia's extensive cattle operations sustain demand for portable ultrasound platforms capable of field deployment in Queensland and New South Wales pastoral zones.
- Equine Care:Large-animal orthopedic and reproductive imaging requiring specialized sensor calibration.
- Wildlife Conservation:Mobile anesthesia and diagnostic systems for field veterinary interventions.
Pet care commands the dominant revenue share; livestock management retains margin density through program subsidies and equipment standardization.
End User:
Procurement centralization distinguishes institutional buyers from independent operators, with network scale determining specification authority and vendor negotiation leverage.
- Veterinary Clinics:Small and mid-sized companion animal practices with constrained capital budgets. Procurement autonomy persists in independent Bangkok and Jakarta clinics, though equipment utilization suffers from anesthesia technician certification gaps.
- Animal Hospitals:Multi-specialty referral centers with consolidated purchasing power. Sydney, Melbourne, and Brisbane networks centralize procurement through cooperatives, displacing individual clinic autonomy and compressing vendor margins.
- Research Institutions:Academic and pharmaceutical veterinary research facilities with specialized compliance requirements.
- Zoos:Conservation-focused institutions requiring species-diverse equipment portfolios.
Animal hospitals drive premium equipment specifications; veterinary clinics represent the deepest volume pool across the region.
Distribution Channel:
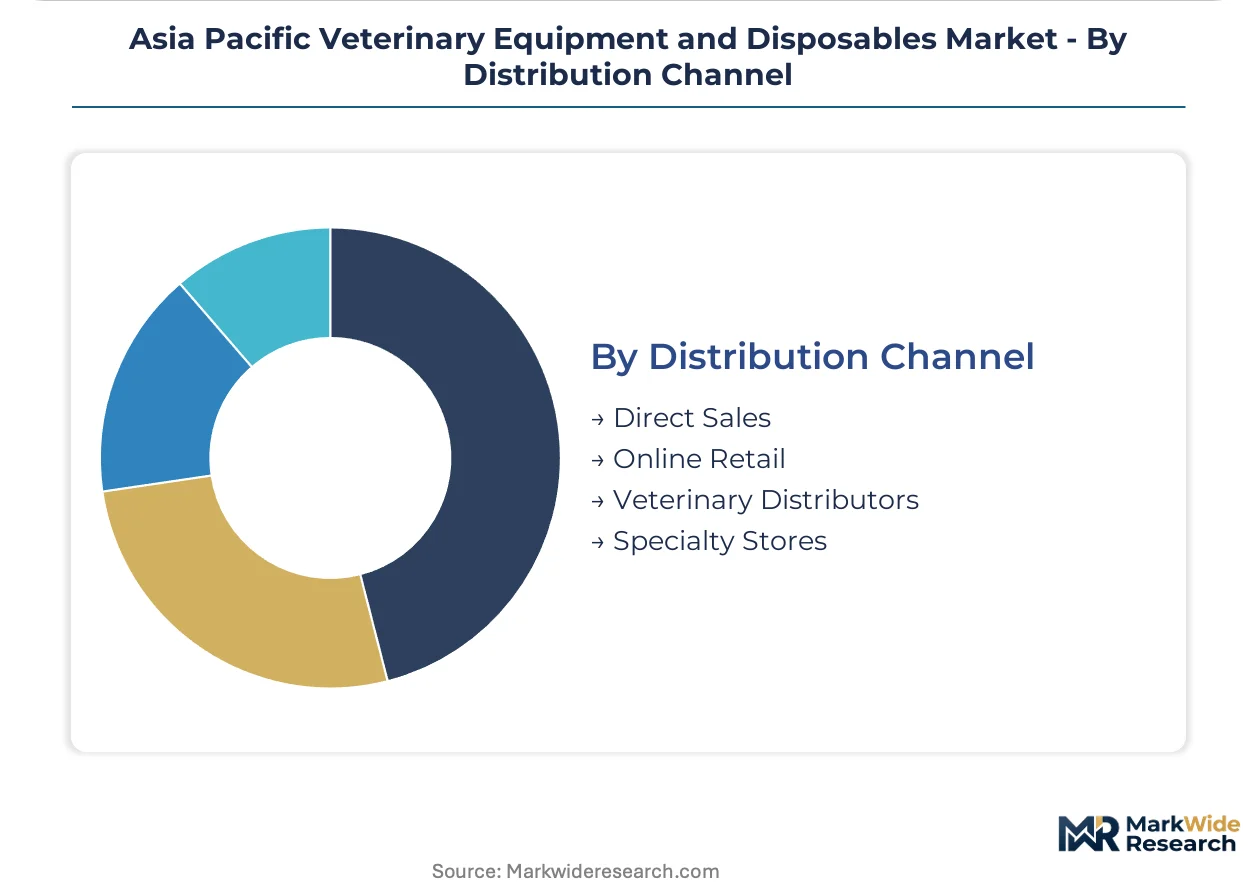
Channel selection reflects product complexity and buyer sophistication, with capital equipment favoring direct engagement while consumables flow through consolidated distributor networks.
- Direct Sales:Manufacturer-led engagement for digital radiography and anesthesia platform installations. Extended sales cycles in Australian specialist centers reflect capital intensity and PACS integration requirements.
- Veterinary Distributors:Regional networks consolidating consumables and mid-tier equipment procurement. South Korea's distributor landscape concentrates anesthesia supply specification authority within Seoul's university-affiliated referral clusters.
- Online Retail:E-commerce platforms for standardized consumables and replacement parts.
- Specialty Stores:Niche retail for equine and livestock equipment in agricultural supply chains.
Veterinary distributors capture the largest transaction volume; direct sales channels gain share fastest as imaging platform complexity demands technical consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's tier-two veterinary networks and Australia's metropolitan referral clusters, with regulatory harmonization compressing product registration timelines across the region.
China
NMPA registration pathway streamlining accelerates diagnostic imaging approvals for multinational suppliers targeting Chengdu and Wuhan clinic networks. Tier-two cities exhibit sparse digital radiography deployment, creating positioning advantages for domestic-scale manufacturers. Shenzhen anchors manufacturing scale for regional export competitiveness.
Australia
Metropolitan veterinary hospital networks in Sydney, Melbourne, and Brisbane centralize procurement through purchasing cooperatives, displacing individual clinic autonomy. TGA medical device classification overlaps with veterinary equipment create dual compliance burdens for anesthesia platform entrants. Specialist referral centers drive premium detector array upgrades.
Japan
Tokyo and Osaka metropolitan animal hospitals face METI energy-efficiency procurement specifications favoring low-power digital radiography systems. PMDA animal health product frameworks streamline Class II veterinary device clinical evidence requirements. University-affiliated referral centers dominate anesthesia equipment specification authority.
South Korea
Seoul metropolitan area concentrates demand for advanced imaging as pet humanization trends elevate specialist procedure funding. Point-of-care analyzer convergence into single-platform devices creates workflow optimization white space. Distributor networks concentrate anesthesia supply specification within university-affiliated clusters.
Thailand
Bangkok companion animal clinics expand procurement of digital radiography and anesthesia systems despite certified anesthesia technician shortages constraining equipment utilization. Southeast Asia surgery volume compression shortens equipment replacement cycles. Independent clinic procurement autonomy persists alongside utilization challenges.
Asia Pacific Veterinary Equipment and Disposables Market Competitive Environment
Product registration acceleration dominates the current landscape as suppliers compress time-to-market for diagnostic platforms. The vendor base organizes around three tiers: multinational imaging specialists with captive regulatory affairs capabilities, regional consumables fabricators with metallurgy scale, and domestic Chinese manufacturers leveraging NMPA proximity. Strategic archetypes include regulatory-first entrants, backward-integrated instrument forgers, and software-anchored diagnostics platforms. M&A activity and geographic licensing partnerships represent the dominant competitive vectors.
Among diversified health technology conglomerates, IDEXX Laboratories and Zoetis Inc. exemplify the R&D-intensive diagnostics archetype, while Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies a position representing domestic-scale manufacturing leverage. B. Braun Melsungen AG anchors the European-origin consumables and infusion control segment. These three entities collectively illustrate the competitive tension between regulatory sophistication, manufacturing scale, and supply chain verticality that defines vendor positioning across Asia Pacific veterinary networks.
| Leading Market Players |
|---|
| Zoetis Inc. |
| IDEXX Laboratories |
| B. Braun Melsungen AG |
| Medtronic PLC |
| Midmark Corporation |
| Covetrus |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Elanco Animal Health |
| Patterson Companies |
| Others |
Value Chain & Pricing Dynamics
Wireless digital radiography detector adoption across Australia's metropolitan veterinary networks is compressing equipment replacement cycles while simultaneously elevating capital intensity, concentrating pricing power with manufacturers possessing captive sensor calibration capabilities and NMPA registration proximity.
Pricing Analysis
Volume concentration in surgical instruments trades against margin density in anesthesia platforms across the Asia Pacific veterinary equipment landscape. Three-tier pricing structure across premium, standard, and economy levels separates university-affiliated referral centers from independent Bangkok clinics and government-subsidized livestock operations. Price differentiation hinges on NMPA registration tier and after-sales service bundling, with domestic Chinese manufacturers anchoring economy positioning. Pricing pressure stems from stainless steel input cost volatility, compressing mid-tier instrument supplier margins. Independent veterinary clinics in Southeast Asia exhibit highest price sensitivity, while Australian purchasing cooperatives leverage consolidated volume for premium tier access.
Supply Chain Analysis
Single-source vulnerability sits with Japanese sensor array suppliers feeding digital radiography assembly lines across the region. Manufacturing gravity centers on China, Japan, and South Korea, with Shenzhen anchoring domestic-scale production for tier-two city deployment. Raw material dependencies encompass medical-grade stainless steel, nickel-chromium alloys, and precision vaporizer components. Supply chain risk manifests through NMPA regulatory restriction complexity for multinational entrants lacking localized registration infrastructure. Distribution runs through veterinary distributors capturing consumables volume, while direct sales channels gain imaging platform share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific veterinary equipment sector is transitioning from analog radiography to wireless digital detector systems, with legacy PACS infrastructure interoperability emerging as the critical adoption bottleneck.
For Market Incumbents: Deploy backward integration into stainless steel forging capabilities to defend surgical instrument margins against nickel price volatility. IDEXX Laboratories and B. Braun Melsungen AG should consolidate anesthesia technician certification partnerships across Bangkok and Jakarta to unlock equipment utilization rates currently constrained by skill gaps. Threat of domestic Chinese manufacturers with NMPA registration advantages necessitates accelerated tier-two city channel control.
For New Entrants and Emerging Players: Capture point-of-care analyzer convergence white space in South Korea's Seoul metropolitan veterinary networks, where single-platform hematology-chemistry integration remains underdeployed. Target livestock management applications in Australia's Queensland pastoral zones with portable ultrasound platforms optimized for field bovine reproductive imaging. Go-to-market leverage rests on government-subsidized herd health program procurement specifications.
For Investors and Strategic Acquirers: Exit pathways concentrate in regulatory-first acquisition archetypes, where NMPA-registered domestic Chinese manufacturers command strategic premiums from multinational imaging specialists. Long-term viability favors entities with software-anchored diagnostics platforms capable of PACS integration. Signal to watch: METI energy-efficiency mandate expansion beyond Tokyo and Osaka into secondary Japanese metropolitan animal hospitals.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Acceleration | Compresses time-to-market for diagnostic imaging platforms targeting Chengdu and Wuhan clinic networks. |
| Anesthesia Technician Certification Partnerships | Unlocks equipment utilization rates in Southeast Asia clinics facing certified professional shortages. |
| Wireless Detector Platform Launch | Displaces fixed-installation revenue structures in Australia's mobile veterinary service models. |
| PACS Integration Development | Resolves interoperability failures plaguing metropolitan veterinary hospital network upgrade cycles. |
| Livestock Ultrasound Field Deployment | Captures government-subsidized procurement specifications across Queensland cattle operations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary clinic owners, biomedical equipment procurement managers, anesthesia technicians, and distributor network heads across Sydney, Tokyo, Seoul, Bangkok, and Shanghai. NMPA veterinary device registration databases, PMDA animal health product frameworks, and TGA medical device classification records provided regulatory timeline validation. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Product type, application, end user, and distribution channel dimensions were modeled at country-level granularity across the projection horizon. CAGRs derived from equipment replacement cycle compression analysis and companion animal surgery volume trajectory assessment. Forecast inputs incorporated NMPA registration pathway streamlining velocity, METI energy-efficiency mandate adoption rates, and stainless steel input cost volatility indices.
The model holds under stable regulatory harmonization assumptions; deviation in NMPA technical requirement convergence or PMDA Class II evidence standard alignment would shift registration timeline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cardiac Implants Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Operating Room Integration Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Global Wheelchair Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market