
 Nanomedical Devices Market | 2026-2036
Nanomedical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomedical Devices Market Outlook
Hospital procurement for nanomedical devices is pivoting toward consolidated group purchasing organizations that negotiate system-wide contracts for nanoparticle-based cancer therapies. Johnson & Johnson sustains R&D intensity across lipid-based nanocarrier platforms for oncology applications. Abbott Laboratories anchors its position through diagnostic nanosensor integration with existing hospital laboratory workflows. Pfizer Inc. competes by extending manufacturing scale for mRNA-lipid nanoparticle formulations.
Nanomedical devices are engineered systems with at least one functional dimension between 1 and 100 nanometers, typically fabricated from biocompatible polymers, lipids, or noble metals to enable targeted cellular interaction, controlled drug release, or enhanced imaging contrast. These devices serve primarily to improve therapeutic indices by concentrating active agents at disease sites while sparing healthy tissue. Targeted drug delivery systems lead product type revenue due to established clinical validation in oncology, while nanosensors represent the fastest-growing category as point-of-care diagnostic protocols expand. Among applications, cancer therapy commands the deepest margin pools, though vaccine development is accelerating following lipid nanoparticle platform validation.
The FDA's nanotechnology regulatory framework and the EU MDR's classification requirements for nano-enabled products shape premarket submission pathways and post-market surveillance obligations for manufacturers. ISO 10993 biocompatibility standards and REACH nanomaterial registration mandates in Europe further constrain material selection and supply chain documentation. Stakeholders must monitor evolving nanospecific guidance from FDA and EMA to anticipate clinical trial design requirements and reimbursement dossier expectations.
Market Dynamics
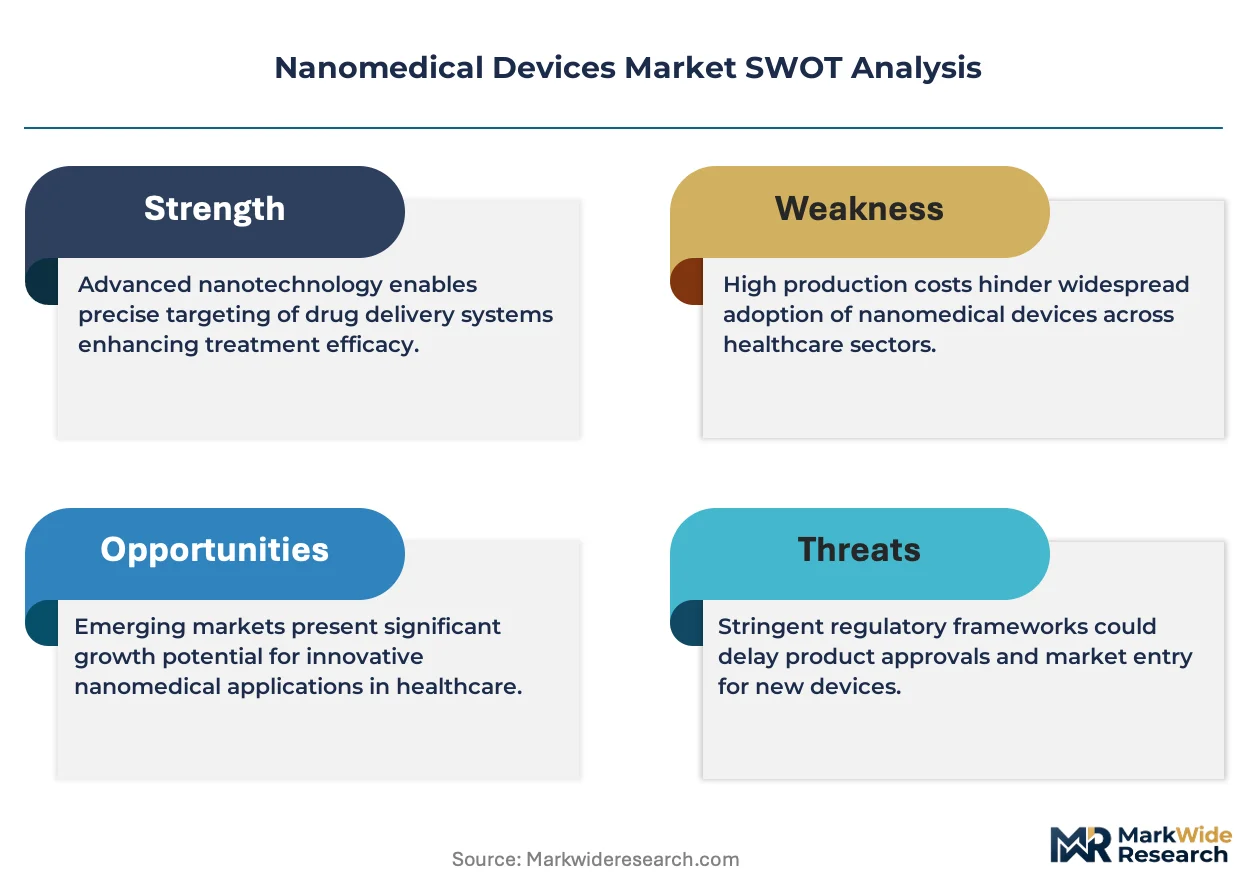
The FDA's nanotechnology guidance framework and the EU MDR's classification requirements are compressing premarket timelines while elevating documentation burdens, forcing manufacturers to restructure clinical trial designs and supply chain traceability systems simultaneously.
Growth Catalysts
- Oncology procurement expansion:Academic medical centers in the United States, Germany, and Japan are accelerating group purchasing organization contracts for targeted drug delivery systems as reimbursement pathways mature.
- REACH nanomaterial mandates:Europe's registration requirements are standardizing supply chain documentation, reducing regulatory friction for compliant manufacturers seeking cross-border market access.
- Lipid nanoparticle platform validation:mRNA vaccine applications have established manufacturing scalability protocols that transfer directly to cancer therapeutics, shortening development cycles.
Market Restraints
- Biocompatible polymer supply concentration:Specialty polymer production clusters in Germany and Switzerland, creating geographic vulnerability for manufacturers dependent on ISO 10993-certified material streams.
- EMA nanospecific guidance gaps:Evolving European Medicines Agency documentation requirements generate submission resubmission cycles that extend time-to-revenue by 8-14 months for novel devices.
- Gold and platinum price volatility:Noble metal nanoshell production faces input cost instability that compresses margins on diagnostic contrast agents and photothermal therapy platforms.
Strategic Opportunities
- Point-of-care diagnostic expansion:Nanosensor integration with hospital laboratory workflows in Japan and South Korea creates white space for multiplexed biomarker detection platforms outside oncology.
- India's CDSCO fast-track pathway:The national pharmaceutical regulator's accelerated approval channel for breakthrough devices offers first-mover positioning for manufacturers with existing FDA or EMA clearances.
- AI-driven nanocarrier design:Machine learning convergence with lipid formulation science is compressing lead optimization timelines from 24 months to under 8 months for targeted delivery systems.
Industry Challenges
- Multidisciplinary talent scarcity:The intersection of nanomaterial science, regulatory affairs, and clinical trial design requires hybrid expertise that academic programs have not scaled to market demand.
- ISO 10993-18 chemical characterization:Updated biocompatibility testing standards for nanomaterials demand capital-intensive analytical infrastructure that mid-scale manufacturers struggle to finance.
- Legacy hospital IT integration:Nanosensor data streams require real-time connectivity with electronic health record systems that lack standardized API architectures for nanoscale diagnostic outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomedical Devices Market |
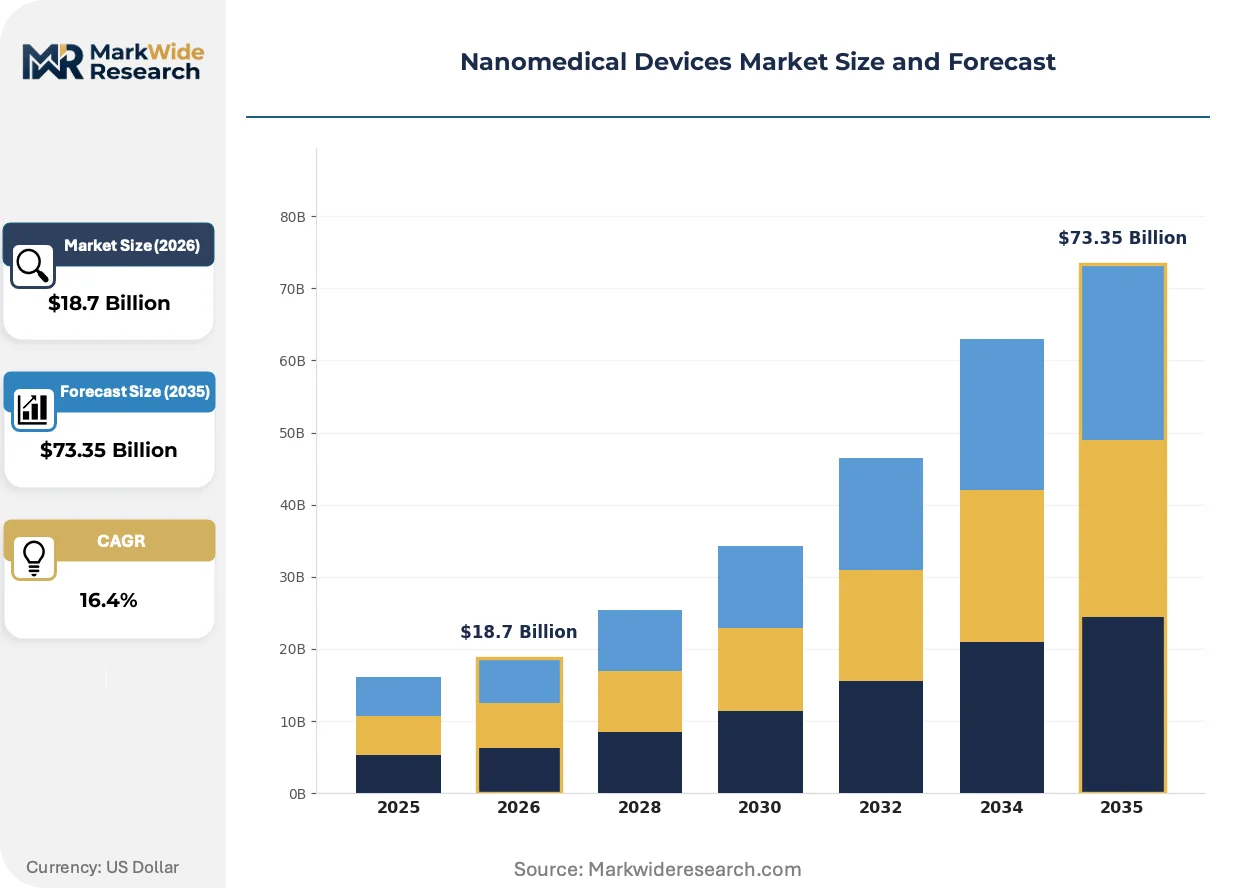
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalable Particles, Targeted Drug Delivery Systems, Nanoparticles, Nanosensors Technology: Polymer Nanotechnology, Lipid-Based Nanocarriers, Nanostructured Coatings, Metal Nanoparticles Application: Cancer Therapy, Imaging Agents, Gene Therapy, Vaccine Development End User: Research Laboratories, Hospitals, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Abbott Laboratories, Johnson & Johnson, Merck & Co., Inc., Pfizer Inc., GE Healthcare, Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, Novartis International AG, Nanobiotix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomedical Devices Market Strategic Shifts
Lipid nanoparticle engineering is fragmenting into application-specific architectures, with manufacturing protocols diverging between mRNA vaccines, small-molecule oncology payloads, and CRISPR delivery systems. This specialization is reshaping competitive positioning across the value chain.
Modular microfluidic synthesis platforms are modularizing production workflows for lipid-based nanocarriers. Contract development and manufacturing organizations in the United States and Switzerland are adopting these systems to enable rapid formulation switching between client programs. The technology is modularizing asset utilization rates, allowing single facilities to serve multiple therapeutic modalities without dedicated cleanroom reconfiguration.
The EU Medical Device Regulation's Annex XVI expansion to nanotechnology-enabled products is forcing manufacturers to reclassify previously exempt diagnostic nanosensors as Class IIa or higher devices. European notified bodies are extending review timelines by 40-60% for submissions lacking nanospecific risk management files. German and French manufacturers are responding by front-loading clinical evidence generation to preempt regulatory queries during conformity assessment.
Hospital procurement committees are consolidating vendor relationships for nanoparticle-based cancer therapies under multi-year system-wide agreements. Group purchasing organizations in the United States are displacing single-hospital contracts, compressing supplier margins while guaranteeing volume commitments. The shift is most visible in academic medical center networks across California, Massachusetts, and Texas, where oncology departments coordinate formulary decisions across 12-20 affiliated hospitals.
Nanomedical Devices Market Segmentation
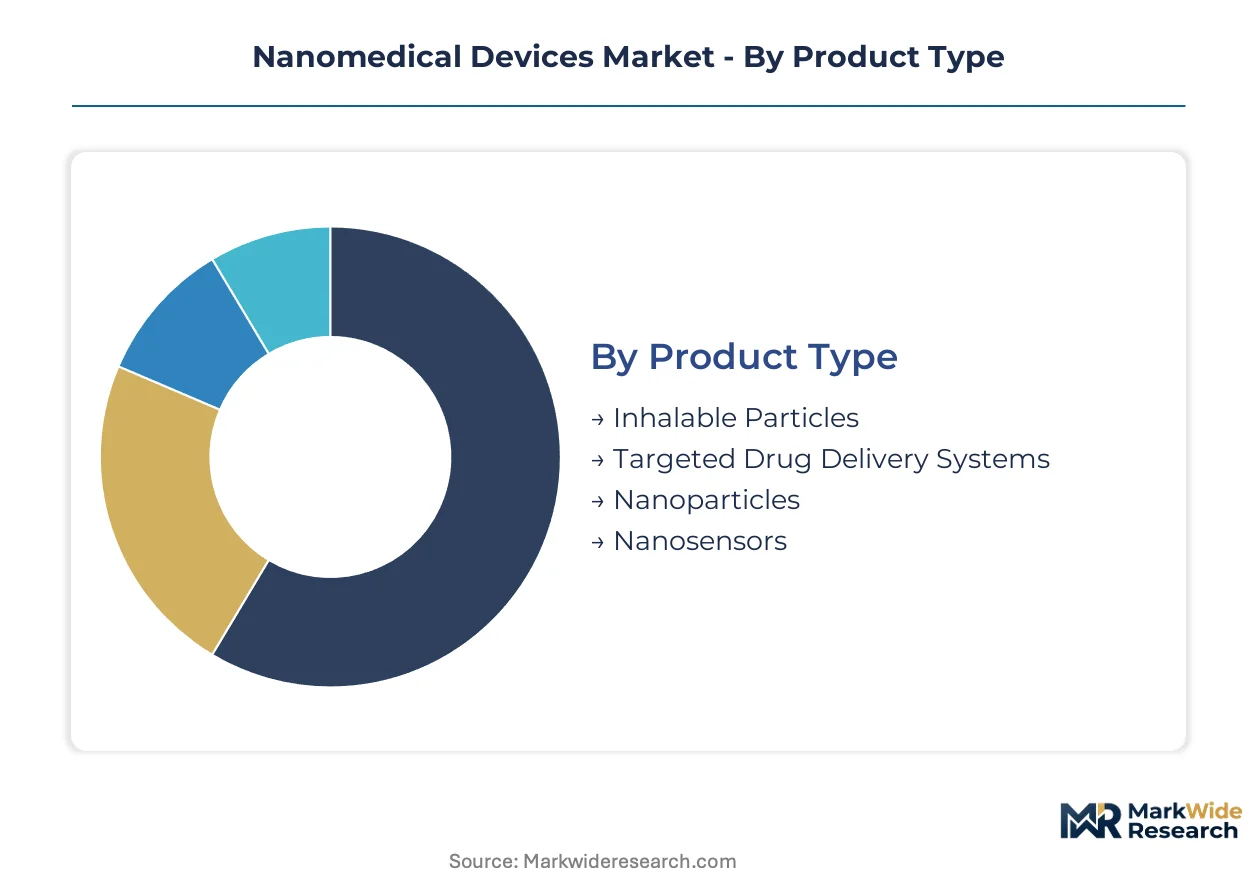
Segmentation in nanomedical devices reveals distinct procurement patterns across technology platforms and clinical settings. Each dimension carries unique regulatory pathways and margin structures that reshape competitive positioning.
Product Type:
Lipid formulation science and surface engineering specifications differentiate therapeutic efficacy and manufacturing scalability across device architectures.
- Targeted Drug Delivery Systems:These architectures employ surface-functionalized nanoparticles with ligand-receptor targeting moieties to concentrate cytotoxic payloads at tumor microenvironments. Academic medical centers in the United States and Germany are expanding group purchasing organization contracts for these systems as FDA and EMA reimbursement pathways mature for nano-enabled oncology therapeutics.
- Nanosensors:Electrochemical and optical transduction platforms detect biomarkers at femtomolar concentrations through noble metal or carbon nanotube interfaces. Point-of-care diagnostic protocols in Japan and South Korea are driving procurement expansion, though legacy hospital IT integration remains a constraint for real-time electronic health record connectivity.
- Inhalable Particles:Engineered porous structures with aerodynamic diameters between 1-5 micrometers enable deep lung deposition of biologics.
- Nanoparticles:Core-shell architectures from gold, silver, or iron oxide serve dual imaging-therapeutic functions.
Mature deployment sits with targeted drug delivery systems. Newer deployment is concentrated in nanosensors.
Technology:
Material selection determines biocompatibility certification requirements and supply chain geographic concentration.
- Lipid-Based Nanocarriers:Ionizable cationic lipids complexed with nucleic acids form the dominant mRNA vaccine and gene editing delivery platform. Johnson & Johnson and Pfizer Inc. have established manufacturing scale for these systems, with ISO 10993-18 chemical characterization now mandatory for FDA submissions.
- Polymer Nanotechnology:PLGA-PEG block copolymers enable tunable drug release kinetics through bulk erosion mechanisms. German and Swiss specialty polymer producers concentrate supply, creating geographic vulnerability for manufacturers dependent on REACH-compliant material streams.
- Metal Nanoparticles:Gold nanoshells and iron oxide cores provide photothermal therapy and magnetic resonance contrast functions.
- Nanostructured Coatings:Sol-gel and atomic layer deposition techniques modify implant surface topography and protein adsorption profiles.
Volume concentration favors lipid-based nanocarriers. Margin expansion is strongest in metal nanoparticles.
Application:
Clinical validation depth and reimbursement density vary sharply across therapeutic domains.
- Cancer Therapy:Lipid nanoparticle and polymer micelle platforms deliver paclitaxel, doxorubicin, and nucleic acid therapeutics to solid tumors. The United States maintains the deepest margin pools here, with academic medical center networks in California, Massachusetts, and Texas coordinating formulary decisions across 12-20 affiliated hospitals.
- Vaccine Development:mRNA-lipid nanoparticle formulations validated through COVID-19 applications now transfer manufacturing protocols to infectious disease and oncology prophylactics. This segment is climbing the fastest as platform standardization shortens development cycles.
- Gene Therapy:Viral and non-viral nanocarriers deliver CRISPR-Cas9 systems and replacement genes.
- Imaging Agents:Superparamagnetic iron oxide and quantum dot constructs enhance magnetic resonance and fluorescence contrast.
Revenue depth concentrates in cancer therapy. Regulatory velocity favors vaccine development.
End User:
Procurement authority and technical specification requirements diverge across institutional categories.
- Hospitals:Group purchasing organizations in the United States are consolidating vendor relationships for nanoparticle-based cancer therapies under multi-year system-wide agreements. Abbott Laboratories anchors its position through diagnostic nanosensor integration with existing laboratory workflows.
- Pharmaceutical Companies:Internal manufacturing scale and contract development organization partnerships govern lipid nanoparticle supply security. Pfizer Inc. competes by extending manufacturing scale for mRNA-lipid nanoparticle formulations.
- Research Laboratories:Academic and government facilities drive early-stage platform validation.
- Biotechnology Firms:Venture-backed developers pursue novel nanocarrier architectures for orphan indications.
Procurement volume aggregates with hospitals. Specification influence concentrates with pharmaceutical companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss specialty polymer production clusters anchor material supply for nanocarrier fabrication, while academic medical centers in the United States and Japan concentrate demand for clinical deployment.
United States
Academic medical center networks in California, Massachusetts, and Texas coordinate formulary decisions across 12-20 affiliated hospitals for nanoparticle-based cancer therapies. FDA nanotechnology guidance frameworks compress premarket timelines while elevating documentation burdens for manufacturers. Greater Boston and San Diego biotech corridors host lipid nanoparticle contract development organizations serving pharmaceutical clients.
Germany
REACH nanomaterial registration mandates standardize supply chain documentation for biocompatible polymer producers concentrated in Baden-Württemberg and North Rhine-Westphalia. The country's national pharmaceutical regulator aligns with EMA nanospecific guidance requirements for clinical trial design. Munich and Heidelberg oncology research institutes drive procurement of targeted drug delivery systems through consolidated group purchasing organization contracts.
Japan
Point-of-care diagnostic protocols in Tokyo and Osaka medical centers expand procurement of nanosensor platforms for multiplexed biomarker detection. METI standards development for nanomaterial characterization supports domestic manufacturing quality assurance. The Kansai region hosts diagnostic nanosensor integration projects with hospital laboratory workflow systems.
Switzerland
ISO 10993-certified polymer production clusters in Basel and Zurich create geographic concentration for lipid-based nanocarrier material supply. Swissmedic regulatory pathways for nano-enabled medical devices emphasize biocompatibility testing infrastructure investment. The Basel pharmaceutical manufacturing corridor anchors contract manufacturing organization capacity for European market access.
India
CDSCO fast-track approval pathways for breakthrough devices attract manufacturers with existing FDA or EMA clearances seeking first-mover positioning. The national pharmaceutical regulator's accelerated channel compresses time-to-market for imported nanomedical technologies. Maharashtra and Gujarat pharmaceutical manufacturing zones develop domestic lipid nanoparticle formulation capabilities for regional supply.
Nanomedical Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue point-of-care diagnostic specialization and AI-driven nanocarrier design. The vendor base stratifies across three tiers: diversified healthcare conglomerates with manufacturing scale, mid-scale specialists in lipid formulation science, and venture-backed developers of novel targeting moieties. Dominant competitive moves include strategic partnerships for microfluidic synthesis platform access and backward integration into specialty polymer supply chains.
Within the diversified healthcare conglomerate tier, Abbott Laboratories and Johnson & Johnson represent archetypal positions anchored through diagnostic nanosensor integration and lipid-based nanocarrier R&D intensity respectively. Pfizer Inc. occupies a scale-driven position exemplifying manufacturing extension for mRNA-lipid nanoparticle formulations. These three entities collectively illustrate how incumbent players defend position through vertical control over formulation science and hospital procurement channel access.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Pfizer Inc. |
| GE Healthcare |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| Novartis International AG |
| Nanobiotix |
| Others |
Value Chain & Pricing Dynamics
Modular microfluidic synthesis platforms are fragmenting production economics across lipid-based nanocarrier manufacturing, simultaneously compressing unit costs for contract development organizations while concentrating equipment supply among Swiss and United States precision engineering firms. This technology transition is reshaping how manufacturers balance captive production against outsourced formulation services.
Pricing Analysis
Service bundling separates equipment-only transactions from full formulation-development contracts, with United States contract manufacturing organizations commanding premiums for integrated regulatory dossier preparation. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993-18 certification depth and FDA master file availability. Cost compression in standard-tier lipid nanoparticle production is intensifying because German polymer suppliers are extending volume rebates to qualified buyers. Academic medical center networks exhibit lowest price sensitivity due to reimbursement pathway security, while emerging biotechnology firms face acute procurement constraints.
Supply Chain Analysis
Dual-sourcing requirements for ionizable cationic lipids now mandate qualified backup suppliers across Germany, Switzerland, and the United States to satisfy FDA drug master file expectations. Raw material streams draw from specialty polymer production clusters, noble metal refineries, and cell-culture media suppliers. Single-source vulnerability concentrates in ISO 10993-certified polymer supply where Baden-Württemberg and Basel facilities control critical PLGA-PEG block copolymer grades. Distribution runs through pharmaceutical-grade cold-chain logistics networks serving hospital pharmacies and contract manufacturing organization facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanomedical devices sector is executing a platform transition from legacy polymer micelle architectures toward lipid nanoparticle systems validated through mRNA vaccine applications. This substitution is compressing development timelines and reshaping competitive moats around manufacturing scale rather than molecular discovery.
For Market Incumbents: To counter emerging AI-driven nanocarrier design firms, Johnson & Johnson and Pfizer Inc. should deepen backward integration into ionizable lipid supply chains while locking multi-year group purchasing organization contracts across California and Texas academic medical center networks. Captive control over formulation science and procurement channel access remains the defensive priority.
For New Entrants and Emerging Players: Begin with point-of-care diagnostic nanosensor deployment in Japan and South Korea where hospital laboratory workflow integration lags and regulatory pathways are clarifying under METI standards development. The most penetrable white space sits in multiplexed biomarker detection outside oncology, with go-to-market execution hinging on electronic health record connectivity partnerships.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified healthcare conglomerates seeking lipid nanoparticle manufacturing scale, with initial public offering windows requiring demonstrated commercial revenue from FDA-cleared devices. Target acquisition profiles center on venture-backed developers with validated targeting moieties and existing contract manufacturing organization relationships. The signal to watch is CDSCO fast-track approval momentum for breakthrough device candidates with prior FDA or EMA clearances.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Front-Loading | German and French manufacturers preempt EMA nanospecific queries by accelerating clinical evidence generation ahead of submission. |
| Microfluidic Platform Partnership | Contract development organizations in Greater Boston and San Diego secure rapid formulation switching capabilities across client programs. |
| Group Purchasing Organization Consolidation | United States academic medical center networks displace single-hospital contracts for nanoparticle-based cancer therapies. |
| CDSCO Fast-Track Positioning | Manufacturers with existing FDA clearances exploit India's accelerated approval channel for first-mover market entry. |
| AI-Driven Lead Optimization | Machine learning convergence with lipid formulation science compresses targeted delivery system development timelines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning nanomaterial scientists, regulatory affairs leads, hospital procurement managers, and contract manufacturing organization executives. FDA nanotechnology guidance documents, EMA submission dossiers, ISO 10993 biocompatibility standards, and REACH nanomaterial registration databases furnished validation sources. Bottom-up segmentation modeling and top-down market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across volume and value outputs employed a triangulated analytical framework spanning the projection horizon. Segmentation dimensions modeled include product type, technology platform, therapeutic application, and end-user procurement authority. CAGRs were derived from normalized growth trajectory analysis against baseline clinical validation milestones and reimbursement pathway maturation curves. Forecast inputs incorporated lipid nanoparticle manufacturing scale expansion rates and regulatory approval velocity by jurisdiction.
Underlying measurement precision varies by segment; targeted drug delivery systems and lipid-based nanocarriers carry tighter precision than emerging nanosensor categories where commercial deployment remains sparse. Forecasts reflect assumptions regarding FDA and EMA guidance stability, polymer supply chain continuity, and hospital procurement committee consolidation trajectories. A model refresh is warranted upon material change in EMA nanospecific documentation requirements or breakthrough device designation velocity at CDSCO.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Coatings Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Respiratory Devices Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Silastic Implant Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Spine Surgery Robots Market