
 Nano Healthcare Technology Market | 2026-2036
Nano Healthcare Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Healthcare Technology Market Analytics
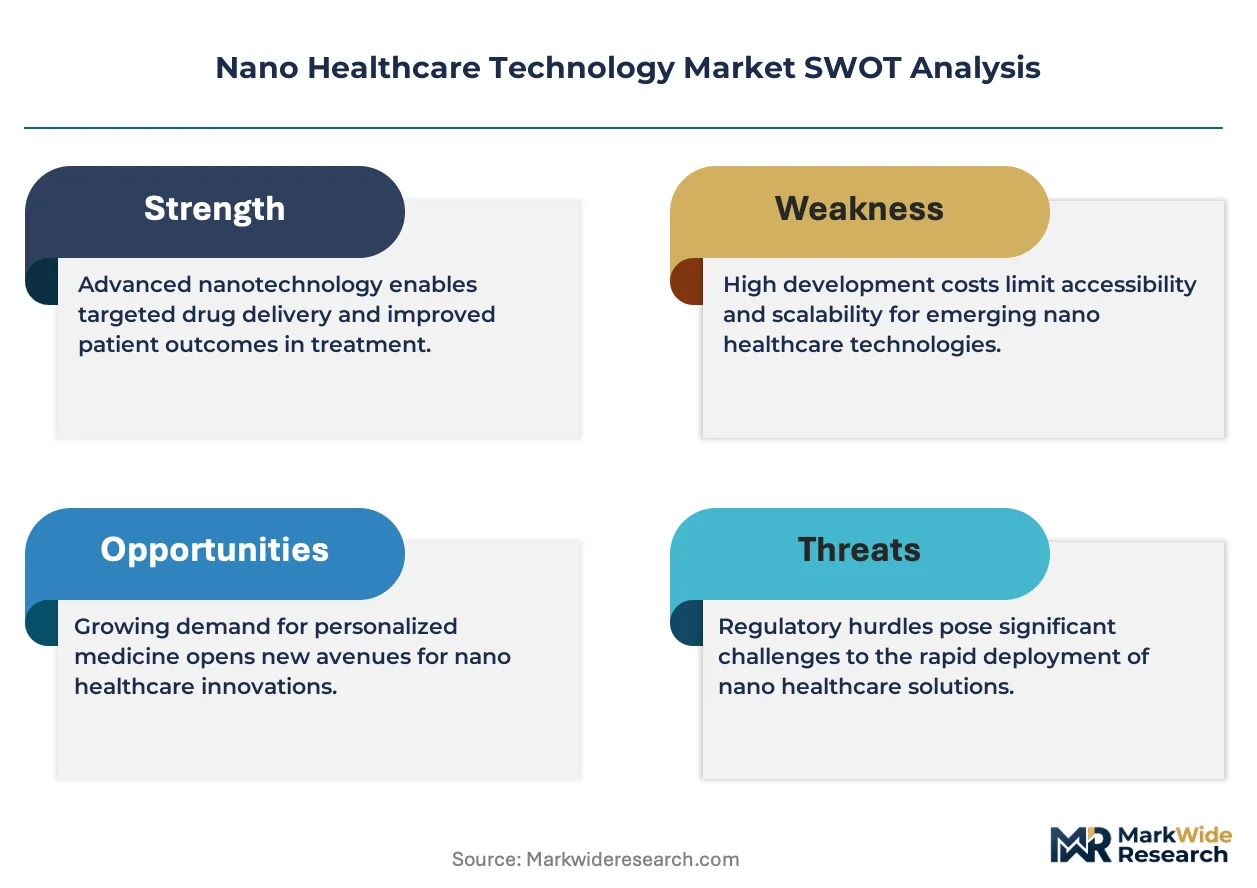
ISO/TS 19337:2016 qualification for nanoparticle-based biopharmaceuticals is unwinding competitive access for firms lacking validated manufacturing controls. Pfizer Inc. leverages its lipid nanoparticle platform expertise to anchor positions in mRNA therapeutics. Nanobiotix specializes in radio-enhancing nanoparticles for oncology, sustaining clinical differentiation through tumor-specific activation mechanisms. Johnson & Johnson controls orthopedics and wound care nano-coating segments through extensive patent estates.
Nano healthcare technology encompasses engineered structures with at least one dimension between 1-100 nanometers, designed for therapeutic intervention, targeted drug delivery, or molecular-scale diagnostic detection; liposomal formulations and polymeric micelles represent dominant manufacturing architectures achieving enhanced permeability and retention in tumor vasculature. Diagnostic Tools command established revenue streams through quantum dot imaging agents and magnetic nanoparticle contrast media, while Delivery Systems capture expanding margin pools as gene therapy vectors require sophisticated encapsulation technologies. Targeted Therapy within the Application dimension shows accelerating clinical translation, though Imaging maintains volume leadership through established radiology department procurement cycles.
FDA nanotechnology regulatory guidance, EMA reflection papers on nanomedicine quality, and ISO 10993 biocompatibility standards collectively govern preclinical characterization requirements and post-market surveillance obligations for nano-enabled products. These frameworks elevate compliance costs for entrants while rewarding incumbents with existing quality management infrastructure. Stakeholders must monitor evolving pharmacovigilance expectations for long-acting nanoparticle depots as real-world evidence requirements intensify.
Market Dynamics
ISO/TS 19337:2016 qualification requirements are compressing competitive access for firms lacking validated manufacturing controls, rewarding incumbents with existing quality management infrastructure while elevating barriers for new entrants in nanoparticle-based biopharmaceuticals.
Growth Catalysts
- FDA Accelerated Approval Pathways:Nanomedicine developers benefit from streamlined review timelines for breakthrough therapies, reducing time-to-market for oncology and rare disease indications.
- mRNA Therapeutic Expansion:Lipid nanoparticle encapsulation platforms anchor positions in gene therapy vectors, with demand concentrating around Boston and San Diego biotech corridors.
- EMA Reflection Papers on Nanomedicine Quality:European regulatory clarity provides development roadmaps that reduce regulatory uncertainty for cross-border product registration.
Market Restraints
- Specialized Manufacturing Infrastructure:Aseptic nanoscale production requires capital-intensive cleanroom facilities and validated process analytical technology, limiting contract manufacturing options.
- Raw Material Concentration:High-purity lipids and functionalized polymers for nanoparticle synthesis concentrate among a narrow supplier base, creating input cost volatility.
- Long-Acting Depot Surveillance:FDA pharmacovigilance expectations for sustained-release nanoparticle formulations intensify post-market evidence collection burdens.
Strategic Opportunities
- Radio-Enhancing Oncology Platforms:Tumor-specific activation mechanisms in radiotherapy enhancement represent underpenetrated clinical applications with premium pricing potential.
- Quantum Dot Diagnostic Agents:Multiplexed molecular imaging capabilities create white space in precision pathology workflows beyond conventional immunohistochemistry.
- India PLI Scheme for Pharmaceuticals:Production-linked incentives for active pharmaceutical ingredients and formulations attract nanomedicine manufacturing investment.
Industry Challenges
- Cross-Functional Talent Scarcity:Nanomedicine development requires rare combinations of formulation science, regulatory affairs, and clinical trial design expertise.
- ISO 10993 Biocompatibility Testing:Extended characterization timelines for novel nanomaterials delay preclinical-to-clinical transitions.
- Patent Estate Navigation:Dense intellectual property thickets around polymeric micelle architectures and surface modification chemistries complicate freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Healthcare Technology Market |
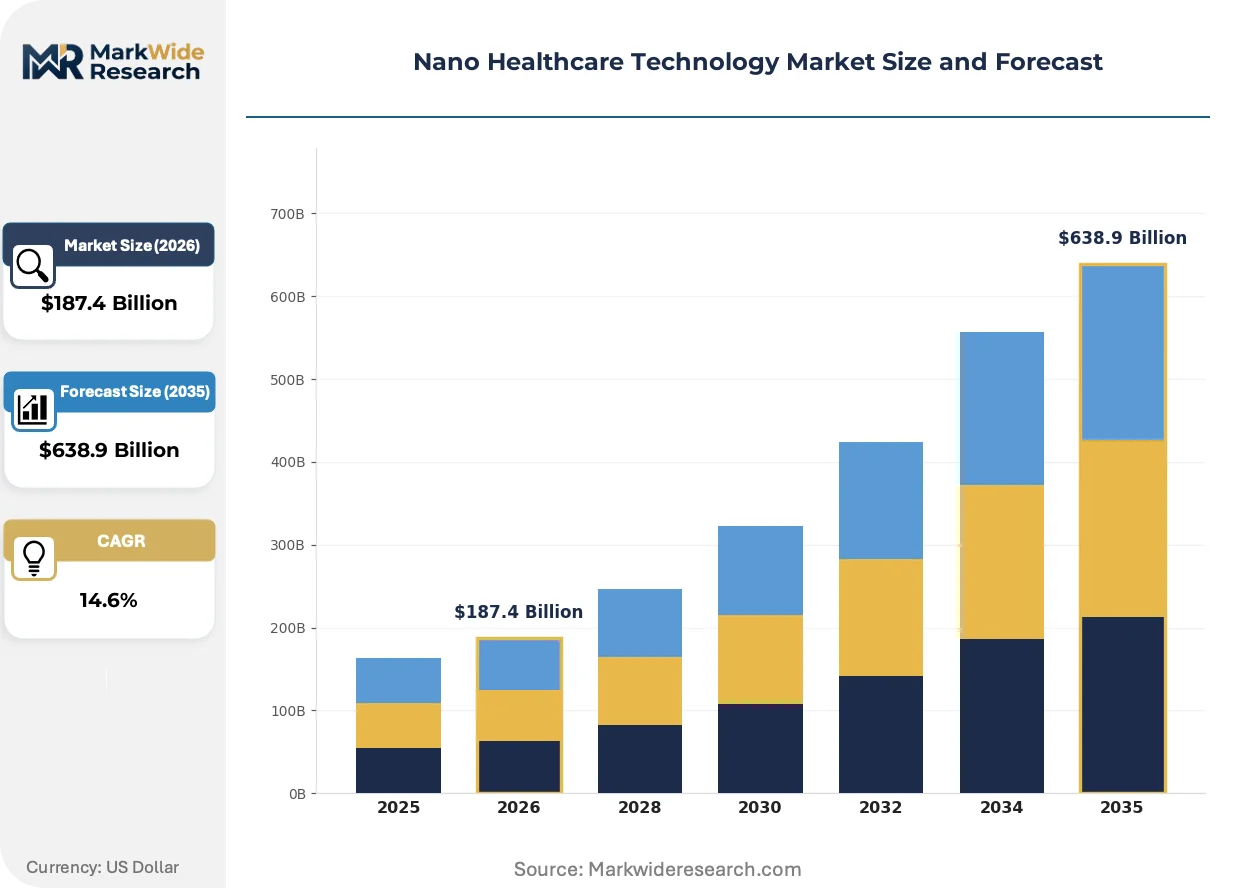
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano Drugs, Delivery Systems, Diagnostic Tools, Imaging Agents End User: Hospitals, Research Facilities, Pharmaceutical Companies, Diagnostic Laboratories Application: Treatment, Imaging, Drug Delivery, Diagnostics Technology: Nanotechnology, Bioengineering, Molecular Imaging, Targeted Therapy |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Merck & Co. Inc., Sanofi SA, Bristol-Myers Squibb Company, Novartis AG, Nanobiotix, Abbott, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Healthcare Technology Market Evolving Landscape
Clinical translation of nanoparticle therapeutics is bifurcating development pathways, with established liposomal architectures facing displacement from next-generation polymeric and inorganic platforms engineered for stimulus-responsive drug release.
Lipid nanoparticle technology is bifurcating into two distinct commercial tracks. Conventional liposomal doxorubicin formulations face commoditization pressure as biosimilar entrants multiply. Ionizable lipid architectures for mRNA delivery command premium valuations from gene therapy developers seeking tissue-specific transfection efficiency. This divergence compresses margins in mature oncology indications while enabling pricing power in rare disease and personalized vaccine applications.
EMA nanomedicine reflection papers are clarifying quality attribute expectations for complex drug products. Manufacturers must demonstrate batch-to-batch consistency for critical quality attributes including particle size distribution, surface charge, and drug loading. Oncology and immunology segments are responding by investing in process analytical technology and real-time release testing capabilities to preempt regulatory scrutiny.
Academic medical center procurement is consolidating supplier relationships around integrated nanomedicine platforms. Radiology departments and oncology infusion centers increasingly specify end-to-end solutions encompassing imaging agents, therapeutic payloads, and companion diagnostics. This pattern concentrates purchasing influence at major cancer centers in the United States, with European university hospitals following similar consolidation trajectories.
Nano Healthcare Technology Market Segmentation
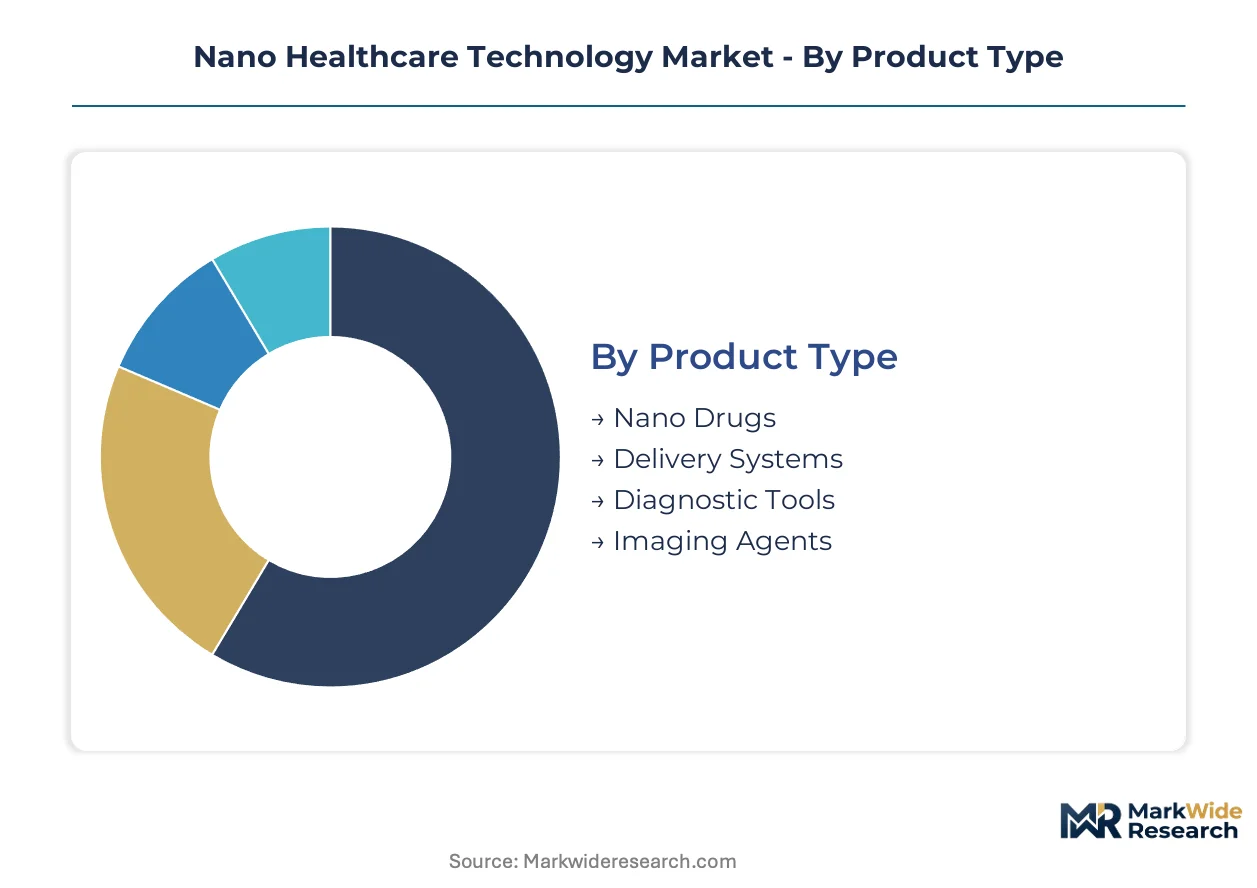
Nano healthcare technology segments diverge sharply in regulatory burden and manufacturing complexity. FDA breakthrough therapy designations cluster in drug delivery applications, while diagnostic tools face more predictable 510(k) pathways.
Product Type:
FDA accelerated approval pathways favor lipid nanoparticle platforms over conventional liposomal formulations, compressing development timelines for mRNA encapsulation technologies while extending scrutiny for metallic nanoparticle architectures.
- Delivery Systems:Lipid nanoparticles and polymeric micelles achieve enhanced permeability in tumor vasculature through size-tuned architectures between 10-200 nanometers. Demand concentrates at academic medical centers in Boston and San Diego seeking tissue-specific transfection efficiency for gene therapy vectors.
- Diagnostic Tools:Quantum dot imaging agents and magnetic nanoparticle contrast media enable multiplexed molecular detection with photostability exceeding organic fluorophores. Radiology departments in the United States specify these for precision pathology workflows beyond conventional immunohistochemistry.
- Nano Drugs:Therapeutic nanoparticles incorporating active pharmaceutical ingredients into core-shell architectures for controlled release kinetics.
- Imaging Agents:Contrast-enhancing nanomaterials functionalized with targeting ligands for specific tissue accumulation and signal amplification.
Delivery Systems handles the majority of throughput; Diagnostic Tools is the fastest mover on share.
End User:
Procurement authority concentrates at integrated cancer centers with combined radiology and oncology infusion capabilities, forcing suppliers to bundle imaging agents with therapeutic payloads.
- Hospitals:Academic medical centers anchor purchasing volume through consolidated supplier relationships spanning imaging agents, therapeutic nanoparticles, and companion diagnostics. Oncology departments at major cancer centers in the United States drive specification requirements for radio-enhancing platforms.
- Pharmaceutical Companies:Gene therapy developers seek validated manufacturing controls for ionizable lipid architectures, with in-house production investments rising to secure supply chain continuity for clinical trial materials.
- Research Facilities:University laboratories conduct preclinical characterization of novel nanomaterials under ISO 10993 biocompatibility protocols.
- Diagnostic Laboratories:Clinical pathology operations implement quantum dot-based multiplexed assays for precision diagnostics.
Hospitals command the dominant procurement volume; Pharmaceutical Companies are expanding most quickly as vertical integration accelerates.
Application:
Margin pools align with clinical translation maturity, with established imaging applications facing pricing pressure while targeted therapy commands premium valuations.
- Drug Delivery:Nanoparticle encapsulation enables solubility enhancement, sustained release kinetics, and tissue-specific accumulation for compounds with poor bioavailability. Gene therapy vectors utilizing lipid nanoparticle platforms concentrate demand around rare disease and personalized vaccine applications.
- Targeted Therapy:Tumor-specific activation mechanisms in radio-enhancing nanoparticles create premium pricing potential in radiotherapy enhancement indications with limited competitive alternatives.
- Imaging:Contrast agent applications in radiology departments maintain volume leadership through established procurement cycles and reimbursement pathways.
- Treatment:Direct therapeutic intervention using nanoparticle-based modalities including photothermal ablation and photodynamic therapy.
Imaging maintains established revenue scale; Targeted Therapy shows the steepest expansion trajectory as clinical translation accelerates.
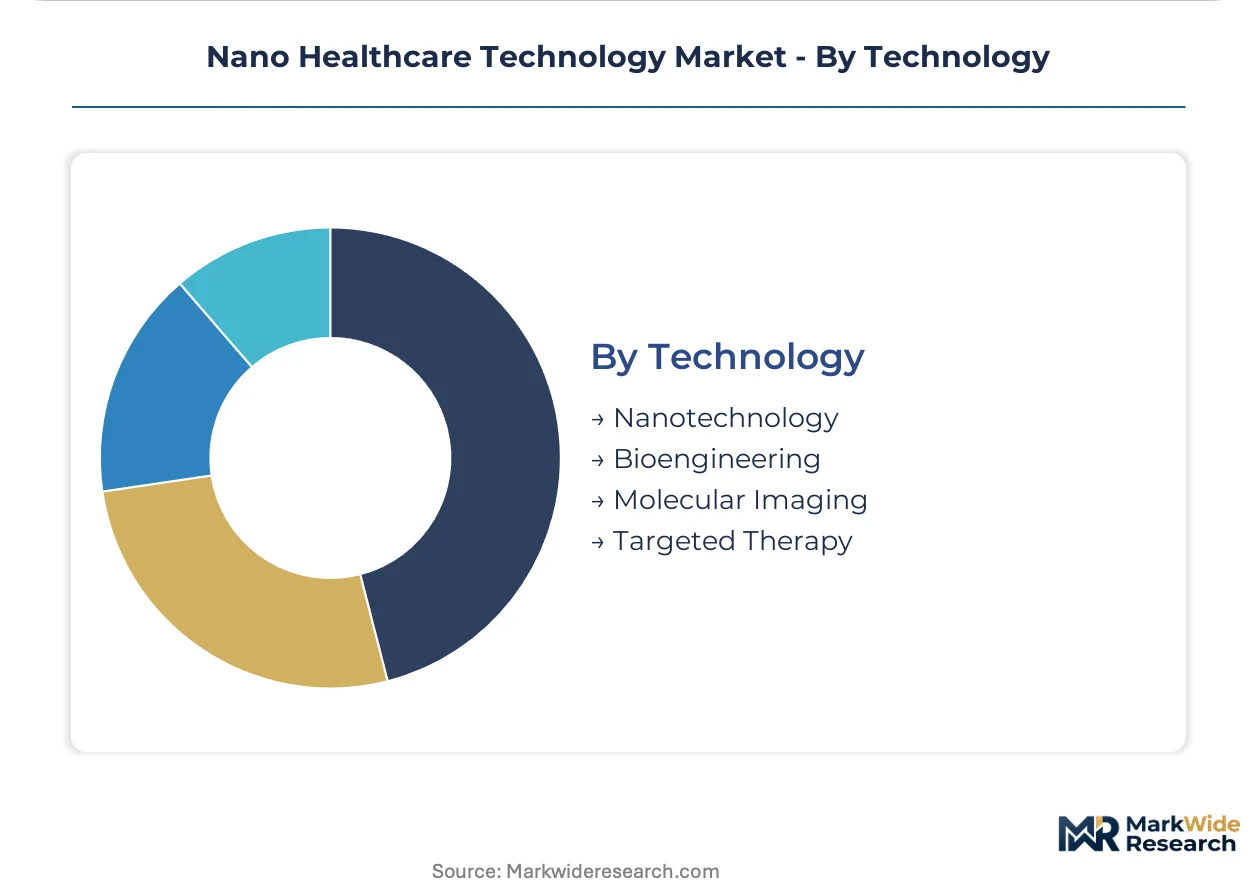
Technology:
Patent estate density varies dramatically across technology platforms, with polymeric micelle architectures presenting dense intellectual property thickets that complicate freedom-to-operate assessments.
- Nanotechnology:Engineered structures with at least one dimension between 1-100 nanometers designed for therapeutic intervention or molecular-scale diagnostic detection. ISO/TS 19337:2016 qualification requirements compress competitive access for firms lacking validated manufacturing controls.
- Targeted Therapy:Surface-functionalized nanoparticles with ligand-directed specificity for receptor-overexpressing cell populations. EMA reflection papers on nanomedicine quality provide development roadmaps that reduce regulatory uncertainty for cross-border registration.
- Bioengineering:Integration of biological recognition elements with synthetic nanomaterials for bioresponsive drug release.
- Molecular Imaging:Nanoparticle-based contrast agents enabling detection of molecular biomarkers with enhanced sensitivity.
Nanotechnology underpins the broadest application base; Targeted Therapy is gaining share fastest through clinical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive nanomedicines. Boston's Logan International Airport anchors North American air freight corridors for clinical trial materials. Singapore's Changi Airport free trade zone enables Asia-Pacific transshipment of high-value diagnostic nanoparticles.
United States
FDA accelerated approval pathways for nanomedicines concentrate gene therapy vector demand in Greater Boston and San Diego biotech corridors. The Biologics Price Competition and Innovation Act shapes patent cliff strategies for liposomal formulations. Massachusetts General Hospital and Dana-Farber Cancer Institute anchor procurement authority for radio-enhancing oncology platforms.
Germany
EMA reflection papers on nanomedicine quality reduce regulatory uncertainty for cross-border product registration from German manufacturing sites. The country's national pharmaceutical regulator enforces ISO/TS 19337:2016 qualification requirements for nanoparticle-based biopharmaceutical exports. Heidelberg and Munich academic medical centers consolidate supplier relationships around integrated nanomedicine platforms.
China
NMPA innovation pathways for breakthrough therapies attract lipid nanoparticle platform investments from domestic gene therapy developers. Dual carbon goals accelerate green chemistry mandates for nanoparticle synthesis processes. Shanghai Zhangjiang Hi-Tech Park concentrates contract manufacturing capacity for ionizable lipid architectures serving regional vaccine programs.
India
CDSCO streamlined approval mechanisms for complex drug products enable faster market entry for polymeric micelle formulations. The PLI scheme for pharmaceuticals attracts active pharmaceutical ingredient and nanomedicine manufacturing investment from multinational sponsors. Hyderabad and Bangalore clusters develop process analytical technology capabilities for export-oriented nanoparticle production.
Switzerland
Swissmedic alignment with EMA quality standards positions Basel and Zurich as regulatory launch pads for European nanomedicine registration. The country's national pharmaceutical regulator maintains accelerated assessment pathways for orphan drug nanoparticle indications. Novartis and Roche anchor supplier ecosystems for diagnostic nanoparticle contrast agents across radiology departments.
Nano Healthcare Technology Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory infrastructure dimensions. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with validated quality management systems, mid-cap biotech firms with platform-specific expertise, and emerging specialists with stimulus-responsive release technologies. Strategic archetypes include lipid nanoparticle platform licensors, radio-enhancing oncology developers, and diagnostic imaging agent suppliers. Competitive moves concentrate on backward integration into ionizable lipid supply and capacity expansion in aseptic nanoscale production facilities.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. occupy positions spanning orthopedics nano-coating and mRNA therapeutic encapsulation respectively. Nanobiotix exemplifies the radio-enhancing oncology specialist archetype with tumor-specific activation mechanisms. These three entities anchor competitive dynamics across the delivery systems and targeted therapy segments without exclusive territorial claims.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Sanofi SA |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Nanobiotix |
| Abbott |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
ISO/TS 19337:2016 qualification gates both supply qualification and price differentiation simultaneously, restricting contract manufacturing access to firms with validated process analytical technology while enabling premium pricing for ionizable lipid architectures serving gene therapy developers. Academic medical centers in Boston and San Diego concentrate procurement authority, compressing margins for conventional liposomal formulations while sustaining pricing power for tissue-specific transfection platforms.
Pricing Analysis
Volume-discount tiering structures separate ionizable lipid platforms for mRNA delivery from commoditized liposomal doxorubicin formulations, with pricing stratifying across premium, standard, and economy tiers based on certification grade and customization level. Cost compression in mature oncology indications intensifies as biosimilar entrants multiply, while gene therapy vectors command reduced price sensitivity from pharmaceutical companies seeking supply security for clinical trial materials.
Supply Chain Analysis
Just-in-time inventory strategies dominate for temperature-sensitive clinical trial materials, though strategic stockpiling of high-purity lipids and functionalized polymers buffers against raw material concentration among narrow supplier bases. Manufacturing draws from the United States, Germany, and China for aseptic nanoscale production, with single-source vulnerability in ionizable lipid feedstocks creating exposure to regulatory restriction. Distribution runs through academic medical center procurement departments consolidating around integrated platform suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware in nano healthcare technology, with process analytical technology consulting and real-time release testing validation capturing recurring revenue streams beyond nanoparticle formulation supply.
For Market Incumbents: Shield market position by deepening backward integration into ionizable lipid supply and expanding aseptic manufacturing capacity in Germany to preempt EMA quality scrutiny. Patent estate thickets around polymeric micelle architectures require active freedom-to-operate monitoring against emerging stimulus-responsive release specialists. For New Entrants and Emerging Players: Companion diagnostic software layers represent under-served white space where incumbents lack integrated imaging-therapy platforms. Radio-enhancing oncology applications in European university hospitals offer the most penetrable entry point, with go-to-market acceleration through academic medical center pilot programs preceding regulatory submission. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy vector manufacturing as in-house production investments rise. Long-term viability across the analysis window favors platform licensors with validated quality management infrastructure over asset-specific developers. Watch FDA pharmacovigilance guidance for sustained-release depots as the signal indicating regulatory burden expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Aseptic nanoscale capacity expansion in Germany reduces EMA qualification timelines for cross-border registration. |
| Backward Integration | Captive ionizable lipid supply secures continuity for clinical trial materials amid raw material concentration. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for oncology and rare disease indications. |
| Hospital System Partnership | Integrated platform bundling with Massachusetts General Hospital concentrates procurement influence in radiology and oncology. |
| Pipeline Diversification | Stimulus-responsive release technologies displace conventional liposomal architectures in next-generation therapeutic portfolios. |
Research Methodology
Desk research of FDA filings, EMA reflection papers, ClinicalTrials.gov entries, and ISO standard documentation preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Primary fieldwork combined with secondary validation through hospital procurement databases and GPO contracts, with bottom-up segment sizing triangulated against top-down market aggregation.
Variance decomposition across product type, application, end user, and regional regulatory cluster dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level growth trajectory modeling incorporated gene therapy pipeline advancement rates and academic medical center capital expenditure cycles as industry-specific inputs.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA nanomedicine quality frameworks; material policy shifts would require re-modeling. Revision becomes warranted when pharmacovigilance burden thresholds for long-acting depots cross materially higher compliance cost boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Telehealth Device Market
Medical Devices
US Clear Aligners Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
EEG Amplifiers Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Baby Thermometer Market