
 Testicular Cancer Treatment Market | 2026-2036
Testicular Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Testicular Cancer Treatment Market Analytics
Modular protocol bundling is broadening buyer choice across chemotherapy, radiation therapy, and surgery combinations. Bristol Myers Squibb leverages its immuno-oncology portfolio to anchor positions in checkpoint inhibitor development. Merck & Co. sustains R&D intensity across targeted therapy platforms. Pfizer Inc competes through manufacturing scale in cytotoxic agent supply chains.
Testicular cancer treatment encompasses surgical intervention, cytotoxic chemotherapy, external beam radiation, and systemic hormonal modulation administered to eliminate germ cell malignancies and prevent metastatic progression. Platinum-based regimens remain the backbone of first-line intervention, with carboplatin and cisplatin formulations specified by tumor histology and staging parameters. Chemotherapy segments occupy the largest value share due to established reimbursement and protocol standardization, while immunotherapy segments represent the fastest-expanding margin pool as PD-1 and CAR-T platforms advance through clinical pipelines. Targeted therapy segments concentrate premium pricing around biomarker-identified patient subsets with specific genetic alterations.
FDA oversight shapes drug approval pathways and post-market surveillance requirements for testicular cancer therapeutics in the United States, while EMA centralized procedures govern market access across European Union member states. NMPA regulatory frameworks in China increasingly align with ICH guidelines, accelerating multinational trial participation and product registration timelines. Stakeholders must monitor evolving biomarker-driven labeling expansions and companion diagnostic co-development requirements to secure competitive positioning.
Market Dynamics
Checkpoint inhibitor development is restructuring competitive positioning across testicular cancer protocols, as PD-1 and PD-L1 platforms displace platinum-based monotherapy in relapsed settings and force protocol redesign at major oncology centers.
Growth Catalysts
- Biomarker-driven labeling:Companion diagnostic co-development with FDA and EMA is expanding addressable patient populations through histology-specific indications.
- Japan's PMDA accelerated pathways:Reduced review timelines for orphan oncology indications are shortening market entry lag for novel immunotherapies.
- CAR-T manufacturing scale-up:Automated cell processing platforms are compressing production cycles and enabling decentralized treatment delivery.
Market Restraints
- Platinum supply concentration:Refining capacity bottlenecks in South Africa and Russia are creating input cost volatility for cisplatin and carboplatin formulations.
- EMA centralized procedure delays:Post-Brexit workload redistribution is extending marketing authorization timelines for combination therapies.
- Curative surgery substitution:High retroperitoneal lymph node dissection success rates in early-stage seminoma are limiting adjuvant chemotherapy addressability.
Strategic Opportunities
- Germany's Diagnosis-Related Group reform:Outpatient chemotherapy reimbursement expansion is shifting site-of-care economics toward community oncology networks.
- Digital pathology integration:AI-assisted histopathology review is converging with telemedicine platforms to enable remote expert consultation in underserved regions.
- India's CDSCO streamlined registration:Reliance on foreign trial data and priority review vouchers is reducing entry barriers for biosimilar platinum agents.
Industry Challenges
- Cell therapy manufacturing talent scarcity:Shortages of vector production specialists and GMP facility operators are constraining CAR-T capacity expansion.
- Cross-border trial harmonization:Divergent NMPA and FDA data requirements are complicating multinational study design and patient recruitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testicular Cancer Treatment Market |
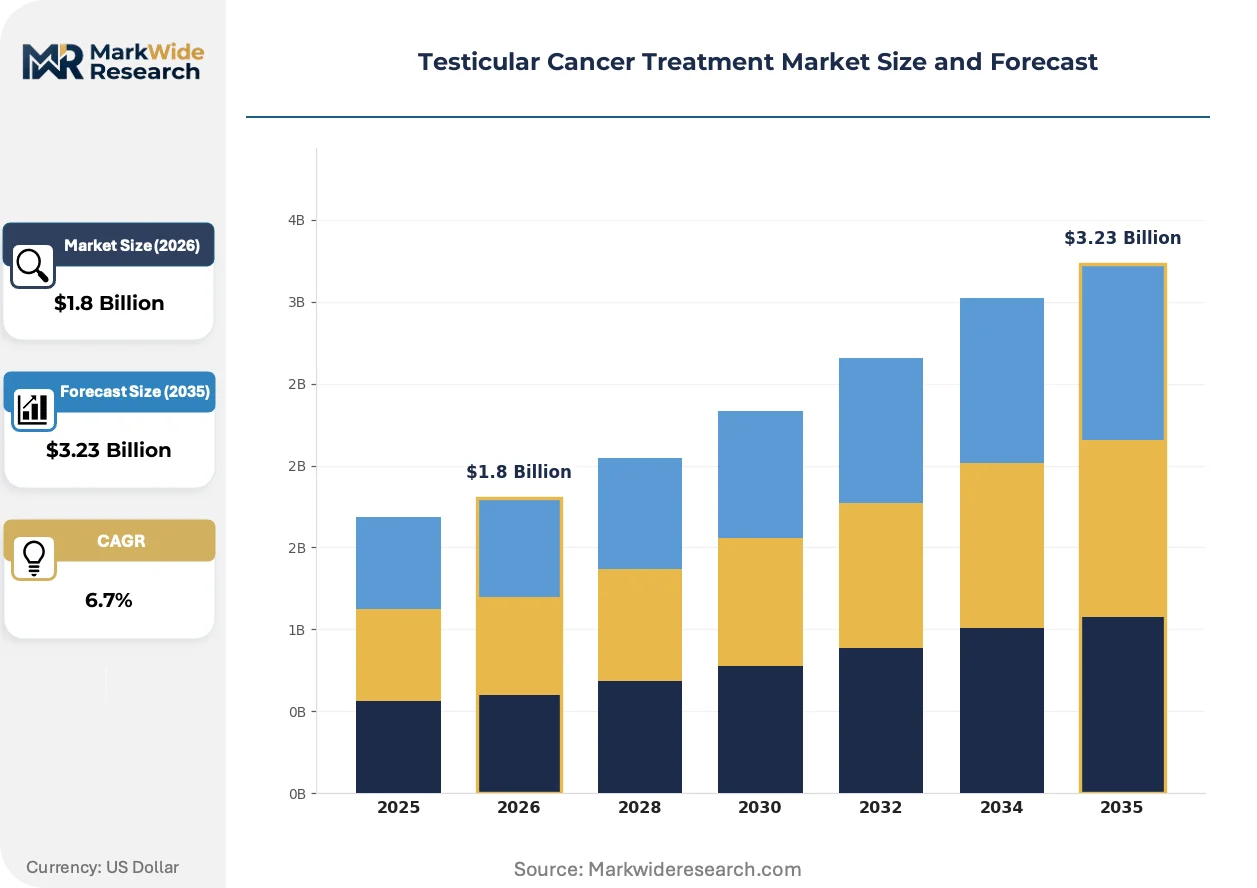
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Surgery, Hormonal Therapy End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular Technology: Conventional, Targeted Therapy, Immunotherapy, Gene Therapy |
| Companies Covered | Pfizer Inc, Bristol Myers Squibb, Merck & Co., Novartis AG, F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries, Fresenius Kabi, BioNTech SE, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testicular Cancer Treatment Market Evolving Landscape
Immunotherapy platform maturation is compressing development timelines and forcing legacy cytotoxic manufacturers to reposition around combination regimens and supportive care portfolios.
Liquid biopsy monitoring is converging with circulating tumor DNA sequencing to enable real-time treatment response assessment without repeated surgical sampling. Academic medical centers in the United States and Germany are adopting these platforms for surveillance protocols. This convergence is compressing the interval between progression detection and protocol switch decisions.
EMA's Medical Device Regulation is imposing new clinical evidence requirements on companion diagnostic co-development, extending validation timelines for biomarker-linked therapies. Manufacturers must now generate prospective diagnostic accuracy data alongside therapeutic efficacy trials. Oncology divisions are responding by front-loading diagnostic development budgets and securing parallel scientific advice meetings.
Site-of-care migration is accelerating as hospital outpatient departments lose reimbursement advantages to freestanding infusion centers under United States Medicare payment restructuring. Community oncology practices in Texas and Florida are capturing volume through lower overhead structures. This channel shift is visible most acutely in platinum-based regimen administration where monitoring intensity permits decentralized delivery.
Testicular Cancer Treatment Market Segmentation
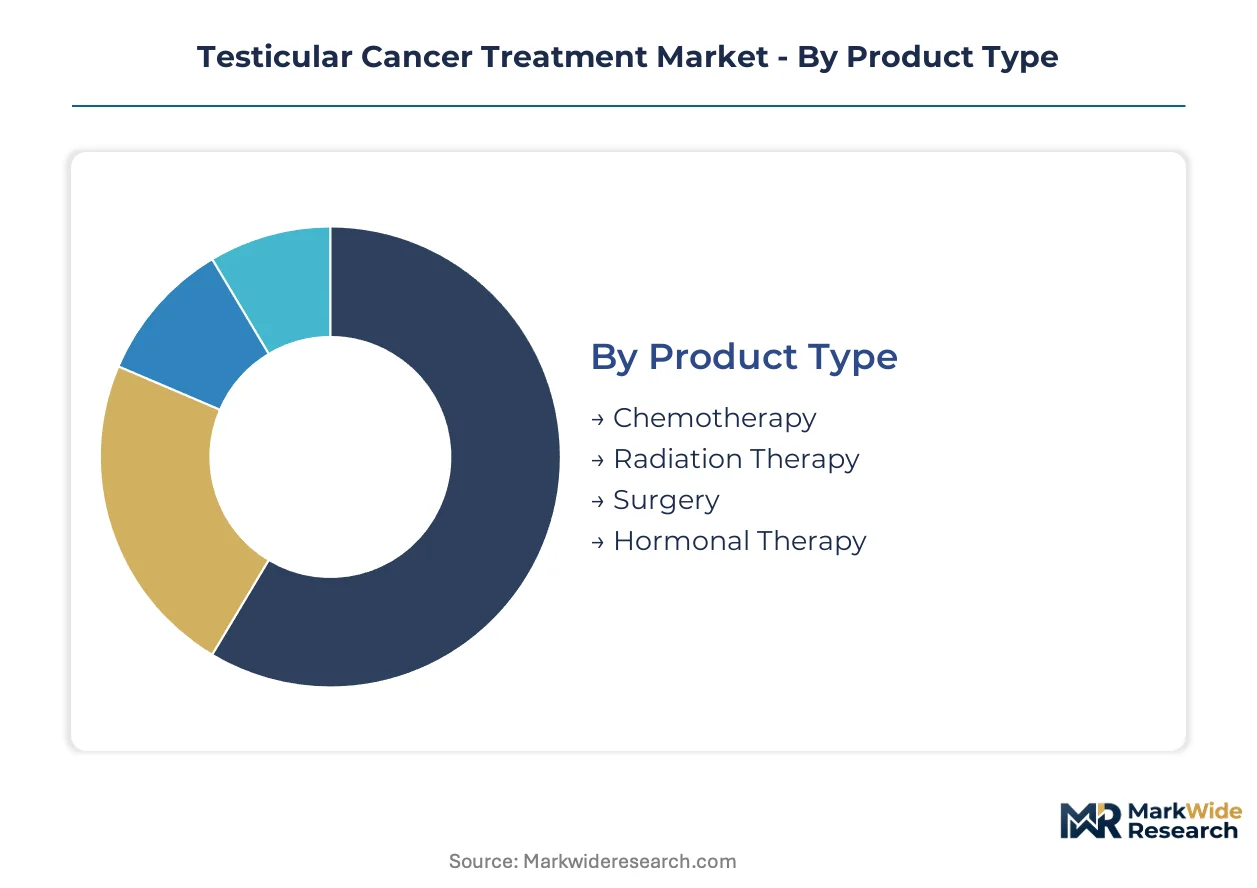
Testicular cancer treatment protocols vary sharply by tumor histology and staging, creating distinct procurement patterns across therapeutic modalities. Segmentation reveals where platinum-based regimens retain dominance versus where immunotherapy platforms are gaining protocol share.
Product Type:
Chemotherapy commands volume leadership through established reimbursement, while immunotherapy captures premium expansion despite smaller patient bases.
- Chemotherapy:Platinum-based agents—cisplatin, carboplatin, and etoposide combinations—constitute first-line intervention for metastatic germ cell tumors. Demand concentrates in United States hospital outpatient departments and Germany's community oncology networks, where protocol standardization supports high-throughput administration. Reimbursement certainty and decades of outcome data reinforce clinical preference despite toxicity profiles.
- Surgery:Retroperitoneal lymph node dissection and orchiectomy procedures deliver curative outcomes in early-stage seminoma. High success rates in Japan's academic medical centers and Texas surgical hubs are constraining adjuvant therapy addressability. Robotic-assisted techniques are compressing recovery timelines and shifting site-of-care economics.
- Radiation Therapy:External beam protocols target residual disease post-surgery. Germany's Diagnosis-Related Group reforms are expanding outpatient reimbursement for fractionated delivery.
- Hormonal Therapy:Systemic modulation suppresses testosterone-driven tumor progression. Prescription volume trails other modalities due to limited indication scope.
Today's leader: Chemotherapy. Tomorrow's challenger: Surgery.
End User:
Site-of-care migration is redistributing patient volume from inpatient wards to decentralized settings with lower overhead structures.
- Hospitals:Academic medical centers anchor complex case management—relapsed disease, multi-line therapy, and surgical intervention. United States NCI-designated centers and Japan's national cancer centers concentrate trial access and specialized pathology. High fixed costs are eroding reimbursement advantage under Medicare payment restructuring.
- Oncology Clinics:Freestanding infusion centers in Florida and Texas are capturing platinum-based regimen volume through streamlined monitoring protocols. Community networks in Germany are expanding service lines under outpatient reimbursement expansion. Lower overhead permits competitive pricing without quality compromise.
- Research Institutions:Phase I/II trial sites drive protocol innovation and biomarker validation. Patient access to CAR-T and checkpoint inhibitor studies concentrates at these facilities.
- Home Care:Oral agent administration and subcutaneous delivery are enabling limited treatment displacement from clinical settings. Growth constrained by monitoring requirements for cytotoxic therapy.
Volume gravity: Oncology Clinics. Margin capture: Hospitals.
Delivery Mode:
Route selection reflects therapy half-life, toxicity monitoring needs, and patient compliance economics across treatment cycles.
- Intravenous:Platinum agents and checkpoint inhibitors require supervised infusion with cardiac and renal monitoring. United States freestanding centers and hospital outpatient departments administer the majority of doses. Infusion chair capacity and nursing ratios constrain throughput expansion.
- Oral:Targeted therapy agents enable decentralized administration with periodic laboratory surveillance. Patient adherence programs and specialty pharmacy distribution are critical success factors.
- Subcutaneous:Reduced administration time and lower facility overhead appeal to community oncology networks. Formulation stability and bioequivalence data requirements slow platform conversion.
- Intramuscular:Limited application for hormonal modulation agents. Injection site reactions and variable absorption profiles restrict protocol penetration.
Efficiency leader: Intravenous. Convenience frontier: Oral.
Technology:
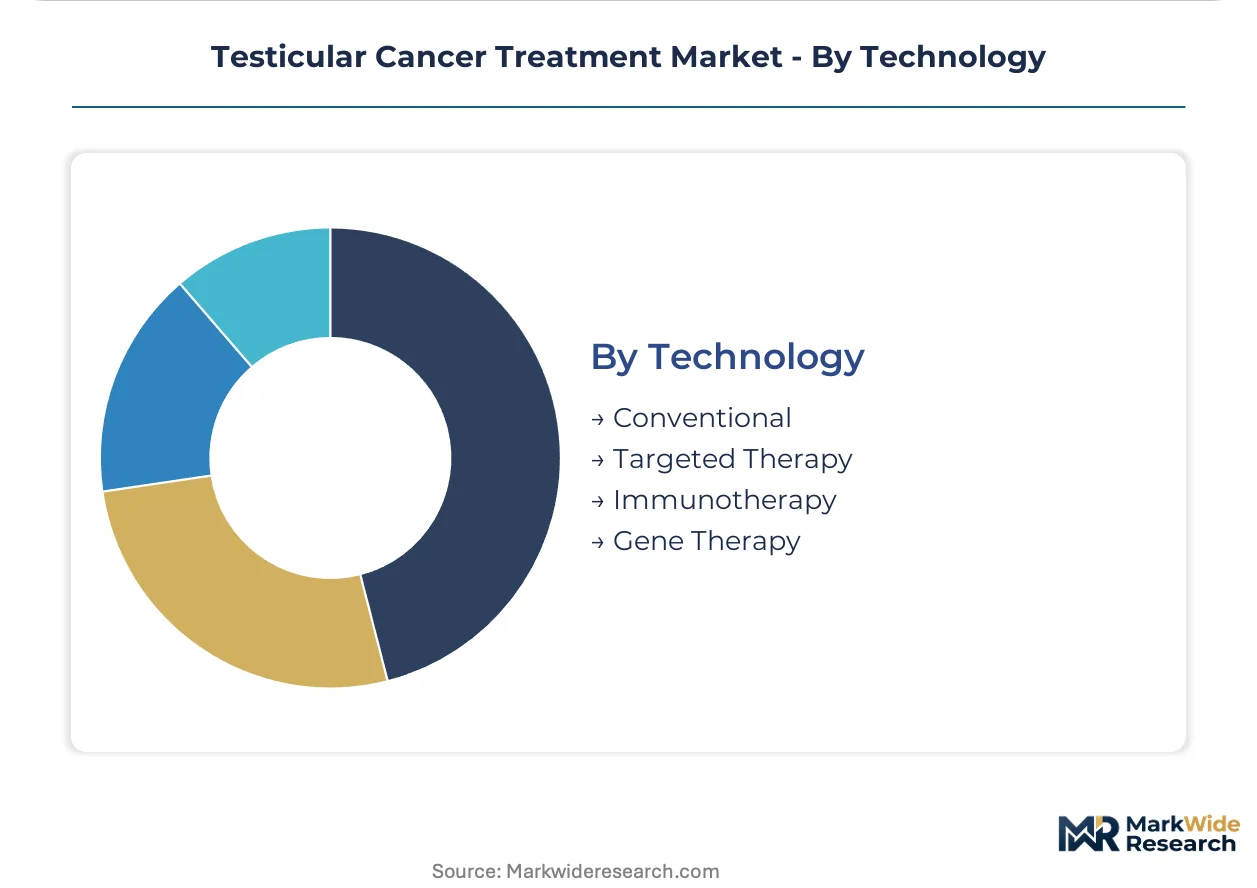
Platform maturity spans decades-old cytotoxic mechanisms to experimental cell engineering, with regulatory velocity determining commercial access timelines.
- Conventional:Cytotoxic chemotherapy and external beam radiation deliver proven outcomes with established manufacturing and reimbursement infrastructure. Cost containment pressures favor these platforms in emerging markets and standard-of-care protocols.
- Immunotherapy:PD-1 checkpoint inhibitors and CAR-T cell platforms are restructuring relapsed disease management. Japan's PMDA accelerated pathways and FDA breakthrough designations are compressing approval timelines. Manufacturing scale and vector production bottlenecks constrain capacity expansion despite clinical demand.
- Targeted Therapy:Biomarker-identified patient subsets command premium pricing through companion diagnostic linkage. EMA Medical Device Regulation diagnostic accuracy requirements are extending validation timelines.
- Gene Therapy:Preclinical and early-phase investigation for germ cell malignancies. Viral vector delivery challenges and durability questions delay commercial translation.
Revenue foundation: Conventional. Expansion trajectory: Immunotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-based chemotherapy protocols first achieved scale in United States academic medical centers during the 1970s, establishing the clinical foundation that spread to Germany and Japan through multinational trial networks. Today's geographic demand patterns reflect those historical treatment hubs and their subsequent regulatory adaptations.
United States
FDA breakthrough therapy designations compress development timelines for checkpoint inhibitors targeting relapsed germ cell tumors. Medicare payment restructuring shifts platinum-based regimen administration from hospital outpatient departments to freestanding infusion centers in Texas and Florida. NCI-designated comprehensive cancer centers in Houston and Boston anchor Phase I/II trial access for CAR-T platforms.
Germany
Diagnosis-Related Group reforms expand outpatient chemotherapy reimbursement, redistributing patient volume toward community oncology networks in Bavaria and North Rhine-Westphalia. EMA centralized procedures govern marketing authorization timelines for combination therapies. Heidelberg and Munich academic clusters concentrate robotic-assisted retroperitoneal lymph node dissection expertise.
Japan
PMDA accelerated approval pathways for orphan oncology indications shorten market entry lag for novel immunotherapies. National cancer centers in Tokyo and Osaka concentrate germ cell tumor surgical volume and biomarker validation studies. METI funding programs support domestic CAR-T manufacturing scale-up initiatives.
India
CDSCO streamlined registration procedures relying on foreign trial data reduce entry barriers for biosimilar platinum agents. Mumbai and Hyderabad oncology networks expand medical tourism capacity for cost-sensitive patients from Southeast Asia and the Middle East. Central government price control mechanisms on essential medicines constrain branded chemotherapy margins.
United Kingdom
NICE technology appraisals determine NHS reimbursement for immunotherapy combinations in relapsed settings, creating access delays compared to private-pay channels. London and Manchester academic medical centers lead European enrollment in circulating tumor DNA surveillance protocols. MHRA post-Brexit regulatory autonomy permits accelerated approval pathways diverging from EMA timelines.
Testicular Cancer Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology spectrum, with immunotherapy developers commanding pricing power while generic platinum manufacturers compete on manufacturing scale and supply security. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with integrated oncology portfolios, mid-cap biotech specialists dependent on partnership structures, and generic manufacturers supplying established cytotoxic agents. Archetypes include checkpoint inhibitor originators, CAR-T platform developers, and high-volume cytotoxic producers. Dominant competitive moves encompass biomarker-linked diagnostic co-development and manufacturing capacity expansion for cell therapy platforms.
Within the multinational conglomerate tier, Pfizer Inc, Bristol Myers Squibb, and Merck & Co. occupy positions defined by immuno-oncology portfolio breadth and manufacturing infrastructure scale. Pfizer represents the high-volume cytotoxic supply archetype through established platinum agent production networks. Bristol Myers Squibb exemplifies checkpoint inhibitor development positioning. Merck & Co. anchors targeted therapy platform investment intensity. These three entities collectively illustrate the competitive tension between legacy chemotherapy dominance and immunotherapy transition investments reshaping protocol economics.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bristol Myers Squibb |
| Merck & Co. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Teva Pharmaceutical Industries |
| Fresenius Kabi |
| BioNTech SE |
| Sanofi |
| Others |
Value Network & Pricing Analysis
NCI-designated comprehensive cancer centers and Germany's community oncology networks concentrate procurement volume for platinum-based regimens, anchoring contract-based long-term offtake agreements that insulate manufacturers from spot market volatility while compressing margins for generic cytotoxic suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates checkpoint inhibitor originators from biosimilar platinum manufacturers and commodity cytotoxic producers. Price differentiation rests on FDA breakthrough designation status and companion diagnostic linkage for immunotherapy platforms, while volume scale and manufacturing efficiency determine positioning among generic suppliers. Pricing pressure stems from Medicare payment restructuring shifting site-of-care economics toward freestanding infusion centers with lower reimbursement ceilings. Community oncology networks in Texas and Florida exhibit highest price sensitivity due to thin overhead structures, whereas academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Vector production specialist shortages in Massachusetts and North Carolina biomanufacturing clusters are constraining CAR-T capacity expansion and extending production lead times for personalized cell therapies. Active pharmaceutical ingredient sourcing concentrates in India and China for platinum salts, while sterile fill-finish capacity clusters in Germany and the United States for finished dose formulation. Supply chain risk centers on single-source vulnerability for specialized cell processing equipment and viral vector substrates. Distribution runs through cold-chain logistics networks serving hospital outpatient departments and freestanding oncology clinics with temperature-validated last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough therapy designations and EMA centralized procedures accelerate commercial access timelines and reshape competitive positioning across immunotherapy platforms.
For Market Incumbents: Anticipate checkpoint inhibitor displacement of platinum monotherapy in relapsed settings by front-loading biomarker-driven diagnostic co-development budgets and securing parallel scientific advice meetings with FDA and EMA. Defensive consolidation around CAR-T manufacturing capacity in Massachusetts and North Carolina bioclusters offsets emerging entrant threats from automated cell processing platform developers. Vertical integration into vector production capabilities secures supply continuity against raw material concentration risks. For New Entrants and Emerging Players: Capture outpatient chemotherapy volume migration under Germany's Diagnosis-Related Group reform by positioning biosimilar platinum agents through community oncology networks in Bavaria and North Rhine-Westphalia. India's CDSCO streamlined registration pathway offers lowest entry barrier for foreign trial data-reliant submissions. Go-to-market execution through specialty pharmacy distribution partnerships enables rapid formulary access without hospital procurement committee navigation. For Investors and Strategic Acquirers: Mid-cap biotech specialists with Phase II checkpoint inhibitor assets are the most active acquisition targets for multinational pharmaceutical conglomerates seeking immunotherapy portfolio expansion. Long-term viability over the coming decade hinges on successful biomarker validation and companion diagnostic co-development execution. Manufacturing scale readiness signals inflection timing for CAR-T platform commercial translation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | EMA Medical Device Regulation compliance expands addressable patient populations through histology-specific labeling. |
| CAR-T Manufacturing Scale-Up | Automated cell processing platforms in Massachusetts compress production cycles and enable decentralized treatment delivery. |
| Regulatory Approval Pathway | PMDA accelerated orphan oncology pathways in Japan shorten market entry lag for novel immunotherapy platforms. |
| Site-of-Care Expansion | Freestanding infusion center networks in Texas and Florida capture platinum-based regimen volume under Medicare restructuring. |
| Pipeline Diversification | Targeted therapy investments around biomarker-identified subsets command premium pricing through diagnostic linkage. |
Research Methodology
Multiple input streams — structured interviews with oncology clinical directors, regulatory affairs leads at multinational pharmaceutical manufacturers, hospital procurement managers, and payer access specialists — were reconciled against FDA filings, EMA centralized procedure databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Secondary validation drew from SEC 10-K oncology segment disclosures and formulary database audits. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across treatment modality, tumor histology, administration route, and regional regulatory cluster dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from patient incidence trajectories, protocol penetration assumptions, and pricing evolution by technology tier. Forecast inputs incorporated biomarker testing adoption curves, site-of-care migration velocity, and manufacturing capacity expansion timelines for cell therapy platforms.
Regulatory pathway delays, platinum supply disruptions, and immunotherapy manufacturing bottlenecks are the dominant revision risks that could compress or extend commercial translation timelines. Forecasts reflect assumptions around reimbursement stability and clinical trial success rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
South Korea Radiotherapy Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Particle Therapy Systems Market
Oncology
Europe Tumor Ablation Market
Oncology
Esophageal Cancer Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
North America Tumor Ablation Market
Oncology
Laser Cancer Therapy Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Metastases Spinal Tumor Market
Oncology
Global Interventional Oncology Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Thyroid Cancer Market
Oncology
Global Particle Therapy Market
Oncology
Gallbladder Cancer Treatment Market