
 US Autonomous Car Market | 2026-2036
US Autonomous Car Market Size, Share, and Industry Trends Forecast 2026-2036
US Autonomous Car Market Analytics
Software-defined feature subscriptions is recalibrating revenue models across the US autonomous car landscape. Tesla leverages over-the-air capability upgrades to sustain recurring revenue streams alongside hardware sales. Waymo dominates commercial robotaxi deployment in mapped urban zones, while Nvidia anchors the compute layer through its DRIVE platform architecture.
An autonomous car integrates sensor fusion arrays, redundant computing stacks, and machine-learning perception models to navigate without continuous human operator intervention, typically achieving SAE Level 3 or higher driving automation. The vehicle category spans passenger cars, trucks, buses, and SUVs, with trucks attracting concentrated R&D investment due to highway predictability and fleet economics. LiDAR and computer vision technologies compete as primary perception modalities, with radar retaining critical redundancy functions across all configurations.
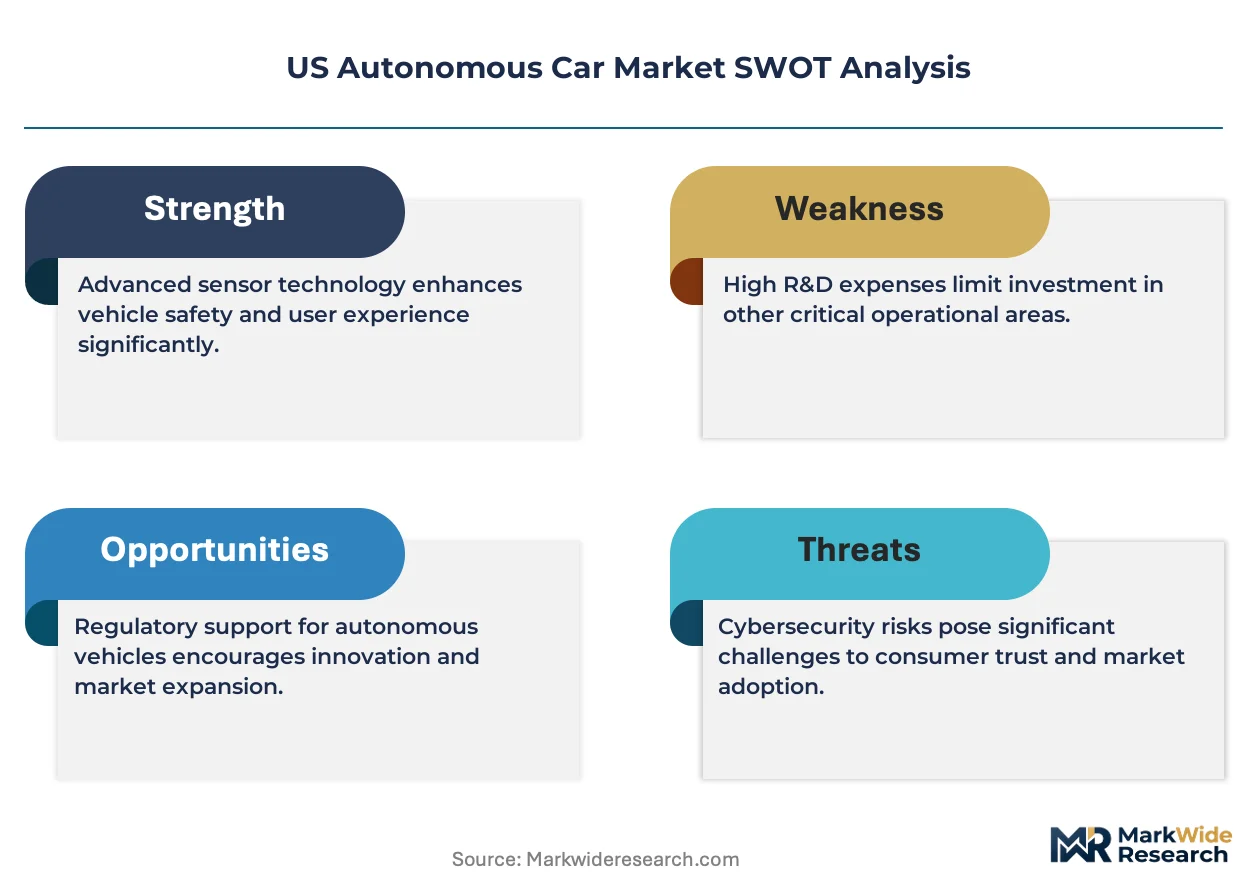
NHTSA, the FAA for emerging aerial mobility interfaces, and state-level departments of motor vehicles collectively shape deployment permits, safety reporting, and insurance frameworks across the United States. FMVSS exemptions and state-by-state operating authority create a fragmented compliance landscape that elevates legal and engineering costs for market participants. Stakeholders must monitor the interplay between federal preemption debates and state-level liability rules as this determines where commercial scale becomes economically viable.
Market Dynamics
Fleet operators in logistics and last-mile delivery are accelerating deployment timelines as labor cost pressures and route optimization imperatives override consumer adoption hesitancy. This buyer segment concentration is compressing development cycles and redirecting R&D investment toward commercial vehicle architectures.
Growth Catalysts
- FMVSS Exemption Pathways:NHTSA's evolving Federal Motor Vehicle Safety Standards for automated driving systems are creating streamlined certification routes for commercial deployment.
- Sensor Fusion Maturation:LiDAR and computer vision convergence is delivering redundant perception stacks that satisfy safety-critical redundancy requirements.
- Arizona Testing Corridors:Permissive state regulations in Phoenix metropolitan zones have established dense autonomous vehicle clusters with expanded operating envelopes.
Market Restraints
- LiDAR Cost Structure:Solid-state and mechanical LiDAR arrays remain prohibitively expensive for mass-market passenger vehicle integration.
- California Regulatory Density:State-level operating authority fragmentation creates compliance multiplicity that elevates legal and engineering expenditures.
- Edge Case Perception Limits:Adverse weather conditions and construction zone variability expose persistent gaps in machine-learning perception robustness.
Strategic Opportunities
- Texas Interstate Corridors:Underpenetrated highway freight routes between Dallas and Houston present untapped commercial truck deployment potential.
- Software-Defined Subscriptions:Over-the-air capability upgrades are establishing recurring revenue streams alongside hardware monetization.
- Silicon Valley Talent Convergence:Machine-learning and robotics expertise concentration is accelerating perception algorithm development cycles.
Industry Challenges
- Systems Safety Engineering Talent:Functional safety certification expertise for SAE Level 4 systems remains scarce relative to deployment ambitions.
- Product Liability Framework Uncertainty:Federal preemption debates and state-level liability rule variation create insurance and legal exposure ambiguity.
- Compute Stack Thermal Management:Redundant processing architectures generate heat loads that strain vehicle thermal design envelopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Autonomous Car Market |
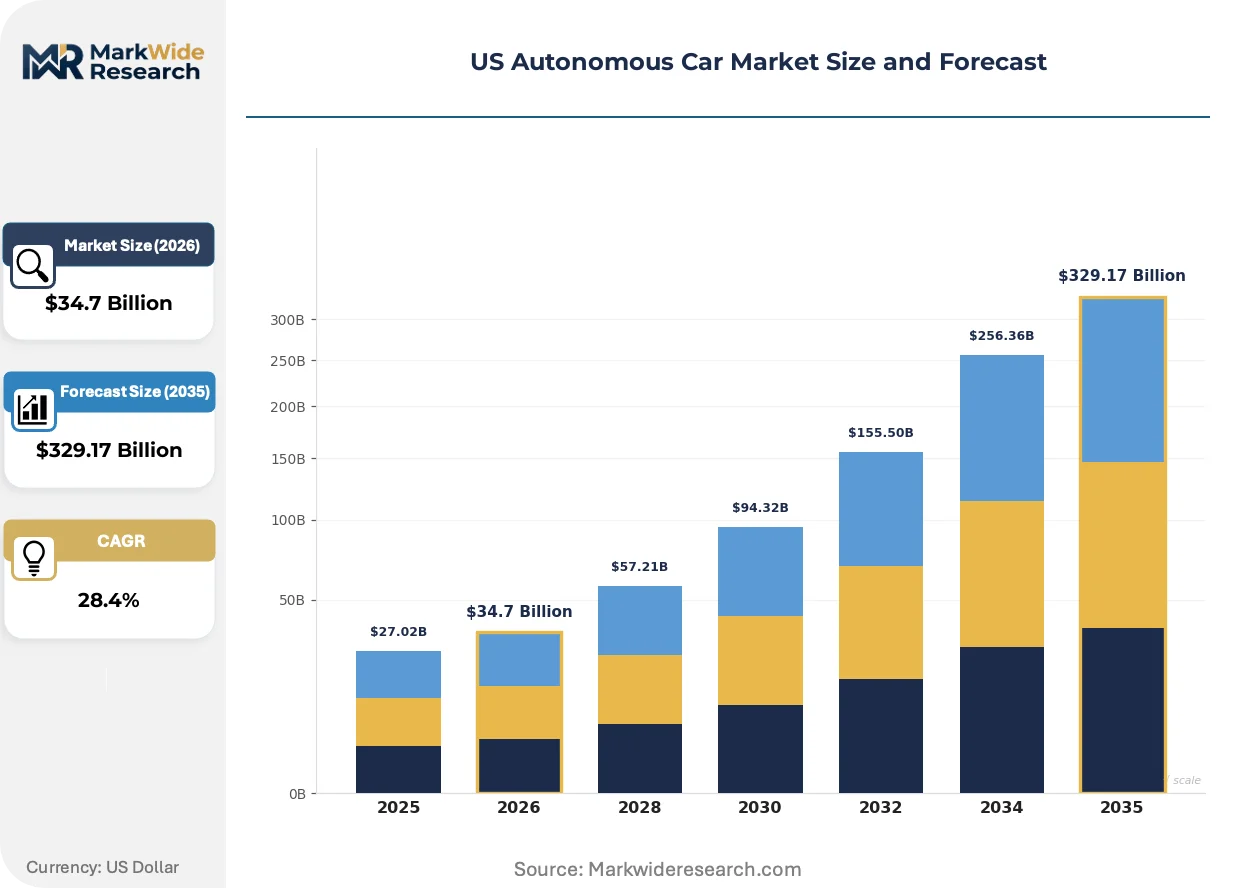
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $329.17 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Computer Vision, GPS Navigation Vehicle Type: Passenger Cars, Trucks, Buses, SUVs End User: Consumers, Fleet Operators, Government, Rideshare Services Deployment: Urban Areas, Suburban Areas, Highway Systems, Private Properties |
| Companies Covered | Ford, Nvidia, Waymo, Lucid, Uber, Zoox, Mobileye, Nuro, Tesla, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Autonomous Car Market Evolving Landscape
Revenue model transformation is overtaking hardware-centric paradigms as the defining competitive axis. Subscription-based feature activation and fleet-management platforms are displacing traditional unit-sale economics across both passenger and commercial segments.
End-to-end neural network architectures are absorbing perception, prediction, and planning functions into unified models. Logistics fleet operators are adopting these consolidated stacks most aggressively, compressing vendor count and integration complexity. This absorption is collapsing the traditional tiered supplier structure that separated sensing hardware from software middleware.
NHTSA's pending updates to Federal Motor Vehicle Safety Standards for automated driving systems are mandating standardized crash reporting and safety performance metrics. The industrial consequence is forcing manufacturers to redesign validation protocols around reproducible test scenarios. Commercial robotaxi operators face the steepest compliance adaptation requirements as they scale beyond geo-fenced pilot zones.
Fleet procurement is consolidating around outcome-based contracts that tie vendor compensation to uptime and safety performance metrics. Third-party fleet management platforms are disintermediating traditional OEM service relationships. This shift is most visible in California and Arizona logistics corridors where operator concentration enables contract standardization.
US Autonomous Car Market Segmentation
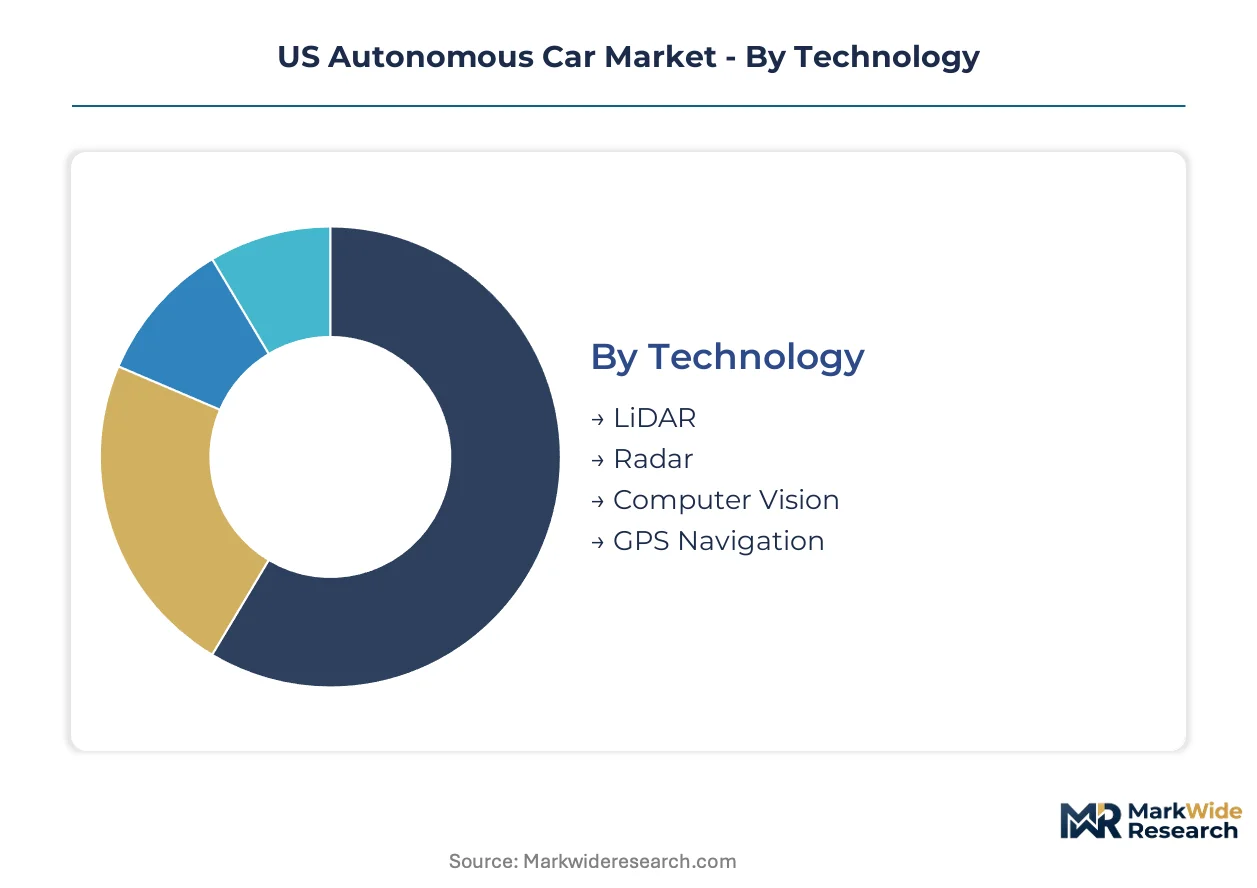
Segmentation in the US autonomous car market reveals how technology choices, vehicle architectures, and deployment contexts determine viable commercial pathways. Understanding these divisions exposes where capital concentrates and which configurations face regulatory or economic headwinds.
Technology:
Upgrade cycles in perception hardware are compressing as sensor fusion architectures mature and fleet operators demand redundancy guarantees.
- LiDAR:Solid-state and mechanical arrays emit pulsed laser light to construct three-dimensional point clouds with centimeter-level precision. Arizona's Phoenix metropolitan testing corridors favor LiDAR-heavy configurations for their mapping fidelity in dense urban grids, though unit economics constrain passenger vehicle adoption.
- Computer Vision:Convolutional neural networks process camera feeds to classify road markings, traffic signals, and pedestrian intent. Silicon Valley development clusters concentrate demand here as machine-learning talent density enables rapid algorithm iteration with lower hardware bills than LiDAR alternatives.
- Radar:Frequency-modulated continuous wave sensors penetrate precipitation and fog where optical systems degrade. Radar retains mandatory redundancy status across all SAE Level 4 certifications regardless of primary perception modality.
- GPS Navigation:Real-time kinematic positioning and augmentation systems provide lane-level localization. Highway freight routes in Texas and California's Central Valley leverage this for predictable corridor navigation.
Volume placements concentrate in Computer Vision; the faster expansion belongs to LiDAR as solid-state manufacturing scales.
Vehicle Type:
Cost tier differentiation separates premium R&D investment from mass-market feasibility across autonomous platforms.
- Trucks:Class 8 highway tractors integrate redundant braking and steering actuators for platooning and solo autonomous operation. Interstate corridors between Dallas and Houston attract concentrated fleet procurement due to route predictability and labor cost arbitrage.
- Passenger Cars:SAE Level 2+ systems dominate current production as manufacturers balance sensor costs against consumer price sensitivity. California's Silicon Valley generates outsized software development activity for this segment despite modest deployment volumes.
- SUVs:Higher ride heights accommodate larger sensor payloads and improve camera sightlines. Family-oriented buyers in suburban Arizona and Texas municipalities show stronger willingness-to-pay for advanced driver assistance packages.
- Buses:Fixed-route shuttle applications in Phoenix and Austin deploy compact autonomous buses for last-mile connectivity. Municipal procurement cycles and accessibility mandates slow deployment timelines relative to commercial freight.
Revenue concentration sits with Trucks; Passenger Cars claim the steepest expansion trajectory as NHTSA certification pathways clarify.
End User:
Customer type determines contract structures, with outcome-based pricing penetrating fleet relationships faster than consumer transactions.
- Fleet Operators:Logistics and last-mile delivery companies contract for uptime guarantees and safety performance metrics. These buyers compress development cycles by accepting geo-fenced operational envelopes in exchange for earlier commercial deployment.
- Rideshare Services:Robotaxi operators in mapped urban zones pursue 24-hour utilization rates impossible with human drivers. Phoenix and San Francisco municipal authorities have granted expanded operating permits to this segment.
- Consumers:Private ownership models face adoption hesitancy around liability ambiguity and technology trust gaps. Subscription-based feature activation is emerging as the dominant monetization path for this buyer type.
- Government:Municipal transit authorities and federal research programs fund pilot deployments with safety validation objectives. Procurement timelines extend 18-36 months longer than commercial fleet contracts.
Contract standardization advances fastest among Fleet Operators; Rideshare Services are climbing the fastest toward scaled revenue.
Deployment:
Geography dictates regulatory permissiveness and infrastructure readiness, fragmenting go-to-market strategies across contexts.
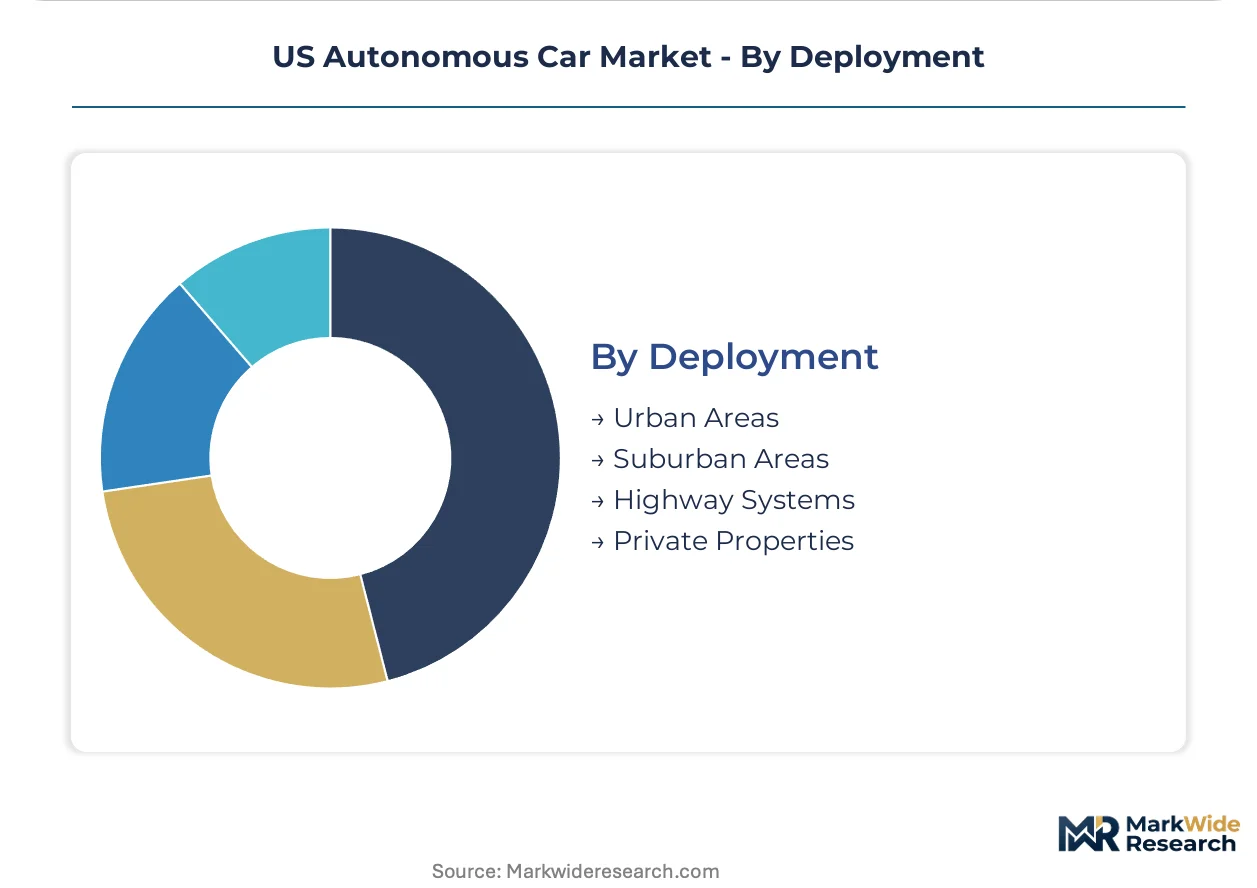
- Highway Systems:Limited-access interstates offer predictable lane markings, gentle curves, and absence of pedestrian conflict points. Texas and Arizona departments of transportation have designated freight corridors for autonomous truck pilot programs.
- Urban Areas:Dense signalized intersections, jaywalking pedestrians, and construction variability stress perception systems most severely. California's regulatory density elevates compliance costs for urban robotaxi operators.
- Suburban Areas:Lower traffic densities and standardized residential street grids enable cautious expansion beyond geo-fenced downtown cores. Phoenix metropolitan sprawl provides extensive testing territory with permissive state oversight.
- Private Properties:Controlled environments such as industrial campuses, mining operations, and airport grounds bypass public road regulations. These deployments generate revenue while accumulating safety data for broader certification.
Permitting velocity favors Private Properties; Highway Systems are gaining share fastest as FMVSS exemption pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors autonomous vehicle development density in the United States, with Phoenix metropolitan corridors and Texas interstate freight routes forming complementary deployment clusters.
California
Silicon Valley machine-learning talent density and Bay Area venture capital flows accelerate perception algorithm development cycles. NHTSA collaborates with California DMV on safety performance metric standardization for SAE Level 4 certifications. Los Angeles-San Diego corridor testing programs concentrate robotaxi pilot deployments in dense urban signal environments.
Arizona
Permissive state operating authority and expanded geo-fenced envelopes attract commercial robotaxi operators pursuing 24-hour utilization rates. Arizona Department of Transportation designates Phoenix metropolitan testing corridors with reduced regulatory friction versus coastal jurisdictions. Tempe-Mesa-Scottsdale suburban sprawl provides extensive low-density validation territory for cautious expansion beyond downtown cores.
Texas
Interstate freight routes between Dallas and Houston present concentrated demand from logistics fleet operators seeking labor cost arbitrage on predictable highway corridors. Texas Department of Transportation autonomous truck pilot programs designate specific interstate segments for Class 8 tractor platooning trials. Austin municipal authorities deploy compact autonomous shuttles for last-mile connectivity in controlled campus environments.
Nevada
Las Vegas tourism and convention infrastructure generates structured demand for fixed-route autonomous shuttle services on private resort properties. Nevada DMV early-adopter regulatory frameworks predate federal FMVSS exemption pathways by several years. Reno-Sparks industrial corridor testing programs validate warehouse-to-highway freight handoff protocols for logistics integrators.
Florida
Retirement community mobility needs and tourism shuttle applications create distinct deployment contexts separate from freight-focused western states. Florida Department of Transportation pilot programs emphasize low-speed autonomous shuttles in controlled master-planned communities. Orlando metropolitan area attractions districts test passenger-carrying autonomous vehicles in semi-private road networks.
US Autonomous Car Market Competitive Landscape
Capital-heavy automotive manufacturers compete with asset-light software and compute platform designers for control of autonomous system architecture. The vendor base concentrates around three strategic tiers: vertically integrated OEMs developing full-stack capabilities, specialized perception and compute layer suppliers, and fleet-focused robotaxi operators. Competitive positioning hardens through strategic partnerships binding hardware platforms to deployment networks, while M&A activity absorbs niche sensing technology developers into consolidated supply chains.
Within the integrated OEM tier, Tesla and Ford anchor divergent commercialization philosophies. Among compute-layer specialists, Nvidia occupies a position exemplifying platform-centric market architecture. On the robotaxi deployment vector, Waymo represents the mapped-urban-zone operating model. These three anchors illustrate how vertical integration depth, horizontal platform licensing, and fleet-operator scale constitute distinct competitive vectors.
| Leading Market Players |
|---|
| Ford |
| Nvidia |
| Waymo |
| Lucid |
| Uber |
| Zoox |
| Mobileye |
| Nuro |
| Tesla |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation around uptime-guaranteed contracts is forcing perception hardware vendors to absorb warranty risk and compress sensor fusion stack costs, redistributing pricing power toward logistics operators with standardized safety performance metrics.
Pricing Analysis
Margin tightening in SAE Level 4 perception modules reflects solid-state LiDAR manufacturing scale inefficiencies and computer vision algorithm commoditization. Three-tier pricing structure across premium, standard, and economy levels separates redundant fusion arrays from single-modality configurations, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure on passenger vehicle integration accelerates because OEMs resist passing sensor costs to price-sensitive consumers. Fleet operators exhibit lowest price sensitivity due to labor arbitrage payback calculations, while private buyers demand subscription alternatives to upfront hardware premiums.
Supply Chain Analysis
Domestic-content mandates in NHTSA's evolving FMVSS exemption pathways are reshaping sourcing toward US-based compute packaging and final assembly integration. Geographic supply concentration centers on Taiwan for advanced semiconductor fabrication, South Korea for high-density memory modules, and Japan for precision optical components. Raw material dependencies span rare-earth magnets for LiDAR actuators, high-purity silicon for photonic chips, and copper-laminated substrates for redundant processing boards. Single-source vulnerability in solid-state LiDAR emitter arrays creates qualification bottlenecks. Distribution runs through Tier 1 automotive suppliers with embedded software integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into safety-critical compute hardware and captive fleet deployment networks is becoming the decisive competitive moat as software differentiation compresses.
For Market Incumbents: To counter end-to-end neural network architectures collapsing traditional tiered supplier structures, anchor platform control through backward integration into sensor calibration facilities and captive supply of redundant processing units. Secure NHTSA certification precedence in Arizona and Texas corridors to establish regulatory reference architectures that latecomers must displace. For New Entrants and Emerging Players: Perception algorithm specialization for adverse weather robustness offers defensible white-space against Waymo and Tesla mapping-dependent approaches. Target Texas interstate freight corridors where logistics fleet operators prioritize uptime guarantees over urban complexity coverage. Pursue outcome-based pilot contracts with Dallas-Houston trucking operators to accumulate safety performance data for broader FMVSS exemption eligibility. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive sensor manufacturing and existing NHTSA safety validation relationships. Long-term viability hinges on accumulation of geo-fenced operating permits in permissive regulatory jurisdictions. Watch Arizona Department of Transportation expansion of autonomous truck pilot program scope as inflection signal for commercial scale feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Integration | Consolidates LiDAR, radar, and vision modules under unified compute architecture reducing vendor count. |
| NHTSA Certification Precedence | Establishes safety performance benchmarks that competitors must replicate for FMVSS exemption eligibility. |
| Fleet Deployment Network Expansion | Captures recurring revenue through outcome-based uptime contracts with logistics operators. |
| Software-Defined Vehicle Investment | Enables over-the-air capability upgrades sustaining subscription monetization alongside hardware sales. |
| Geographic Manufacturing Footprint | Positions final assembly in Arizona and Texas corridors to align with permissive state operating authority. |
Research Methodology
Independent corroboration across NHTSA safety filing databases, Arizona Department of Transportation pilot program disclosures, and Texas Department of Transportation freight corridor designations underwrites the qualitative findings. Primary interviews with autonomous vehicle platform engineers, fleet procurement directors at logistics operators, NHTSA regulatory affairs specialists, and Tier 1 supplier program managers combined with secondary validation from SEC automotive OEM filings, state DMV deployment permit registries, and commercial insurance underwriting guidelines. Bottom-up unit deployment estimates triangulated against top-down addressable fleet replacement value across the analysis window.
Comparable-period anchoring to historical NHTSA exemption grant timelines and state-level pilot program expansion phases structured the forecast window. Segmentation dimensions modeled span vehicle class, perception technology modality, SAE automation level, end-user contract type, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to fleet operator adoption thresholds and consumer willingness-to-pay survey calibration. Industry-specific forecast inputs encompass LiDAR cost decline trajectories and machine-learning training data accumulation rates.
Several conditions sit outside the modeled scope, including federal preemption legislation outcomes, adverse weather perception breakthrough timelines, and lithium-ion battery supply disruptions affecting electric autonomous platform economics. Forecasts reflect documented assumptions regarding NHTSA rulemaking velocity and state regulatory permissiveness stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Singapore Autonomous Navigation Market