
 Vehicle Parking Meter Market | 2026-2036
Vehicle Parking Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Parking Meter Market Analytics
China is narrowing its technology gap in parking meter manufacturing through scaled electronics assembly and sensor integration. Flowbird leverages its European installed base to sustain service revenue across municipal clients. IPS Group anchors North American supply through vertically integrated production of solar-powered and cellular-enabled meters. CivicSmart competes on software-layer differentiation, embedding dynamic pricing algorithms that extend hardware utility beyond basic collection.
A vehicle parking meter constitutes a self-contained revenue collection terminal engineered to enforce time-limited parking through coin, card, or digital payment acceptance, typically incorporating durable housings rated for outdoor exposure and communication modules for remote monitoring. The device serves primary commercial purpose by enabling municipalities and private operators to monetize curb space while managing traffic turnover. Smart meters and multi-space meters now capture the dominant margin pools as cities prioritize centralized management platforms over standalone mechanical units. IoT-enabled technology segments are expanding fastest where cellular connectivity and cloud-based enforcement reduce on-site maintenance requirements. Payment gateway integration increasingly determines vendor selection as cashless transaction volumes displace coin-operated legacy systems across municipal procurement.
The Federal Communications Commission governs wireless communication modules embedded in US-deployed meters, while the European Union's Radio Equipment Directive and GDPR shape product certification and data handling protocols for connected parking systems. Municipal procurement codes in Canada and Australia increasingly mandate accessibility standards and open-payment interoperability, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving cybersecurity requirements for connected infrastructure as attack surface expansion accompanies smart city integration.
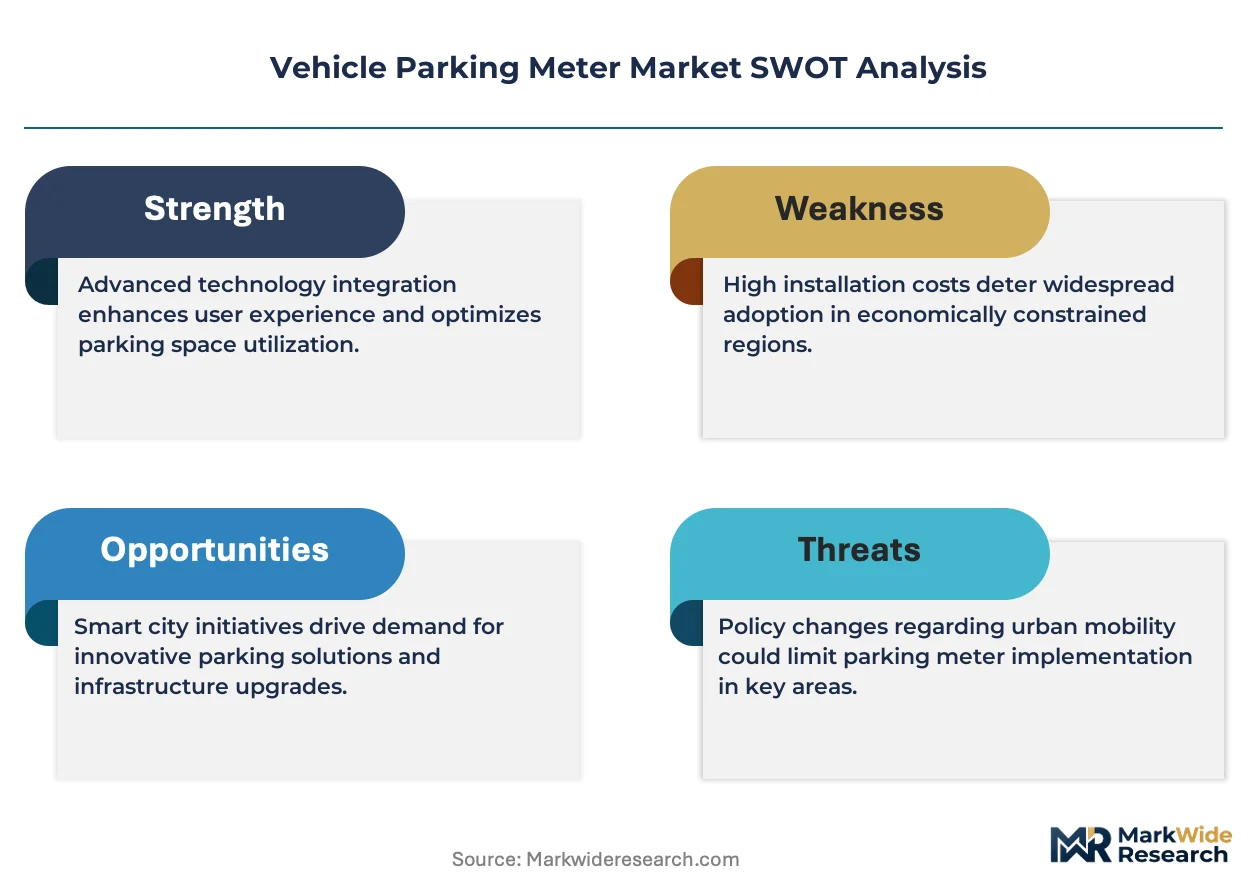
Market Dynamics
Municipal procurement offices are consolidating vendor relationships around integrated platform providers capable of delivering hardware, software, and payment processing through unified service contracts, compressing the addressable supplier base.
Growth Catalysts
- Contactless Payment Mandates:Municipal codes in the United States and Canada now require tap-to-pay compatibility at all new meter installations, forcing replacement cycles for coin-only legacy equipment.
- IIJA Funding Streams:The Infrastructure Investment and Jobs Act directs federal capital toward smart city mobility infrastructure, creating dedicated budget lines for parking system modernization.
- License Plate Recognition:Camera-based enforcement integration reduces personnel costs for municipal parking authorities and accelerates violation processing throughput.
Market Restraints
- Cellular Module Supply Concentration:Dependence on a narrow base of semiconductor fabricators in East Asia creates vulnerability to trade policy disruptions and allocation delays.
- GDPR Compliance Burden:European data handling requirements impose architectural constraints on cloud-connected meters, increasing firmware development cycles and certification costs.
- Solar Panel Degradation:Photovoltaic cell efficiency decay in northern latitudes limits off-grid deployment viability and drives battery replacement expenses.
Strategic Opportunities
- Curbside Management Platforms:Integration of parking meters with loading zone reservation systems and electric vehicle charging allocation opens new revenue streams for municipal clients.
- Dynamic Pricing Algorithms:Real-time demand-responsive rate adjustment captures previously uncaptured willingness-to-pay during peak congestion periods.
- Open Payment Interoperability:Transit agency procurement specifications increasingly mandate unified fare media acceptance, creating cross-vertical vendor qualification advantages.
Industry Challenges
- Cybersecurity Certification Delays:Municipal IT departments lack standardized frameworks for evaluating connected infrastructure attack surfaces, extending sales cycles.
- Legacy System Integration:Backward compatibility requirements with decades-old mechanical meter zones constrain architectural flexibility and inflate deployment engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Parking Meter Market |
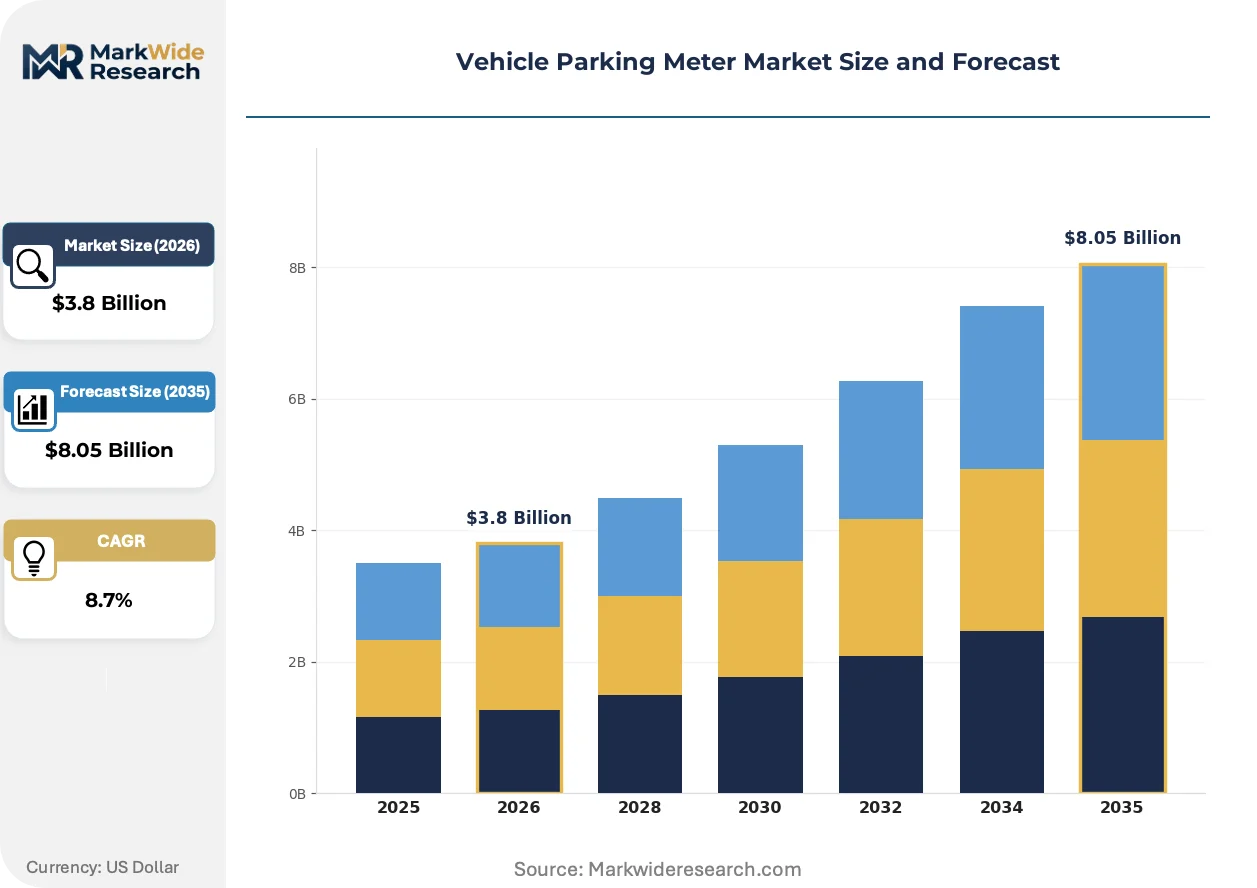
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Digital Meters, Mechanical Meters, Multi-Space Meters Technology: IoT Enabled, Solar Powered, Coin Operated, Payment Gateway Application: On-Street, Off-Street, Commercial, Residential End User: Municipalities, Private Operators, Transportation Authorities, Property Managers |
| Companies Covered | IPS Group, Flowbird, Duncan Solutions, Parking BOXX, Ventek International, CivicSmart, J.J. MacKay Canada Limited, Cale Access, LocoMobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Parking Meter Market Evolving Landscape
Payment modality convergence and enforcement automation are compressing the functional boundary between parking meters and broader urban mobility platforms, repositioning hardware vendors as software service providers.
Edge computing architectures are virtualizing meter intelligence. On-device transaction processing and local enforcement decisioning reduce latency for payment authorization and eliminate dependency on continuous cloud connectivity. Municipal operators in Scandinavia and the Netherlands are piloting these distributed systems to ensure service continuity during network outages. The shift is virtualizing what had been centralized SaaS functionality into firmware-resident capabilities, altering vendor margin structures toward perpetual licensing.
The European Union's Radio Equipment Directive 2014/53/EU is tightening electromagnetic compatibility testing protocols for cellular-enabled meters entering member state markets. Manufacturers must now demonstrate interference resilience across expanded frequency bands, adding six to nine months to product certification timelines. German and French testing laboratories report backlog accumulation, disadvantaging smaller suppliers lacking dedicated regulatory affairs capacity.
Municipal procurement departments are consolidating vendor panels and awarding multi-year managed service contracts in lieu of capital equipment purchases. This shift transfers operational risk to suppliers while locking in recurring revenue streams. The model is most advanced in United Kingdom local authorities, where budget pressures favor operational expenditure treatment over capital appropriations. Vendors must now underwrite hardware deployment costs against future transaction fee shares, restructuring cash flow profiles and balance sheet requirements.
Vehicle Parking Meter Market Segmentation
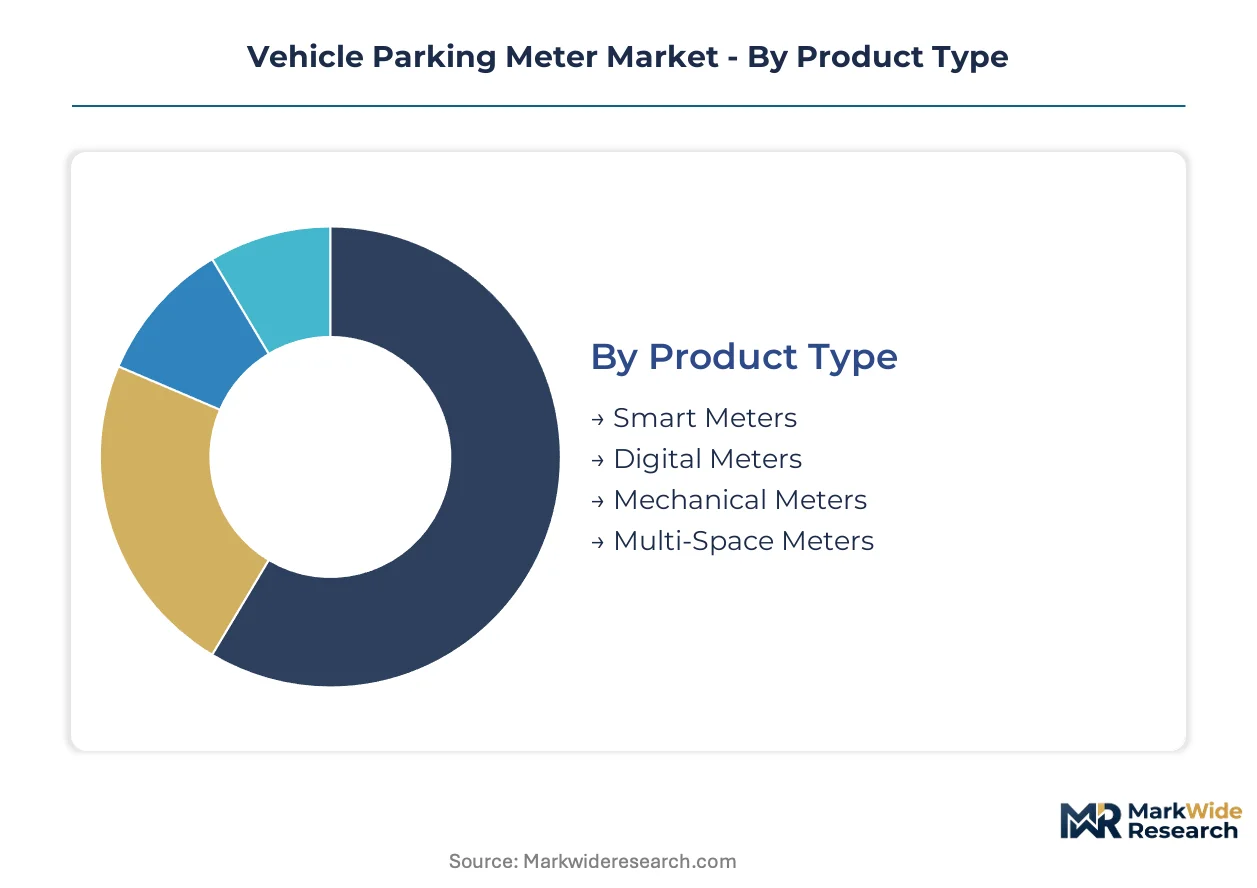
Parking meter procurement specifications diverge sharply across deployment contexts, from municipal curb management to private garage monetization. Segment-level technology choices determine service life, maintenance burden, and revenue capture efficiency for operators.
Product Type:
Smart meters anchor high-value municipal contracts through centralized management platforms and dynamic rate adjustment capabilities.
- Smart Meters:Cellular-connected terminals integrate payment processing, enforcement cameras, and cloud-based analytics in sealed outdoor housings. Demand concentrates in United States cities accessing IIJA infrastructure funding for congestion management upgrades.
- Digital Meters:Electronic payment acceptance modules with LED displays and card readers replace legacy coin mechanisms in retrofit deployments. European municipalities favor these units where GDPR constraints limit full cloud connectivity.
- Mechanical Meters:Spring-wound or battery-powered coin collectors serve budget-constrained smaller cities with minimal enforcement staffing. These units dominate replacement cycles in regions with intermittent cellular coverage.
- Multi-Space Meters:Centralized pay stations serve vehicle clusters through license plate entry, reducing hardware count per block face. Shopping districts in Canadian and Australian cities deploy these for pedestrian-friendly streetscapes.
Established volume favors mechanical meters in legacy replacement; emerging adoption favors smart meters in new infrastructure deployment.
Technology:
Power and connectivity architectures determine deployment feasibility across climate zones and network maturity gradients.
- IoT Enabled:Real-time occupancy sensing, predictive maintenance alerts, and API integration with municipal mobility platforms define this segment. Scandinavian cities pilot edge-computing variants that process transactions locally during network outages.
- Solar Powered:Photovoltaic cells with lithium battery backup eliminate trenching costs in historic districts and remote locations. Northern latitude deployments in Germany and Netherlands face efficiency degradation constraints during winter months.
- Coin Operated:Mechanical or electromechanical coin validation mechanisms persist where cash transaction volumes remain significant among elderly populations or unbanked communities. These units require frequent collection routes and vandalism-resistant housings.
- Payment Gateway:Integrated card processors and mobile wallet acceptance modules comply with contactless mandates in United States and Canadian procurement codes. Transaction fee structures influence vendor selection more than hardware specifications.
Cellular module supply concentration constrains IoT-enabled deployment scaling; payment gateway integration accelerates fastest where cashless mandates apply.
Application:
Revenue model and enforcement intensity vary across curb, garage, and private property contexts.
- On-Street:Curb-side meters manage traffic turnover in commercial corridors and generate fine revenue through license plate recognition integration. United States downtown business districts prioritize these deployments for congestion pricing pilots.
- Off-Street:Surface lots and structured garages deploy multi-space or pay-by-plate systems with barrier arm integration. Airport and hospital campuses in France and United Kingdom represent concentrated demand for payment flexibility.
- Commercial:Retail and entertainment venues deploy meters or pay stations to monetize customer parking and validate patron purchases. These installations emphasize throughput speed over enforcement integration.
- Residential:Permit-based or time-limited meters manage neighborhood parking scarcity near transit hubs and university zones. Resident preference programs and visitor pass systems complicate rate structure design.
On-street applications dominate municipal procurement volume; off-street commercial deployments expand fastest where private operators underwrite capital costs.
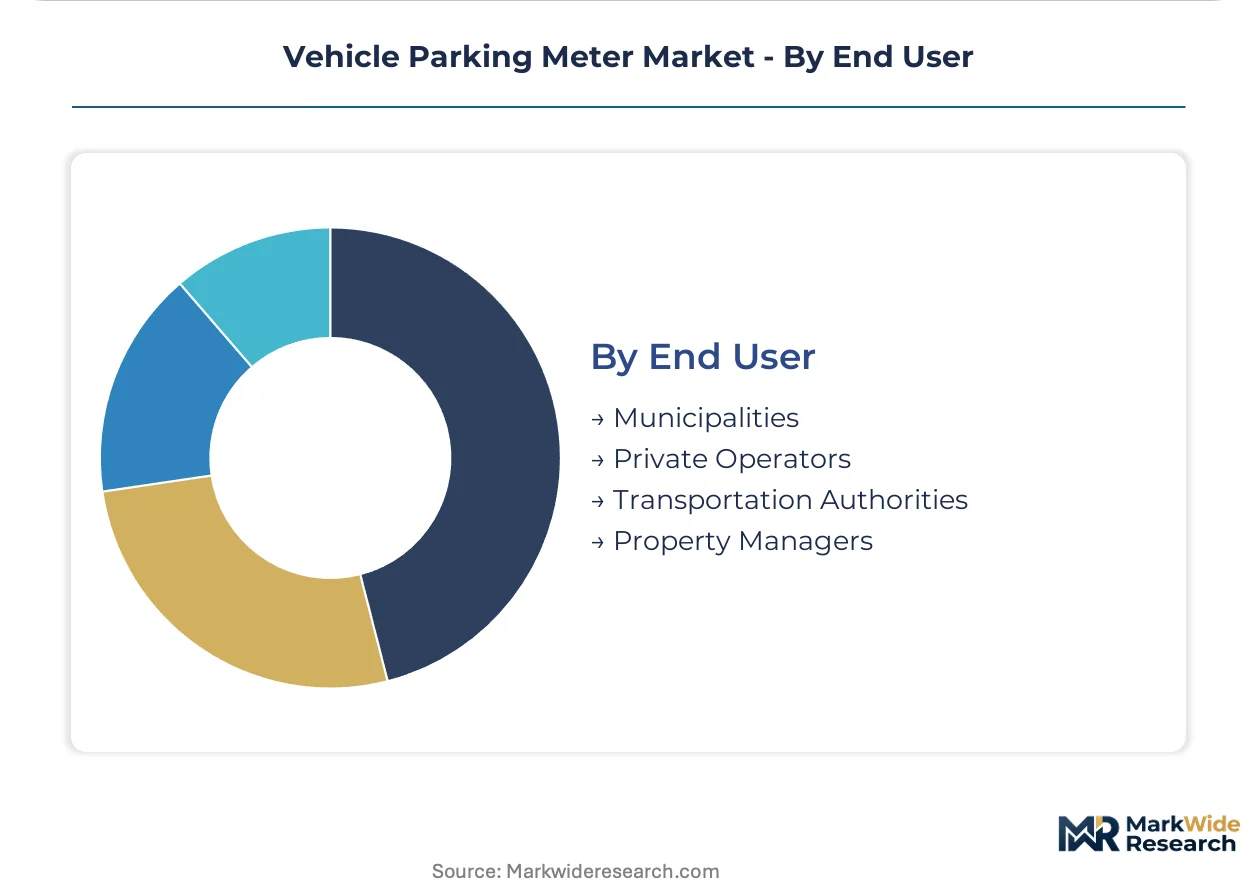
End User:
Procurement authority and budget treatment shape vendor engagement models and contract structures.
- Municipalities:City transportation departments issue RFPs emphasizing open payment interoperability, accessibility compliance, and multi-year service contracts. These buyers consolidate vendor panels around integrated platform providers.
- Private Operators:Parking management companies prioritize hardware reliability and remote diagnostics to minimize labor dispatch costs. Revenue-sharing agreements with property owners influence technology upgrade timing.
- Transportation Authorities:Transit agencies mandate unified fare media acceptance across parking meters and bus/rail systems, creating cross-vertical qualification requirements. United Kingdom and Netherlands authorities lead this integration.
- Property Managers:Commercial real estate owners deploy meters to control tenant and visitor access in mixed-use developments. These buyers emphasize lease-compliant installation speed and minimal structural modification.
Municipalities anchor procurement volume through federal infrastructure funding; transportation authorities represent the steepest expansion trajectory through mobility platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in China and the United States supplies the dominant share of smart meter hardware, while municipal procurement patterns diverge sharply across regulatory environments and infrastructure funding cycles.
United States
Federal infrastructure funding through the Infrastructure Investment and Jobs Act accelerates smart parking deployment in downtown business districts and transit corridors. The Federal Communications Commission governs wireless communication modules embedded in connected meters, mandating specific frequency certifications. Chicago, Los Angeles, and New York City represent concentrated demand centers where congestion pricing pilots drive multi-space meter installations.
Germany
Municipal transportation authorities prioritize solar-powered and edge-computing meter variants to ensure service continuity during network outages. The European Union's Radio Equipment Directive and GDPR impose architectural constraints on cloud-connected systems, extending firmware development cycles. Testing laboratories in Berlin and Munich report certification backlogs that disadvantage smaller suppliers lacking dedicated regulatory affairs capacity.
United Kingdom
Budget pressures at local authorities favor operational expenditure treatment over capital appropriations, accelerating managed service contract awards. Transportation authorities mandate unified fare media acceptance across parking meters and bus or rail systems, creating cross-vertical qualification requirements. London boroughs lead procurement consolidation around integrated platform providers capable of delivering hardware, software, and payment processing.
Canada
Municipal procurement codes mandate accessibility standards and open-payment interoperability, tightening market access for non-compliant suppliers. Contactless payment mandates require tap-to-pay compatibility at all new meter installations, forcing replacement cycles for legacy equipment. Toronto and Vancouver anchor demand through smart city mobility infrastructure upgrades funded by federal-provincial partnerships.
Netherlands
Scandinavian and Dutch municipal operators pilot edge-computing architectures that process transactions locally during network outages. The country's national data protection authority enforces GDPR compliance burdens on cloud-connected meter deployments. Amsterdam and Rotterdam concentrate demand for curbside management platforms integrating parking meters with loading zone reservation systems and electric vehicle charging allocation.
Vehicle Parking Meter Market Competitive Landscape
Integrated platform providers and specialized hardware fabricators split the market along the service-contract versus equipment-sale divide. Municipal procurement consolidation compresses the addressable supplier base around vendors capable of unified hardware, software, and payment processing delivery. Three archetypes dominate: vertically integrated North American manufacturers, European service-revenue incumbents leveraging installed bases, and software-layer specialists embedding dynamic pricing algorithms. Competitive moves center on multi-year managed service contract underwriting against transaction fee shares, and edge-computing firmware development to reduce cloud dependency.
Within the integrated platform tier, IPS Group and Flowbird exemplify contrasting geographic anchors, with the former representing North American vertical integration and the latter European service-revenue persistence. CivicSmart occupies a position emphasizing software-layer differentiation over hardware manufacturing scale. These three companies illustrate the strategic divergence between hardware-centric and software-centric competitive positioning in municipal procurement environments.
| Leading Market Players |
|---|
| IPS Group |
| Flowbird |
| Duncan Solutions |
| Parking BOXX |
| Ventek International |
| CivicSmart |
| J.J. MacKay Canada Limited |
| Cale Access |
| LocoMobi |
| Others |
Value Network & Pricing Analysis
Cellular module supply concentration in East Asian semiconductor fabricators creates simultaneous pricing tier compression and supply chain vulnerability for parking meter manufacturers. This single-source dependency forces tier-one vendors to absorb component cost volatility while budget-tier competitors face extended lead times that erode municipal contract competitiveness.
Pricing Analysis
The FCC's equipment authorization requirements dictate the pricing tier structure across the United States market, separating premium cellular-enabled units from standard digital meters and economy mechanical alternatives. Price differentiation hinges on certification grade for wireless modules and the depth of software-layer integration, with dynamic pricing algorithms commanding substantial premiums over basic payment terminals. Cost compression in the economy tier is intensifying because municipal procurement consolidation favors multi-year managed service contracts that transfer hardware risk to vendors. Small cities with intermittent cellular coverage exhibit the highest price sensitivity, while major metropolitan authorities prioritize interoperability over unit cost.
Supply Chain Analysis
Photovoltaic cells for solar-powered housings and lithium battery packs feed from concentrated manufacturing bases in China, South Korea, and Japan. Semiconductor fabrication for cellular modules and edge-computing processors draws from Taiwan and South Korean foundries, with aluminum die-cast housings sourced from Chinese and Mexican metalworking clusters. Single-source vulnerability in cellular baseband chip supply creates exposure to trade policy disruptions and allocation delays. Distribution runs through municipal procurement departments consolidating vendor panels around integrated platform providers capable of unified hardware, software, and payment processing delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation around integrated platform providers has shifted bargaining power decisively toward buyer organizations, compressing margins for hardware-centric suppliers unable to bundle software and payment services.
For Market Incumbents: Build switching-cost moats through deep integration with municipal mobility platforms and transportation authority fare systems. IPS Group and Flowbird should anchor multi-year managed service contracts with performance guarantees that lock out competitors, while accelerating edge-computing firmware development to reduce cloud dependency and GDPR compliance burdens. Certification investment in FCC modular approvals and EU Radio Equipment Directive pre-qualifications creates regulatory barriers against emerging entrants lacking dedicated compliance capacity. For New Entrants and Emerging Players: Secondary cities in Canada and Australia with accessibility mandate gaps but limited enforcement staffing represent the most penetrable white-space targets. These municipalities favor retrofit digital meters over full smart meter deployments, creating entry points for vendors with card-reader modules and LED displays that bypass cellular connectivity requirements. A go-to-market angle emphasizing rapid installation speed and minimal trenching disruption aligns with property manager procurement priorities in mixed-use commercial developments. For Investors and Strategic Acquirers: The Infrastructure Investment and Jobs Act's funding sunset provisions reshape the acquisition landscape by compressing the window for hardware deployment returns before federal capital flows diminish. Long-term viability favors software-layer specialists with recurring SaaS revenue streams over equipment-dependent fabricators. Acquisition targets should demonstrate embedded dynamic pricing algorithms and API integration capabilities with curbside management platforms. The signal to watch is municipal RFP language shifting from capital equipment purchases to operational expenditure treatment for managed service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Firmware Development | On-device transaction processing reduces GDPR cloud compliance burdens and network outage vulnerability. |
| Multi-Year Managed Service Contract Underwriting | Transfers hardware deployment risk to vendors while capturing recurring transaction fee revenue streams. |
| Transportation Authority Fare System Integration | Unified payment media acceptance creates cross-vertical qualification advantages in United Kingdom and Netherlands procurement. |
| Curbside Management Platform Expansion | Integration with loading zone reservations and EV charging allocation opens municipal revenue diversification. |
| Open Payment Interoperability Certification | Tap-to-pay mandate compliance in United States and Canadian procurement codes tightens market access for non-compliant suppliers. |
Research Methodology
Cross-validation between municipal procurement officer interviews and parking technology vendor secondary disclosures anchors the qualitative findings in this study. Primary fieldwork encompassed transportation authority planners, parking operations directors at city transportation departments, private parking management company executives, and cellular module procurement specialists at meter manufacturers. Secondary validation drew from FCC equipment authorization databases, IIJA funding allocation disclosures, European Union Radio Equipment Directive certification registries, and municipal RFP document repositories. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending analysis.
Calibration against historical replacement cycles and federal funding authorization timelines shaped the projection framework across the analysis window. Segmentation modeling incorporated product type hierarchies, power and connectivity architectures, deployment context variations, and procurement authority structures. CAGRs were derived from elasticity-adjusted demand curves and technology substitution rates. Forecast inputs included cellular module supply allocation patterns, municipal budget appropriation cycles, and contactless payment mandate implementation schedules.
Practitioners should monitor IIJA funding reauthorization debates, East Asian semiconductor trade policy shifts, and GDPR enforcement precedents for early signals requiring forecast revision. Cross-checking against municipal capital improvement plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market