
 Electric Garbage Van Market | 2026-2036
Electric Garbage Van Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Garbage Van Market Foresight
Leasing and municipal fleet-as-a-service models is fragmenting capital barriers across the electric garbage van competitive landscape. BYD leverages integrated battery manufacturing to anchor cost structures in high-volume Asian deployments. Volvo sustains Scandinavian municipal relationships through extended service contracts and charging infrastructure bundling. Daimler competes across the full-size segment with established dealer networks that control aftermarket parts availability.
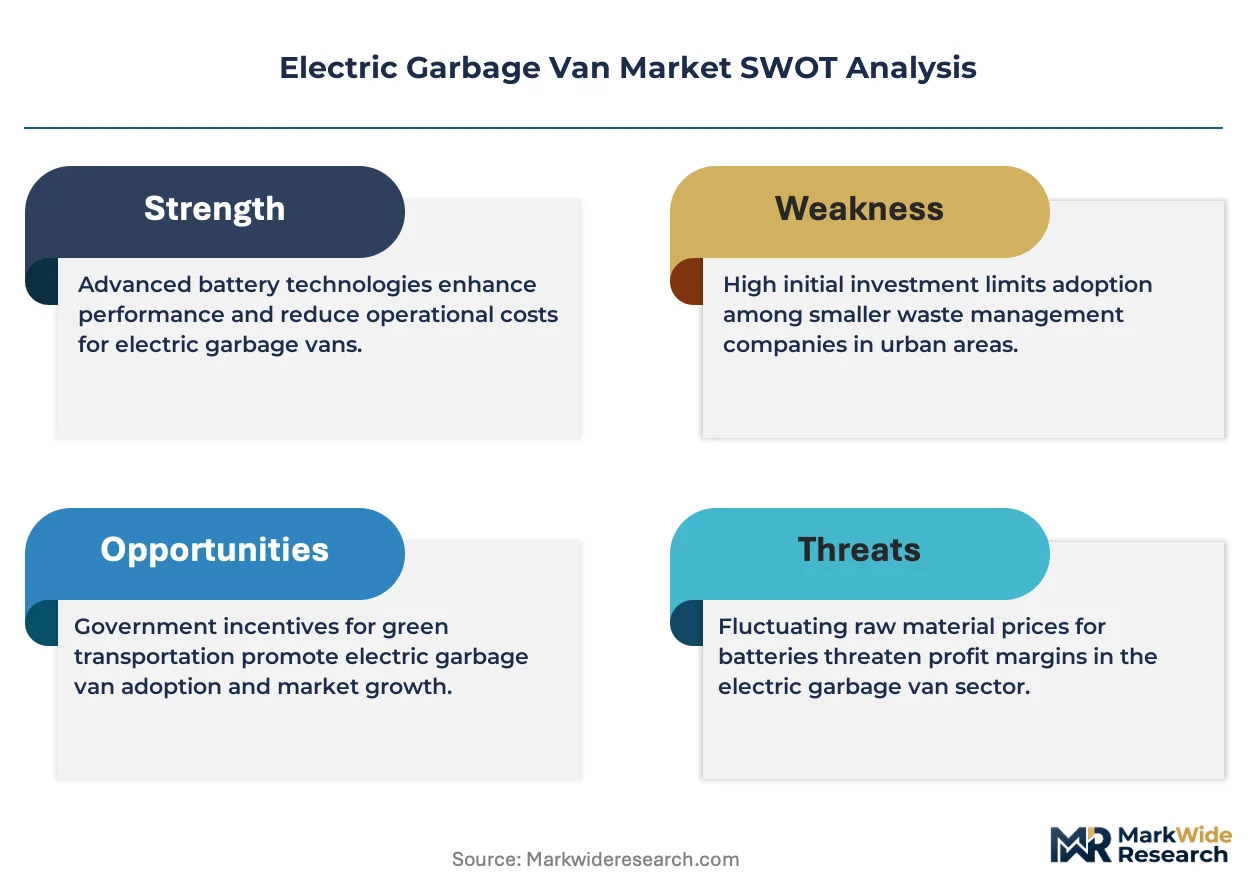
An electric garbage van is a purpose-built refuse collection vehicle propelled by electric drivetrains, typically incorporating 150-300 kWh battery packs, regenerative braking systems, and low-floor cab configurations to enable frequent stop-start urban operations. These vehicles serve municipal and commercial waste management operators seeking to eliminate tailpipe emissions during dense residential and commercial route cycles. Battery electric configurations dominate current order books while hydrogen fuel cell variants represent the fastest-growing power source for extended rural and suburban route profiles. Telematics integration now sits at the core of margin pools as fleet operators demand real-time energy consumption monitoring and predictive maintenance scheduling.
EPA emissions standards and the EU Green Deal framework shape product certification requirements and procurement eligibility across North American and European markets. The F-Gas Regulation and REACH compliance protocols constrain refrigerant and material choices in battery thermal management systems. California Air Resources Board mandates and Germany's KBA type-approval processes create divergent but equally stringent homologation pathways. Stakeholders must monitor subsidy renewal timelines and charging infrastructure build-out commitments to calibrate production capacity and regional market entry sequencing.
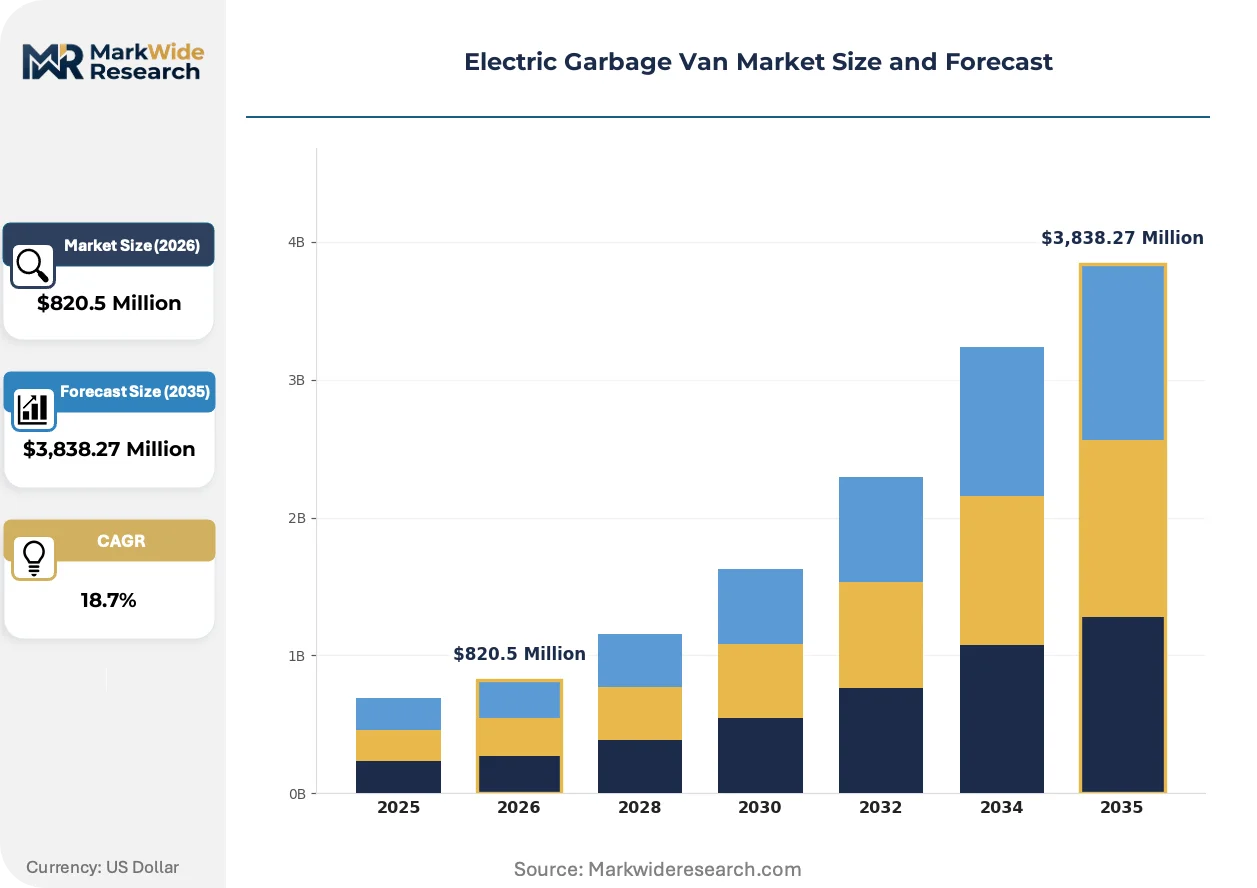
Market Dynamics
Municipal fleet electrification mandates are compressing procurement cycles as cities face binding zero-emission zone deadlines and diesel vehicle retirement cliffs. Battery energy density gains and charging infrastructure build-outs are now altering total cost of ownership calculations for sanitation departments.
Growth Catalysts
- California Air Resources Board mandates:Fleet purchase requirements under the Advanced Clean Trucks rule are forcing municipal sanitation departments to accelerate electric refuse vehicle procurement timelines.
- Lithium-ion energy density improvements:Cell chemistry advances are extending daily route range capabilities without increasing pack weight, enabling full-shift operations previously reserved for diesel platforms.
- Germany's municipal subsidy frameworks:Federal and state-level funding pools for zero-emission commercial vehicles are covering 40-80% of acquisition premiums in dense urban clusters.
Market Restraints
- Battery raw material concentration:Cobalt and lithium processing capacity concentrates in limited geographies, exposing fleet operators to supply disruption risks and input cost volatility.
- Charging infrastructure capital intensity:Depot upgrades requiring megawatt-scale grid connections and on-site energy storage impose six-figure installation costs per facility.
- F-Gas Regulation compliance friction:Thermal management system refrigerant restrictions under EU rules are constraining battery pack design options and extending homologation timelines.
Strategic Opportunities
- Japan's carbon-neutral waste collection targets:Prefecture-level mandates in Tokyo and Osaka are creating immediate demand for battery-electric and hydrogen fuel cell refuse platforms.
- Telematics-enabled fleet-as-a-service models:Real-time energy consumption monitoring and predictive maintenance bundling are opening recurring revenue streams beyond vehicle sales.
- Rural route hydrogen fuel cell convergence:Extended range requirements outside urban cores are accelerating pilot deployments of fuel cell-battery hybrid configurations.
Industry Challenges
- High-voltage technician skill gaps:Fleet maintenance departments lack certified personnel for 400-800V battery system diagnostics and repair, forcing reliance on OEM service networks.
- Divergent homologation pathways:Germany's KBA type-approval processes and EPA certification requirements create parallel testing burdens for manufacturers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Garbage Van Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,838.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact, Full-Size, Side Loader, Rear Loader Power Source: Battery Electric, Plug-in Hybrid, Hydrogen Fuel Cell, Range-Extended Electric End User: Municipalities, Waste Management Companies, Private Contractors, NGOs Technology: Telematics, Autonomous Driving, Charging Infrastructure, Battery Management |
| Companies Covered | Hop Motors, Prestantia, Ceeon India, Jessun Techno Private Limited, BYD, Daimler, Volvo, McNeilus, Heil Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Garbage Van Market Shifts & Advancements
Digital twin and simulation technologies are virtualizing vehicle development and fleet management workflows across the electric refuse vehicle sector. These capabilities compress design iteration cycles and enable predictive operational optimization.
Regenerative braking energy recovery systems are virtualizing kinetic waste into usable battery charge during the frequent stop-start cycles characteristic of residential waste collection. Municipal operators in Germany and California are retrofitting existing route planning software to capture these energy gains. The technology is compressing per-mile energy costs and extending effective range without pack expansion.
The EU Green Deal framework and its implementing regulations are tightening embodied carbon disclosure requirements for municipal procurement eligibility. REACH compliance protocols and battery passport mandates are forcing manufacturers to document supply chain provenance. European sanitation departments are now excluding bids that cannot demonstrate full lifecycle emissions transparency.
Leasing structures with bundled charging infrastructure are displacing traditional capital purchase models among budget-constrained municipalities. Fleet operators in Japan and select US states are prioritizing contracts that transfer technology obsolescence risk to vendors. This shift is most visible in California, where cities face accelerated compliance deadlines without matching capital appropriations.
Electric Garbage Van Market Segmentation
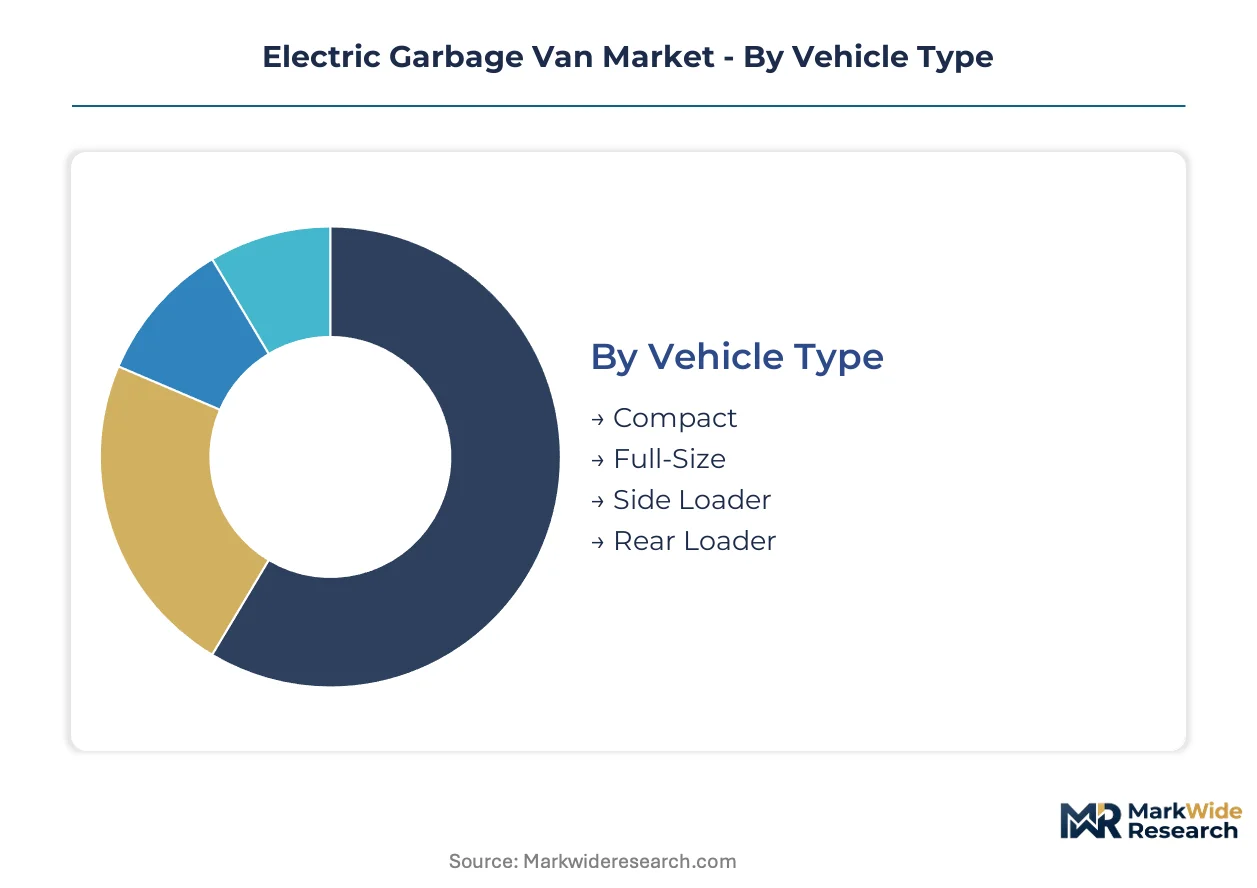
Segmentation in the electric garbage van market reveals how procurement priorities diverge across operational scales, energy strategies, and fleet management sophistication. Understanding these divisions enables manufacturers to align product development with the specific route profiles and regulatory pressures facing each buyer category.
Vehicle Type:
The use-case spectrum spans dense urban alleyways to high-volume suburban corridors, with chassis configuration directly determining payload capacity and maneuverability trade-offs.
- Compact:Narrow-body designs with sub-10-ton GVWR navigate restricted residential streets and historic districts. German cities including Munich and Hamburg are standardizing compact electric fleets for Altstadt waste collection where diesel bans are already enforced.
- Full-Size:Heavy-duty platforms exceeding 15-ton GVWR serve commercial and industrial routes with continuous high-volume pickup cycles. California municipalities facing CARB Advanced Clean Trucks mandates are prioritizing full-size electric replacements for diesel retirement cliffs.
- Side Loader:Automated arm configurations enable single-operator efficiency on standardized residential routes. Demand concentrates among waste management companies seeking labor cost reduction.
- Rear Loader:Manual and semi-automated rear compaction suits variable commercial waste streams with irregular container placements. Private contractors favor this flexibility for multi-site service contracts.
The dominant share belongs to Full-Size, while Compact is closing the gap fastest as zero-emission zone enforcement penetrates older European city centers.
Power Source:
Cost tier differentiation separates capital-intensive hydrogen deployments from battery-electric volume plays, with hybrid configurations serving transitional fleet strategies.
- Battery Electric:Lithium-ion packs ranging 150-300 kWh power the majority of current municipal orders. Tokyo and Osaka prefectures are accelerating procurement through combined national and metropolitan subsidy stacking.
- Hydrogen Fuel Cell:Fuel cell-battery hybrids extend range beyond 400 km for rural and exurban route profiles where depot charging infrastructure remains sparse. Pilot programs in Japan's mountainous prefectures are validating total cost of ownership models.
- Plug-in Hybrid:Dual-power architectures preserve operational flexibility during charging infrastructure build-out phases. Waste management companies with mixed urban-rural territories are deploying these as bridge technologies.
- Range-Extended Electric:Small combustion generators supplement battery packs for extended shifts without full hydrogen infrastructure investment. Private contractors serving dispersed commercial clients favor this configuration for route versatility.
Battery Electric commands the installed base, though Hydrogen Fuel Cell is expanding most quickly among operators with extended suburban coverage requirements.
End User:
Customer type determines procurement mechanism, with municipalities leveraging sovereign borrowing capacity against private sector fleet-as-a-service preferences.
- Municipalities:Direct ownership models with 10-15 year asset lifecycles dominate sanitation department procurement. German federal KfW funding pools and California HVIP vouchers are compressing payback periods for city fleets.
- Waste Management Companies:National and regional operators prioritize standardization across territory portfolios. Extended service contracts with OEMs are displacing traditional capital purchases.
- Private Contractors:Small and mid-sized operators demand financing structures that transfer technology obsolescence risk. Leasing penetration is highest among this segment in Japan and select US states.
- NGOs:Non-profit and environmental organizations deploy electric refuse vehicles for demonstration and education purposes. Funding depends on grant cycles rather than operational revenue streams.
Municipalities retain the largest order volume, while Waste Management Companies are consolidating procurement fastest through national fleet transition commitments.
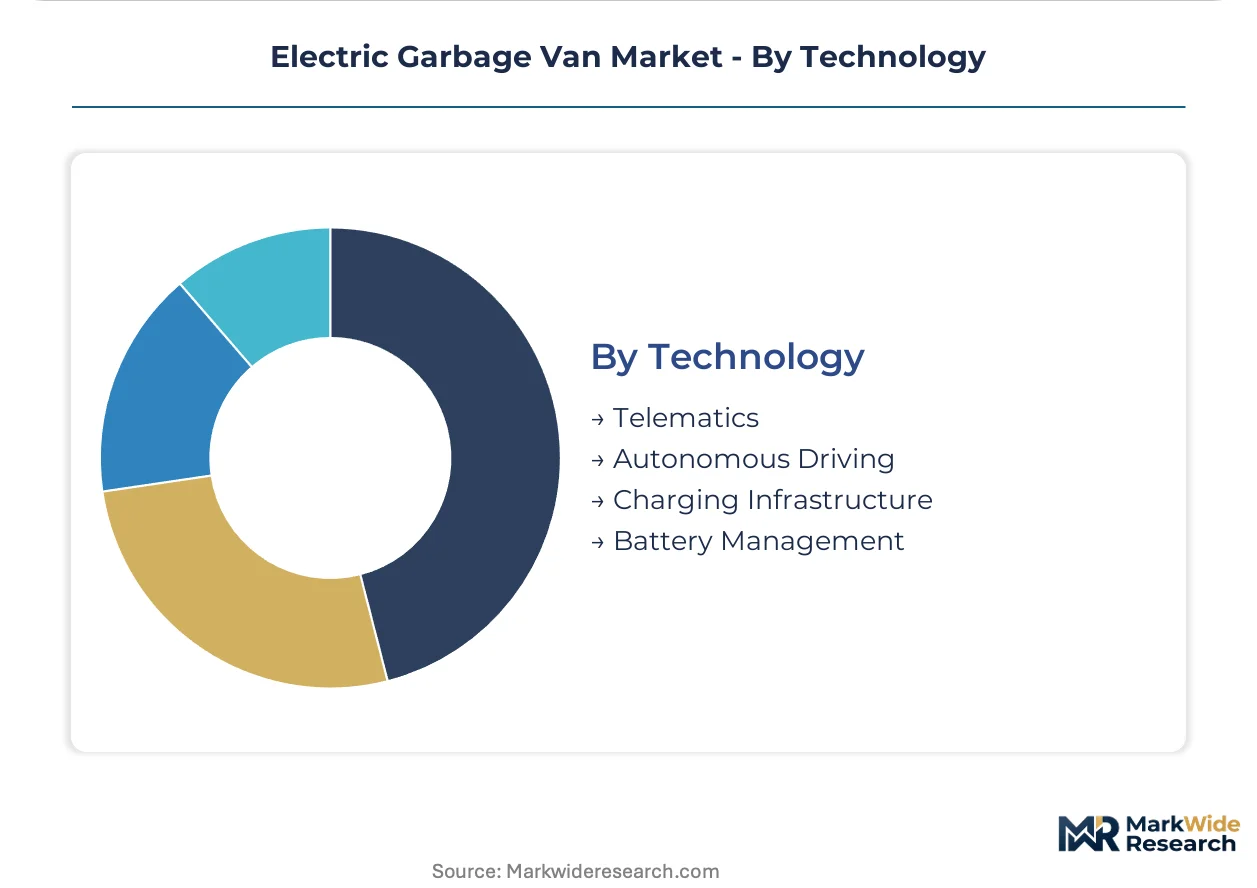
Technology:
Margin concentration shifts toward software-enabled services as hardware commoditization pressures intensify across battery and drivetrain components.
- Telematics:Real-time energy consumption monitoring and route optimization algorithms generate recurring SaaS revenue. EU Green Deal lifecycle emissions disclosure requirements are mandating telematics integration for procurement eligibility.
- Battery Management:Cell balancing and thermal regulation systems protect warranty terms and residual value. REACH compliance and F-Gas Regulation constraints are complicating refrigerant selection for thermal management architectures.
- Charging Infrastructure:Depot energy management and grid integration services bundle with vehicle sales. California utilities are co-funding megawatt-scale installations through rate-base mechanisms.
- Autonomous Driving:Low-speed automation for residential route following remains in pilot phase. Regulatory frameworks from NHTSA and KBA have not yet established homologation pathways for unsupervised operation.
Telematics generates the highest attach rates, while Battery Management is deepening integration fastest as cell chemistry diversity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KfW funding pools and California's HVIP voucher program are compressing payback periods for municipal sanitation departments. Battery-electric refuse vehicle procurement concentrates where subsidy frameworks align with enforced zero-emission zone deadlines.
United States
California Air Resources Board mandates under the Advanced Clean Trucks rule are forcing municipal fleet conversions ahead of diesel retirement cliffs. The HVIP voucher program covers substantial acquisition premiums for battery-electric refuse vehicles. Los Angeles and San Francisco sanitation departments are consolidating procurement through joint purchasing agreements to secure volume pricing.
Germany
Federal KfW funding pools combined with state-level subsidies now cover 40-80% of electric garbage van acquisition premiums. KBA type-approval processes create stringent homologation pathways that favor established manufacturers with certification expertise. Munich and Hamburg are deploying compact electric fleets for historic district waste collection where diesel bans are already enforced.
Japan
Prefecture-level carbon-neutral waste collection mandates in Tokyo and Osaka are generating immediate demand for battery-electric and hydrogen fuel cell platforms. METI subsidy frameworks support combined national and metropolitan funding stacking for municipal operators. Pilot programs in mountainous prefectures are validating fuel cell-battery hybrid configurations for extended rural routes.
China
Dual carbon goals and municipal air quality enforcement are accelerating fleet electrification in tier-one cities. MIIT standards and GB certification requirements shape product development for domestic manufacturers. Shenzhen and Beijing sanitation departments are deploying high-volume electric refuse fleets with integrated charging infrastructure at central depots.
United Kingdom
Ultra Low Emission Zone expansion in London is mandating zero-emission waste collection vehicles for contracted operators. Department for Transport funding pools support local authority fleet transition programs with grant-based acquisition support. Birmingham and Manchester are piloting hydrogen fuel cell refuse vehicles for suburban route coverage beyond battery-electric range limitations.
Electric Garbage Van Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Municipal fleet-as-a-service contracts favor vendors with integrated charging infrastructure bundling, while capital purchase markets reward manufacturing scale and battery cost positioning. Three archetypes dominate: integrated battery manufacturers leveraging cell chemistry control, established commercial vehicle builders with service network density, and regional specialists capturing subsidy-driven municipal orders. Competitive moves center on strategic partnerships for charging infrastructure deployment and geographic expansion through local assembly licensing.
Among the named players, BYD and Daimler occupy positions reflecting divergent strategic foundations. BYD represents the integrated battery manufacturing archetype with captive cell production anchoring cost structures. Daimler exemplifies the established commercial vehicle builder model with dealer network control over aftermarket parts availability. Volvo sits within the premium-tier service bundling segment, extending municipal relationships through extended maintenance contracts. Hop Motors, Prestantia, Ceeon India, Jessun Techno Private Limited, McNeilus, and Heil Co. populate the regional specialist and equipment fabricator tiers where local market knowledge and customization capabilities determine competitive viability.
| Leading Market Players |
|---|
| Hop Motors |
| Prestantia |
| Ceeon India |
| Jessun Techno Private Limited |
| BYD |
| Daimler |
| Volvo |
| McNeilus |
| Heil Co. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's container rate volatility transmits directly into landed battery pack costs, compressing margins for European assemblers while amplifying price spreads between integrated manufacturers and import-dependent competitors. This freight-cost wedge interacts with lithium carbonate contract structures to stratify procurement economics across municipal fleet operators and commercial waste management companies.
Pricing Analysis
Certification level (KBA type-approval versus EPA certification) creates the primary spread between premium and standard tiers, with dual-homologated platforms commanding acquisition premiums from multinational fleet operators. Battery management system warranty terms and charging infrastructure bundling serve as secondary differentiation levers. Cost compression in the compact vehicle segment is intensifying because BYD's captive cell production anchors price floors below European competitor cost structures. Municipal sanitation departments exhibit highest price sensitivity due to fixed capital appropriations, while waste management companies prioritize total cost of ownership over upfront acquisition cost.
Supply Chain Analysis
CATL, BYD, and LG Energy Solution hold dominant contract manufacturing capacity for lithium-ion battery modules serving electric refuse vehicle platforms. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Chinese chemical hubs. The supply chain draws from cobalt hydroxide feedstock originating in the Democratic Republic of Congo and refined lithium carbonate from Chilean salar operations. Single-source vulnerability in high-nickel cathode chemistries exposes assemblers to disruption risks from Indonesian nickel export policy shifts. Distribution runs through OEM-direct municipal procurement channels and regional dealer networks controlling aftermarket parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal fleet purchasing consolidation through joint procurement agreements across California and German city clusters is shifting negotiating leverage toward buyers, fragmenting vendor pricing power across standardized vehicle configurations.
For Market Incumbents: Pre-empt hydrogen fuel cell entrenchment in Japanese prefectures by accelerating fuel cell-battery hybrid platform certification before METI subsidy frameworks mature. Secure backward integration into battery thermal management component supply to defend margin position against refrigerant cost volatility under F-Gas Regulation compliance timelines. Channel control through extended service contract bundling remains the priority defensive lever against fleet-as-a-service disruptors. For New Entrants and Emerging Players: Establish a beachhead in Japan's mountainous prefecture pilot programs where fuel cell range extension creates immediate procurement eligibility outside BYD's battery-electric dominance. Target private contractor segments in select US states where leasing penetration transfers technology obsolescence risk and lowers capital barriers. A telematics-first go-to-market angle capturing predictive maintenance revenue streams opens recurring margin pools beyond hardware sales. For Investors and Strategic Acquirers: Regional charging infrastructure specialists with municipal utility relationships represent the most defensible acquisition target archetype for long-term positioning across the electrification transition. Platform standardization commitments from major waste management companies signal vendor consolidation inflection. Watch for KBA-EPA dual certification completion timelines as capacity allocation signals among established assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtake contracts secure cost positioning for European municipal fleet bids. |
| Charging Infrastructure Partnership | Utility co-funding mechanisms through California rate-base structures reduce depot upgrade capital intensity. |
| Geographic Manufacturing Footprint | Local assembly licensing in Germany satisfies KBA content requirements and compresses delivery lead times. |
| Platform Standardization | Common chassis architectures across compact and full-size variants spread R&D recovery across volume tiers. |
| Software-Defined Vehicle Investment | Over-the-air battery management updates extend vehicle residual value and deepen OEM service revenue attachment. |
Research Methodology
Operator-level perspectives from municipal fleet managers, waste management company procurement directors, charging infrastructure developers, and high-voltage technician training providers anchored the qualitative base. Primary fieldwork combined structured interviews with sanitation department planning officers and aftermarket service heads at major OEM networks. Secondary validation drew from EPA certification filings, KBA type-approval documentation, METI subsidy program disclosures, and California HVIP voucher utilization records. Bottom-up route economics modeling and top-down fleet replacement cycle analysis were triangulated against disclosed municipal procurement timelines.
Scenario bracketing around subsidy renewal schedules and charging infrastructure build-out commitments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, power source architecture, end-user procurement mechanism, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and fleet electrification mandate compliance deadlines. Battery energy density improvement curves and lithium carbonate contract price trajectories served as key forecast sensitivity inputs.
Sensitivities concentrate around METI and California subsidy renewal timelines, cobalt supply disruption scenarios, and F-Gas Regulation refrigerant substitution cost shocks. Forecasts reflect documented assumptions regarding municipal capital appropriation cycles and zero-emission zone enforcement schedules. Quarterly review of HVIP voucher exhaustion rates, KfW funding pool allocation announcements, and KBA certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Mini Truck Market