
 United States Vans Market | 2026-2036
United States Vans Market Size, Share, and Industry Trends Forecast 2026-2036
United States Vans Market Analytics
Michigan is rewriting commercial van manufacturing intensity as Detroit-area assembly plants retool for electrified platforms. Ford Motor Company leverages its River Rouge complex to sustain integrated van production from stamping to final assembly. General Motors Company anchors its commercial portfolio through GMC Savana and Chevrolet Express variants built in Wentzville, Missouri. Stellantis competes via Ram ProMaster output from its Saltillo, Mexico operations serving US commercial channels.
A van denotes a light commercial vehicle with enclosed cargo or passenger compartment, typically featuring unibody or body-on-frame construction with payload ratings between 1,500 and 4,500 pounds, designed for urban maneuverability and multi-stop duty cycles. Passenger vans and cargo vans remain the volume backbone, though electric vans represent the fastest-expanding segment as battery-electric range climbs past 200 miles and total cost of ownership improves for fleet operators. Full-size vans capture the dominant margin pool in commercial channels, while compact vans face displacement from crossover utility vehicles in retail consumer segments.
The EPA administers Corporate Average Fuel Economy standards that tighten van fleet efficiency requirements, while NHTSA enforces Federal Motor Vehicle Safety Standards governing crashworthiness and autonomous system integration. California Air Resources Board operates under EPA waiver authority to mandate zero-emission van sales quotas that cascade to thirteen adopting states. Fleet managers and OEM product planners must weigh charging infrastructure readiness against total cost of ownership thresholds as electrification mandates phase in across jurisdictions.
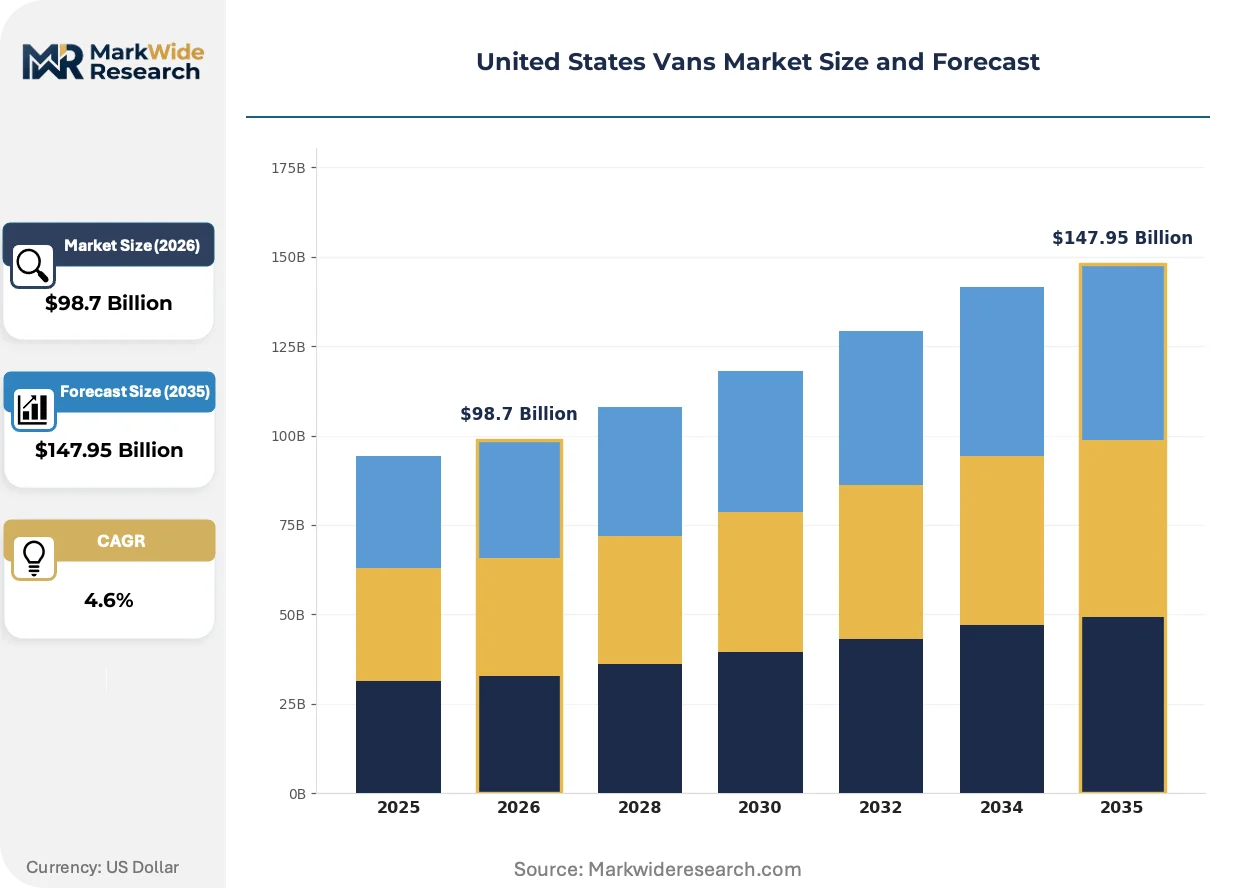
Market Dynamics
EPA emissions standards and California's Advanced Clean Trucks regulation are compressing fleet procurement timelines, forcing operators to accelerate electrification investments ahead of total cost of ownership parity.
Growth Catalysts
- Last-mile logistics density:E-commerce fulfillment networks in Texas and Florida corridors are expanding van procurement for urban delivery routes. Fleet operators prioritize payload capacity and maneuverability in dense metropolitan zones.
- IRA commercial vehicle incentives:Federal tax credits for zero-emission commercial vehicles reduce upfront acquisition costs for electric van adopters. The incentive structure favors vehicles under 14,000 pounds gross vehicle weight rating.
- Battery energy density gains:Lithium iron phosphate cell chemistry improvements extend electric van range past 200 miles per charge. This threshold eliminates range anxiety for multi-stop urban duty cycles.
Market Restraints
- Charging infrastructure gaps:DC fast charging networks remain concentrated along interstate corridors, leaving secondary urban routes underserved. Fleet depots require electrical service upgrades averaging six-figure capital outlays.
- Lithium supply concentration:Cathode material processing concentrates in China, creating geopolitical exposure for US-based battery assembly operations. Domestic mining and refining capacity expansion lags cell manufacturing buildout.
- Payload-range tradeoff:Battery weight reduces available cargo capacity versus internal combustion equivalents. Refrigerated van operators face compounded efficiency penalties from thermal management electrical loads.
Strategic Opportunities
- Rural fleet electrification:Secondary markets in the Mountain West and Great Plains remain underpenetrated by electric van distribution. Early entrants capture fleet relationships before infrastructure matures.
- Vehicle-to-grid integration:Bidirectional charging capability transforms fleet assets into grid stabilization resources. Utility demand response programs create ancillary revenue streams for large fleet operators.
- Modular upfit ecosystems:Standardized electric platform architectures enable rapid body configuration swaps between cargo, passenger, and specialty applications. Upfitters reduce time-to-delivery from months to weeks.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance requires specialized certification beyond traditional automotive repair training. Community college programs and OEM academies struggle to graduate sufficient qualified technicians.
- Depot electrical permitting:Local utility interconnection approvals extend fleet electrification project timelines by 12-18 months. Jurisdictional variation in building codes creates unpredictable deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Vans Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vans, Cargo Vans, Minivans, Electric Vans End User: Commercial Users, Retail Consumers, Government Agencies, Transportation Services Size: Compact, Standard, Full-Size, Extended Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | Ford Motor Company, General Motors Company, Mercedes-Benz Group, Stellantis, Ram, Chevrolet, Nissan Motor Co., Volkswagen AG, Workhorse Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Vans Market Evolving Landscape
Telematics integration and predictive maintenance algorithms are compressing vehicle lifecycle management from reactive repair to preemptive intervention, reshaping how fleet operators calculate total cost of ownership.
Silicon carbide power electronics are replacing insulated-gate bipolar transistors in electric van inverters, enabling higher switching frequencies and reduced thermal losses. Tier 1 suppliers are scaling production for 2025-2026 model year integration. This efficiency gain is rendering obsolete the range penalties that previously constrained electric van adoption in high-mileage commercial applications.
California Air Resources Board's Advanced Clean Trucks regulation mandates zero-emission vehicle sales quotas that cascade to thirteen adopting states through EPA waiver authority. Fleet managers in affected jurisdictions must now model compliance pathways across multi-state operational territories. Large national operators are prioritizing electric van procurement for California-based routes while maintaining internal combustion assets elsewhere.
Fleet leasing structures are displacing traditional vehicle ownership models among small and mid-size commercial operators. Full-service leases bundle maintenance, charging infrastructure, and energy management into per-mile pricing. This shift concentrates procurement authority with national fleet management companies and reduces direct OEM relationships for end-users in the Southeast and Texas logistics corridors.
United States Vans Market Segmentation
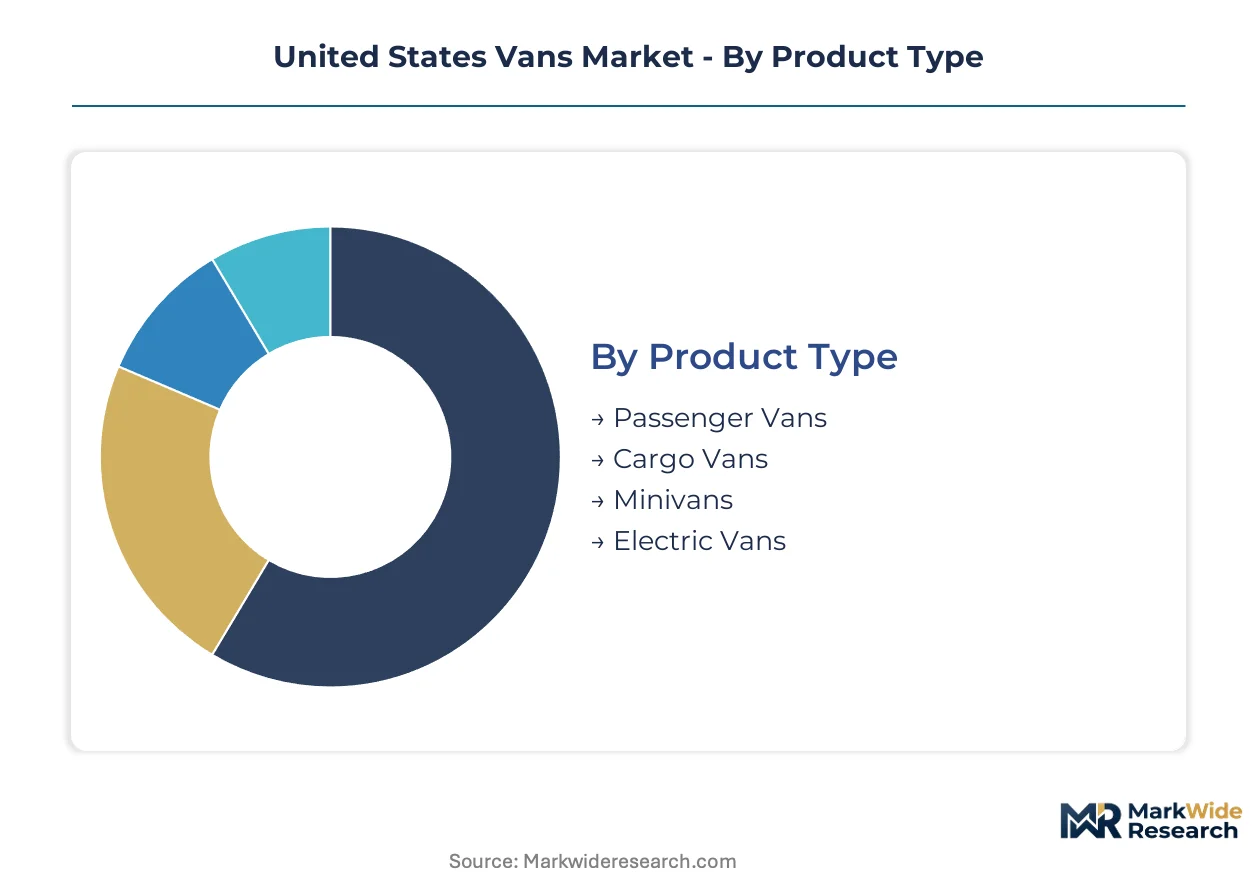
Segmentation in the United States vans market reveals how fleet operators, retail buyers, and government purchasers prioritize fundamentally different attributes. Procurement patterns diverge sharply across product configuration, duty cycle intensity, and compliance requirements.
Product Type:
Application use case determines platform selection, with enclosed cargo capacity and passenger seating configurations driving fundamentally different engineering priorities.
- Cargo Vans:Enclosed unibody or body-on-frame construction with payload ratings between 1,500 and 4,500 pounds, optimized for multi-stop urban delivery cycles. Demand concentrates in Texas and Florida logistics corridors where last-mile fleet operators prioritize maneuverability in dense metropolitan zones combined with EPA fuel economy compliance pressures.
- Electric Vans:Battery-electric powertrains with lithium iron phosphate cell chemistry extending range past 200 miles per charge. Fleet procurement in California accelerates under CARB Advanced Clean Trucks regulation mandates, creating compliance-driven demand despite depot charging infrastructure gaps.
- Passenger Vans:Multi-row seating configurations for institutional and commercial shuttle applications.
- Minivans:Unibody family-oriented vehicles facing displacement from crossover utility vehicles in retail consumer segments.
Cargo vans hold installed capacity. Electric vans are rotating up the share rankings.
End User:
Customer type shapes volume commitment, financing structure, and replacement cycle predictability across the procurement base.
- Commercial Users:Fleet operators managing 50-plus vehicle portfolios with centralized maintenance facilities and telematics integration. Procurement concentrates in Southeast and Texas corridors where e-commerce fulfillment networks expand van deployment for urban delivery routes combined with IRA commercial vehicle tax credit eligibility.
- Retail Consumers:Individual purchasers prioritizing passenger capacity and fuel efficiency for family transportation. Demand localizes in suburban markets where minivan segments face sustained crossover utility vehicle competition.
- Government Agencies:Municipal and federal fleets subject to federal procurement standards and electrification mandates.
- Transportation Services:Shuttle operators, paratransit providers, and ride-hail fleet managers serving fixed-route and on-demand mobility.
Commercial users hold installed capacity. Electric van adoption among government agencies is rotating up the share rankings.
Size:
Dimensional class determines payload-range tradeoffs, parking accessibility, and upfit compatibility for specialized body configurations.
- Full-Size:Extended wheelbase and roof height variants maximizing enclosed cargo volume for high-payload commercial applications. Fleet procurement in California and Texas prioritizes these platforms for parcel delivery density combined with driver productivity per route.
- Compact:Short wheelbase configurations optimized for urban maneuverability and parking-constrained environments. Demand localizes in older northeastern metropolitan cores where street width and garage clearance restrict larger van deployment.
- Standard:Mid-length wheelbase balancing cargo capacity with drivability.
- Extended:Maximum-length variants for specialized upfit applications requiring elongated cargo floors.
Full-size vans hold installed capacity. Compact configurations are rotating up the share rankings.
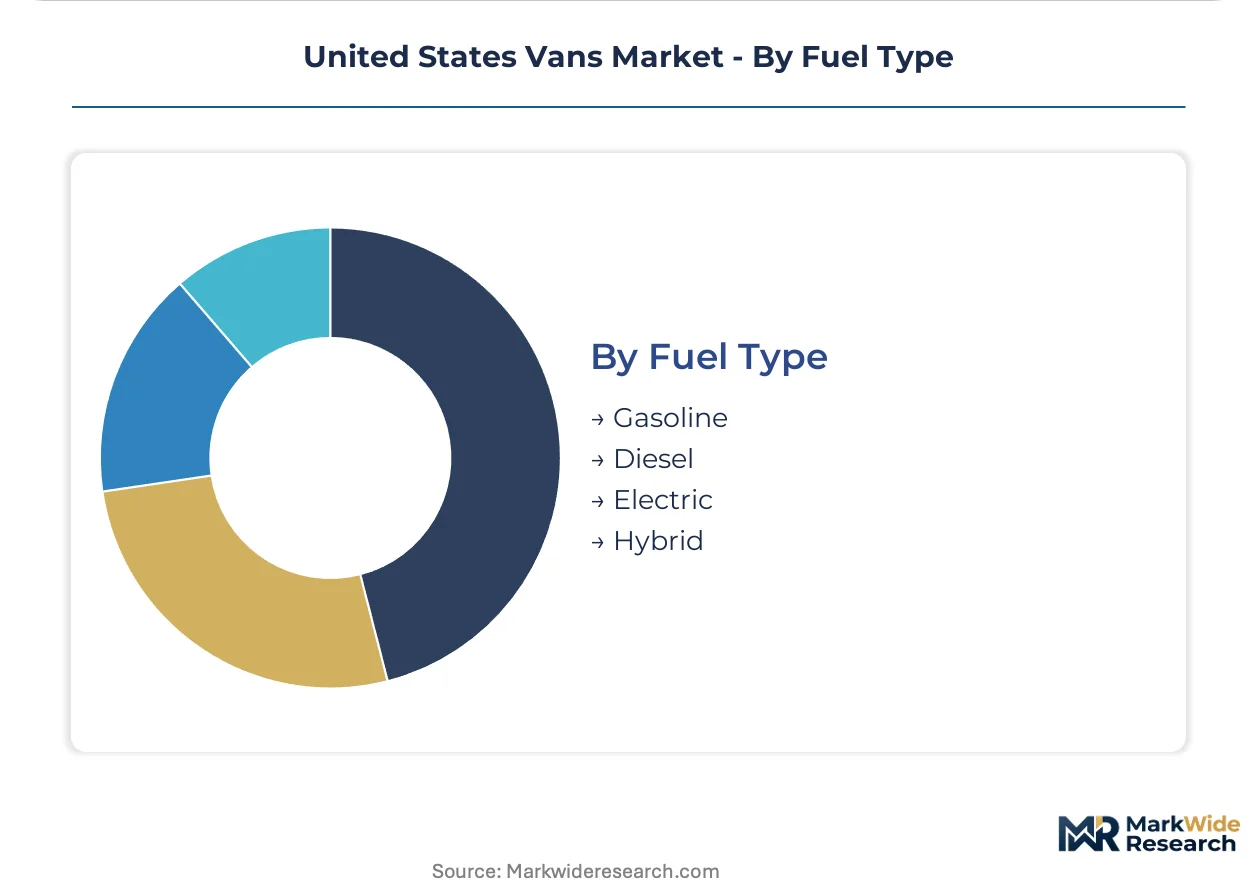
Fuel Type:
Powertrain selection increasingly reflects regulatory compliance timelines rather than pure total cost of ownership optimization.
- Electric:Battery-electric drivetrains with silicon carbide power electronics replacing insulated-gate bipolar transistors for efficiency gains. Fleet procurement accelerates in California and thirteen adopting states under CARB zero-emission sales quotas combined with IRA commercial vehicle incentives.
- Gasoline:Internal combustion engines dominating current installed fleet with established refueling infrastructure. Demand persists in Texas and Florida corridors where fleet operators defer electrification until charging infrastructure matures.
- Diesel:Compression-ignition powertrains for high-torque towing and extended-range highway duty cycles.
- Hybrid:Electrified powertrains without plug-in capability serving transitional fleet strategies.
Gasoline powertrains hold installed capacity. Electric drivetrains are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in the Great Lakes corridor and northern Mexico, with Detroit-area plants retooling for electrified platforms and Saltillo operations feeding commercial channels across the southern border states. Fleet procurement concentrates in logistics corridors where population density and e-commerce fulfillment networks sustain replacement cycles.
California
CARB's Advanced Clean Trucks regulation mandates zero-emission van sales quotas that cascade to thirteen adopting states. Fleet operators in Los Angeles and San Francisco metro areas accelerate electric procurement ahead of compliance deadlines. Silicon Valley telematics providers integrate predictive maintenance platforms for electrified commercial fleets.
Texas
Dallas-Fort Worth and Houston logistics hubs expand last-mile delivery fleets as e-commerce fulfillment networks densify. Fleet operators defer full electrification until charging infrastructure matures along secondary urban routes. The state's independent grid operator creates uncertainty for depot electrification load management.
Michigan
Detroit-area assembly plants at the River Rouge complex sustain integrated van production from stamping through final assembly. EPA fuel economy standards drive powertrain diversification investments. Flint and Lansing supplier networks retool for battery-electric component manufacturing.
Florida
Miami and Tampa metropolitan zones prioritize compact van configurations for dense urban delivery cycles. Fleet leasing structures displace traditional ownership among mid-size commercial operators. The state's hurricane resilience requirements influence depot charging infrastructure hardening specifications.
Missouri
Wentzville assembly operations anchor commercial van production for GMC and Chevrolet variants serving national fleet channels. NHTSA safety standards enforcement shapes autonomous system integration timelines. Kansas City logistics corridors connect Midwest distribution networks to southeastern markets.
United States Vans Market Competitive Landscape
Legacy Detroit manufacturers and European premium marques split the market along fleet-versus-retail segmentation lines. The structure concentrates procurement authority with national fleet management companies that bundle maintenance and charging infrastructure into full-service leases. Three archetypes dominate: vertically integrated domestic OEMs with captive financing arms, European luxury brands emphasizing driver comfort specifications, and emerging electric specialists targeting compliance-driven California procurement. Competitive moves center on platform electrification investments and strategic partnerships with charging network operators.
Among Detroit-based manufacturers, Ford Motor Company and General Motors Company exemplify the vertically integrated archetype with end-to-end production control from component stamping through final assembly. Stellantis occupies a position spanning North American fleet channels and European-derived platform architectures. These three anchors represent distinct strategic postures: integrated domestic production, multinational platform sharing, and compliance-focused powertrain diversification.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Mercedes-Benz Group |
| Stellantis |
| Ram |
| Chevrolet |
| Nissan Motor Co. |
| Volkswagen AG |
| Workhorse Group Inc. |
| Others |
Value Network & Pricing Analysis
Assembly plant undercapacity in the Great Lakes corridor is compressing supplier lead times while elevating pricing leverage for domestic OEMs with captive stamping and final assembly operations. Fleet procurement concentration in Texas and California logistics hubs amplifies regional price differentiation as operators weigh electrification compliance costs against total cost of ownership thresholds.
Pricing Analysis
EPA Corporate Average Fuel Economy standards dictate the pricing tier structure across gasoline, hybrid, and battery-electric van configurations. Three-tier pricing separates fleet-volume contracts from mid-size commercial leases and retail consumer transactions. Price differentiation rests on electrification compliance grade and IRA tax credit eligibility rather than payload capacity alone. Cost compression in entry-level gasoline variants is intensifying because fleet operators defer electrification until charging infrastructure matures. Small and mid-size commercial operators exhibit highest price sensitivity, while national fleet management companies with full-service lease structures demonstrate lowest sensitivity due to bundled energy management.
Supply Chain Analysis
Tier 1 suppliers including Bosch, Denso, and Magna hold concentrated capacity for electric powertrain components feeding Detroit-area assembly operations. Geographic supply concentration centers on Mexico for body-on-frame platforms, South Korea for battery cell assembly, and China for cathode material processing. Raw material dependencies include lithium carbonate, nickel sulfate, and silicon carbide substrates for inverter efficiency gains. Single-source vulnerability in Chinese cathode refining creates geopolitical exposure for US-based battery operations. Distribution runs through national fleet management companies that bundle vehicle procurement with charging infrastructure and maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States vans market is recovering from cyclical lows as e-commerce fulfillment density and regulatory compliance timelines compress fleet replacement cycles. IRA commercial vehicle incentives and CARB zero-emission mandates constitute the primary cyclical driver accelerating procurement ahead of historical patterns.
For Market Incumbents: Build captive charging infrastructure moats by deploying depot electrification services alongside vehicle sales to national fleet operators. Prioritize backward integration into battery pack assembly at River Rouge and Wentzville complexes to secure cell supply against Chinese cathode concentration. Defensive positioning requires accelerating silicon carbide inverter sourcing before Tier 1 capacity constraints materialize.
For New Entrants and Emerging Players: Pursue white-space opportunities in rural Mountain West and Great Plains markets where electric van distribution remains underpenetrated and fleet relationships are unsettled. Target secondary urban routes in Texas corridors where charging infrastructure gaps delay incumbent electrification timelines. Go-to-market positioning should emphasize modular upfit ecosystems enabling rapid body configuration swaps for specialty commercial applications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric platform development as OEMs retool stamping lines and assembly sequences for electrified architectures. Long-term viability over the next decade hinges on securing lithium supply agreements and qualifying for IRA domestic content bonuses. Acquisition targets should display established fleet relationships in California compliance corridors and demonstrated depot electrification deployment capability. Quarterly review of CARB waiver adoption state counts and DC fast charging network expansion metrics is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Electrification Investment | Retooling River Rouge and Wentzville stamping lines for battery-electric van architectures secures EPA compliance pathways. |
| Charging Infrastructure Partnership | Depot electrification bundling with fleet leases concentrates procurement authority with national fleet management companies. |
| Battery Supply Agreement | Domestic cell sourcing from South Korean partners reduces Chinese cathode concentration exposure for IRA credit eligibility. |
| Modular Upfit Ecosystem Development | Standardized electric platform architectures enable rapid body swaps from cargo to passenger configurations. |
| Telematics Platform Integration | Predictive maintenance algorithms compress lifecycle management from reactive repair to preemptive intervention. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and charging infrastructure developers and refined through secondary validation. Fleet procurement directors at national operators provided volume commitment and replacement cycle intelligence. OEM platform engineers disclosed powertrain diversification timelines and retooling capital allocation. Tier 1 supplier account managers revealed silicon carbide inverter capacity scaling plans. Charging infrastructure developers detailed depot electrical permitting timelines and utility interconnection bottlenecks. Secondary sources included EPA fuel economy compliance filings, CARB Advanced Clean Trucks regulatory dockets, NHTSA safety standard rulemakings, and IHS Markit vehicle registration databases. Bottom-up fleet operator surveys triangulated against top-down OEM production forecasts.
Demand-supply balance modeling anchored projections across the analysis window, with fleet procurement intentions weighted against assembly plant capacity utilization and battery cell supply commitments. Segmentation dimensions included propulsion architecture, vehicle size class, end-use application, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to electrification mandate phase-in schedules and IRA incentive eligibility windows. Industry-specific forecast inputs incorporated CARB zero-emission sales quota enforcement intensity and DC fast charging network buildout velocity along secondary urban routes.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, diesel-gasoline price spreads, or lithium carbonate spot pricing would shift the trajectory of fleet electrification adoption. Forecasts reflect assumptions regarding regulatory enforcement continuity and charging infrastructure deployment schedules. Quarterly review of CARB waiver state adoption counts, depot electrical permitting approval velocities, and high-voltage technician graduation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Japan Commercial Vehicles Market