
 Cryogenic Liquid Transport Vehicle Market | 2026-2036
Cryogenic Liquid Transport Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Liquid Transport Vehicle Market Analysis
Carbon fiber composite is consolidating its position as a substitute for conventional aluminum alloy in cryogenic tank construction, reducing vehicle tare weight by substantial margins while improving thermal insulation performance. Chart Industries leverages in-house vacuum insulation expertise to anchor North American supply chains for liquid hydrogen road transport. CIMC Enric dominates cylindrical tank manufacturing scale across Asia, while Linde AG sustains captive fleet operations that integrate production with logistics control.
A cryogenic liquid transport vehicle is a purpose-built mobile containment system engineered to sustain temperatures below minus 150 degrees Celsius through multi-layer vacuum insulation and pressure-rated vessel design, primarily serving the distribution of liquefied natural gas, liquid oxygen, liquid nitrogen, and liquid hydrogen from production facilities to end-use sites. Tankers and semi-trailers command the largest installed base due to highway accessibility and modal flexibility across continental supply corridors. Medium-capacity vessels between 11 and 50 cubic meters represent the fastest-expanding configuration as regional hydrogen refueling networks require frequent, moderate-volume deliveries rather than bulk terminal transfers.
DOT regulations in the United States, ADR provisions in Europe, and China's GB standards collectively mandate periodic pressure vessel recertification, crashworthiness testing, and materials traceability that elevate manufacturing compliance costs while screening out low-capability fabricators. ECE R110 specifically governs compressed gaseous and liquefied hydrogen vehicle components, creating a dual-certification burden for OEMs serving cross-border European routes. Stakeholders must monitor evolving national hydrogen strategies and corresponding fleet procurement timelines to align capacity investments with infrastructure deployment velocity.
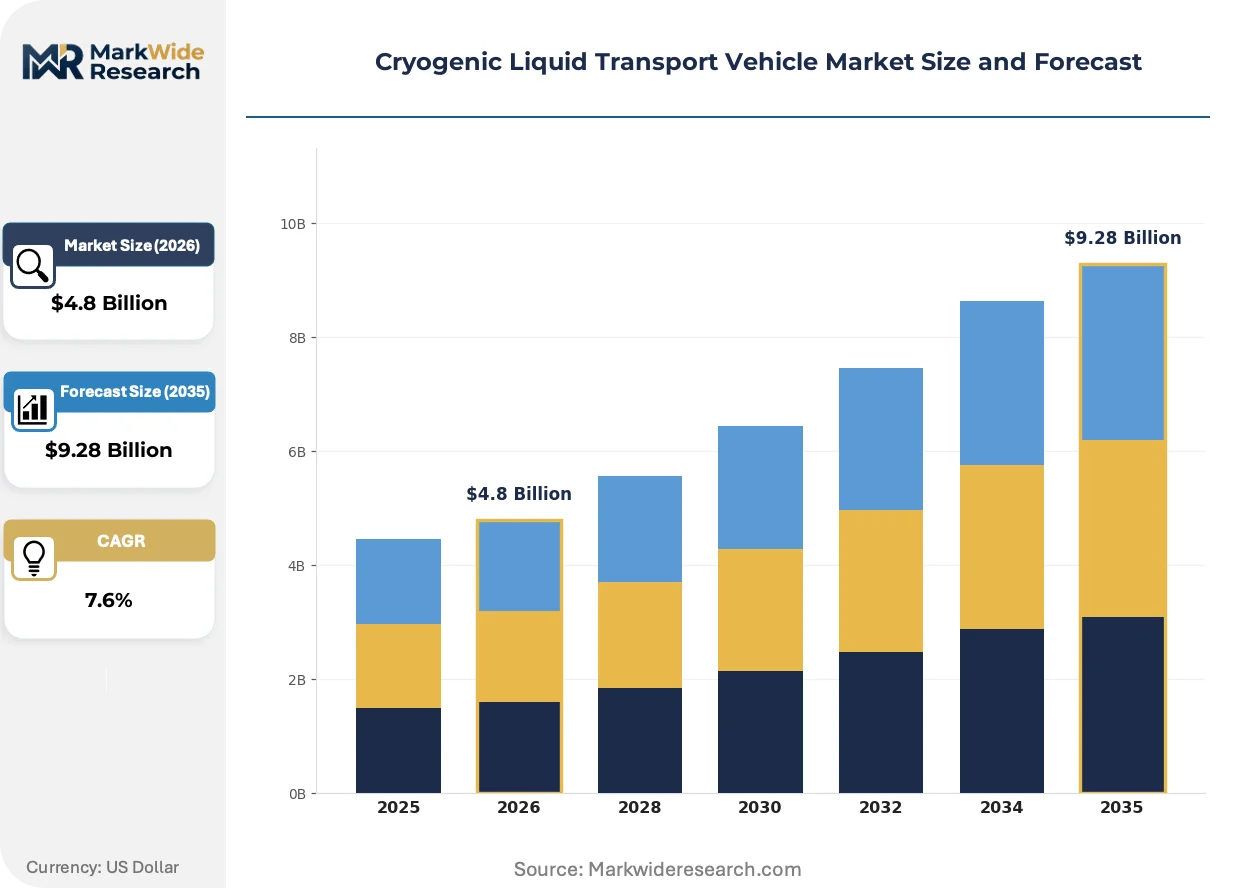
Market Dynamics
The transition from aluminum alloy to carbon fiber composite tank construction is compressing vehicle tare weight and extending thermal hold times, forcing incumbent fabricators to retool vacuum insulation production lines or cede regional hydrogen logistics contracts to composite-capable competitors.
Growth Catalysts
- Liquid Hydrogen Distribution Networks:Germany, Japan, and South Korea are deploying highway-accessible hydrogen refueling corridors that require dedicated cryogenic road transport capacity. Fleet operators in these markets are placing multi-year vessel procurement contracts.
- ECE R110 Certification Harmonization:The European regulation governing hydrogen vehicle components is creating cross-border equipment standardization, reducing OEM compliance duplication for tank systems serving France, Germany, and Benelux routes.
- Carbon Fiber Manufacturing Scale-Up:Automated filament winding and resin transfer molding advances are lowering composite tank unit costs, enabling mid-capacity vessel configurations that match regional delivery economics.
Market Restraints
- Specialized Welding Labor Scarcity:Vacuum-insulated vessel fabrication requires certified cryogenic welders, with training pipelines in the United States and Germany failing to match fleet expansion timelines.
- Stainless Steel Price Volatility:Inner vessel construction relies on 304L and 316L grades, with nickel content exposing fabricators to London Metal Exchange price swings that compress quoted margins.
- Dual-Certification Burden:OEMs serving European cross-border routes must satisfy both ECE R110 and national ADR provisions, extending engineering validation cycles and screening out smaller tank builders.
Strategic Opportunities
- India Hydrogen Hub Development:The country's National Hydrogen Mission is catalyzing liquid hydrogen production investments in Gujarat and Tamil Nadu, creating first-mover vessel deployment opportunities ahead of dedicated transport infrastructure.
- Small-Scale LNG Bunkering:Maritime decarbonization regulations at the International Maritime Organization level are driving port-side LNG fuelling networks that demand compact cryogenic road delivery systems.
- Modular Tank Leasing Models:Industrial gas majors are piloting containerized swap-body systems that separate asset ownership from logistics operation, opening fleet financing structures for independent transport operators.
Industry Challenges
- ECE R110 Type-Approval Timelines:European hydrogen component certification requires witnessed burst testing and fire exposure validation that extends product launch schedules by 8-14 months.
- Legacy Fleet Retrofit Complexity:Existing LNG-dedicated trailers lack pressure ratings and safety system architectures compatible with liquid hydrogen service, constraining asset redeployment options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Liquid Transport Vehicle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tankers, Trailers, Containers, Semi-Trailers End User: Industrial Gas Companies, Energy Sector, Research Institutions, Food and Beverage Companies Capacity: Small (1-10m³), Medium (11-50m³), Large (51-100m³), Extra Large (100m³+) Deployment: Onshore, Offshore, Land Transport, Rail Transport |
| Companies Covered | Cryolor, CIMC Enric, Chart Industries, Cryogenmash, Zhangjiagang Furui Special Equipment, Linde AG, Wessington Cryogenics, FIBA Technologies, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Liquid Transport Vehicle Market Emerging Trajectories
Materials substitution and regulatory harmonization are converging to reshape competitive positioning in cryogenic transport equipment, with fabrication technology advances enabling vessel configurations previously uneconomical at commercial scale.
Carbon fiber composite is overtaking aluminum alloy in cryogenic tank construction. The material reduces tare weight by substantial margins while improving thermal insulation performance. Industrial gas distributors in Germany and Japan are specifying composite vessels for new hydrogen fleet orders. This shift is compressing the addressable market for conventional aluminum tank fabricators unable to retool filament winding capabilities.
REACH and the EU Green Deal are tightening materials traceability and end-of-life recycling requirements for pressure equipment placed on the European market. Fabricators must now document carbon fiber resin systems and stainless steel alloy compositions through the supply chain. Tank OEMs serving cross-border European routes are consolidating supplier bases to reduce compliance audit burden.
Refueling station operators are consolidating procurement around medium-capacity vessels between 11 and 50 cubic meters. Bulk terminal transfers once dominated fleet planning. Regional hydrogen networks in California, Germany, and South Korea now favor frequent, moderate-volume deliveries that match station storage constraints and demand profiles. This pattern is visible where infrastructure deployment precedes mass fleet adoption.
Cryogenic Liquid Transport Vehicle Market Segmentation
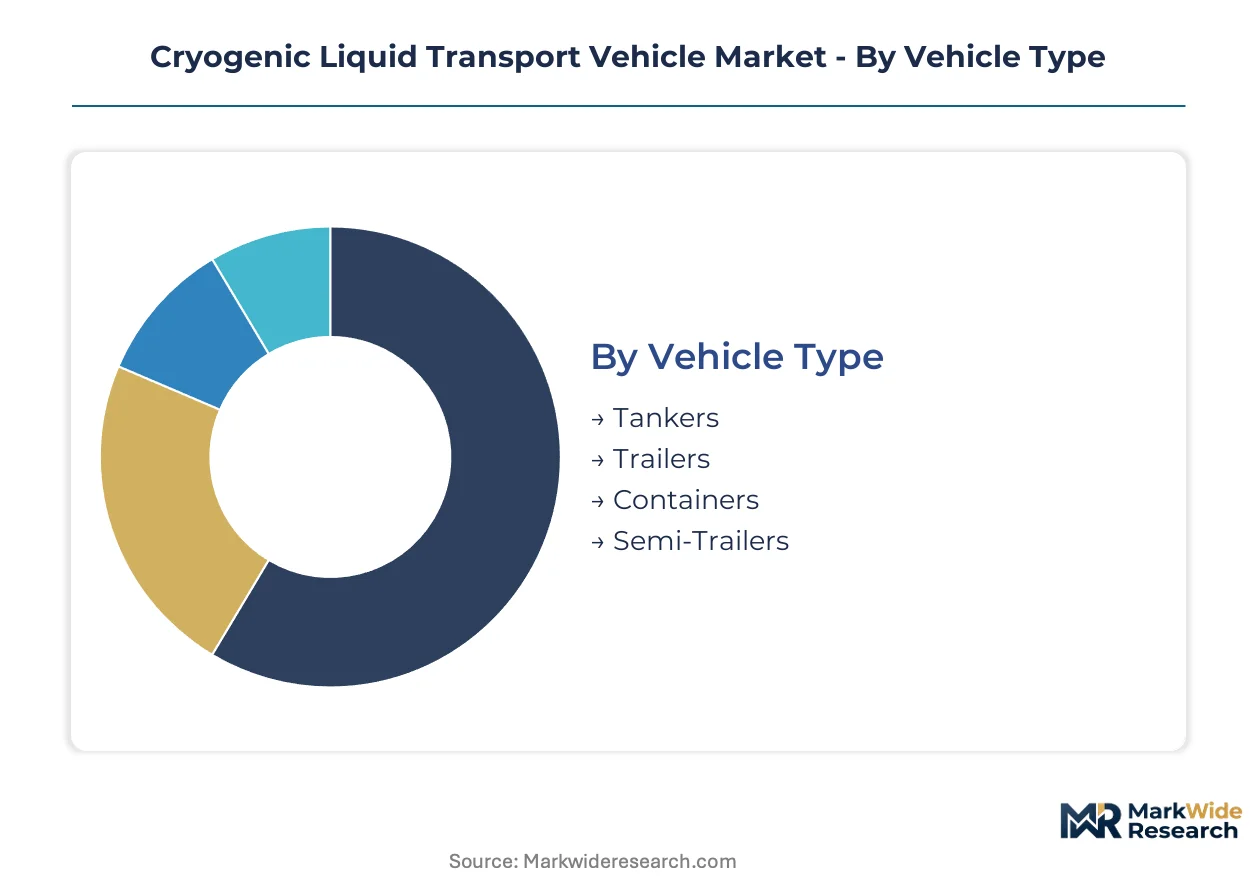
Cryogenic liquid transport equipment varies dramatically in capital requirements, certification burden, and operational flexibility across configuration types. Segment selection directly determines vessel pressure ratings, insulation specifications, and regulatory compliance pathways that shape procurement economics.
Vehicle Type:
Tankers and semi-trailers demand the heaviest upfront capital outlays due to chassis integration, vacuum insulation systems, and multi-jurisdictional homologation requirements.
- Tankers:Purpose-built rigid vehicles with integrated cryogenic vessels and dedicated chassis configurations. Demand concentrates in Germany and Japan where liquid hydrogen refueling corridors require highway-accessible delivery fleets with ECE R110 certification.
- Semi-Trailers:Detachable vessel units mounted on standardized fifth-wheel chassis, offering modal flexibility across continental supply corridors. Fleet operators in the United States favor this configuration for interstate LNG distribution due to tractor interchangeability and reduced asset idle time.
- Trailers:Smaller-capacity towable units designed for localized industrial gas delivery and backup supply redundancy.
- Containers:Intermodal tank systems engineered for rail-to-road transfer and maritime logistics integration.
Most installed capacity flows through Semi-Trailers. Expansion is steepest in Tankers as hydrogen infrastructure accelerates.
End User:
Customer procurement patterns diverge sharply between captive fleet operators and third-party logistics providers, with contract structures ranging from asset ownership to long-term vessel leasing.
- Industrial Gas Companies:Vertically integrated distributors operating captive transport fleets to control supply chain reliability. Linde AG and Air Liquide maintain dedicated procurement programs specifying carbon fiber composite vessels for liquid hydrogen service.
- Energy Sector:LNG bunkering operators and hydrogen refueling station developers sourcing medium-capacity vessels for port-side and corridor-based fuel delivery. California and South Korea represent concentrated demand nodes.
- Research Institutions:Low-volume purchasers requiring small-capacity vessels for laboratory liquid helium and liquid nitrogen supply.
- Food and Beverage Companies:Cryogenic carbon dioxide and nitrogen users deploying leased container systems for processing and packaging applications.
Industrial Gas Companies command the dominant share of vessel orders. Energy Sector procurement is climbing fastest as hydrogen networks expand.
Capacity:
Vessel size selection trades off delivery frequency against infrastructure compatibility, with regional hydrogen stations imposing strict storage volume constraints that favor mid-range configurations.
- Medium (11-50m³):Configurations optimized for regional hydrogen refueling networks requiring frequent, moderate-volume deliveries. Germany's highway-accessible H2 corridors and California's station clusters specify this range to match on-site storage limitations.
- Large (51-100m³):Bulk terminal transfer vessels serving industrial gas production facilities and maritime LNG bunkering operations. China's coastal LNG infrastructure and Rotterdam's port fueling network deploy these for high-throughput delivery.
- Small (1-10m³):Compact units for laboratory supply and specialized research applications with limited on-site storage.
- Extra Large (100m³+):Dedicated systems for liquefaction plant-to-terminal bulk movement with restricted road access permits.
Large capacity vessels handle the greatest cargo volume. Medium capacity configurations are gaining share fastest as distributed hydrogen infrastructure scales.
Deployment:
Modal selection reflects infrastructure availability, distance economics, and regulatory jurisdiction complexity across surface transport modes.
- Land Transport:Dominant mode encompassing highway tankers and semi-trailers serving continental supply corridors. ECE R110 harmonization is reducing cross-border equipment certification duplication for European routes.
- Onshore:Fixed-site vessel systems for production facility storage and buffer inventory management at liquefaction plants.
- Rail Transport:Cryogenic railcars for bulk liquid hydrogen and LNG movement across extended distances where pipeline infrastructure is absent.
- Offshore:Specialized marine cargo systems for platform supply and coastal bunkering operations subject to International Maritime Organization safety protocols.
Land Transport carries the predominant equipment base. Rail Transport is expanding most quickly as hydrogen production clusters seek distance-efficient delivery options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor concentrates liquid hydrogen refueling infrastructure investment, with fleet procurement timelines accelerating vessel demand across European cross-border routes.
United States
California's hydrogen highway corridors and Texas LNG export clusters drive medium-capacity vessel orders. DOT regulations mandate periodic pressure vessel recertification and crashworthiness testing. Gulf Coast fabricators in Houston and Louisiana anchor production capacity for interstate distribution fleets.
Germany
ECE R110 certification harmonization enables cross-border equipment standardization for hydrogen refueling networks. The EU Green Deal tightens materials traceability requirements for pressure equipment. Industrial gas distributors in the Ruhr and Bavaria specify carbon fiber composite vessels for captive fleet expansion.
China
GB standards govern pressure vessel construction and materials traceability for domestic transport fleets. Coastal LNG infrastructure in Guangdong and Zhejiang provinces deploys large-capacity vessels for high-throughput terminal transfers. Yangtze River Delta fabricators scale cylindrical tank manufacturing for regional hydrogen hub development.
Japan
METI hydrogen roadmaps catalyze liquid hydrogen import terminal investments in Kobe and Yokohama. JIS standards intersect with ECE R110 for equipment serving international supply chains. Kanto region refueling station operators consolidate procurement around medium-capacity configurations matching storage constraints.
South Korea
Highway-accessible hydrogen corridors connecting Seoul to Busan require dedicated cryogenic road transport capacity. MFDS regulations align with international pressure equipment standards for cross-border fleet compatibility. Ulsan industrial complex anchors liquid hydrogen production scaling vessel deployment timelines.
Cryogenic Liquid Transport Vehicle Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and manufacturing scale, producing a tiered structure where ECE R110-compliant fabricators command premium positioning in European hydrogen corridors. The vendor base separates into captive fleet operators, independent tank OEMs, and industrial gas integrators. Strategic moves concentrate on filament winding technology licensing and backward integration into carbon fiber supply.
Among North American equipment specialists, Chart Industries exemplifies vacuum insulation expertise applied to liquid hydrogen service, while CIMC Enric anchors Chinese-scale cylindrical tank fabrication for Asia-Pacific infrastructure buildout. Linde AG occupies a position as captive fleet operator integrating production with logistics control across European corridors.
| Leading Market Players |
|---|
| Cryolor |
| CIMC Enric |
| Chart Industries |
| Cryogenmash |
| Zhangjiagang Furui Special Equipment |
| Linde AG |
| Wessington Cryogenics |
| FIBA Technologies |
| Air Liquide |
| Others |
Supply Flow & Price Mechanics
Backward integration into carbon fiber filament winding anchors pricing power for composite-capable fabricators serving European hydrogen corridors, while outsourced aluminum tank assembly faces margin compression from nickel volatility and certified welder scarcity.
Pricing Analysis
Input-cost pass-through from stainless steel and carbon fiber resin systems shapes contract structures across vessel tiers. Three-tier pricing structure across ECE R110-certified premium, ADR-compliant standard, and domestic-only economy levels reflects certification burden and materials traceability depth. Pricing pressure stems from automated filament winding scale-up lowering composite tank unit costs. Third-party logistics operators exhibit highest price sensitivity due to asset-light fleet financing constraints.
Supply Chain Analysis
Domestic-content mandates in China's GB standards and India's National Hydrogen Mission are reshaping sourcing patterns toward Yangtze River Delta and Gujarat-based fabricators. Vacuum-insulated vessel production draws from Japanese carbon fiber prepreg, German stainless steel coil, and Chinese cylindrical tank forming equipment. Single-source vulnerability concentrates in certified cryogenic welder training pipelines failing to match fleet expansion timelines. Distribution runs through captive industrial gas fleets and independent tank OEMs serving third-party logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as hydrogen infrastructure deployment creates durable vessel replacement cycles and certification barriers protect incumbent positioning.
For Market Incumbents: Cement composite manufacturing scale through automated filament winding licensing to lock in European hydrogen corridor contracts. ECE R110 type-approval timelines extending product launches by 8-14 months protect certified fabricators from fast-follower entry. Capacity addition in Germany's Ruhr and China's Yangtze River Delta reinforces regional supply positioning against emerging Asian competitors. For New Entrants and Emerging Players: ECE R110 harmonization in Europe opens a window for mid-capacity vessel specialization targeting regional hydrogen refueling networks. India's National Hydrogen Mission in Gujarat and Tamil Nadu represents the most penetrable geography ahead of dedicated transport infrastructure buildout. Containerized swap-body leasing models offer a go-to-market angle separating asset ownership from logistics operation for independent transport operators. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification burden screens out smaller tank builders unable to sustain ECE R110 and national ADR validation cycles. Long-term viability favors fabricators with captive carbon fiber supply and in-house vacuum insulation expertise. Watch filament winding technology licensing velocity as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Scale-Up | Automated filament winding lowers unit costs for carbon fiber cryogenic vessels serving German hydrogen corridors. |
| ECE R110 Certification Investment | Type-approval for hydrogen components enables cross-border equipment standardization across France, Germany, and Benelux routes. |
| Backward Integration into Carbon Fiber | In-house prepreg supply secures margin control and materials traceability compliance under EU Green Deal requirements. |
| Regional Capacity Expansion | Manufacturing footprint in Yangtze River Delta and Ruhr corridor reduces logistics cost and delivery lead times. |
| Modular Leasing Model Pilot | Containerized swap-body systems separate asset ownership from operation, opening fleet financing for independent operators. |
Methodological Framework
Multiple input streams — fleet procurement directors at industrial gas majors, vacuum insulation engineering leads, and regulatory compliance officers — were reconciled against secondary validation from ECE R110 filing databases, ADR provision updates, and national hydrogen strategy documents. Primary interviews with cryogenic vessel procurement managers, aftermarket service heads, and carbon fiber composite R&D directors informed demand-side assumptions. Customs records for stainless steel coil and carbon fiber prepreg trade flows, combined with SEC filings from listed equipment specialists, anchored supply-side calibration. Bottom-up vessel deployment tracking and top-down infrastructure investment forecasts were triangulated for segment-level sizing.
Historical capacity deployment patterns were cross-referenced against expert panel input on fleet replacement timelines and certification backlog durations. Segmentation modeling covered vehicle type, capacity tier, end-user vertical, and regional regulatory cluster throughout the forecast period. CAGRs were derived from infrastructure investment velocity and vessel-to-station ratio assumptions specific to liquid hydrogen and LNG distribution economics. Filament winding automation adoption curves and certified welder pipeline constraints informed manufacturing capacity expansion boundaries.
Revisions become necessary when hydrogen refueling station deployment timelines shift, ECE R110 certification requirements expand to additional component categories, or carbon fiber resin system supply experiences disruption. Forecasts reflect documented assumptions on infrastructure investment pacing and regulatory harmonization progress. A small set of named triggers — including national hydrogen mission funding allocations and composite manufacturing equipment lead times — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Canada Refrigerated Vehicles Market