
 Middle East Vacuum Truck Market | 2026-2036
Middle East Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Vacuum Truck Market Analytics
Preventive maintenance contracts and telemetry-enabled fleet management is broadening what operators sell beyond the vehicle itself. KOKS Group BV leverages its European engineering heritage to anchor premium positioning across Gulf municipal tenders. Federal Signal Corporation sustains competitive presence through specialized industrial vacuum configurations suited to refinery turnaround cycles. Cappellotto Spa differentiates via deep product specialization in high-capacity liquid vacuum systems for petrochemical clients.
Vacuum trucks in the Middle East are mobile suction vehicles employing high-capacity blowers, debris tanks typically ranging from 3,000 to 15,000 liters, and water jetting systems for excavation and material recovery; hydrovac units deploy pressurized water to liquefy soil while simultaneously extracting slurry through vacuum suction, enabling non-destructive digging around buried utilities. Hydrovac configurations lead product-type demand as Gulf utility operators replace mechanical excavation methods to reduce fiber-optic and pipeline strike incidents. Tank cleaning applications command premium pricing margins due to confined-space certification requirements and specialized hazmat handling protocols. Small and medium-size units dominate municipal fleet procurement while extra-large capacity trucks concentrate in upstream oilfield services.
Saudi Standards, Metrology and Quality Organization (SASO) mandates vacuum truck emissions compliance aligned with Gulf Cooperation Council technical regulations, compelling fleet upgrades and cleaner engine adoption across Saudi Arabia and neighboring GCC states. The UAE's Ministry of Climate Change and Environment enforces waste transport vehicle licensing that shapes product specification for sludge removal contractors operating in Dubai and Abu Dhabi. Stakeholders must monitor how municipal privatization timelines and hydrocarbon sector capital discipline reshape fleet replacement cycles and service contract structures.
Market Dynamics
Municipal privatization across Gulf Cooperation Council states is compressing fleet replacement cycles while tightening performance-based contract terms for vacuum truck operators. SASO emissions mandates and telemetry integration requirements are forcing capital-intensive upgrades across Saudi contractor fleets.
Growth Catalysts
- Hydrovac Technology:UAE utility operators are replacing mechanical excavation with pressurized water liquefaction systems to reduce fiber-optic strike incidents along Dubai-Abu Dhabi infrastructure corridors.
- SASO Technical Regulations:Saudi Arabia's tightening safety and emissions certification is compelling fleet-wide engine upgrades and cleaner blower system adoption across municipal procurement.
- Stormwater Management:Qatar's coastal infrastructure investments are expanding vacuum truck deployment for flood prevention and drainage network maintenance ahead of seasonal peak demand.
Market Restraints
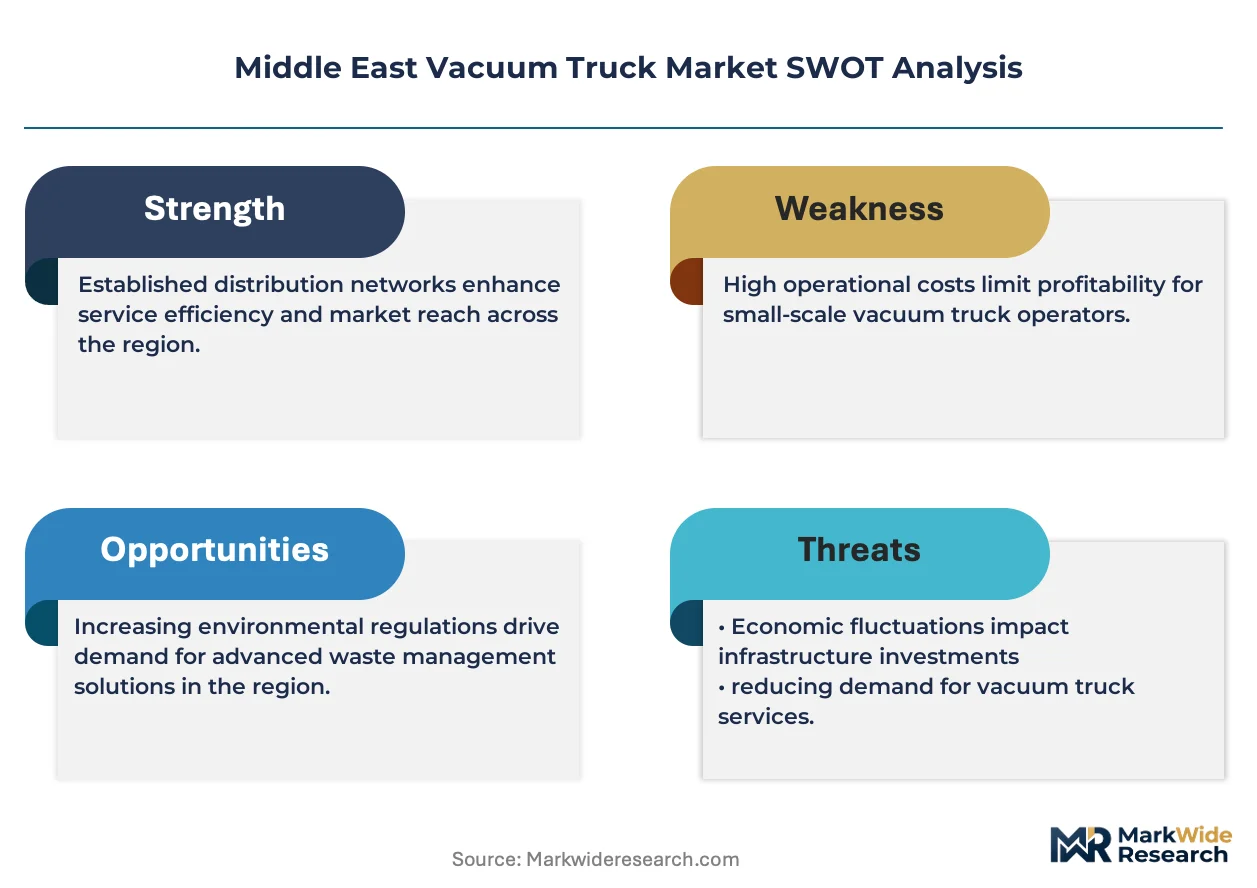
- Specialized Steel Input Volatility:Debris tank fabrication depends on corrosion-resistant alloy plate subject to Gulf import tariff fluctuations and regional mill capacity constraints.
- European Component Concentration:High-capacity blower systems and vacuum pumps concentrate among German and Dutch specialist manufacturers, exposing fleets to euro-denominated cost volatility.
- Hydrocarbon Capital Discipline:Upstream oilfield services demand for extra-large capacity trucks faces replacement deferrals as national oil companies prioritize upstream spending restraint.
Strategic Opportunities
- Oman Municipal Modernization:Underpenetrated sewer network maintenance contracts in Muscat and Salalah present first-mover positioning for telemetry-enabled fleet operators.
- Tank Cleaning Premium Services:Confined-space certification requirements for petrochemical hazmat handling command pricing premiums above standard sludge removal rates.
- Telematics Convergence:Integration of GPS fleet tracking with predictive maintenance algorithms is creating subscription revenue streams beyond equipment sale margins.
Industry Challenges
- Certified Operator Scarcity:Confined-space entry and hazmat handling credentials require specialized training pipelines that Gulf technical institutes have not yet scaled to fleet expansion timelines.
- Legacy Fleet Integration:Retrofitting existing vacuum trucks with SASO-compliant emissions controls and telemetry hardware creates downtime conflicts with contracted service obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Vacuum Truck Market |
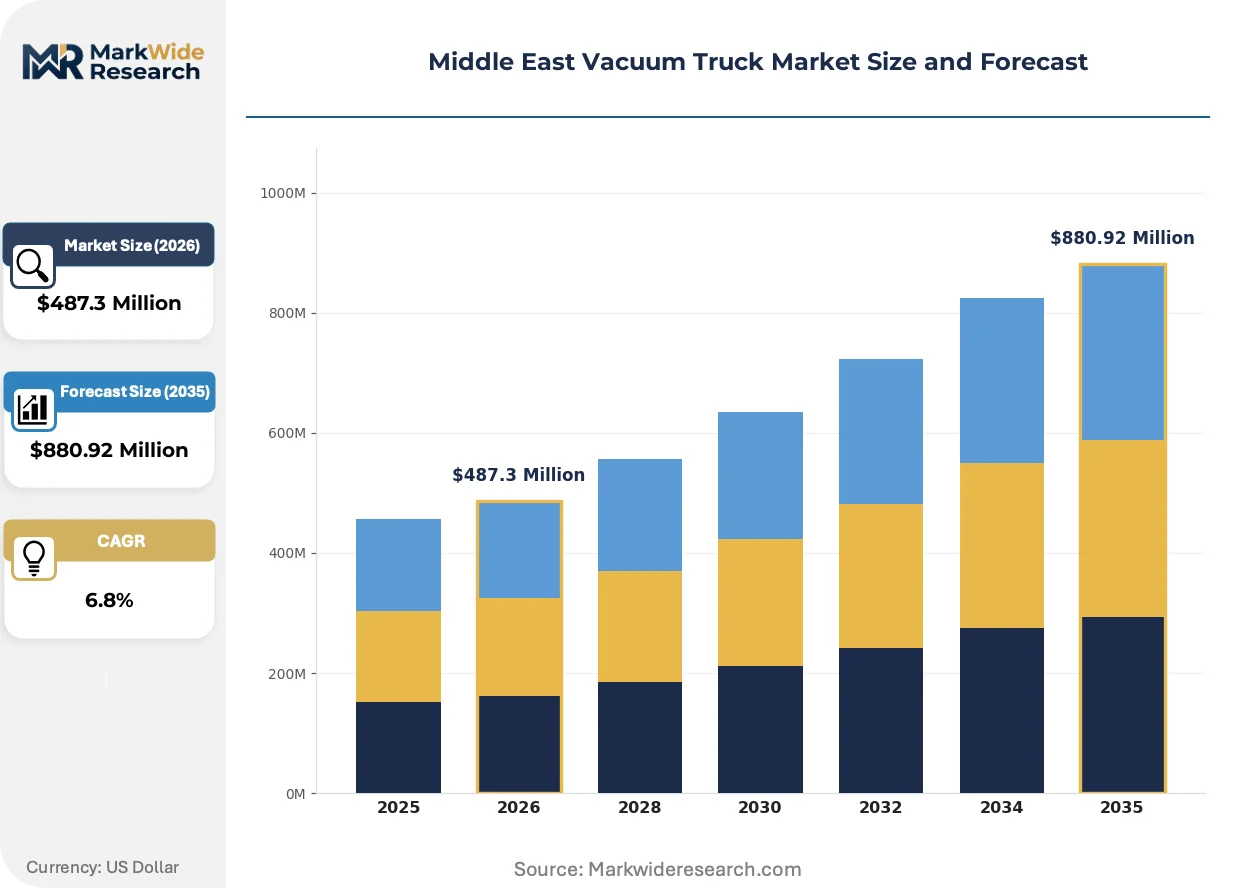
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrovac, Industrial Vacuum, Combination Vacuum, Liquid Vacuum End User: Construction, Oil & Gas, Waste Management, Municipal Services Application: Drainage, Sludge Removal, Excavation, Tank Cleaning Size: Small, Medium, Large, Extra Large |
| Companies Covered | Kanematsu Engineering Co., Ltd., KOKS Group BV, Cappellotto Spa, FULONGMA Group Co., Ltd., GapVax, Inc., Alamo Group Inc. (Rivard), Federal Signal Corporation, Keith Huber Corporation, Vac-Con, Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Vacuum Truck Market Evolving Landscape
Telemetry-enabled predictive maintenance is transforming how Gulf municipal fleets manage asset utilization and contract compliance. Three converging developments are restructuring competitive positioning across equipment supply and service provision.
Telematics integration is decentralizing fleet management authority from centralized maintenance depots toward real-time operator decision-making. Dubai municipality contractors are deploying sensor-equipped hydrovac units that transmit tank levels, engine diagnostics, and location data to dispatch centers. This distributed intelligence model is compressing response times for emergency sewer overflows while enabling dynamic route optimization that reduces fuel consumption per service call.
SASO's alignment with Gulf Cooperation Council technical regulations is tightening emissions compliance timelines for vacuum truck engines and blower systems. The regulatory framework mandates cleaner combustion standards that disqualify older fleet assets from municipal tender eligibility. Saudi contractors are responding with accelerated replacement schedules and retrofitted exhaust treatment systems to maintain procurement qualification status.
Service contract unbundling is separating equipment ownership from operational delivery across UAE municipal frameworks. Dubai and Abu Dhabi utilities are shifting from capital purchase models toward long-term lease arrangements with embedded maintenance obligations. This financial restructuring concentrates fleet ownership among specialized lessors while transferring operational risk to contractor consortia competing on performance metrics rather than asset depreciation schedules.
Middle East Vacuum Truck Market Segmentation
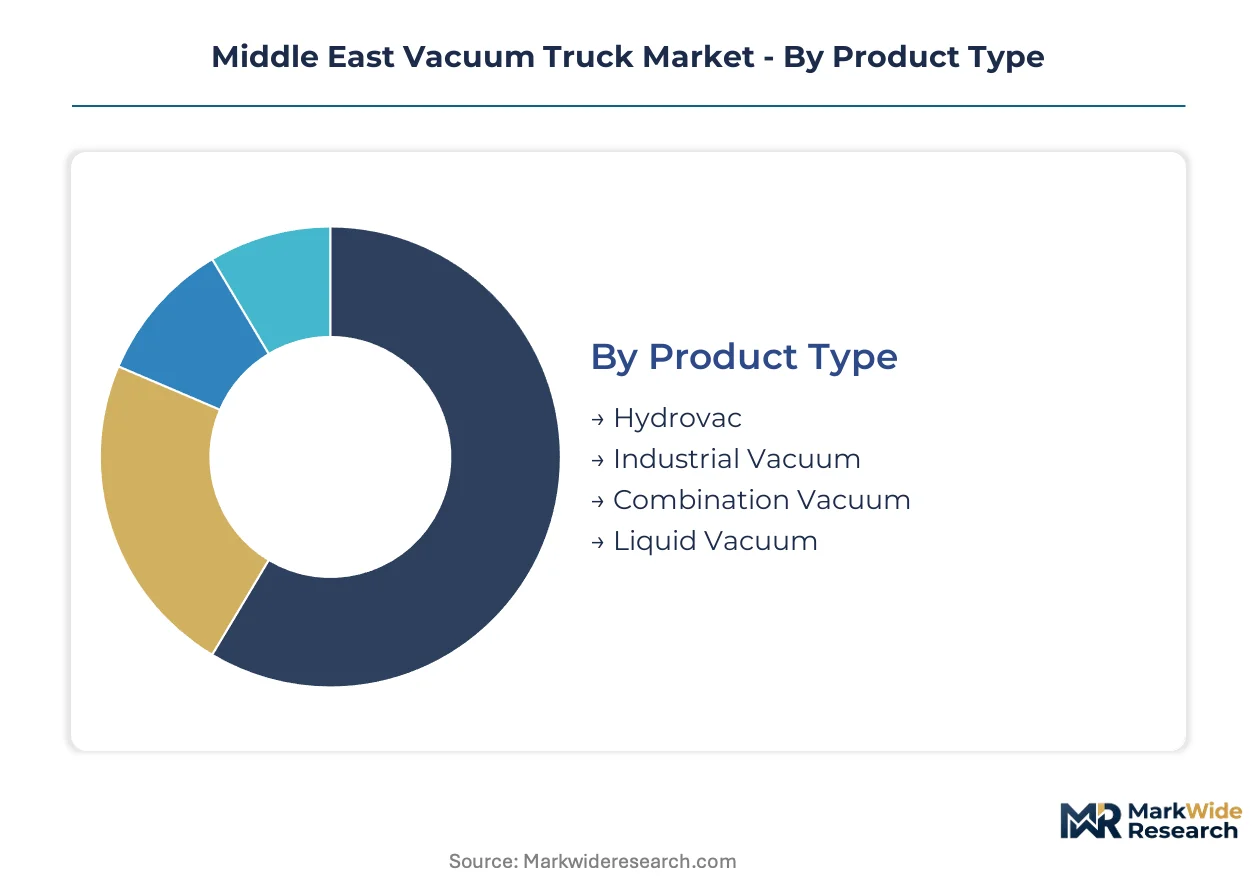
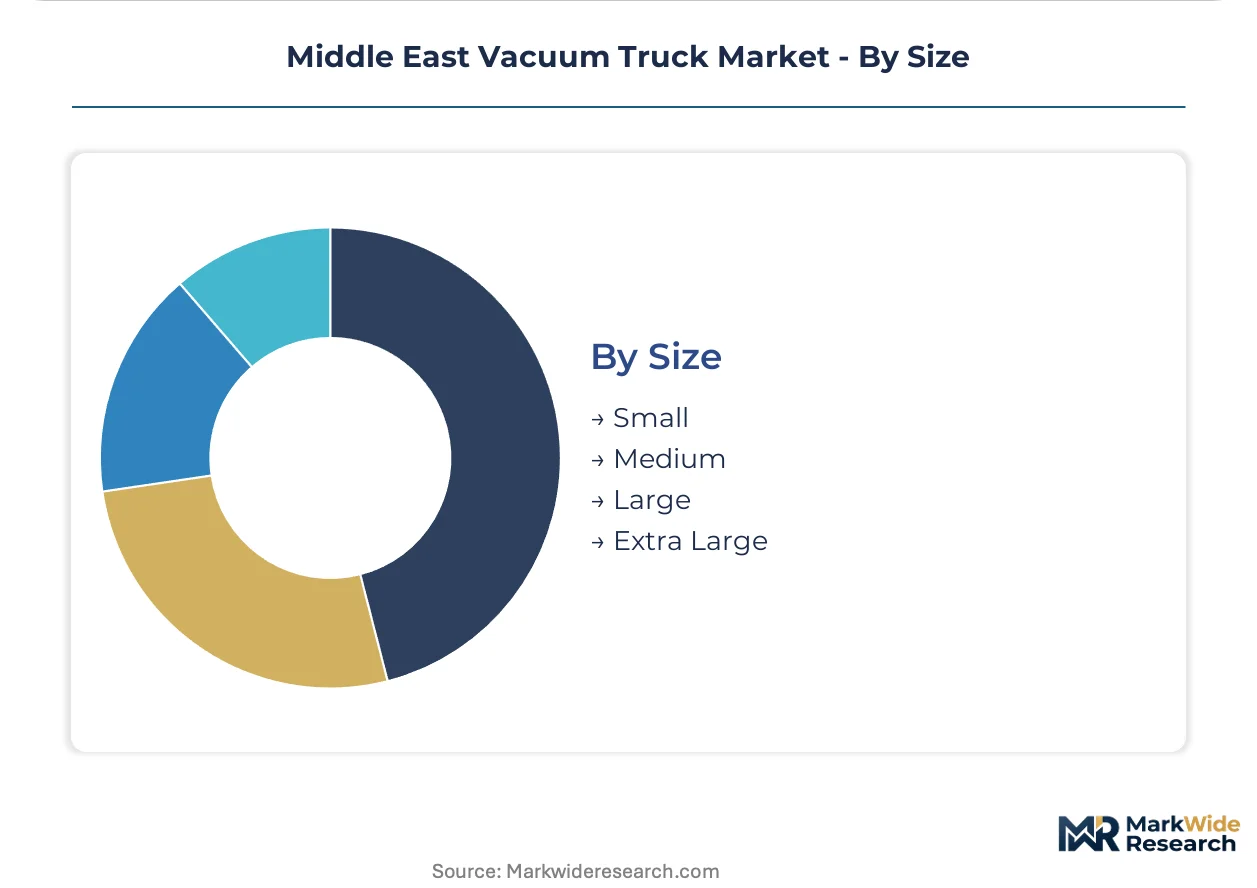
Vacuum truck procurement patterns across the Middle East diverge sharply between standardized municipal fleet purchases and highly customized industrial configurations. Understanding these segment boundaries reveals where margin concentration aligns with technical complexity versus where volume scale dominates competitive dynamics.
Product Type:
Customization intensity spans from standardized hydrovac platforms to engineered industrial vacuum systems requiring site-specific blower configurations and corrosion-resistant tank alloys.
- Hydrovac:Pressurized water liquefaction systems deploy simultaneous water jetting and vacuum suction for non-destructive excavation around buried utilities. Demand clusters along the Dubai-Abu Dhabi construction corridor where fiber-optic strike avoidance drives replacement of mechanical excavation methods.
- Industrial Vacuum:High-capacity blower systems engineered for refinery turnaround cycles and petrochemical material recovery command premium pricing through specialized configurations. Saudi Aramco contractor fleets specify these units for upstream production facility maintenance where downtime costs dwarf equipment procurement.
- Combination Vacuum:Dual-purpose platforms merge liquid and dry debris handling capabilities for municipal operators seeking fleet flexibility across stormwater and sewer maintenance contracts.
- Liquid Vacuum:Purpose-built systems for sludge transport and hazardous liquid recovery concentrate in UAE waste management contractor fleets serving Dubai Municipality tenders.
Most installed capacity flows through Hydrovac configurations. Expansion is steepest in Industrial Vacuum as petrochemical operators prioritize strike-prevention protocols.
End User:
Customer sophistication tiers separate price-sensitive municipal procurement from performance-guaranteed industrial contracting where uptime penalties reshape total cost of ownership calculations.
- Construction:Hydrovac demand concentrates in UAE infrastructure development where pressurized excavation replaces mechanical digging around dense utility corridors. Contractors face liquidated damages for pipeline strikes that accelerate technology substitution.
- Oil & Gas:Upstream operators in Saudi Arabia and Kuwait deploy extra-large capacity trucks for production facility tank cleaning and flare system maintenance. Capital discipline at national oil companies is deferring fleet replacement cycles despite aging asset bases.
- Waste Management:Sludge transport contractors across Qatar and Bahrain operate under Ministry licensing regimes that specify tank integrity standards and telemetry tracking for environmental compliance.
- Municipal Services:Sewer network maintenance fleets in Saudi Arabia, the UAE, and Qatar are expanding procurement for preventive maintenance contracts with performance-based service level agreements.
Procurement volume concentrates in Municipal Services. Margin expansion is most pronounced in Oil & Gas where confined-space certification requirements create contractor scarcity premiums.
Application:
Application complexity correlates directly with pricing power, separating commodity sludge transport from hazardous tank cleaning where regulatory compliance creates defensible service moats.
- Drainage:Stormwater network maintenance and flood prevention deployment concentrates in Qatar's coastal infrastructure investments ahead of seasonal peak demand periods.
- Sludge Removal:Standardized municipal sewer cleaning operations represent high-volume, price-competitive contracting where telemetry-enabled fleet efficiency separates profitable operators from marginal competitors.
- Tank Cleaning:Confined-space entry protocols and hazmat handling certifications for petrochemical tank maintenance command pricing premiums substantially above standard sludge removal rates. Saudi and UAE refineries specify contractors with SASO-compliant safety credentials.
- Excavation:Hydrovac-based utility exposure work is displacing mechanical excavation across Gulf municipal infrastructure projects where buried fiber-optic density raises strike-risk liabilities.
Service revenue concentrates in Sludge Removal. Pricing power is strongest in Tank Cleaning where certification scarcity limits qualified contractor supply.
Size:
Fleet scale economics separate compact urban maneuverability from oilfield capacity requirements, with municipal procurement optimizing for street network constraints versus upstream operators maximizing payload per dispatch.
- Small:Compact units with sub-5,000 liter tanks navigate dense urban sewer networks in Dubai and Riyadh where street width and turning radius constrain larger vehicle deployment.
- Medium:Versatile configurations dominate municipal fleet procurement across Saudi Arabia, balancing tank capacity with residential street accessibility for routine maintenance contracts.
- Large:Extended-range platforms serve intercity sludge transport and regional waste consolidation contracts where payload efficiency outweighs maneuverability constraints.
- Extra Large:High-capacity trucks exceeding 12,000 liters concentrate in Saudi and Kuwait upstream oilfield services where remote site access justifies dedicated heavy-haul logistics.
Unit volume concentrates in Medium configurations. Revenue per vehicle is highest in Extra Large platforms serving hydrocarbon production maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage across Gulf Cooperation Council states is intensifying as SASO emissions mandates in Saudi Arabia widen compliance cost differentials against UAE and Qatar procurement frameworks. Fleet operators are relocating service contracts toward jurisdictions with phased regulatory timelines.
Saudi Arabia
Riyadh municipal utilities are accelerating hydrovac procurement for sewer network modernization under Vision 2030 infrastructure targets. SASO technical regulations now mandate telemetry integration and cleaner engine standards for all new fleet acquisitions. The Eastern Province concentrates upstream oilfield vacuum truck deployment for Aramco contractor maintenance cycles.
United Arab Emirates
Dubai Municipality contractors dominate regional hydrovac demand along the Dubai-Abu Dhabi construction corridor where fiber-optic density drives strike-prevention protocols. MOCCAE waste transport licensing shapes sludge removal contractor specifications across both emirates. Abu Dhabi National Oil Company maintenance frameworks command premium pricing for confined-space tank cleaning services.
Qatar
Coastal infrastructure investments ahead of seasonal storm peaks are expanding drainage network maintenance fleets in Doha and Al Wakrah. The Public Works Authority Ashghal specifies performance-based service contracts with embedded telemetry requirements. Lusail City development corridors concentrate utility excavation work driving hydrovac substitution of mechanical digging methods.
Kuwait
Kuwait Oil Company upstream maintenance schedules sustain demand for extra-large capacity vacuum trucks despite broader hydrocarbon capital discipline. The Environment Public Authority is tightening waste transport vehicle emissions standards affecting contractor fleet renewal timelines. Al Ahmadi refinery complex maintenance contracts anchor industrial vacuum service provider presence.
Oman
Underpenetrated sewer network maintenance contracts in Muscat and Salalah present positioning opportunities for telemetry-enabled fleet operators. The Ministry of Regional Municipalities and Water Resources is privatizing municipal service delivery under new public-private partnership frameworks. Sohar Industrial Port petrochemical cluster demand for tank cleaning services remains underserved by certified contractors.
Middle East Vacuum Truck Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European-engineered premium configurations dominating municipal tenders while Asian fabricators capture standardized fleet procurement. The vendor base concentrates among three tiers: heritage European specialists with Gulf tender anchoring positions, diversified industrial equipment conglomerates with refinery service relationships, and emerging Asian manufacturers competing on delivery timelines. Consolidation pressure is mounting as telemetry integration requirements raise R&D capitalization thresholds. Strategic moves center on SASO certification pre-qualification partnerships and service contract unbundling toward long-term lease structures.
Within the European heritage tier, KOKS Group BV and Cappellotto Spa exemplify premium positioning strategies built on specialized blower engineering and petrochemical application expertise. Federal Signal Corporation occupies a distinct position among diversified industrial equipment suppliers with refinery turnaround cycle service relationships. These three anchors demonstrate how competitive separation derives from certification depth and sector-specific application knowledge rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Kanematsu Engineering Co., Ltd. |
| KOKS Group BV |
| Cappellotto Spa |
| FULONGMA Group Co., Ltd. |
| GapVax, Inc. |
| Alamo Group Inc. (Rivard) |
| Federal Signal Corporation |
| Keith Huber Corporation |
| Vac-Con, Inc. |
| Others |
Value Network & Pricing Analysis
Captive production of corrosion-resistant alloy tanks by European heritage manufacturers anchors premium positioning across Gulf municipal tenders while insulating these suppliers from commodity steel volatility. This vertical control over debris tank fabrication enables sustained margin capture despite pressure from Asian fabricators competing on delivery timelines for standardized fleet procurement.
Pricing Analysis
Distributor margins concentrate in the aftermarket service layer where telemetry-enabled fleet management contracts generate recurring revenue streams beyond equipment sale margins. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified European configurations from Asian-fabricated municipal fleet units. Pricing pressure stems from hydrocarbon capital discipline deferring upstream oilfield fleet replacement cycles. Municipal procurement teams exhibit highest price sensitivity while petrochemical operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Freight costs from German and Dutch specialist manufacturers amplify landed costs for high-capacity blower systems and vacuum pumps deployed across Saudi and UAE contractor fleets. Component sourcing draws from Germany, the Netherlands, and South Korea for precision-engineered blower assemblies, with debris tank fabrication resting on corrosion-resistant alloy plate from European and Japanese mills. Single-source vulnerability concentrates in euro-denominated vacuum pump procurement. Distribution runs through specialized industrial equipment distributors with refinery service relationships and direct municipal tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO emissions compliance timelines in Saudi Arabia run ahead of UAE and Qatar regulatory phases, creating procurement cost arbitrage for fleet operators able to relocate service contracts toward jurisdictions with deferred upgrade obligations.
For Market Incumbents: To counter Asian fabricator price competition in standardized municipal procurement, deepen captive supply of corrosion-resistant tank alloys and accelerate telemetry platform integration to capture recurring service contract revenue. SASO certification pre-qualification partnerships anchor tender eligibility against emerging competitors lacking regulatory track records. For New Entrants and Emerging Players: Begin with underpenetrated sewer network maintenance contracts in Oman's Muscat and Salalah corridors where telemetry-enabled fleet operators face limited incumbent presence. Sohar Industrial Port petrochemical tank cleaning services remain underserved by certified contractors, offering a go-to-market angle through confined-space certification investment. For Investors and Strategic Acquirers: Roll-up economics work for regional service contractors with embedded municipal relationships because privatization timelines compress fleet replacement cycles and concentrate operational risk among specialized lessors. Target mid-scale operators with SASO-compliant fleets and existing telemetry infrastructure as acquisition candidates. Monitor hydrocarbon capital discipline relaxation at Saudi Aramco and Kuwait Oil Company as the inflection signal for upstream oilfield services demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Enables subscription revenue streams beyond equipment sale margins for municipal fleet operators. |
| SASO Certification Pre-qualification | Secures tender eligibility for Saudi municipal procurement under tightening emissions mandates. |
| Backward Integration into Tank Fabrication | Insulates margin position from corrosion-resistant alloy plate import tariff volatility. |
| Long-term Lease Structure Transition | Aligns with Dubai and Abu Dhabi municipal frameworks separating ownership from operational delivery. |
| Confined-space Certification Investment | Captures pricing premiums in petrochemical tank cleaning where qualified contractor scarcity limits supply. |
Research Methodology
Multiple input streams — primary interviews with municipal fleet managers, aftermarket service directors, and petrochemical maintenance contractors; secondary validation through customs trade data, SEC filings of listed equipment manufacturers, and Gulf municipal tender databases; plus technical documentation from SASO and MOCCAE regulatory filings — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, end user, application, and size segmentation dimensions. CAGRs were derived from installed base replacement cycles, fleet expansion timelines, and regulatory compliance phase-ins. Industry-specific forecast inputs incorporated hydrocarbon capital discipline indicators and municipal privatization contract award patterns.
Several conditions sit outside the modeled scope, including geopolitical disruptions to steel alloy supply routes and unannounced regulatory accelerations beyond published SASO implementation timelines. Forecasts reflect documented assumptions about fleet replacement elasticity and contractor consolidation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Used Truck Market