
 North America Van Market | 2026-2036
North America Van Market Size, Share, and Industry Trends Forecast 2026-2036
North America Van Market Analytics
The US EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is recalibrating fleet procurement priorities across North America. Ford Motor Company leverages its commercial vehicle heritage to sustain dominance in full-size cargo configurations. Stellantis anchors its position through multi-brand distribution spanning Ram and Chrysler minivan channels. General Motors Company competes aggressively in the electric van segment through its BrightDrop subsidiary's manufacturing scale.
A van denotes a light-to-medium-duty enclosed-body vehicle engineered on unibody or body-on-frame architecture, with payload capacities ranging from 1,500 to 4,500 pounds and wheelbases spanning 118 to 178 inches, designed primarily for commercial freight transport, passenger shuttle service, or specialized upfit applications. Cargo van configurations lead unit volume across the Vehicle Type dimension, while electric powertrains within the Fuel Type category represent the fastest-growing margin pool as fleet operators amortize total cost of ownership advantages. The Luxury Vans sub-segment under Market Segment commands premium pricing through bespoke interior upfitting, whereas Economy Vans dominate absolute fleet procurement volumes for delivery and service contractors.
The US EPA, NHTSA, and California Air Resources Board collectively shape van powertrain compliance through coordinated emissions benchmarks and zero-emission vehicle mandates that restrict market access for non-conforming models. Canada's federal carbon pricing framework and provincial clean fuel standards add parallel compliance layers for cross-border manufacturers. Stakeholders must monitor how battery supply constraints and charging infrastructure gaps interact with regulatory deadlines to determine optimal powertrain portfolio timing.
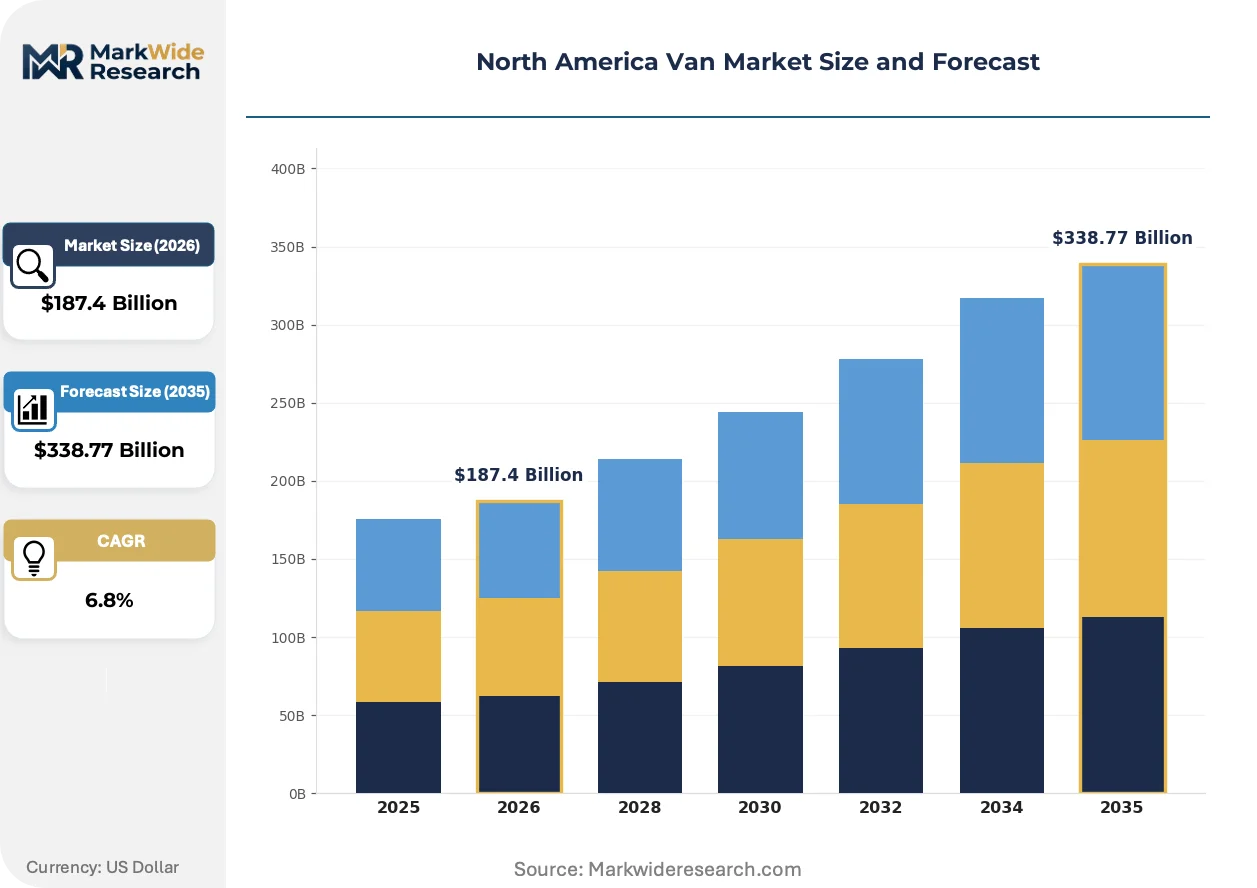
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing powertrain transition timelines across North American van fleets, forcing manufacturers to accelerate electrified platform deployment while managing battery supply constraints and charging infrastructure gaps.
Growth Catalysts
- Last-mile delivery fleet expansion:E-commerce fulfillment networks across the US Sun Belt corridor are scaling van procurement to serve population migration toward logistics hubs in Texas, Arizona, and Florida.
- California Air Resources Board zero-emission mandates:CARB's Advanced Clean Trucks regulation is compelling fleet operators to electrify medium-duty van segments ahead of federal compliance deadlines.
- Battery cost curves:Lithium-ion pack economics are improving total cost of ownership calculations for electric cargo configurations versus diesel equivalents in high-utilization duty cycles.
Market Restraints
- Critical mineral supply concentration:Cobalt and lithium processing capacity concentrates in China, creating geopolitical exposure for North American battery supply chains.
- Charging infrastructure gaps:Depot electrification requires utility interconnection timelines that lag fleet procurement schedules in secondary US markets.
- Payload-range tradeoffs:Battery weight penalties reduce available cargo capacity for electric full-size vans versus internal combustion equivalents in refrigerated upfit applications.
Strategic Opportunities
- Canadian provincial clean fuel standards:British Columbia and Quebec incentive stacks create favorable economics for zero-emission van adoption in cross-border fleet operations.
- Autonomous delivery integration:Self-driving middleware is converging with electric van platforms to enable driverless last-mile pilots in controlled urban geofences.
- Mobile service van electrification:Underpenetrated contractor segments in Texas and Florida present white space for purpose-built electric work van configurations with onboard power export.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks face skill gaps in diagnosing and repairing electric powertrain systems, extending vehicle downtime.
- Upfitter certification delays:Third-party body builders require EPA and CARB compliance validation for electric chassis modifications, stretching delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Van Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Van, Cargo Van, Minivan, Camper Van Usage Type: Commercial Use, Family Use, Recreational Use, Delivery Fuel Type: Gasoline, Diesel, Electric, Hybrid Market Segment: Luxury Vans, Economy Vans, Off-road Vans, Converted Vans |
| Companies Covered | Ford Motor Company, General Motors Company, Mercedes-Benz Group AG, Stellantis, Ram Trucking, Chevrolet, Nissan Motor Co., Ltd., Toyota Motor Corporation, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Van Market Evolving Landscape
Powertrain electrification is rewiring competitive advantage across van segments, while regulatory compliance timelines and procurement model evolution reshape how fleets acquire and operate commercial vehicles.
Solid-state battery chemistry is expanding into prototype van platforms, offering energy density improvements that could extend electric range without increasing pack footprint. Fleet operators in California are monitoring pilot programs through the state's clean freight corridor initiatives. This technology is expanding into long-haul capable electric vans previously constrained by lithium-ion limitations.
EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are tightening CO2 emissions trajectories through 2032, with interim targets accelerating powertrain refresh cycles. Manufacturers must certify van platforms across multiple weight classes simultaneously, straining engineering resources. The full-size cargo segment faces the steepest compliance gradient, driving accelerated hybrid and battery-electric product launches.
Fleet-as-a-service contracting is displacing traditional capital acquisition for delivery operators seeking to offload residual value risk and charging infrastructure investment. Third-party mobility providers are bundling vehicles, maintenance, and energy into per-mile or per-stop pricing. This model is gaining traction most visibly among regional parcel carriers in the US Southeast managing seasonal volume volatility.
North America Van Market Segmentation
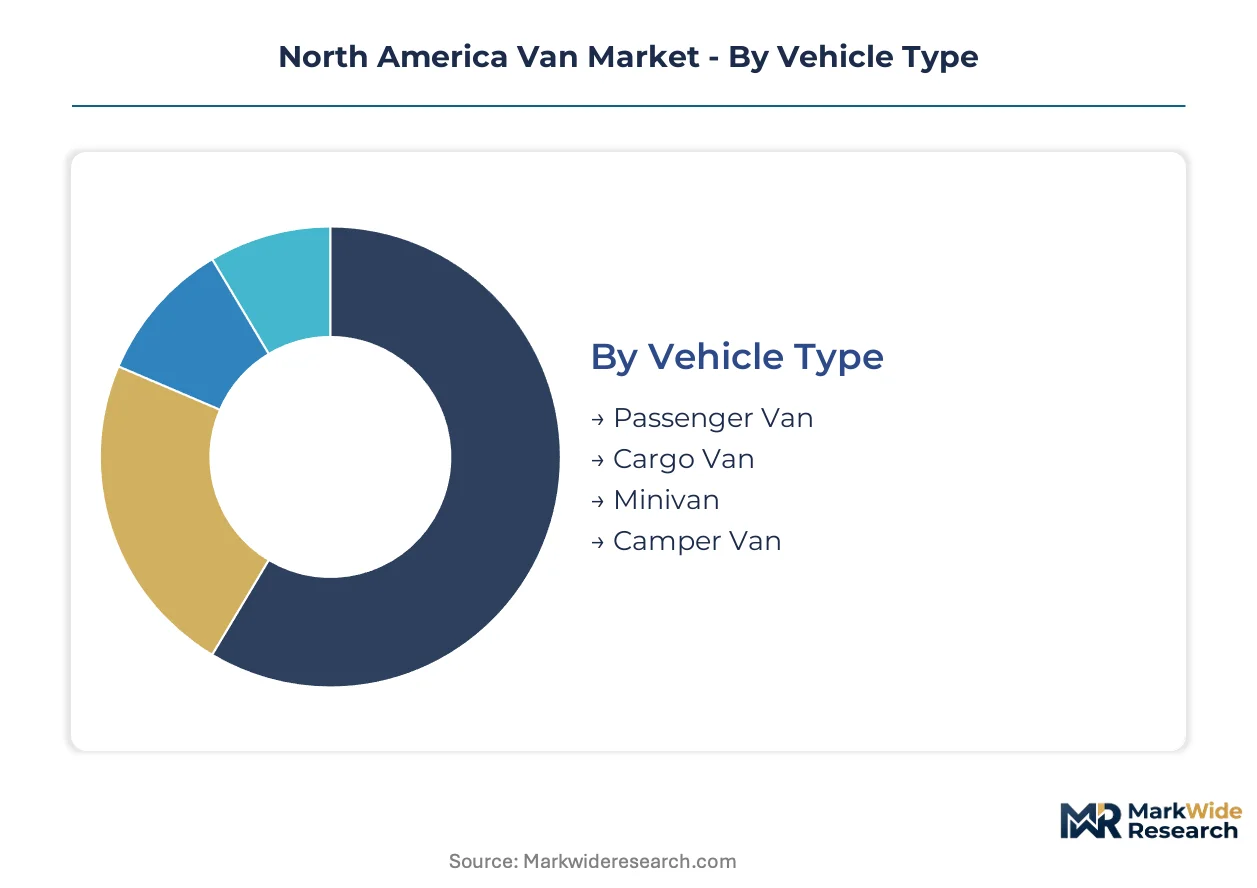
Van procurement patterns across North America diverge sharply by duty cycle intensity and upfit complexity. Fleet operators segment their acquisition strategies around payload requirements, depot charging availability, and total cost of ownership amortization periods.
Vehicle Type:
Replacement cycles vary dramatically by body configuration, with commercial operators retiring cargo platforms faster than passenger or recreational variants due to structural fatigue from continuous loading.
- Cargo Van:Enclosed unibody or body-on-frame architecture optimized for freight transport, with payload ratings spanning 1,500 to 4,500 pounds. Fleet procurement concentrates in the US Sun Belt corridor, where last-mile delivery networks serving Texas, Arizona, and Florida logistics hubs sustain high-volume orders despite electrification transition costs.
- Minivan:Compact unibody design with sliding side doors and three-row seating configurations prioritizing passenger access. Family transportation demand clusters in suburban markets across the US Midwest and Ontario, though unit volumes face compression from crossover SUV substitution.
- Passenger Van:Extended wheelbase configurations accommodating 8-15 occupants for shuttle, transit, and institutional transport. Airport shuttle operators and senior care facilities in California and British Columbia drive procurement.
- Camper Van:Purpose-built or converted recreational platforms with integrated living amenities including sleeping quarters and onboard power systems. Demand surges in Colorado, Utah, and Pacific Northwest outdoor recreation corridors.
Volume placements concentrate in Cargo Van configurations; the faster expansion belongs to Camper Van segments as remote work mobility trends persist.
Usage Type:
Cost tier stratification separates capital-intensive commercial deployments from discretionary family and recreational acquisitions with divergent financing structures.
- Commercial Use:High-utilization fleet applications encompassing service contractors, mobile workshops, and trade-specific upfits. Electric powertrain adoption accelerates fastest here, where total cost of ownership calculations favor battery-electric platforms in urban duty cycles with predictable depot charging.
- Delivery:Dedicated last-mile freight operations with standardized route profiles and high stop frequency. E-commerce fulfillment networks across the US Southeast and Southwest sustain procurement growth, though payload-range tradeoffs constrain refrigerated upfit applications.
- Family Use:Multi-passenger transportation for suburban households prioritizing seating capacity and safety features. Minivan and passenger van configurations dominate, with demand softening in favor of three-row crossover alternatives.
- Recreational Use:Seasonal and weekend mobility for outdoor tourism and adventure travel. Camper van and converted van segments capture this spend, with rental fleet operators in national park gateway cities expanding electric camper pilot programs.
Commercial Use and Delivery segments combine for dominant volume share; Recreational Use climbs fastest as vanlife tourism infrastructure matures.
Fuel Type:
Application maturity separates established internal combustion platforms from emerging electric architectures with divergent infrastructure dependencies.
- Electric:Battery-electric powertrains with zero tailpipe emissions and regenerative braking systems. CARB's Advanced Clean Trucks regulation compels California fleet electrification ahead of federal EPA Phase 3 compliance deadlines, creating concentrated demand in Los Angeles, San Francisco, and San Diego logistics corridors.
- Gasoline:Conventional spark-ignition engines with established service networks and lowest upfront acquisition cost. Family and light commercial segments in Texas, Florida, and Arizona continue gasoline dominance where charging infrastructure gaps persist.
- Diesel:Compression-ignition powertrains with superior torque characteristics for heavy towing and high-mileage operations. Long-haul shuttle operators and rural commercial fleets in the US Mountain West and Canadian Prairie provinces retain diesel preference.
- Hybrid:Combined internal combustion and electric propulsion without plug-in charging dependency. Urban delivery fleets in Seattle, Vancouver, and Portland deploy hybrids as bridging technology during charging infrastructure buildout.
Gasoline retains dominant placement volume; Electric gains share fastest where regulatory mandates and utility incentive stacks align.
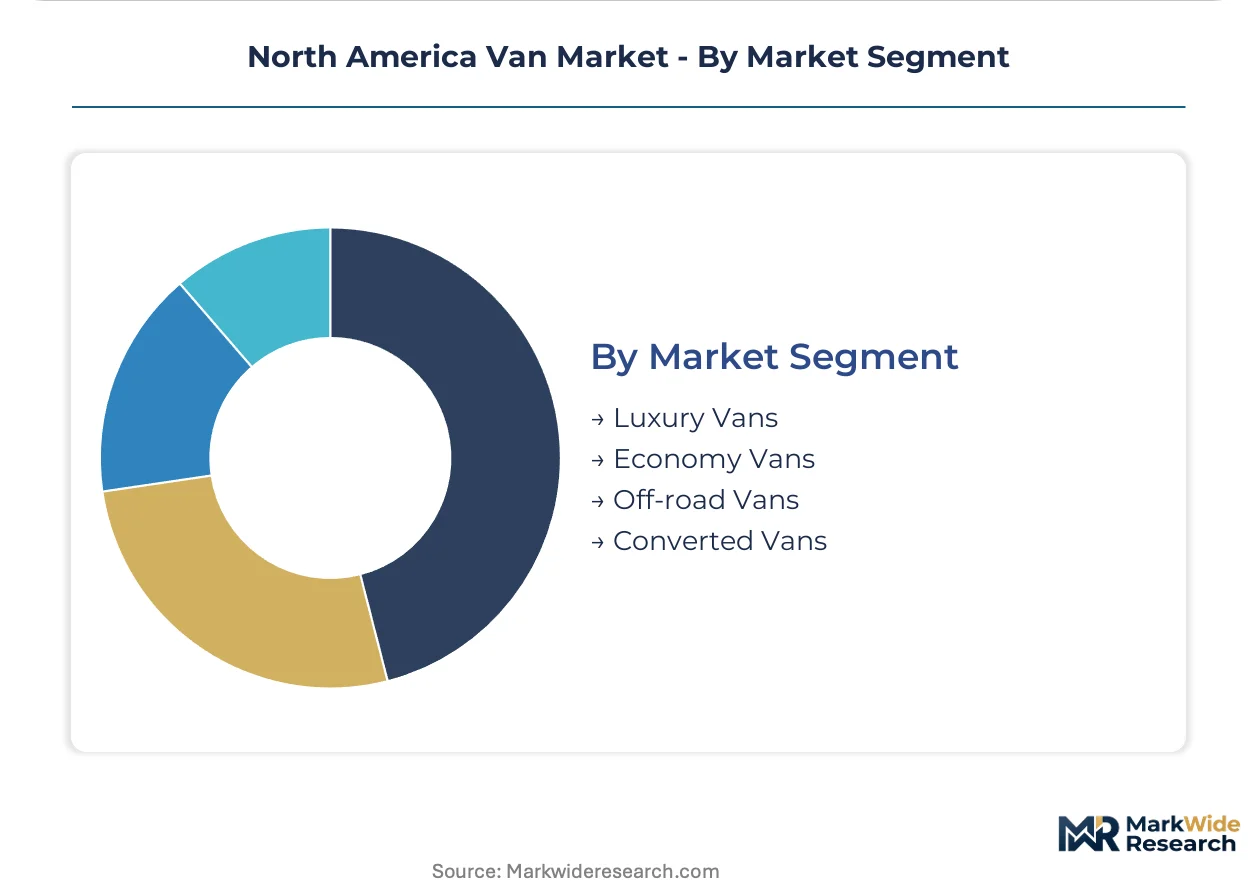
Market Segment:
Margin concentration stratifies across bespoke upfitting versus standardized fleet procurement with divergent pricing power dynamics.
- Economy Vans:Standardized configurations with minimal factory options and third-party upfit compatibility. Delivery contractors and service fleets across the US Sun Belt prioritize these platforms for capital efficiency and rapid replacement cycling.
- Luxury Vans:Premium interiors with bespoke materials, advanced driver assistance systems, and executive seating configurations. Corporate shuttle operators in Manhattan, Toronto, and Los Angeles sustain demand for chauffeured transport.
- Off-road Vans:Elevated suspension, all-terrain tires, and reinforced underbody protection for unpaved access. Adventure tourism operators in Moab, Sedona, and British Columbia backcountry regions drive niche procurement.
- Converted Vans:Aftermarket upfit platforms transformed for mobile living, workspace, or specialized commercial functions. Independent upfitters in Colorado, Oregon, and Quebec supply this segment with custom electrical and plumbing installations.
Economy Vans command absolute volume leadership; Luxury Vans achieve the steepest margin expansion through bespoke upfitting premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of North American van output while Canadian and Mexican production facilities supply cross-border assembly integration. Manufacturing clusters concentrate near Great Lakes automotive corridors and Mexican border states to optimize logistics reach. Regulatory divergence between federal EPA standards and California's CARB mandates creates compliance complexity for multi-market operators.
United States
Last-mile delivery fleets in Texas, Arizona, and Florida are expanding van procurement to serve e-commerce fulfillment networks. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles mandate CO2 reductions through 2032, compressing powertrain transition timelines. Los Angeles and San Francisco logistics corridors concentrate electric van adoption where CARB's Advanced Clean Trucks regulation enforces zero-emission mandates ahead of federal deadlines.
Canada
Cross-border fleet operators prioritize zero-emission configurations to capture British Columbia and Quebec provincial incentive stacks. Federal carbon pricing frameworks and clean fuel standards add parallel compliance layers for manufacturers serving both markets. Toronto and Vancouver metropolitan areas anchor commercial van demand through logistics hub expansion and airport shuttle procurement.
Mexico
Export-oriented assembly plants in Nuevo León and Bajío Region integrate van production into North American supply chains. Mexican manufacturing serves US and Canadian markets through USMCA trade provisions while domestic commercial demand concentrates in Mexico City Metro logistics corridors. The Secretariat of Environment and Natural Resources coordinates emissions benchmarks with EPA harmonization timelines.
North America Van Market Competitive Landscape
The competitive structure tilts toward diversified automotive conglomerates with commercial vehicle heritage. Market concentration remains moderate with three to four integrated manufacturers commanding volume leadership in full-size cargo configurations. Strategic archetypes divide between legacy Detroit-based full-line producers, European premium van specialists, and Asian mass-market entrants. Capacity expansion in Mexican assembly corridors and electric platform partnerships represent dominant competitive moves.
Within the legacy domestic tier, Ford Motor Company and General Motors Company exemplify scale-driven commercial vehicle positioning. Stellantis occupies a distinct multi-brand distribution archetype spanning Ram and Chrysler minivan channels. Mercedes-Benz Group AG represents the premium commercial van specialist segment with European engineering positioning.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Mercedes-Benz Group AG |
| Stellantis |
| Ram Trucking |
| Chevrolet |
| Nissan Motor Co., Ltd. |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Others |
Value Network & Pricing Analysis
Lithium carbonate and cobalt sulfate pricing volatility cascades through North American van manufacturing, compressing margins on economy cargo configurations while premium electric platforms absorb input spikes through longer amortization cycles and fleet-as-a-service contracting structures.
Pricing Analysis
Total cost of ownership calculations anchor pricing power for electric cargo vans in high-utilization delivery fleets. Three-tier pricing structure across premium, standard, and economy levels separates bespoke upfitted luxury shuttles from standardized fleet procurement. Cost compression in the economy tier is intensifying because battery pack economics improve faster than chassis material inflation. Delivery contractors show highest price sensitivity, while executive shuttle operators accept premium positioning for chauffeured configurations.
Supply Chain Analysis
Battery cell supply rests on South Korean and Chinese cathode material producers, with North American pack assembly drawing from Mexican wire harness and Canadian aluminum body panel suppliers. Lithium hydroxide, nickel manganese cobalt cathodes, and high-strength steel stampings constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare earth processing for electric motor magnets. Distribution runs through Detroit-based OEM captive finance arms and third-party fleet lessors serving Sun Belt logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American van manufacturing is becoming a vertical-integration race, with battery supply security and charging infrastructure deployment emerging as the decisive downstream levers separating market leaders from margin-squeezed assemblers.
For Market Incumbents: Lock in long-term offtake agreements with Canadian and Australian lithium developers to reduce Chinese supply chain exposure. Secure depot electrification partnerships with Texas and Florida utilities ahead of EPA Phase 3 compliance deadlines. Battery cell backward integration and captive charging infrastructure deployment represent the critical defensive moves against Stellantis and Ford's platform scale advantages. For New Entrants and Emerging Players: Begin with mobile service van electrification in underpenetrated Texas and Florida contractor segments, where onboard power export features command premium positioning. Target refrigerated last-mile configurations where payload-range tradeoffs have slowed incumbent electric adoption. A purpose-built electric work van with V2G capability offers the most penetrable white-space entry angle. For Investors and Strategic Acquirers: CARB's Advanced Clean Trucks regulation enforcement acceleration is the leading indicator that zero-emission van adoption is crossing from pilot to replacement-cycle mainstream. Mid-tier electric upfitters with EPA and CARB certification pipelines represent the optimal acquisition archetype for platform consolidation. Watch for utility interconnection queue clearance rates as the signal of infrastructure readiness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake with Korean suppliers secures cell allocation ahead of EPA Phase 3 ramp. |
| Charging Infrastructure Partnership | Utility co-development in Texas and Florida accelerates depot electrification for Sun Belt fleet operators. |
| Platform Standardization | Shared electric skateboard across cargo and passenger variants reduces engineering overhead for compliance deadlines. |
| Geographic Manufacturing Footprint | Mexican assembly expansion leverages USMCA provisions while serving US and Canadian demand clusters. |
| Software-Defined Vehicle Investment | Over-the-air powertrain optimization extends vehicle lifecycle value for fleet-as-a-service providers. |
Research Methodology
Document review covered EPA Phase 3 regulatory filings, CARB Advanced Clean Trucks compliance databases, and USMCA trade flow records, complemented by interviews with fleet procurement directors at regional parcel carriers, OEM platform engineers, Tier 1 battery supplier commercial leads, and utility demand-side management officers. Secondary validation drew from NHTSA vehicle registration data, EIA transportation energy consumption surveys, and provincial clean fuel standard incentive disclosures. Bottom-up fleet operator surveys and top-down production capacity assessments were triangulated to anchor volume estimates.
Historical registration trends were cross-referenced against panel input from fleet operators and charging infrastructure developers. The analytical framework modeled vehicle type, fuel type, market segment, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from segment-level replacement cycle analysis and powertrain adoption curve modeling. Battery cost trajectory assumptions and utility incentive stack evolution constituted key industry-specific forecast inputs.
Underlying measurement precision varies by segment; electric powertrain adoption rates carry tighter precision than camper van recreational demand projections. Forecasts reflect documented assumptions about regulatory enforcement timing and mineral supply chain expansion. Battery supply constraints, charging interconnection delays, and CARB waiver litigation outcomes represent the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Modular Trailer Market