
 Slovakia Solar Energy Market | 2026-2036
Slovakia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Solar Energy Market Analytics
Aftermarket service revenue is narrowing as manufacturers compete to capture lifetime value from photovoltaic installations. Slovenské elektrárne, A.S. leverages its legacy grid infrastructure to dominate utility-scale project development. Západoslovenská energetika sustains regional channel control through integrated metering and distribution networks. Green Energy SK s.r.o. specializes in distributed commercial installations, occupying a niche between residential rooftops and national grid feeders.
Slovakia solar energy encompasses photovoltaic systems that convert sunlight into electricity through semiconductor junctions, typically silicon cells with conversion efficiencies ranging from 18% to 22% for commercial modules, deployed to displace fossil generation in centralized and distributed grids. Photovoltaic modules lead installed capacity but battery storage attachments are expanding fastest as grid operators impose stricter ramp-rate requirements. Utility-scale installations command the largest capital deployment while residential segments generate higher margins per kilowatt due to soft-cost premiums in permitting and customer acquisition.
The European Union's Green Deal and Slovakia's national renewable energy action plan shape project economics through feed-in tariff structures and grid-connection priority rules. BIS-aligned technical standards govern module certification and inverter grid-code compliance for market access. Slovakia's regulatory authority for network industries oversees interconnection queues that determine project timelines. Stakeholders must monitor pending revisions to EU electricity market design rules that could alter revenue stacking for storage-coupled solar assets.
Market Dynamics
The EU Green Deal's binding renewable targets are compressing Slovakia's deployment timelines, forcing developers to accelerate grid interconnection queues while battery storage mandates reshape project economics.
Growth Catalysts
- EU Green Deal framework:Binding renewable energy targets create regulatory certainty for utility-scale developers planning multi-year capital commitments.
- Trnava industrial corridor:Dense manufacturing load centers generate concentrated offtake demand for behind-the-meter solar installations.
- Battery storage coupling:Grid operators impose stricter ramp-rate requirements that favor co-located photovoltaic-plus-storage configurations.
Market Restraints
- Polysilicon supply concentration:Input cost volatility from Chinese ingot and wafer producers squeezes module procurement margins for Slovak developers.
- Grid interconnection queues:Slovakia's regulatory authority for network industries processes connection requests through sequential technical studies that extend project timelines.
- Land use competition:Agricultural zoning restrictions in western Slovakia's fertile lowlands limit available terrain for ground-mounted solar parks.
Strategic Opportunities
- Eastern Slovakia penetration gap:Košice and Prešov regions show minimal installed capacity relative to technical solar potential and available transmission headroom.
- Agrivoltaics convergence:Dual-use installations combining photovoltaic arrays with crop cultivation unlock previously restricted agricultural land for energy production.
- Corporate PPA structures:Large industrial offtakers in Bratislava automotive clusters seek direct power purchase agreements bypassing regulated tariff frameworks.
Industry Challenges
- Grid code compliance certification:BIS-aligned inverter testing and grid synchronization protocols create multi-month approval bottlenecks before commercial operation.
- Electrical engineering talent scarcity:Specialized skills in medium-voltage substation design and protection relay configuration command premium wages that inflate EPC costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Solar Energy Market |
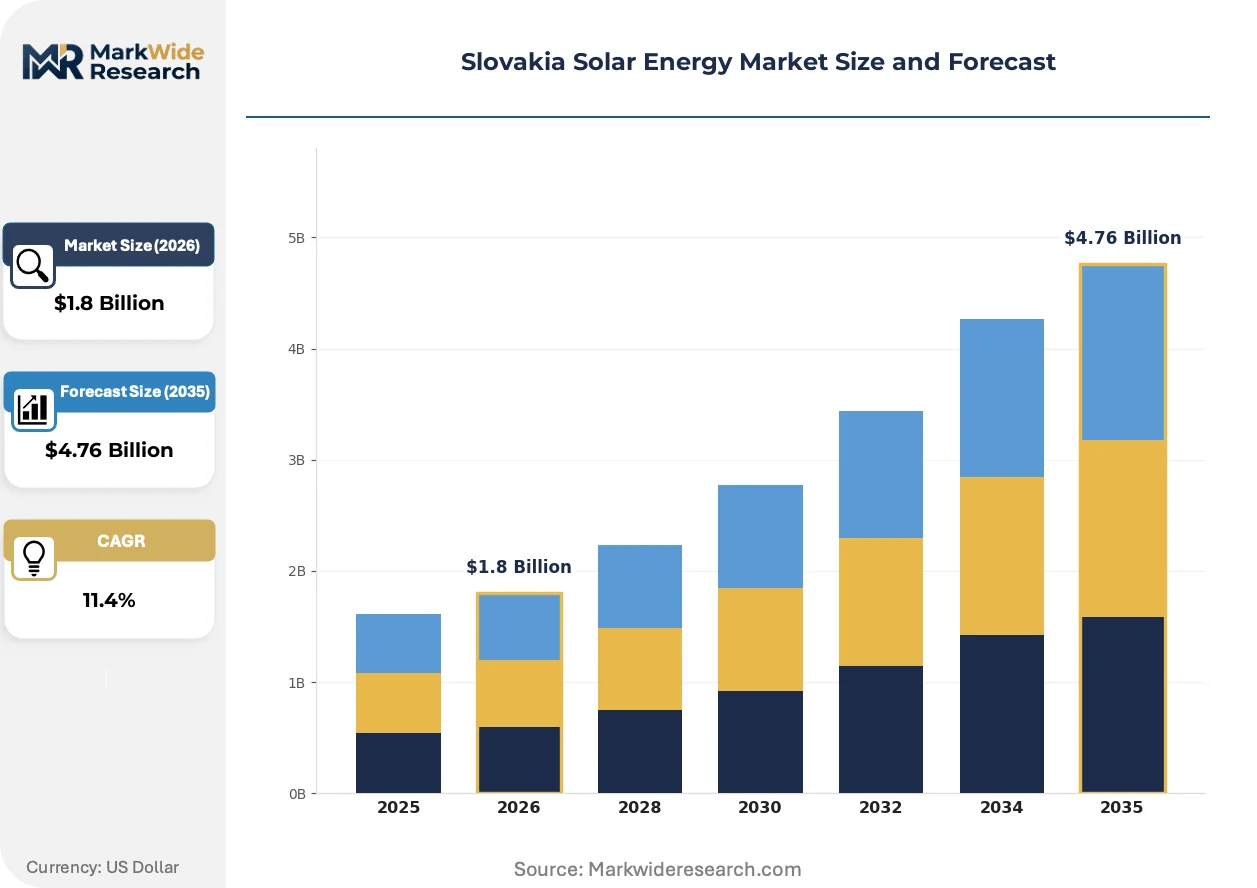
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Modules, Inverters, Mounting Systems, Batteries Installation Type: Residential, Commercial, Utility-scale, Off-grid Technology: C-Si, Thin-Film, Bifacial, Concentrated Solar Power End User: Households, Businesses, Government, Non-profits |
| Companies Covered | Slovenské elektrárne, A.S., Západoslovenská energetika (ZSE), Axpo Holding AG, CEZ Group – Slovak unit, Green Energy SK s.r.o., VP Solar, Acrosun s.r.o., Solartec Group, Enery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Solar Energy Market Evolving Landscape
Digital intelligence is penetrating photovoltaic asset management, compressing operational response times while policy instruments accelerate storage attachment rates and buyer sophistication reshapes contract structures.
Module-level power electronics is digitizing performance optimization across Slovakia's distributed commercial fleet. Microinverter and power optimizer architectures enable granular monitoring of individual panel output. Industrial facility managers in Bratislava's logistics parks adopt these systems to isolate shading losses and accelerate fault detection. The technology is digitizing traditional string-level maintenance workflows into predictive, panel-specific intervention protocols.
EU electricity market design revisions are restructuring revenue stacking opportunities for hybrid solar-storage assets. Pending capacity remuneration mechanisms and fast-frequency response markets create new value streams beyond energy arbitrage. Utility-scale developers in Trnava region reconfigure project layouts to maximize grid services revenue. Battery inverter sizing now dominates early-stage engineering discussions.
Industrial offtakers are consolidating procurement authority through centralized energy management functions. Automotive suppliers and electronics manufacturers establish dedicated sustainability procurement teams that negotiate multi-site solar contracts. Traditional installer-led sales channels face displacement from direct developer relationships. The shift is most pronounced among Bratislava-based multinational subsidiaries with group-level renewable targets.
Slovakia Solar Energy Market Segmentation
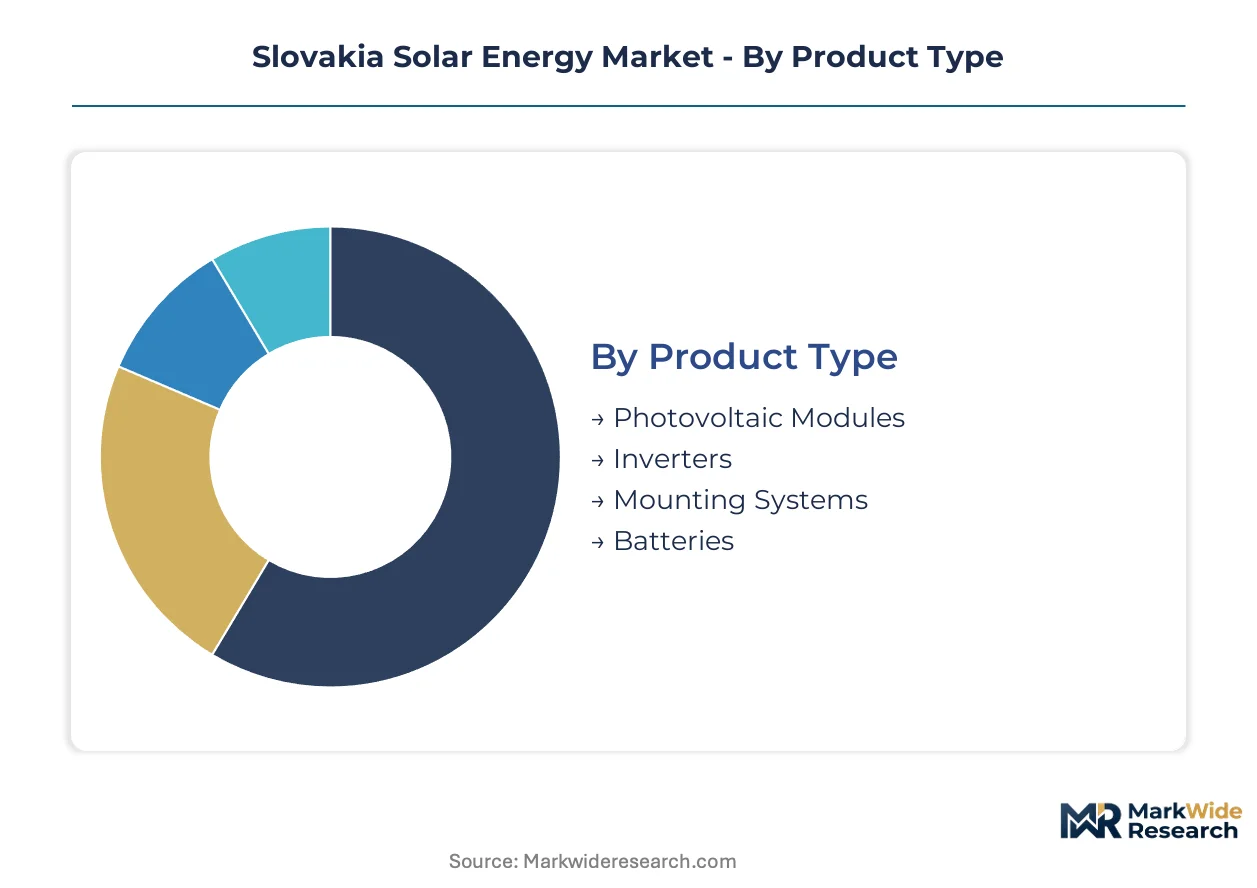
Slovakia's solar market segments reveal divergent procurement patterns across hardware categories and installation scales. Understanding these divisions exposes where margin compression concentrates and where pricing power persists for developers and equipment suppliers.
Product Type:
The hardware spectrum spans from commodity silicon cells to integrated storage systems, with each tier commanding distinct procurement channels and technical service requirements.
- Photovoltaic Modules:Crystalline silicon panels with conversion efficiencies between 18% and 22% constitute the core revenue base. Industrial buyers in Trnava's automotive corridor specify performance warranties and degradation curves in procurement tenders. Module sourcing concentrates through distributors serving utility-scale developers with volume pricing structures.
- Batteries:Lithium-ion storage systems are expanding fastest as Slovakia's grid operator imposes ramp-rate requirements on new interconnections. Behind-the-meter installations in Bratislava logistics parks drive demand for containerized battery inverters sized to photovoltaic generation profiles. Battery attachment rates are climbing as grid services revenue stacks with energy arbitrage.
- Inverters:String and central inverter architectures convert DC panel output to grid-synchronized AC power.
- Mounting Systems:Fixed-tilt and tracking structures support ground-mounted and rooftop installations across Slovakia's western regions.
Established volume favors Photovoltaic Modules; emerging adoption favors Batteries.
Installation Type:
Project scale determines capital intensity, customer acquisition cost structures, and regulatory pathway complexity for developers operating across Slovakia.
- Utility-scale:Ground-mounted solar parks exceeding 1 MW capacity dominate capital deployment and grid interconnection queue positions. Developers cluster projects in Trnava and Bratislava regions where transmission headroom accommodates bulk injection. EU Green Deal binding targets compress development timelines for these installations.
- Residential:Rooftop systems under 10 kW generate higher margins per kilowatt due to soft-cost premiums in permitting and customer acquisition. Slovak households in Bratislava suburbs leverage net metering frameworks and building-integrated photovoltaic aesthetics. Installer networks compete on financing packaging and warranty terms.
- Commercial:Mid-scale rooftop and carport installations serve manufacturing and logistics facilities with behind-the-meter configurations.
- Off-grid:Standalone systems power remote agricultural operations and mountain facilities beyond distribution network reach.
Utility-scale commands deployment capital; Residential captures margin per unit.
Technology:
Cell architecture and module design choices trade efficiency premiums against cost curves and installation flexibility for Slovak project developers.
- C-Si:Crystalline silicon technology with PERC and TOPCon architectures delivers proven bankability for utility-scale financiers. Slovak developers specify C-Si modules for projects requiring 25-year performance warranties and documented degradation rates. Manufacturing scale in Asian supply chains keeps module pricing competitive.
- Bifacial:Double-glass modules capture reflected light from ground surfaces, boosting yield in high-albedo installations. Eastern Slovakia's agrivoltaic pilots specify bifacial configurations to maintain crop cultivation beneath elevated arrays. Bifacial technology is gaining share fastest among ground-mounted projects seeking optimization.
- Thin-Film:Cadmium telluride and CIGS alternatives offer temperature coefficient advantages in specific mounting configurations.
- Concentrated Solar Power:Thermal concentration systems remain absent from Slovak deployment due to lower direct normal irradiance versus southern European markets.
C-Si anchors procurement volumes; Bifacial technology is climbing the fastest.
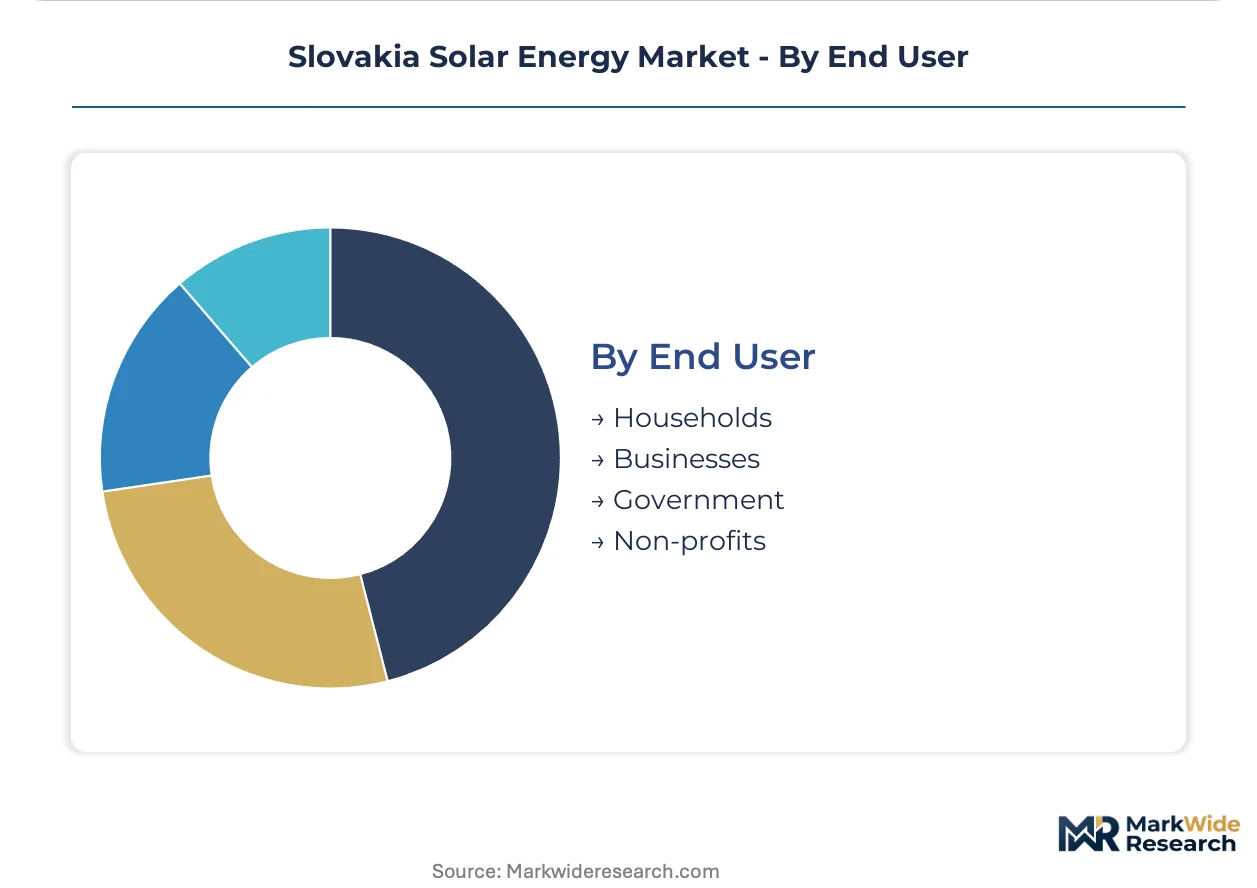
End User:
Customer type shapes contract structures, financing mechanisms, and decision-making timelines for solar developers targeting Slovak markets.
- Businesses:Industrial offtakers in Bratislava automotive clusters and Trnava manufacturing corridors drive corporate PPA demand. Sustainability procurement teams negotiate multi-site contracts with direct developer relationships, displacing traditional installer channels. Energy cost volatility accelerates behind-the-meter adoption.
- Households:Residential owners prioritize aesthetic integration and financing accessibility over technical specifications. Slovak households respond to net metering value propositions and building permit streamlining in western regions. Customer acquisition costs concentrate in urban and suburban municipalities.
- Government:Public buildings and municipal infrastructure procure through tender frameworks with domestic content preferences.
- Non-profits:Social housing and community energy cooperatives access subsidized financing through national renewable energy programs.
Businesses consolidate procurement authority; Households expand addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Slovakia exhibits the highest demand elasticity as industrial buyers negotiate aggressively on corporate PPA terms, while eastern regions show price inelasticity due to limited supplier alternatives and transmission constraints.
Bratislava Region
Automotive clusters and logistics parks drive concentrated behind-the-meter demand. EU Green Deal binding targets compress development timelines for utility-scale interconnectors. Bratislava's Volkswagen and Kia supplier networks negotiate multi-site solar contracts through centralized procurement functions.
Trnava Region
Dense manufacturing load centers generate bulk offtake demand for industrial self-consumption. Slovakia's regulatory authority for network industries processes grid connection requests through sequential technical studies. Peugeot manufacturing complex anchors regional solar park development with dedicated substation infrastructure.
Žilina Region
Mountain terrain limits ground-mounted deployment while rooftop commercial installations expand in urban centers. BIS-aligned technical standards govern module certification for grid-code compliance. Kia Motors Slovakia facility exemplifies large-scale corporate PPA adoption in automotive manufacturing corridors.
Košice Region
Eastern Slovakia penetration gap creates strategic opportunity relative to technical solar potential and available transmission headroom. National renewable energy action plan feed-in tariff structures incentivize first-mover projects. U.S. Steel Košice industrial complex represents untapped demand for behind-the-meter configurations.
Prešov Region
Agricultural zoning restrictions limit terrain availability yet agrivoltaic pilots unlock dual-use potential. Grid operators impose stricter ramp-rate requirements favoring photovoltaic-plus-storage configurations. Eastern lowlands experimental installations combine elevated bifacial arrays with crop cultivation beneath.
Slovakia Solar Energy Market Competitive Landscape
Legacy utilities and specialized developers split the market along infrastructure access versus agility vectors. Slovenské elektrárne leverages captive grid ownership to dominate utility-scale queue positions. Západoslovenská energetika sustains regional channel control through integrated metering networks. Green Energy SK occupies the distributed commercial niche between residential rooftops and national feeders. Competitive moves concentrate on securing interconnection priority rights and forming direct corporate PPA relationships that bypass traditional installer channels.
Within the legacy utility tier, Slovenské elektrárne, A.S. and Západoslovenská energetika exemplify infrastructure-incumbent positioning. Green Energy SK s.r.o. represents the agile specialist archetype targeting mid-scale commercial installations. These three anchors illustrate the market's structural division between grid-access dominance and segment-specific agility.
| Leading Market Players |
|---|
| Slovenské elektrárne, A.S. |
| Západoslovenská energetika (ZSE) |
| Axpo Holding AG |
| CEZ Group – Slovak unit |
| Green Energy SK s.r.o. |
| VP Solar |
| Acrosun s.r.o. |
| Solartec Group |
| Enery |
| Others |
Value Network & Pricing Analysis
Asian polysilicon ingot capacity in Xinjiang and Inner Mongolia feeds module pricing power downstream to Slovak developers negotiating procurement contracts. Module cost volatility transmits directly to project returns as developers buffer margin erosion through warranty tiering and performance guarantees.
Pricing Analysis
Aftermarket service revenue from operations and maintenance contracts drives lifetime value capture as manufacturers compete for recurring income streams. Three-tier pricing structure across premium, standard, and economy levels separates bankable tier-1 modules with 25-year warranties from tier-2 alternatives with reduced degradation guarantees. Cost compression in residential soft costs is intensifying because installer networks compete on customer acquisition efficiency. Utility-scale offtakers exhibit lowest price sensitivity due to long-term corporate PPA structures, while residential households respond most acutely to financing accessibility.
Supply Chain Analysis
Contract manufacturing concentration among Chinese module assemblers in Jiangsu and Anhui provinces controls global photovoltaic output. Geographic supply concentration centers on China for polysilicon and cell production, Vietnam for module assembly, and Germany for inverter manufacturing. Raw material dependencies rest on metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames for structural mounting. Single-source vulnerability in polysilicon purification creates exposure to trade policy shifts. Distribution runs through regional distributors serving utility-scale developers with volume pricing structures and direct manufacturer relationships for residential installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Slovakia solar energy market represents a high-growth disruption as EU Green Deal binding targets compress deployment timelines and force capital reallocation toward storage-coupled assets.
For Market Incumbents: Entrench grid interconnection priority rights through early queue positioning and captive substation infrastructure investments. Slovenské elektrárne must defend against agile commercial specialists by accelerating corporate PPA direct relationships that bypass traditional installer channels. Backward integration into battery inverter sourcing reduces exposure to supply bottlenecks.
For New Entrants and Emerging Players: Eastern Slovakia's Košice and Prešov regions offer minimal installed capacity relative to technical solar potential and available transmission headroom. Agrivoltaic pilots combining elevated bifacial arrays with crop cultivation unlock agricultural land previously restricted by zoning. Target corporate sustainability procurement teams at automotive suppliers with multi-site contract proposals.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy utility renewable divisions seeking balance sheet optimization. Long-term viability hinges on storage attachment rates and grid services revenue stacking rather than pure energy arbitrage. Specialist EPC contractors with medium-voltage substation design capabilities represent priority acquisition archetypes. Watch for EU electricity market design rule finalization as inflection signal for hybrid asset valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Structuring | Bratislava automotive clusters bypass regulated tariffs through direct developer negotiations. |
| Agrivoltaic Pilot Expansion | Eastern Slovakia dual-use installations unlock agricultural land for photovoltaic deployment. |
| Storage Coupling Integration | Trnava region developers reconfigure projects to capture fast-frequency response revenues. |
| Grid Interconnection Prioritization | Queue positioning at Slovakia's regulatory authority for network industries determines project timelines. |
| Module-level Power Electronics Adoption | Bratislava logistics parks deploy microinverters to isolate shading losses and accelerate fault detection. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented project development patterns. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided forward-looking deployment timelines. Secondary validation drew from EU Green Deal implementation documents, national renewable energy action plans, FERC-equivalent interconnection queue data, and project development databases. Bottom-up installation forecasts triangulate against top-down capacity targets issued by regulatory authorities.
Calibration against historical deployment trajectories and policy implementation lags shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include installation scale, technology architecture, end-user category, and regional grid infrastructure type. CAGRs derive from compound growth trajectory analysis rather than linear extrapolation. Forecast inputs incorporate battery attachment rate assumptions and corporate PPA penetration curves specific to automotive manufacturing corridors.
Practitioners should monitor EU electricity market design rule revisions and polysilicon trade policy developments for early signals of forecast deviation. Forecasts reflect assumptions about grid interconnection processing timelines and feed-in tariff continuity. Quarterly review of interconnection queue lengths and module procurement contract pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Panel Bracket Market