
 Alternate Marine Power Market | 2026-2036
Alternate Marine Power Market Size, Share, and Industry Trends Forecast 2026-2036
Alternate Marine Power Market Analysis
Norway's port electrification program is reshaping how vessel operators manage at-berth emissions across Scandinavian trade lanes. ABB leverages its shore connection hardware portfolio to dominate high-voltage installations at container terminals. Siemens sustains technology leadership through integrated grid-to-ship power conversion systems. Cavotec SA specializes in automated mooring and electrification interfaces that reduce connection times for commercial fleets.
Alternate marine power encompasses shore-based electrical supply systems, onboard energy storage, and renewable propulsion architectures that replace auxiliary diesel combustion during port stays and transit. These systems typically deliver power at 6.6 kV or 11 kV through standardized IEC/ISO cable configurations, enabling vessels to shut down auxiliary engines while maintaining hotel loads, cargo handling, and climate control. Battery storage technology commands the largest installed base among technology segments, though hydrogen fuel cells represent the fastest-expanding investment category as vessel operators target zero-emission routes. Commercial ships generate the dominant revenue share within vessel type segmentation, while ferry electrification programs in the Baltic and North Sea corridors concentrate near-term deployment volumes.
The International Maritime Organization's Carbon Intensity Indicator and the EU Emissions Trading System extension to maritime transport are tightening operational compliance requirements for vessel operators. EPA port emissions standards in the United States and MEE marine fuel regulations in China add parallel compliance layers that drive shore power infrastructure procurement. Stakeholders must evaluate which power generation type and technology combination aligns with their route profiles, port call patterns, and regulatory exposure across their operating geographies.
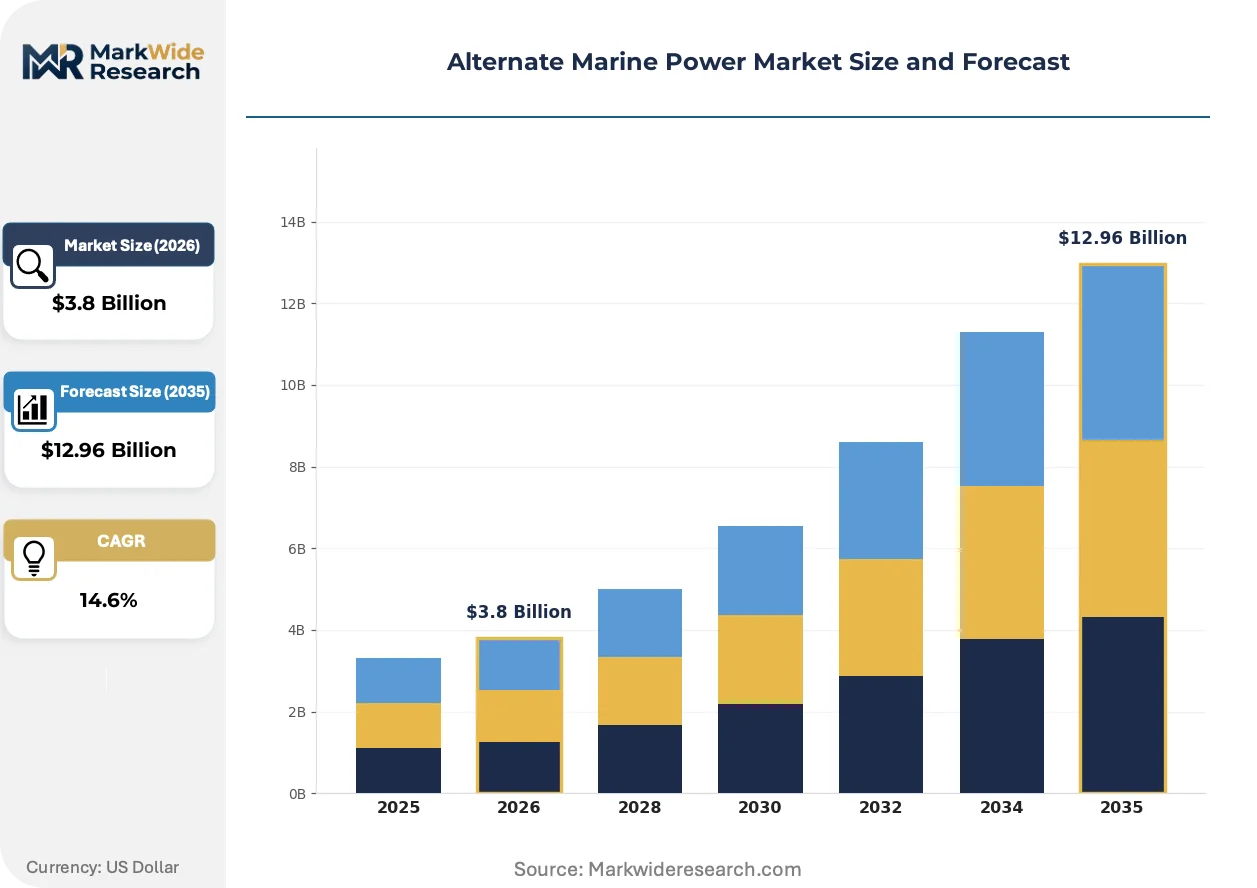
Market Dynamics
Port electrification mandates from the EU Green Deal are forcing vessel operators to reconfigure at-berth power architectures across Northern European trade lanes, compressing installation timelines and reshaping supplier procurement priorities.
Growth Catalysts
- EU Green Deal port mandates:EEA member states now require shore power availability at major commercial terminals, compelling ferry and cruise operators to install onboard connection systems.
- Battery energy density gains:Lithium-ion pack configurations now support 10+ megawatt-hour installations on medium-tonnage vessels, enabling full-electric short-sea routes.
- Norway's zero-emission fjord requirements:The country's maritime regulator bans diesel auxiliary operation in designated heritage waterways, accelerating shore-to-ship infrastructure deployment.
Market Restraints
- Copper and rare earth price volatility:Power cable and permanent magnet motor costs fluctuate with commodity markets, squeezing project margins for system integrators.
- Grid interconnection backlogs:Utility approval timelines for high-voltage shore connections extend 18-24 months at Hamburg, Rotterdam, and Antwerp terminals.
- Onboard space constraints:Battery banks and fuel cell stacks displace cargo capacity on existing hulls, creating tonnage-equivalent penalties for retrofit projects.
Strategic Opportunities
- Baltic Sea corridor electrification:Poland and Estonia lack shore power infrastructure at commercial terminals, creating first-mover installation contracts.
- Hydrogen bunkering convergence:Fuel cell shore power systems paired with port-side H2 storage enable zero-emission cold-ironing for deep-sea vessels.
- Performance-based maintenance contracts:System availability guarantees replace capital sales, locking in decade-long service revenue streams for technology providers.
Industry Challenges
- IEC 80005 certification bottlenecks:Testing facility capacity constraints delay shore connection system approvals, stretching delivery schedules.
- Multivoltage integration complexity:Vessels operating across 6.6 kV Nordic, 11 kV German, and 60 Hz US port standards require modular power management architectures.
- Shipyard electrical specialist scarcity:Qualified marine electricians capable of high-voltage shore connection installation command premium wages, inflating retrofit labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternate Marine Power Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Generation Type: Solar, Wind, Hydrogen, Biomass Vessel Type: Commercial Ships, Leisure Boats, Ferries, Fishing Vessels Technology: Battery Storage, Fuel Cells, Hybrid Systems, Renewable Integrations End User: Shipping Companies, Tour Operators, Freight Forwarders, Energy Suppliers |
| Companies Covered | ABB, Siemens, Wabtec Corporation, Cavotec SA, Wärtsilä, Danfoss, ESL Power Systems, Inc., Ratio Electric B.V., NIDEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternate Marine Power Market Emerging Trajectories
Maritime power systems are converging across generation, storage, and distribution layers, with vessel operators demanding modular architectures that adapt to heterogeneous port infrastructure standards.
Onboard battery systems are hybridizing with shore power interfaces to create seamless at-berth and transit energy management. Ferry operators in the North Sea corridor now specify dual-mode configurations that accept grid power during port calls and discharge stored energy during short crossings. This architecture compresses auxiliary engine runtime hours and extends major overhaul intervals.
REACH chemical restrictions and the EU F-Gas Regulation are phasing out sulfur hexafluoride in shore-side switchgear, compelling ABB and Siemens to accelerate vacuum interrupter and clean air insulation development. Container terminals in Germany and the Netherlands face 2027 compliance deadlines, driving retrofit procurement for existing high-voltage connection points.
Charter contracts now specify emissions performance clauses that penalize diesel auxiliary operation at berth. Cruise lines operating Mediterranean itineraries face EU ETS compliance costs that shift commercial preference toward vessels with certified shore power capability. Shipbrokers in Piraeus and Singapore report charter rate premiums for AMP-ready tonnage.
Alternate Marine Power Market Segmentation
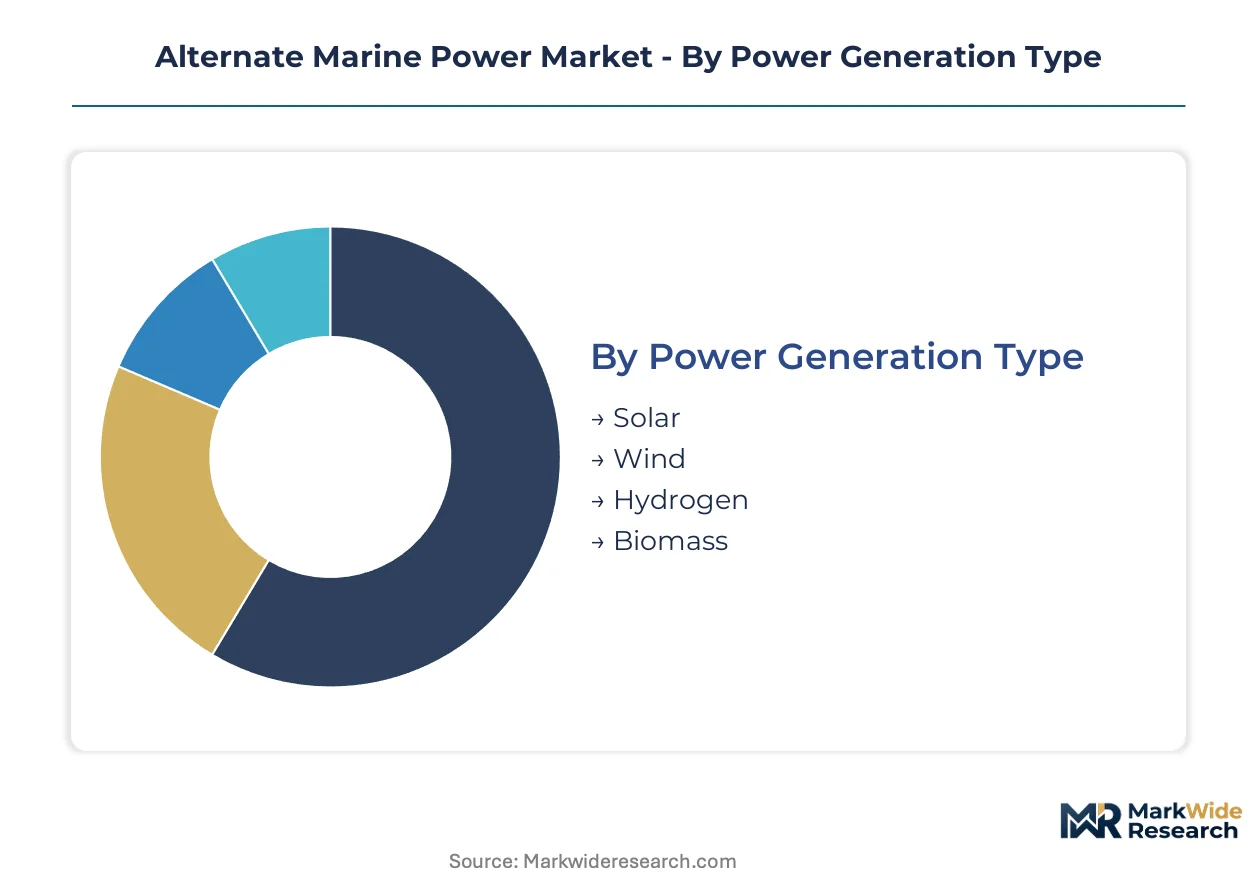
Vessel electrification requirements diverge sharply across operational profiles, forcing technology suppliers to architect modular systems that adapt to heterogeneous port infrastructure and duty cycles. Segmentation reveals where capital deployment concentrates and which power architectures command premium positioning.
Power Generation Type:
Mature grid-tied systems dominate near-term installations while emerging hydrogen pathways reshape long-term investment horizons.
- Solar:Photovoltaic arrays integrated into vessel superstructures and port-side canopies supplement shore power during daylight operations. Norwegian ferry terminals deploy solar-assisted charging to reduce grid draw during peak summer schedules.
- Wind:Shore-based turbines and auxiliary sail-assist systems target deep-sea routes with consistent trade wind exposure. North Sea corridor ports pair offshore wind generation with high-voltage shore connections to decarbonize at-berth supply.
- Hydrogen:Proton exchange membrane fuel cells convert stored H2 to electricity for zero-emission cold-ironing. EU Green Deal funding accelerates port-side electrolyzer and bunkering infrastructure at German and Dutch terminals.
- Biomass:Processed marine biofuels power auxiliary generators where electrical shore connections remain unavailable. Baltic Sea fishing fleets utilize bio-methanol in hybrid configurations to meet MARPOL sulfur caps.
Grid-tied shore power retains volume leadership; hydrogen fuel cell systems hold the steepest expansion trajectory.
Vessel Type:
Application intensity varies by route predictability and port call frequency, concentrating investment where electrification economics prove most compelling.
- Commercial Ships:Container vessels and bulk carriers with regular liner schedules amortize shore connection hardware across hundreds of annual port calls. Hamburg and Rotterdam terminals mandate AMP compatibility for mainline vessel berthing priority.
- Ferries:Short-sea routes with 30-90 minute crossings enable full battery-electric propulsion paired with rapid shore charging. Norway's zero-emission fjord regulations force diesel auxiliary retirement on heritage routes.
- Leisure Boats:Marina-based yacht electrification concentrates in Mediterranean charter hubs where EU ETS compliance costs alter operator preferences.
- Fishing Vessels:Intermittent port presence and high power demand for processing equipment complicate shore power economics, limiting adoption to major processing ports.
Commercial ships dominate installed capacity; ferries command the most aggressive retrofit timelines.
Technology:
Cost tier stratification separates proven lithium-ion installations from emerging fuel cell architectures still scaling manufacturing volume.
- Battery Storage:Lithium-ion packs now achieve 10+ megawatt-hour configurations on medium-tonnage hulls, enabling full-electric short-sea operations. North Sea ferry operators specify dual-mode battery-shore systems to eliminate auxiliary runtime.
- Fuel Cells:Hydrogen proton exchange membrane systems deliver continuous baseload power without the weight penalties of equivalent battery capacity. Port-side H2 storage paired with fuel cell shore power enables zero-emission cold-ironing for deep-sea vessels.
- Hybrid Systems:Diesel-electric architectures with shore power interfaces bridge gaps where grid infrastructure remains incomplete. Polish and Estonian terminals lacking high-voltage connections drive hybrid demand in Baltic expansion corridors.
- Renewable Integrations:Combined solar, wind, and shore power management systems optimize energy sourcing by time-of-day and berth availability.
Battery storage commands the largest installed base; fuel cell systems are expanding most quickly as electrolyzer capacity scales.
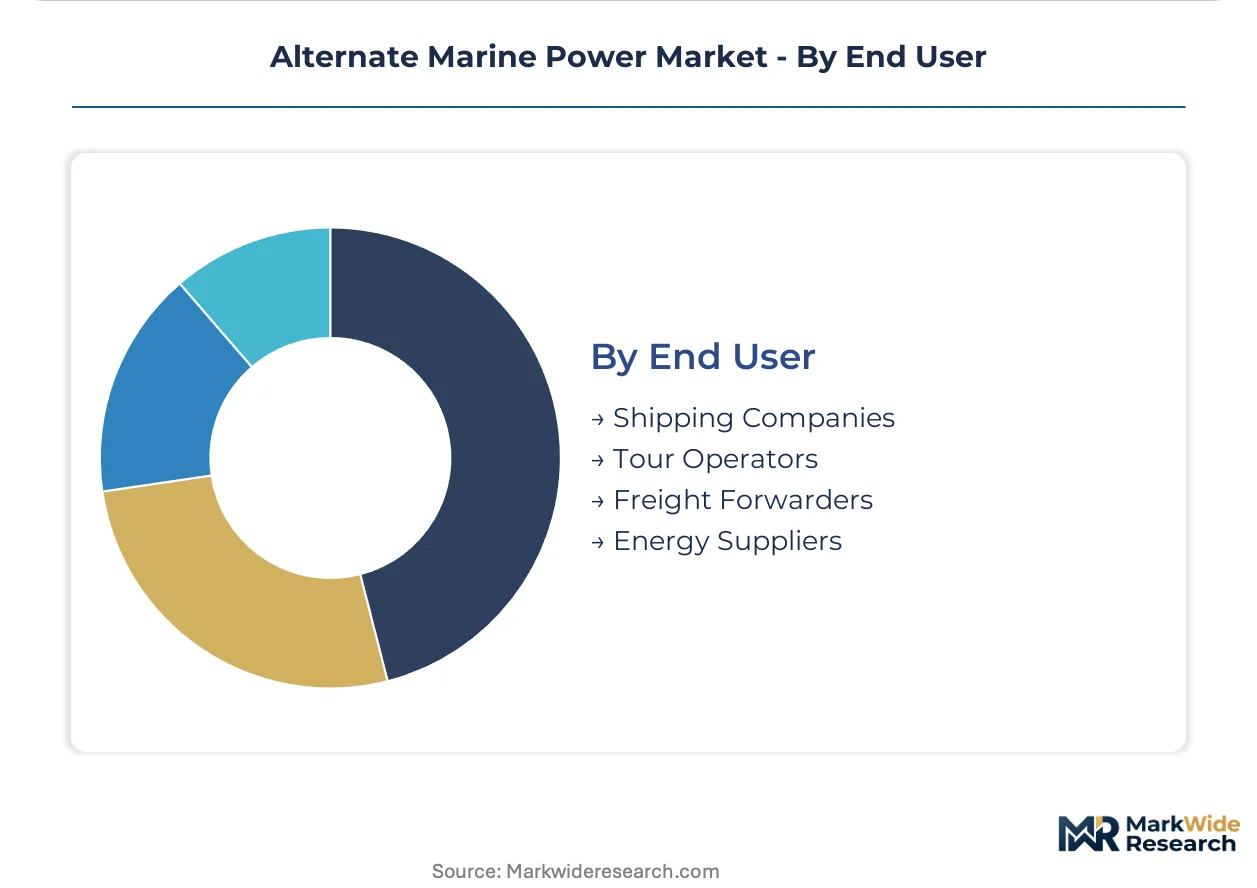
End User:
Procurement authority concentrates with fleet operators facing direct regulatory exposure, while energy suppliers capture recurring revenue through infrastructure ownership.
- Shipping Companies:Container line operators with EU ETS compliance obligations prioritize AMP-ready tonnage in newbuild specifications. Charter rate premiums for shore-power-capable vessels now appear in Piraeus and Singapore brokerage markets.
- Tour Operators:Cruise lines face EU Green Deal port mandates and emissions trading costs that shift commercial preference toward vessels with certified shore power capability. Mediterranean itinerary planning now incorporates berth electrification availability.
- Freight Forwarders:Logistics providers exert indirect pressure through emissions disclosure requirements in supply chain contracts.
- Energy Suppliers:Utility and independent power producers own shore-side infrastructure, capturing decade-long service revenue through availability-based maintenance contracts.
Shipping companies drive capital expenditure volume; energy suppliers are capturing the fastest-expanding share of lifetime value through infrastructure ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shore power infrastructure investment clusters where port electrification mandates intersect with high-frequency vessel traffic. Grid interconnection capacity and utility rate structures determine deployment economics across maritime trade corridors.
Norway
Ferry operators along the Western Fjords route face zero-emission auxiliary engine bans in heritage waterways. The Norwegian Maritime Authority enforces diesel shutdown requirements at Geirangerfjord and Nærøyfjord berths. Bergen and Stavanger terminals now host high-voltage shore connections serving cruise and cargo fleets.
Germany
Container terminals at Hamburg and Bremerhaven mandate AMP compatibility for mainline vessel berthing priority. The EU Green Deal port infrastructure requirements drive Hamburg Port Authority procurement of 11 kV connection systems. Shipyards in Lower Saxony retrofit bulk carriers with modular power management architectures for multivoltage operations.
Netherlands
Rotterdam terminal operators face 2027 deadlines for sulfur hexafluoride-free switchgear under EU F-Gas Regulation. Port of Rotterdam Authority coordinates grid-to-ship power conversion with offshore wind generation from the North Sea. Amsterdam cruise terminals install rapid-connection systems to minimize vessel turnaround times.
United States
EPA port emissions standards compel California and East Coast terminal electrification investments. The Ports of Los Angeles and Long Beach enforce vessel speed reduction and shore power utilization requirements for ocean-going carriers. Seattle and Vancouver terminals in the Pacific Northwest corridor serve Alaska cruise routes with cold-ironing infrastructure.
China
MEE marine fuel regulations tighten at-berth emissions requirements at Shanghai and Shenzhen container terminals. Yangtze River Delta ports pilot hydrogen bunkering paired with fuel cell shore power systems. Qingdao and Tianjin terminals accelerate high-voltage connection deployment for bulk carrier fleets.
Alternate Marine Power Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying power conversion hardware and cable management systems. The vendor base stratifies across three tiers: multinational electrical conglomerates with full-stack capabilities, regional system integrators focused on port-side installation, and niche component fabricators specializing in marine-rated connectors and switchgear. Competitive positioning hinges on IEC 80005 certification timelines, utility intercoordination expertise, and performance-based service contract structuring. Technology licensing and strategic port authority partnerships represent the dominant competitive moves reshaping procurement relationships.
Within the multinational platform tier, ABB and Siemens exemplify integrated grid-to-ship system architectures spanning shore connection hardware through onboard power management. Cavotec SA occupies a specialist position in automated mooring and electrification interfaces that compress vessel connection durations. Wärtsilä anchors the maritime propulsion integrator segment, leveraging engine room system knowledge to hybridize shore power with onboard energy storage. These three companies represent distinct archetypes: electrical infrastructure conglomerate, connection interface specialist, and marine propulsion system integrator.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Wabtec Corporation |
| Cavotec SA |
| Wärtsilä |
| Danfoss |
| ESL Power Systems, Inc. |
| Ratio Electric B.V. |
| NIDEC Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium-ion cell manufacturing is compressing battery pack pricing for marine energy storage systems while forcing European system integrators toward service-based revenue models to defend margins.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure for shore-side switchgear, separating sulfur hexafluoride-free vacuum interrupter systems at premium positioning from conventional equipment facing compliance-driven obsolescence. Project-based contracting dominates, with price differentiation anchored in IEC 80005 certification grade and after-sales service bundling. Cost compression in standard battery storage configurations is intensifying because of oversupplied lithium-ion cell capacity. Ferry operators with predictable route schedules exhibit lowest price sensitivity, while fishing fleet retrofitters face acute capital constraints.
Supply Chain Analysis
Copper cathode and rare earth permanent magnet feedstock volatility in Chile, China, and the Democratic Republic of Congo shapes procurement risk profiles for power cable and motor manufacturers. The supply chain draws from specialized marine electrical component fabricators in Germany, Japan, and South Korea for high-voltage connectors and switchgear. Single-source vulnerability concentrates in IEC-certified testing facility access. Distribution runs through port authority-led infrastructure tenders and shipyard retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
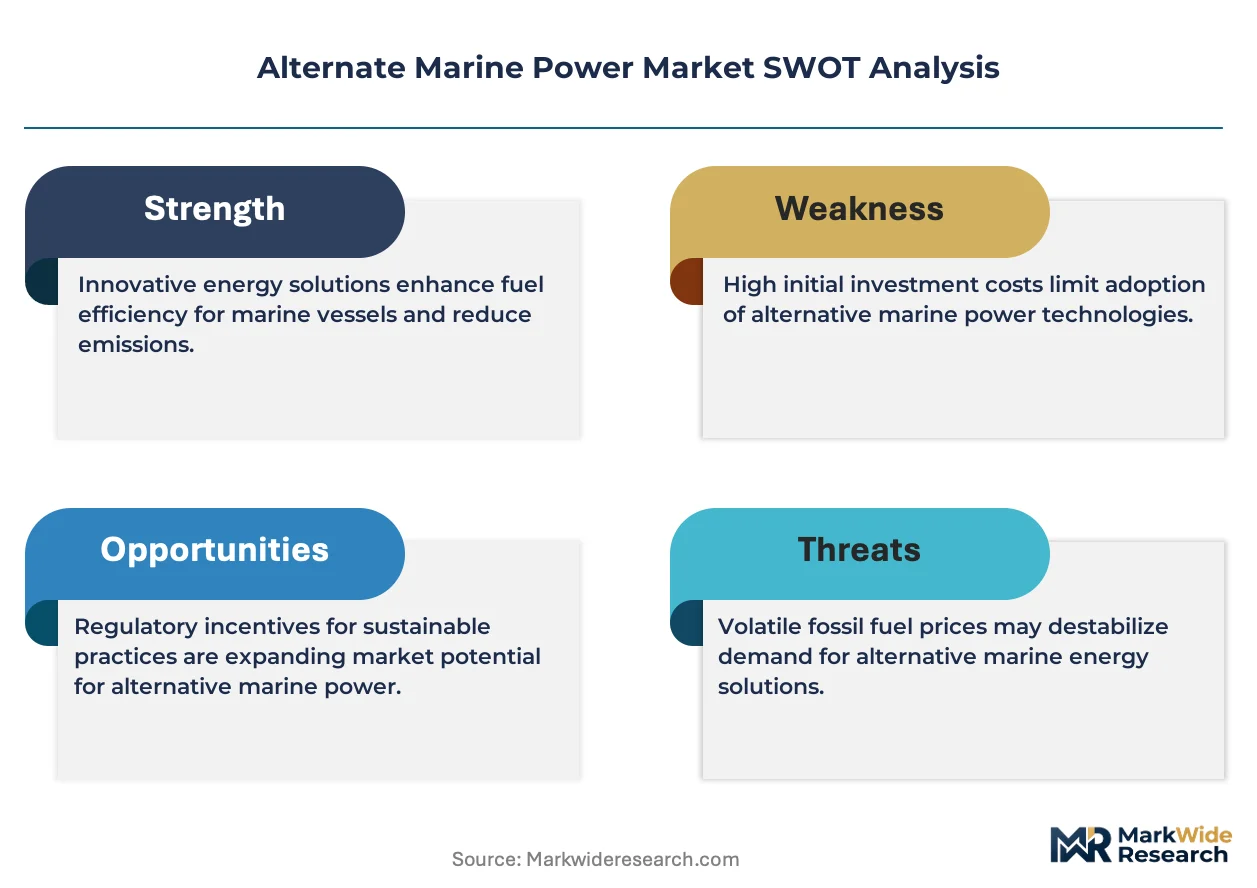
Analyst Recommendations
Incumbents face substitution pressure from hydrogen fuel cell architectures that threaten to displace battery-dominant shore power systems in deep-sea vessel applications.
For Market Incumbents: Pre-empt fuel cell encroachment by securing exclusive electrolyzer partnerships at Rotterdam and Hamburg terminals. Deepen backward integration into power conversion hardware to capture margin from copper price volatility. Lock in decade-long availability contracts with Norwegian ferry operators before hydrogen bunkering infrastructure matures.
For New Entrants and Emerging Players: Build out automated connection interface specialization for cruise terminals where ABB and Cavotec SA hold entrenched positions. Poland and Estonia shore power gaps offer the most penetrable geography. Lead with rapid-deployment modular systems that circumvent 18-24 month utility interconnection timelines plaguing established competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery storage manufacturing as Chinese cell overcapacity persists. Five-to-ten-year viability favors platform integrators with utility coordination capabilities over pure component fabricators. Monitor IEC 80005 certification backlog clearance as inflection signal for delivery timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Port Authority Partnership | Rotterdam and Hamburg tender awards lock in decade-long infrastructure deployment pipelines. |
| Electrolyzer Co-location | German and Dutch terminal hydrogen bunkering enables zero-emission cold-ironing service expansion. |
| Certification Fast-Track | IEC 80005 approval acceleration compresses competitive delivery schedules for system integrators. |
| Performance Contracting | Availability-based maintenance replaces capital sales, anchoring recurring revenue with ferry operators. |
| Multivoltage Architecture | Modular power management adapts vessels across 6.6 kV Nordic, 11 kV German, and 60 Hz US standards. |
Methodological Framework
A spread of perspectives from port authority infrastructure planners, ferry fleet operations directors, marine electrical system integrators, and high-voltage cable manufacturers converged on the working assumptions. Primary fieldwork combined with secondary validation from IMO regulatory filings, EU ETS implementation documents, and national maritime authority enforcement schedules. Customs data on copper and rare earth trade flows, alongside shipyard order books from Lloyd's Register, anchored supply-side calibration. Bottom-up installation projections and top-down regulatory mandate timelines were triangulated.
Demand-supply balance modeling across power generation type, vessel category, and technology segment shaped the analytical framework over the projection horizon. CAGRs derived from installation run-rate analysis and regulatory compliance deadline clustering. Segmentation incorporated power generation source, vessel operational profile, energy storage technology tier, and end-user procurement authority. Grid interconnection queue lengths and IEC certification facility capacity served as industry-specific forecast inputs.
Practitioners should monitor electrolyzer deployment timelines and F-Gas Regulation enforcement rigor for early signals of hydrogen pathway acceleration. Forecasts reflect assumptions on regulatory mandate adherence rates and commodity price stabilization. Cross-checking against Lloyd's Register vessel retrofit tracking and port authority infrastructure disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Green Fuels Market