
 Commercial Solar Panel Market | 2026-2036
Commercial Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Solar Panel Market Insights
A widening capital-intensity divergence between thin-film specialists and crystalline-silicon giants is rotating competitive dynamics across the commercial solar panel value chain. First Solar leverages its vertically integrated cadmium telluride manufacturing to sustain cost leadership in utility-scale procurement. JinkoSolar anchors its position through PERC and TOPCon cell dominance in distributed commercial rooftops across Asia and Europe. Canadian Solar competes on module-plus-storage bundling for North American independent power producers seeking streamlined EPC contracts.
Commercial solar panels are photovoltaic modules engineered for non-residential electricity generation, typically rated between 400W and 700W per unit with aluminum-framed glass laminates encapsulating silicon or thin-film semiconductor junctions. These systems convert solar irradiance into direct current for on-site consumption, grid export, or battery charging across warehouses, factories, and institutional campuses. Monocrystalline technology leads installed capacity due to superior conversion efficiency in space-constrained rooftop applications across dense urban zones. Bifacial modules represent the fastest-expanding technology segment as ground-mounted solar farms exploit reflected albedo gains from concrete, gravel, and snow surfaces. Thin-film panels retain structural relevance in utility-scale deserts where temperature coefficients and partial-shade tolerance offset lower nameplate efficiency.
The US EPA and FERC shape interconnection timelines and environmental permitting for utility-scale arrays, while the EU Green Deal and F-Gas Regulation mandate embodied-carbon disclosures and fluorinated-gas phaseouts in module manufacturing. India's BIS certification and PLI scheme for domestic cell production restrict import access while subsidizing local capacity buildouts. Stakeholders must monitor evolving domestic-content thresholds across the US, EU, and India as tariff walls and subsidy eligibility criteria redefine supply chain economics for project developers and module suppliers alike.
Market Dynamics
Utility-scale developers are consolidating procurement around high-wattage bifacial modules while distributed commercial buyers prioritize rapid-install lightweight systems, creating divergent product roadmaps across the value chain.
Growth Catalysts
- US IRA Investment Tax Credit:The 30% credit extension through 2032 de-risks project finance for Texas and California solar-plus-storage developments, accelerating gigawatt-scale deployment pipelines.
- Data Center Load Growth:Hyperscale cloud operators in Northern Virginia and Singapore are contracting 500MW-plus solar farms under 15-year PPAs, anchoring offtake certainty for developers.
- TOPCon Cell Efficiency Gains:Tunnel oxide passivated contact architecture is pushing module outputs past 600W, shrinking land requirements for ground-mounted arrays in land-constrained Gujarat and Rajasthan.
Market Restraints
- Polysilicon Price Volatility:Xinjiang-sourced metallurgical-grade silicon feedstock exposes crystalline-silicon module margins to energy-cost fluctuations and forced-labor scrutiny in EU supply chains.
- Interconnection Queue Congestion:FERC Order 2023 implementation delays are stretching grid-connection timelines to 36-plus months for Texas ERCOT projects, freezing capital deployment.
- Aluminum Framing Cost Exposure:Primary aluminum smelter concentration in Yunnan and Quebec ties module BOM costs to regional electricity pricing and export tariff volatility.
Strategic Opportunities
- Agrivoltaics in Maharashtra:Elevated mounting systems enabling dual-use solar generation over shade-tolerant crops are unlocking previously excluded agricultural land for commercial arrays.
- Building-Integrated Photovoltaics:Curtain-wall and skylight-integrated thin-film modules are penetrating high-rise commercial construction in Singapore and Dubai, displacing conventional facade materials.
- EU Carbon Border Adjustment:Embodied-carbon disclosure requirements are creating first-mover advantage for European module recyclers and low-carbon polysilicon producers in Norway and France.
Industry Challenges
- Skilled EPC Labor Scarcity:Certified solar electricians and structural engineers are concentrated in legacy markets, constraining buildout velocity in emerging African and Southeast Asian commercial segments.
- Bifacial Performance Modeling Complexity:Albedo variability and rear-side irradiance uncertainty are complicating revenue forecasting and lender due diligence for utility-scale projects.
- Module Recycling Infrastructure Gaps:End-of-life collection networks and high-purity silicon recovery capabilities remain underdeveloped relative to installed base growth in early-adopter markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Solar Panel Market |
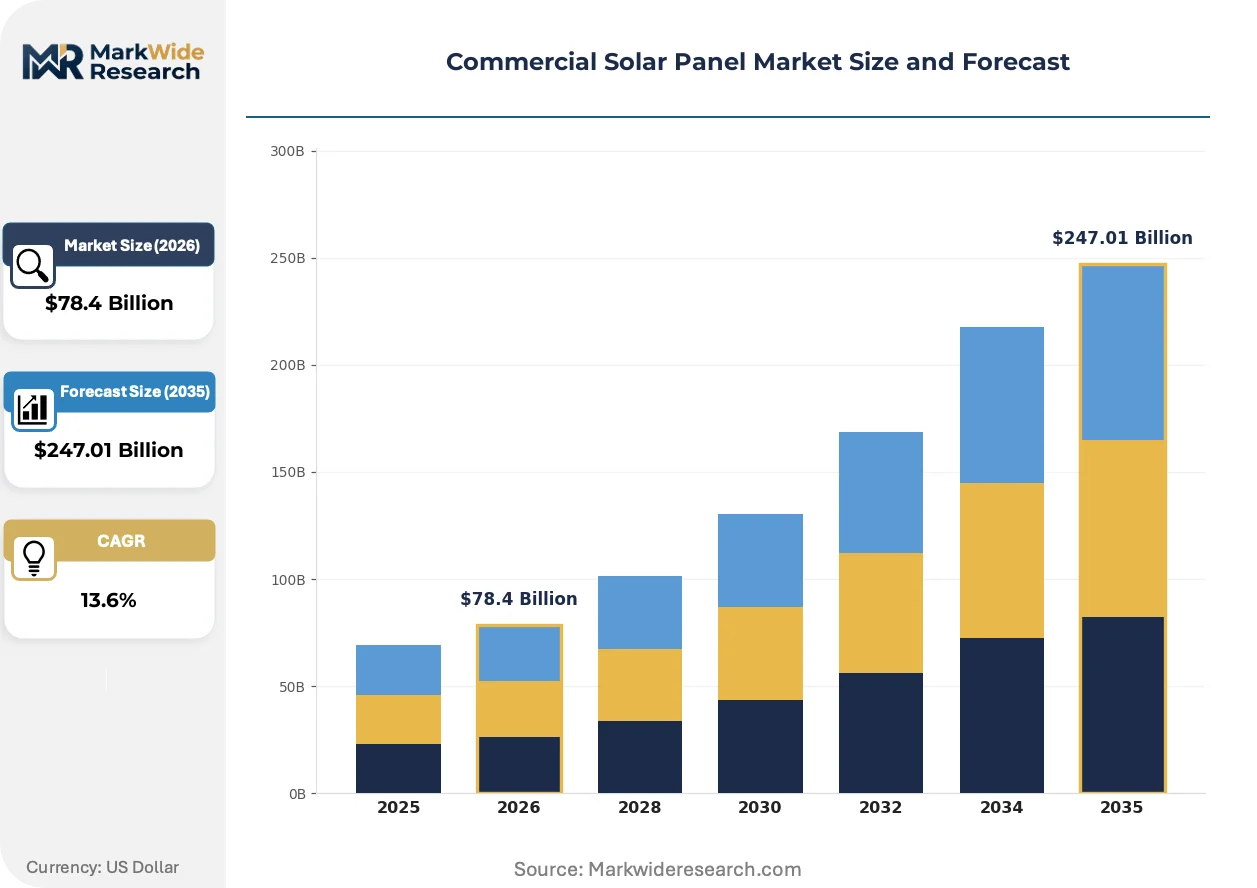
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Rooftop, Ground-mounted, Solar Farms, Carports End User: Commercial Buildings, Educational Institutions, Government Facilities, Industrial Plants Installation Type: On-grid, Off-grid, Hybrid, Community Solar |
| Companies Covered | First Solar, Canadian Solar, Qcells, Trina Solar, JA Solar, LONGi Green Energy, JinkoSolar, SEG Solar, Silfab Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Solar Panel Market Trends and Innovations
Module architecture is fragmenting across three vectors: cell-level efficiency breakthroughs, mounting system integration, and digital performance optimization. Each vector is reshaping supplier competitive position and buyer procurement criteria.
Perovskite-silicon tandem junction technology is miniaturizing the efficiency gap between laboratory demonstrations and field-deployed modules. Oxford PV and Swift Solar are piloting 28%-plus conversion prototypes for commercial rooftop segments where space constraints dominate project economics. This dual-junction approach is compressing the payback period for high-cost urban installations in Tokyo and London.
China's MIIT mandatory module efficiency standards and the EU F-Gas Regulation phase-down are tightening manufacturing specifications simultaneously. The MIIT rules eliminate sub-20% efficiency modules from domestic procurement, while F-Gas restrictions on SF6 and NF3 process gases are forcing polysilicon refiners to adopt fluorine-free cleaning chemistries. European module assemblers are responding by qualifying alternative encapsulant materials and accelerating supply chain audits.
Corporate buyers are consolidating procurement through aggregated virtual PPAs rather than site-specific installations. RE100 members in Germany and the Netherlands are pooling offtake commitments to access utility-scale projects without direct rooftop ownership. This buyer aggregation is visible most acutely in the Netherlands, where port logistics operators and greenhouse clusters are joint-venturing 200MW-plus solar parks to meet Scope 2 reduction targets.
Commercial Solar Panel Market Segmentation
Commercial solar panel procurement channels diverge sharply between utility-scale developers seeking standardized high-wattage modules and distributed buyers demanding rapid-install flexibility. Understanding these pathway distinctions enables suppliers to align product roadmaps with margin structures and buyer decision criteria across the value chain.
Technology:
Distributor and EPC channel flows split between efficiency-optimized rooftop SKUs and cost-minimized utility-scale pallets, with thin-film and bifacial variants commanding specialized procurement relationships.
- Monocrystalline:Single-crystal silicon cells deliver conversion efficiencies above 22% through passivated emitter and rear contact architecture. Demand concentrates in space-constrained commercial rooftops across Tokyo and London where premium pricing offsets land scarcity constraints.
- Bifacial:Dual-sided light capture enables 10-20% energy yield gains from reflected albedo on concrete, gravel, and snow surfaces. Ground-mounted solar farms in Texas and Rajasthan exploit this technology to shrink land requirements per megawatt of contracted output.
- Polycrystalline:Multi-crystal silicon construction offers moderate efficiency at lower manufacturing cost, serving price-sensitive distributed commercial segments in Southeast Asian markets.
- Thin-Film:Cadmium telluride and copper indium gallium selenide junctions tolerate high temperatures and partial shading, retaining relevance in desert utility installations where temperature coefficients offset nameplate efficiency gaps.
Monocrystalline panels dominate installed base across distributed commercial segments. Bifacial modules are where expansion concentrates for utility-scale procurement pipelines.
Application:
Margin profiles vary by installation complexity, with solar farms and ground-mounted arrays permitting standardized EPC contracts while rooftop and carport applications demand customized structural engineering.
- Solar Farms:Utility-scale arrays exceeding 5MW capacity deploy standardized module pallets under long-term power purchase agreements. Texas ERCOT and Gujarat grid interconnection queues are absorbing gigawatt-scale procurement from hyperscale data center offtakers in Northern Virginia and Singapore.
- Rooftop:Commercial building installations integrate modules with existing electrical infrastructure and structural load limits. Warehouse and logistics facilities across Germany and the Netherlands are aggregating virtual PPA commitments to bypass direct ownership complexity.
- Ground-mounted:Fixed-tilt and tracking systems on dedicated land parcels serve industrial campuses and institutional campuses with predictable shading profiles.
- Carports:Elevated canopy structures combine parking coverage with generation capacity, penetrating corporate campuses and retail distribution centers seeking dual-use infrastructure.
Rooftop applications anchor distributed commercial revenue. Solar farms are climbing the fastest as corporate buyers consolidate procurement through aggregated offtake structures.
End User:
Buyer sophistication tiers separate engineering-capable industrial operators from procurement-dependent institutional segments, shaping sales cycle duration and technical support requirements.
- Industrial Plants:Energy-intensive manufacturing facilities with in-house engineering teams negotiate direct EPC contracts and pursue behind-the-meter storage co-location. Automotive assembly plants in Bavaria and battery gigafactories in Nevada are contracting 100MW-plus dedicated solar farms.
- Commercial Buildings:Office and retail property owners prioritize rapid-install lightweight systems with minimal structural reinforcement. Singapore high-rise developments and Dubai commercial towers are piloting building-integrated photovoltaic curtain walls.
- Educational Institutions:Universities and school districts leverage tax-exempt financing and sustainability mandates to justify longer payback periods on rooftop installations.
- Government Facilities:Federal and municipal procurement follows domestic-content requirements and prevailing wage regulations, extending sales cycles in exchange offtake certainty.
Industrial plants dominate procurement volume for utility-scale arrays. Commercial buildings represent the steepest expansion trajectory for distributed rooftop deployment.
Installation Type:
Grid-interconnection status determines equipment specification, with on-grid and hybrid systems requiring inverter compatibility with regional frequency and voltage standards while off-grid configurations prioritize battery integration depth.
- On-grid:Direct utility interconnection enables net metering and export revenue streams, requiring compliance with FERC Order 2023 interconnection standards in US markets and respective grid codes in EU member states.
- Hybrid:Battery-coupled systems enable peak shaving and backup power for commercial buildings facing reliability constraints. Texas ERCOT and California ISO markets are absorbing solar-plus-storage configurations under IRA investment tax credit eligibility.
- Off-grid:Standalone systems with deep-cycle battery banks serve remote industrial facilities and agricultural operations beyond distribution network reach.
- Community Solar:Shared array models enable commercial tenants without suitable rooftops to subscribe to offsite generation, penetrating urban cores with constrained physical infrastructure.
On-grid installations anchor current deployment base. Hybrid systems are gaining share fastest as storage cost declines and grid reliability concerns reshape buyer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, driving procurement toward lower-wattage polycrystalline modules, while data center operators in Northern Virginia and Singapore absorb premium pricing for high-efficiency bifacial systems under long-term power purchase agreements.
United States
Hyperscale cloud operators in Northern Virginia and Texas are contracting gigawatt-scale solar farms under 15-year PPAs. FERC Order 2023 governs interconnection timelines stretching to 36-plus months for ERCOT projects. The Texas Triangle corridor anchors utility-scale deployment as developers chase grid parity with battery co-location.
China
Domestic module demand concentrates in utility-scale solar farms across Qinghai and Inner Mongolia deserts. MIIT mandatory efficiency standards eliminate sub-20% modules from state procurement. The Yangtze River Delta manufacturing cluster pushes TOPCon cell outputs past 600W for export markets.
India
Gujarat and Rajasthan ground-mounted arrays exploit bifacial albedo gains from concrete and gravel surfaces. BIS certification and PLI scheme subsidies restrict import access while financing domestic cell production buildouts. The Mundra port logistics hub channels module exports to African and Middle Eastern markets.
Germany
Automotive assembly plants in Bavaria contract dedicated solar farms exceeding 100MW capacity. EU F-Gas Regulation mandates fluorinated-gas phaseouts in module manufacturing, forcing polysilicon refiners toward fluorine-free chemistries. The Netherlands border region aggregates virtual PPA commitments from port logistics operators.
Singapore
High-rise commercial towers pilot building-integrated photovoltaic curtain walls displacing conventional facade materials. The city-state's space constraints compress payback periods for premium-efficiency monocrystalline installations. Data center load growth drives 500MW-plus offtake contracts under 15-year structures.
Commercial Solar Panel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where efficiency-optimized specialists and scale-driven commodity producers coexist. The vendor base concentrates around three strategic tiers: vertically integrated thin-film manufacturers, crystalline-silicon giants with PERC and TOPCon dominance, and regional assemblers competing on module-plus-storage bundling. Dominant competitive moves include capacity expansion in Southeast Asian manufacturing hubs and strategic partnerships between module suppliers and independent power producers seeking streamlined EPC contracts.
Within the thin-film technology tier, First Solar occupies a position representing vertically integrated cadmium telluride manufacturing. Among crystalline-silicon specialists, JinkoSolar exemplifies PERC and TOPCon cell dominance across distributed commercial rooftops. Canadian Solar anchors the module-plus-storage bundling archetype for North American independent power producers.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar |
| Qcells |
| Trina Solar |
| JA Solar |
| LONGi Green Energy |
| JinkoSolar |
| SEG Solar |
| Silfab Solar |
| Others |
Pricing and Supply Chain Analysis
Gigawatt-scale manufacturing utilization across the Yangtze River Delta and Southeast Asian hubs concentrates cost leadership among crystalline-silicon giants, compressing price floors for standardized modules while preserving premium capture for efficiency-optimized and storage-bundled offerings.
Pricing Analysis
After-sales service revenue from O&M contracts and performance warranties drives lifetime value for module suppliers. The dominant pricing structure operates through long-term power purchase agreements and project-based EPC contracts, with differentiation hinging on module efficiency tier and UL/IEC certification grade. Cost compression in polycrystalline segments is intensifying because of polysilicon feedstock volatility from Xinjiang sourcing. Utility-scale developers exhibit lowest price sensitivity, prioritizing bankability and offtake certainty, while distributed commercial buyers in Southeast Asia show acute sensitivity to upfront capital outlay.
Supply Chain Analysis
Inventory cycles for metallurgical-grade silicon and aluminum framing extend lead times for crystalline-silicon module assembly, compressing working capital flexibility for mid-tier assemblers. Supply concentrates in China, Vietnam, and Malaysia for cell and module manufacturing, with polysilicon refining anchored in Xinjiang and Inner Mongolia. The chain draws from high-purity silicon metal, silver paste for metallization, and aluminum extrusions for framing. Single-source vulnerability in Xinjiang-sourced polysilicon exposes margins to forced-labor scrutiny and energy-cost fluctuations. Distribution runs through regional EPC contractors and independent power producers seeking streamlined procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through domestic-content thresholds and certification requirements creates durable switching costs for established suppliers.
For Market Incumbents: Shield market position through backward integration into polysilicon refining and captive cell production in Southeast Asian hubs to circumvent tariff exposure. Deepen certification investment for bifacial and TOPCon architectures to maintain bankability premium against emerging thin-film challengers. Prioritize channel control via direct EPC partnerships with hyperscale data center operators in Northern Virginia and Singapore. For New Entrants and Emerging Players: Differentiate on agrivoltaics and building-integrated photovoltaic applications where incumbent footprint remains shallow. Target Maharashtra elevated mounting systems and Singapore curtain-wall integration as the most penetrable white-space segments. Pursue a go-to-market angle anchored on low-carbon polysilicon sourcing from Norwegian and French refiners to exploit EU Carbon Border Adjustment first-mover positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors crystalline-silicon specialists with TOPCon cell dominance and utility-scale offtake pipelines over thin-film commodity producers. Long-term viability hinges on storage co-location capabilities and grid-interconnection queue management. Acquisition targets should display module-plus-storage bundling expertise and FERC Order 2023 compliance infrastructure. The signal to watch is bifacial performance warranty claims and albedo modeling disputes that could reshape lender risk appetite.| Strategic Initiative | Industry Significance |
|---|---|
| TOPCon Cell Capacity Buildout | 600W-plus module outputs shrink land requirements for Gujarat and Rajasthan ground-mounted arrays. |
| Solar-Plus-Storage Bundling | IRA investment tax credit eligibility drives Texas ERCOT and California ISO hybrid deployment. |
| Low-Carbon Polysilicon Sourcing | EU F-Gas Regulation and Carbon Border Adjustment favor Norwegian and French refiner partnerships. |
| Agrivoltaics Pilot Expansion | Maharashtra elevated mounting systems unlock agricultural land exclusion from commercial solar development. |
| Building-Integrated Photovoltaic Qualification | Singapore and Dubai high-rise curtain-wall integration displaces conventional facade materials. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interview rounds. Secondary validation drew from EIA generation data, IEA renewable energy reports, FERC interconnection filings, and project development databases tracking gigawatt-scale procurement pipelines. Bottom-up module shipment analysis and top-down capacity utilization modeling were triangulated against utility-scale PPA disclosure trends.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by technology architecture, application type, installation scale tier, and regional regulatory framework. CAGRs were derived from capacity expansion trajectories and offtake contract velocity rather than extrapolated from historical pricing. Forecast inputs included polysilicon spot price volatility, FERC Order 2023 implementation pacing, and IRA investment tax credit utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained IRA policy continuity, stable Xinjiang polysilicon sourcing, and FERC interconnection queue reform would require recalibration. Forecasts reflect documented assumptions regarding module efficiency improvement curves and storage cost decline trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Solar Simulator Market