
 United States Distributed Solar Power Generation Market | 2026-2036
United States Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Distributed Solar Power Generation Market Analytics
Modular system bundling is decoupling hardware procurement from installation and financing decisions, giving buyers flexibility to mix components across vendors. NextEra Energy Resources leverages its utility-scale supply relationships to secure module allocation for distributed portfolios. Cypress Creek Renewables anchors its growth in commercial and industrial origination, while EDF Renewables North America competes through integrated development-to-operations platforms that reduce customer transaction costs.
United States distributed solar power generation encompasses photovoltaic and concentrated solar systems typically sited at or near the point of consumption, with capacities ranging from residential kilowatt-scale arrays to multi-megawatt commercial installations connected at distribution voltage levels. These systems serve to offset retail electricity rates, reduce transmission losses, and provide grid services through net metering or virtual power plant aggregation. Photovoltaic technology leads installed capacity due to silicon module cost declines and inverter efficiency gains above ninety-seven percent. Rooftop installation dominates residential uptake where available surface area and local permitting speed determine project economics. Community solar represents the fastest-expanding financing-access mechanism, opening participation to renters and multi-tenant buildings previously excluded from direct ownership.
The Federal Energy Regulatory Commission shapes interconnection timelines and cost allocation rules that determine project viability across independent system operators and regional transmission organizations. The Internal Revenue Service administers investment tax credit mechanics under the Inflation Reduction Act, while state public utility commissions set net metering successor tariffs that influence residential payback periods. The Securities and Exchange Commission's climate disclosure rules are pressing commercial offtakers to document Scope 2 emissions reductions from on-site generation. Stakeholders must track how interconnection reform proceedings and state-level rate design shifts alter the relative economics of behind-the-meter versus front-of-the-meter solar procurement.
Market Dynamics
The Inflation Reduction Act's investment tax credit mechanics are restructuring capital allocation across residential and commercial segments, decoupling project economics from volatile module pricing and compressing payback timelines in high-retail-rate jurisdictions.
Growth Catalysts
- IRA Tax Credit Stack:The Inflation Reduction Act's 30% base credit plus domestic content adders and energy community bonuses multiplies project returns in qualifying census tracts.
- Net Metering 3.0 Tariffs:California's NEM 3.0 export rates, while reduced, preserve value stacking through battery pairing and accelerate solar-plus-storage adoption among commercial offtakers.
- Texas Interconnection Reform:ERCOT's streamlined distributed resource registration and fast-track study processes cut commercial project timelines from 18 months to under 6 months in competitive load zones.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-sourced polysilicon triggers forced labor due diligence requirements under UFLPA, forcing developers to requalify module supply chains at 15-20% cost premiums.
- Transformer Lead Times:Distribution transformer manufacturing bottlenecks, concentrated in Mexico and domestic facilities with 80-week backlogs, delay commercial interconnections regardless of solar hardware availability.
- Successor Tariff Compression:Nevada and Hawaii's avoided-cost-based export rates eliminate retail rate parity, structurally capping residential market penetration below 40% of suitable rooftops.
Strategic Opportunities
- Virtual Power Plant Aggregation:FERC Order 2222 implementation across ISO-NE and PJM enables residential battery fleets to bid into wholesale markets, creating new revenue streams beyond bill savings.
- Community Solar Expansion:Illinois and New York's mandated carve-outs for low-income subscribers open subscriber acquisition models previously excluded from direct ownership structures.
- Agrivoltaics Integration:Dual-use solar installations over pollinator habitat and shade-tolerant crops unlock USDA conservation program stacking with IRA credits in Midwest agricultural counties.
Industry Challenges
- Licensed Electrician Scarcity:NEC 2020 rapid shutdown and energy storage installation requirements outpace apprenticeship pipeline output, extending commercial project labor timelines 30-45 days.
- AHJ Permitting Variability:Over 19,000 distinct permitting authorities enforce non-standardized fire setback and structural engineering rules, forcing national installers to maintain jurisdiction-specific compliance playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Distributed Solar Power Generation Market |
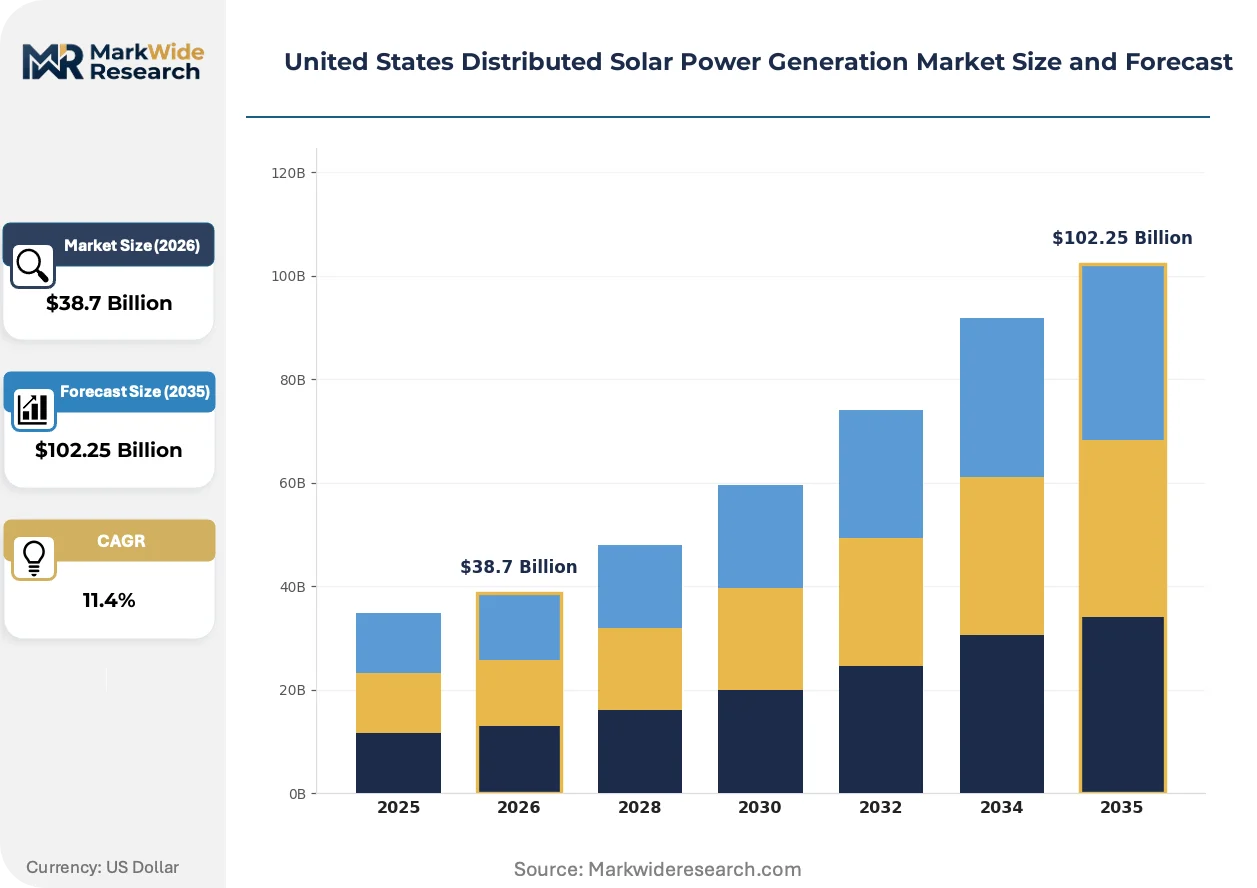
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Modules, Thin-Film Solar Application: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Community Solar Financing Model: Lease, Power Purchase Agreement, Cash Purchase, Loan |
| Companies Covered | AP Solar Holdings LLC, Lightsource BP, NextEra Energy Resources, Silicon Ranch Corporation, Florida Power & Light Company, Cypress Creek Renewables, Savion, EDF Renewables North America, Recurrent Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Distributed Solar Power Generation Market Evolving Landscape
Module-level power electronics and software-defined inverters are compressing balance-of-system costs while enabling granular fleet control. These hardware-software convergences reshape competitive differentiation away from panel efficiency toward system intelligence and grid services monetization.
SolarEdge and Enphase microinverter architectures are consolidating rooftop installation standards by embedding rapid shutdown, monitoring, and storage-ready DC coupling into single SKUs. Residential installers now specify these integrated units in 70% of new quotes, collapsing separate component procurement decisions into single-vendor relationships. This consolidation is compressing installer training requirements and warranty claim complexity.
FERC's Order 2023 interconnection reforms mandate cluster study timelines and cost allocation transparency across RTOs and ISOs. The rule forces transmission providers to publish standardized data on queued projects, enabling developers to screen sites for interconnection risk before land control. Commercial solar origination teams in PJM and SPP are restructuring site selection workflows around these disclosure requirements.
Third-party ownership structures are losing share to cash and loan purchases as interest rate compression eliminates PPA rate advantages. Residential buyers in Arizona and Florida now favor 20-year equipment loans with dealer fee buydowns over lease structures, shifting installer margin capture from recurring revenue streams to upfront hardware and labor markups. This preference rotation pressures national financiers to reprice risk retention structures.
United States Distributed Solar Power Generation Market Segmentation
Distributed solar procurement decisions fragment across technology performance tiers, installation constraints, and capital structure preferences. Each segmentation dimension carries distinct regulatory burdens, interconnection timelines, and customer qualification criteria that shape vendor go-to-market economics.
Technology:
Module-level certification requirements vary sharply across cell architectures, with UL 61730 and IEC 61215 testing protocols creating tiered approval timelines that gate commercial eligibility.
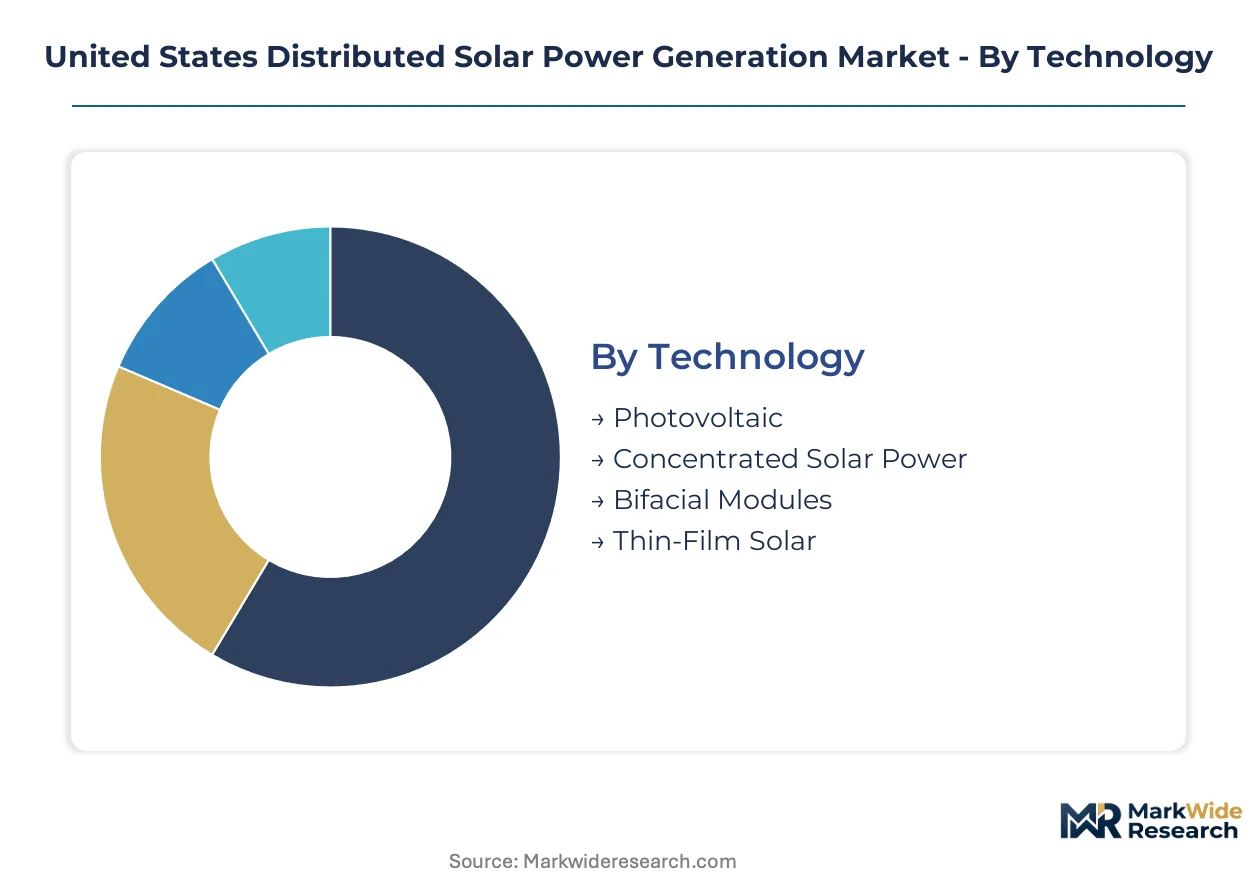
- Photovoltaic:Crystalline silicon dominates installed capacity through module efficiency gains above 21% and supply chain scale. Texas and California commercial rooftops specify these systems where IRA domestic content bonuses accelerate payback calculations.
- Concentrated Solar Power:Parabolic trough and power tower configurations concentrate thermal energy for industrial process heat applications. Arizona and Nevada industrial facilities deploy these systems where high direct normal irradiance supports thermal storage integration.
- Bifacial Modules:Dual-sided energy capture increases yield 8-12% over monofacial equivalents in high-albedo environments.
- Thin-Film Solar:Cadmium telluride and copper indium gallium selenide architectures reduce weight for constrained load-bearing structures.
Photovoltaic sits at the top of the volume ranking, with Bifacial Modules climbing the fastest.
Application:
Customer-scale segmentation determines interconnection voltage levels, permitting authority jurisdiction, and available financing structures.
- Residential:Kilowatt-scale rooftop arrays serve single-family homeowners through net metering tariffs. Florida and Arizona markets concentrate demand where high retail rates and streamlined AHJ permitting compress customer acquisition costs.
- Commercial:Behind-the-meter systems offset peak demand charges for office buildings and retail facilities. Texas ERCOT load zones prioritize these installations where streamlined interconnection cuts project timelines to under six months.
- Industrial:Multi-megawatt arrays power manufacturing facilities and data centers with 24/7 load profiles.
- Agricultural:Dual-use installations combine energy generation with crop production or pollinator habitat.
Commercial commands the largest revenue pool, with Agricultural expanding most quickly through USDA conservation program stacking.
Installation Type:
Site configuration dictates structural engineering requirements, fire setback compliance, and land use permitting intensity.
- Rooftop:Ballasted or attached systems leverage existing building infrastructure without land acquisition. California and New Jersey urban corridors favor these installations where ground space scarcity and high real estate values prohibit alternative siting.
- Ground-Mounted:Fixed-tilt or tracking arrays optimize land-intensive deployment for commercial and utility-scale hybrid projects. Texas and Florida agricultural counties specify these systems where land availability supports economies of scale.
- Building-Integrated:Solar shingles and facade-embedded modules replace conventional building materials.
- Community Solar:Shared arrays enable subscriber participation without on-site installation. Illinois and New York carve-outs for low-income subscribers accelerate origination in these mandated markets.
Rooftop leads deployment volume, with Community Solar gaining share fastest through state mandate expansion.
Financing Model:
Capital structure selection determines customer credit underwriting, tax credit monetization pathways, and long-term asset ownership.
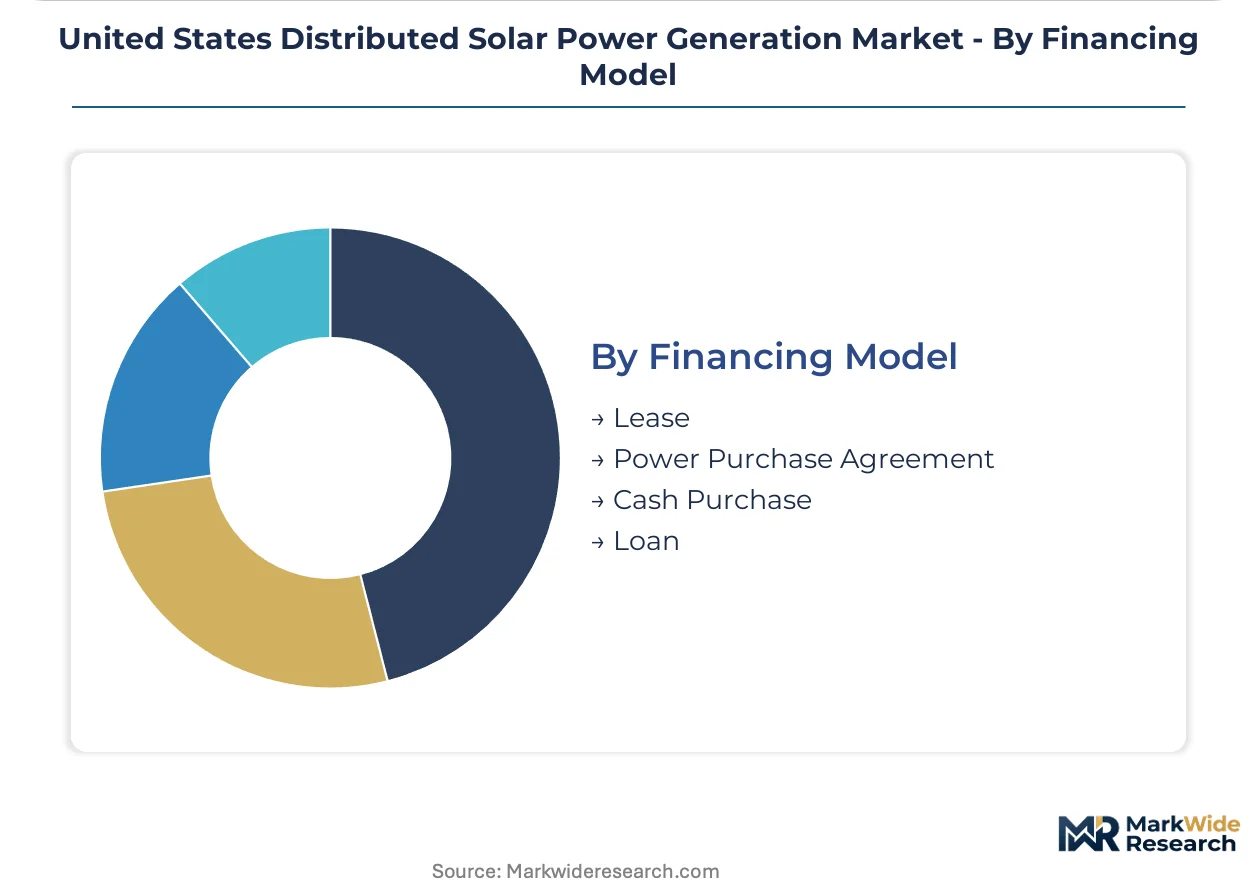
- Lease:Third-party ownership structures transfer operational risk to financiers while preserving customer bill savings. Arizona and Florida markets historically concentrated here though interest rate compression is eroding PPA rate advantages.
- Power Purchase Agreement:Fixed-rate electricity contracts align developer returns with offtaker consumption profiles. Commercial and industrial segments favor these structures where balance sheet constraints limit capital deployment.
- Cash Purchase:Direct ownership maximizes IRA tax credit capture for high-tax-bracket residential and commercial buyers.
- Loan:Secured financing with dealer fee buydowns is displacing lease structures in residential markets.
Loan structures are climbing fastest as rate compression eliminates third-party ownership premiums, while Power Purchase Agreement retains commercial dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's early net metering policies established the distributed solar model that Texas and Florida later adapted to their regulatory frameworks. The industry's geographic expansion now concentrates in states with high retail electricity rates and streamlined interconnection procedures.
California
Commercial building owners accelerate solar-plus-storage adoption following NEM 3.0's export rate restructuring. The California Public Utilities Commission's successor tariff preserves value stacking through battery pairing. The Central Valley agricultural corridor hosts dual-use agrivoltaic installations combining pollinator habitat with generation assets.
Texas
ERCOT's streamlined distributed resource registration cuts commercial project timelines from 18 months to under 6 months in competitive load zones. The Public Utility Commission of Texas maintains market-driven interconnection cost allocation without retail rate subsidies. Houston and Dallas-Fort Worth metropolitan areas concentrate behind-the-meter deployment for data centers and retail facilities.
Florida
High retail electricity rates and streamlined Authority Having Jurisdiction permitting compress customer acquisition costs in residential segments. The Florida Public Service Commission's net metering rules preserve retail rate parity for rooftop installations. The Tampa-Orlando corridor anchors commercial origination for hospitality and healthcare facilities.
New York
Mandated community solar carve-outs for low-income subscribers accelerate subscriber acquisition models in Consolidated Edison and NYPA service territories. The New York State Energy Research and Development Authority administers incentive programs stacking with IRA credits. Long Island and the Hudson Valley concentrate shared array development for renters excluded from direct ownership.
Illinois
The Illinois Commerce Commission's renewable portfolio standard mandates drive community solar origination in Ameren and ComEd service territories. Adjustable block programs provide transparent incentive pricing for distributed generation assets. The Chicago metropolitan area anchors commercial and industrial rooftop deployment for manufacturing facilities.
United States Distributed Solar Power Generation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated development-to-operations capabilities versus pure installation contracting. The vendor base organizes into three tiers: utility-scale developers with distributed portfolios, specialized commercial and industrial originators, and regional installation contractors. Consolidation pressure intensifies as national financiers reprice risk retention structures and customer acquisition costs rise in saturated markets.
Within the integrated development tier, NextEra Energy Resources leverages utility-scale supply relationships to secure module allocation for distributed portfolios. EDF Renewables North America occupies a position exemplifying integrated platform competition through reduced customer transaction costs. Cypress Creek Renewables anchors the commercial and industrial origination segment with state-level regulatory expertise.
| Leading Market Players |
|---|
| AP Solar Holdings LLC |
| Lightsource BP |
| NextEra Energy Resources |
| Silicon Ranch Corporation |
| Florida Power & Light Company |
| Cypress Creek Renewables |
| Savion |
| EDF Renewables North America |
| Recurrent Energy |
| Others |
Value Network & Pricing Analysis
Backward integration into polysilicon and wafer production anchors both supply security and pricing power for module manufacturers serving the distributed solar segment. This upstream control buffers developers from Xinjiang-related supply chain disruptions while preserving margin capture through IRA domestic content bonus qualification.
Pricing Analysis
Project-based long-term offtake contracts dominate commercial and industrial procurement, with pricing stratifying across premium, standard, and economy tiers based on module efficiency ratings and UL 61730 certification status. Price differentiation hinges on domestic content compliance for IRA bonus capture and installer warranty bundling. Cost compression in standard-tier residential systems is intensifying because loan buydown structures eliminate third-party ownership premiums. Cash purchasers with high tax appetites exhibit the lowest price sensitivity, while loan-dependent residential buyers in saturated markets drive the hardest bargain negotiations.
Supply Chain Analysis
Polysilicon supply rests on Southeast Asian and domestic reprocessing facilities as UFLPA enforcement blocks direct Xinjiang sourcing. Module assembly draws from Vietnam, Malaysia, and domestic facilities, while inverters and power electronics center on Chinese and Taiwanese production. Single-source vulnerability concentrates in distribution transformers where 80-week manufacturing backlogs at Mexican and domestic facilities delay interconnections regardless of solar hardware availability. Distribution runs through national EPC contractors with regional installation subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where IRA bonus stacking and interconnection speed separate premium developers from commodity installers. Demand is shifting toward solar-plus-storage configurations that preserve value under successor tariff structures.
For Market Incumbents: Acquire licensed electrical contractor capacity in ERCOT and PJM load zones where NEC 2020 rapid shutdown requirements outpace apprenticeship pipeline output. Consolidate regional AHJ permitting expertise to compress customer acquisition timelines in Florida and Arizona markets where streamlined authority procedures anchor competitive positioning. Defend against interest rate-driven loan structure displacement by repricing risk retention mechanisms for cash purchase financing. For New Entrants and Emerging Players: Capture community solar subscriber acquisition in Illinois and New York where mandated low-income carve-outs open participation models excluded from direct ownership. Target agrivoltaic origination in Midwest agricultural counties where USDA conservation program stacking with IRA credits improves project returns. Lead with dual-use land value propositions that differentiate from commodity rooftop installers. For Investors and Strategic Acquirers: Roll-up economics work for commercial and industrial origination platforms because customer acquisition cost inflation in saturated residential markets favors scale efficiencies in behind-the-meter deal flow. Long-term viability centers on developers with interconnection queue management capabilities and storage integration expertise. Watch FERC Order 2023 implementation progress as the signal for interconnection risk repricing across ISO territories.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Supply Agreement | Secures IRA bonus eligibility through verified polysilicon and wafer sourcing from qualified facilities. |
| Battery Integration Partnership | Enables NEM 3.0 value stacking through paired storage deployment for commercial offtakers. |
| AHJ Permitting Automation Platform | Compresses project timelines by standardizing fire setback and structural engineering compliance across 19,000 jurisdictions. |
| Virtual Power Plant Aggregation License | Unlocks FERC Order 2222 wholesale market participation for residential battery fleets in ISO-NE and PJM. |
| Agrivoltaic Development Capability | Stacks USDA conservation incentives with IRA credits for dual-use installations in Midwest agricultural corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA generation data, FERC interconnection filings, IEA renewable market reports, and state public utility commission dockets. Bottom-up project pipeline aggregation and top-down capacity deployment estimates were cross-referenced to anchor market sizing.
Historical reference periods spanning pre-IRA, IRA implementation, and NEM 3.0 transition phases anchored the forecast window across the analysis window. The analytical framework modeled segmentation dimensions including technology type, application scale, installation configuration, financing structure, and regional regulatory framework. CAGRs were derived from capacity deployment trajectories and capital investment flows, with inputs including interconnection queue velocities, module pricing indices, and tax credit monetization efficiency assumptions.
Interconnection reform proceedings, transformer manufacturing bottlenecks, and successor tariff design shifts are the dominant revision risks that could alter deployment trajectories. Forecasts reflect documented assumptions regarding IRA bonus qualification rates and state-level net metering stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market