
 Global Rooftop Solar Photovoltaic Market | 2026-2036
Global Rooftop Solar Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rooftop Solar Photovoltaic Market Outlook
Module efficiency tiering above 21% is collapsing the cost-per-watt gap between premium monocrystalline and legacy polycrystalline offerings. LONGi Solar leverages vertical integration from polysilicon to module assembly to sustain margin capture across high-efficiency product lines. JinkoSolar anchors its position through Tiger Neo n-type cell technology leadership, while Trina Solar competes via Vertex platform scale and distributed installer channel density.
Rooftop solar photovoltaic systems comprise electrically interconnected solar modules, inverters, mounting structures, and balance-of-system components designed to convert incident solar irradiance into grid-synchronous alternating current, typically operating at system voltages between 600V and 1500V depending on configuration scale. These installations serve on-site electricity generation for behind-the-meter consumption or grid-export revenue streams across residential, commercial, and industrial building stock. Bifacial module penetration is accelerating fastest among commercial applications where elevated roof surfaces and reflective substrates enhance rear-side energy yield capture. Residential segment growth concentrates in homeowner-financed systems where third-party ownership structures face regulatory headwinds in multiple jurisdictions. Thin-film technology occupies niche positions in building-integrated configurations where weight constraints and aesthetic integration requirements override efficiency optimization.
US IRA investment tax credit provisions, EU Green Deal building renovation mandates, and India's MNRE rooftop solar programme collectively reshape demand trajectories and product certification requirements across major deployment corridors. EMA grid connection standards and IEC 61215/61730 module qualification protocols define minimum performance and safety thresholds that gate market access for component suppliers. Stakeholders must monitor evolving distribution network capacity allocation rules and dynamic tariff restructuring as these mechanisms determine project viability more decisively than module cost curves alone.
Market Dynamics
Feed-in tariff recalibration across major deployment corridors is compressing project payback periods and accelerating capital rotation into distributed generation assets. This policy-driven repricing is restructuring installer economics and module procurement patterns.
Growth Catalysts
- Net Metering Mandates:India's CEA mandates in industrial corridor states compel DISCOMs to offer grid export credits, unlocking behind-the-meter deployment at scale for factories and warehouses.
- Building Renovation Directives:EU Green Deal mandates require member states to install solar on public and commercial buildings during major renovations, creating a regulatory floor for demand.
- N-Type Cell Migration:Tunnel oxide passivated contact architectures are displacing PERC dominance in rooftop applications where high-temperature coefficient performance justifies module premiums.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-origin material faces import restrictions under US UFLPA and EU forced labor due diligence rules, fragmenting supply access by geography.
- Distribution Network Capacity:Rural substations in emerging markets lack reverse power flow infrastructure, capping penetration in agriculturally zoned areas despite irradiance abundance.
- Interconnection Queues:Utility approval timelines for commercial systems stretch 12-18 months in jurisdictions with understaffed grid planning departments, freezing capital deployment.
Strategic Opportunities
- Agrisolar Convergence:Elevated tracking arrays over shade-tolerant crops unlock dual revenue streams for landowners in Spain, Italy, and Greece where rural land values support capital deployment.
- Third-Party Ownership Pivot:Community solar subscription models bypass rooftop suitability constraints for renters and multi-tenant buildings in US states with virtual net metering statutes.
- Battery Coupling Mandates:California's NEM 3.0 export rate collapse is forcing storage attachment to preserve project economics, creating integrated system demand.
Industry Challenges
- Skilled Installer Scarcity:NABCEP-certified technicians remain concentrated in coastal US markets and Western European capitals, constraining deployment velocity in secondary cities.
- Module Recycling Infrastructure:End-of-life PV waste streams lack scaled processing capacity under EU WEEE directives, exposing asset owners to future liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rooftop Solar Photovoltaic Market |
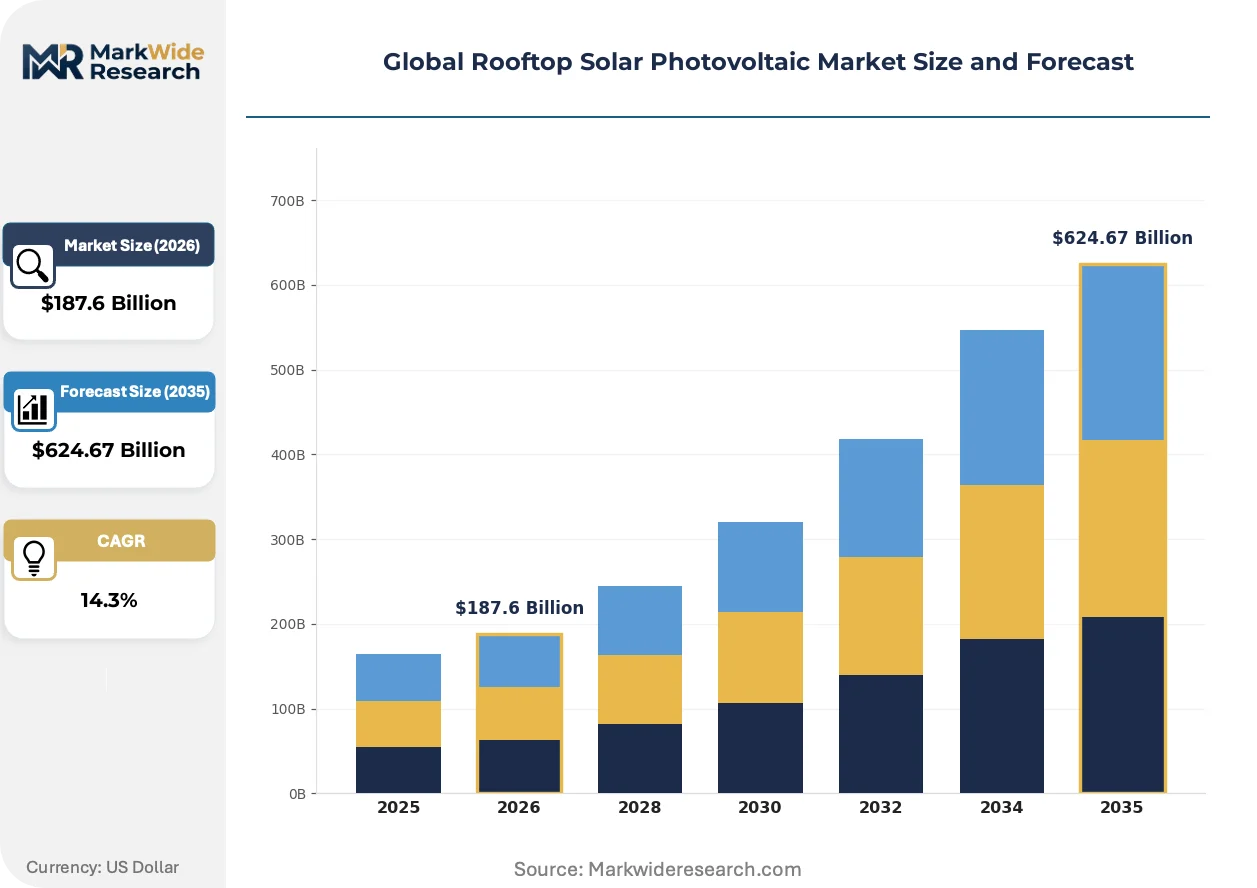
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Government Installation Type: Roof-Mounted, Ground-Mounted, Building-Integrated, Off-Grid End User: Homeowners, Businesses, Utilities, Non-Profits |
| Companies Covered | First Solar, Canadian Solar Inc., JinkoSolar, Trina Solar, SunPower Corporation, JA Solar, LONGi Solar, Hanwha Q CELLS, Tata Power Solar Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rooftop Solar Photovoltaic Market Strategic Shifts
Module form factor standardization and inverter topology evolution are converging to reduce balance-of-system costs and accelerate design-to-installation cycles across distributed project scales.
Bifacial glass-glass modules are decomposing the traditional front-side-only energy yield model in commercial rooftop applications. Warehouse operators with white TPO membranes are capturing 8-12% rear-side gain, compressing levelized cost calculations against single-sided alternatives. This bifacial penetration is forcing EPCs to revise structural load assessments and mounting system specifications.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon refrigerant adoption in heat pump-solar hybrid systems. Building owners pursuing combined electrification retrofits face consolidated compliance pathways under EPBD renovation passports. German KfW promotional loans now require integrated PV-thermal system designs for deep renovation subsidies.
Direct-to-consumer digital platforms are displacing traditional lead-generation intermediaries in residential segment customer acquisition. Homeowners in Australia and the Netherlands now configure system specifications through AI-assisted design tools before installer contact. This channel compression is eroding regional installer margins while concentrating volume with vertically integrated manufacturers operating proprietary sales portals.
Global Rooftop Solar Photovoltaic Market Segmentation
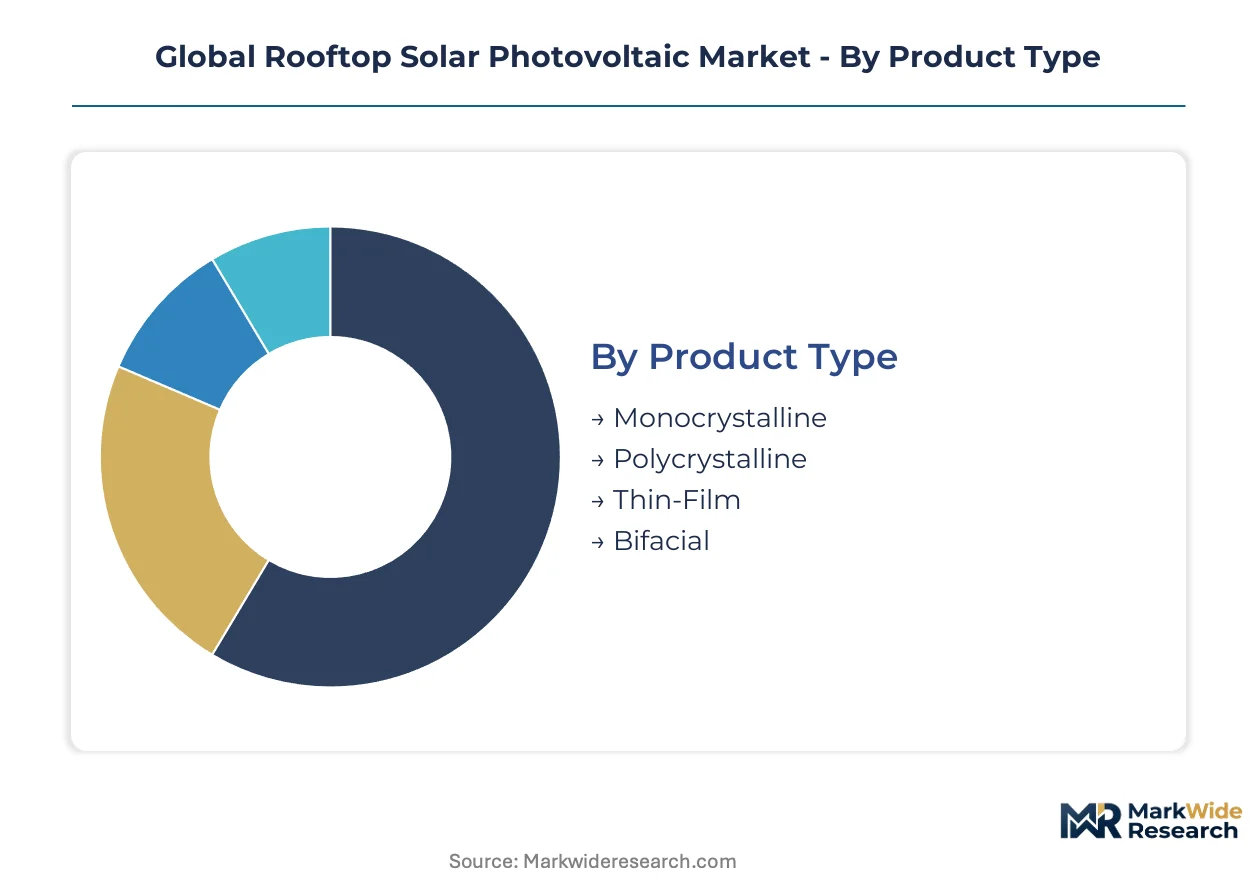
Rooftop solar procurement patterns diverge sharply across product architectures and installation contexts. Technology selection hinges on roof geometry constraints, local irradiance profiles, and regulatory incentive structures rather than module cost alone.
Product Type:
Monocrystalline and bifacial modules dominate export-led demand from Chinese manufacturers, while polycrystalline retains domestic share in price-sensitive emerging markets. Thin-film supply concentrates with First Solar's Ohio production for US utility-scale offtake.
- Monocrystalline:PERC and TOPCon cell architectures deliver conversion efficiencies above 21% in standard test conditions. Factories across India's Maharashtra and Gujarat industrial corridors specify monocrystalline systems to maximize generation density on constrained roof footprints under state-level net metering mandates.
- Bifacial:Dual-glass construction captures rear-side irradiance reflected from TPO membrane and metal roofing substrates. Warehouse operators in Germany's logistics belt and California's Inland Empire deploy bifacial arrays to achieve 8-12% energy yield premiums over monofacial equivalents.
- Polycrystalline:Legacy multi-crystalline technology maintains cost advantage in residential retrofit markets where efficiency premiums cannot be monetized.
- Thin-Film:Cadmium-telluride and CIGS technologies serve building-integrated applications where weight limits and aesthetic integration override efficiency optimization.
Monocrystalline commands the established base. The steepest expansion runs through bifacial technology.
Application:
Commercial installations generate the highest unit margins for EPCs due to standardized roof geometries and streamlined permitting. Industrial segment procurement concentrates in manufacturing clusters with 24/7 load profiles that maximize behind-the-meter consumption value.
- Commercial:Retail chains, logistics facilities, and office buildings deploy rooftop systems to offset retail electricity tariffs. IKEA's global property portfolio and Amazon's fulfillment center network anchor commercial segment volume across multiple jurisdictions.
- Industrial:Heavy manufacturing and cold storage facilities combine high baseload demand with expansive flat roof inventory. Textile mills in Bangladesh's Export Processing Zones and automotive suppliers in Mexico's Bajío region drive industrial procurement.
- Residential:Single-family homeowner adoption accelerates where third-party ownership models remain viable under prevailing net metering regimes.
- Government:Public building mandates under EU Green Deal renovation directives and India's solarization programs for government facilities create regulatory floor demand.
Commercial applications anchor installer profitability. Industrial deployment is gaining share fastest as manufacturing reshoring elevates facility electricity cost sensitivity.
Installation Type:
Roof-mounted systems capture the majority of distributed generation capacity additions. Building-integrated configurations command design premiums in urban core markets where preservation requirements restrict conventional panel aesthetics.
- Roof-Mounted:Conventional rack-mounted arrays on pitched or flat commercial roofs constitute the dominant installation topology. Racking system standardization around 1.0m and 1.1m module widths reduces balance-of-system engineering costs.
- Building-Integrated:Solar tiles, facade cladding, and skylight-integrated cells substitute conventional building materials. Dutch and Belgian residential markets show elevated building-integrated penetration due to strict heritage district planning codes.
- Ground-Mounted:Elevated canopy structures over parking lots and agricultural operations enable dual land use where rooftop area proves insufficient.
- Off-Grid:Battery-coupled standalone systems serve remote telecommunications infrastructure and rural electrification programs beyond distribution network reach.
Roof-mounted configurations represent the volume base. Building-integrated installations are expanding most quickly as architectural integration requirements proliferate in dense urban markets.
End User:
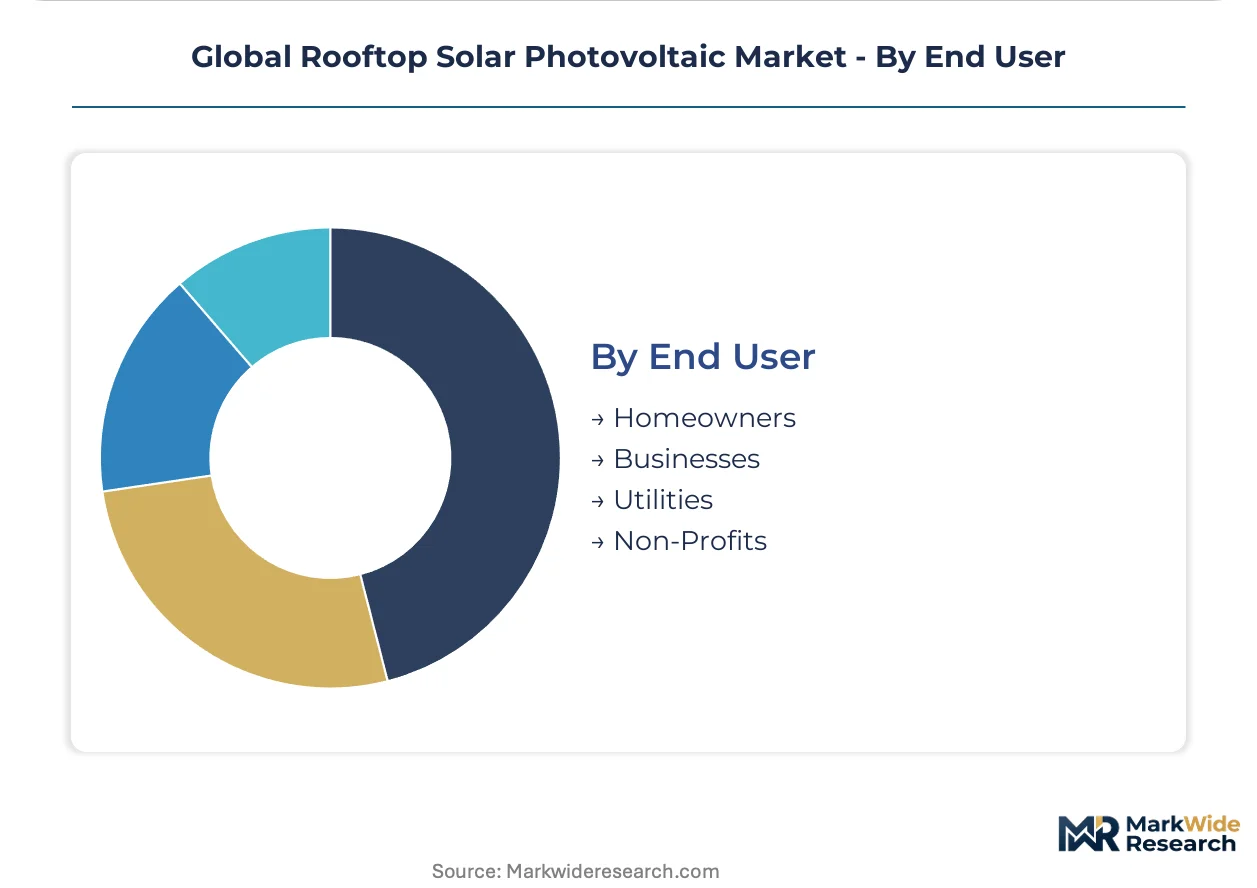
Business procurement decisions emphasize power purchase agreement structures and tax equity monetization. Homeowner adoption depends on financing availability and net metering compensation rates that vary by utility service territory.
- Businesses:Corporate sustainability commitments and electricity cost hedging motivate commercial and industrial offtake. RE100 member companies specify rooftop solar in facility lease requirements across their global real estate portfolios.
- Utilities:Distribution utilities deploy rooftop systems as non-wires alternatives to substation upgrades in load growth corridors. Arizona Public Service and Consolidated Edison operate utility-owned distributed solar programs.
- Homeowners:Residential adoption concentrates in high-retail-rate jurisdictions where solar levelized cost undercuts grid supply. California, Australia, and Germany anchor homeowner demand.
- Non-Profits:Schools, houses of worship, and community organizations access rooftop solar through specialized financing vehicles that monetize tax credits via third-party ownership structures.
Businesses anchor procurement scale. Utility-led distributed programs are climbing the fastest as grid planners prioritize non-wires solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese module exports dominate supply flows into Europe and Asia-Pacific markets, while domestic manufacturing incentives in India and the United States reshape import dependency patterns across major deployment corridors.
United States
California's NEM 3.0 export rate collapse is forcing storage-coupled system designs to preserve project economics. The IRA investment tax credit provisions anchor federal policy support. Texas and Florida industrial corridors are driving commercial deployment velocity as load growth outpaces transmission buildout.
Germany
Building renovation mandates under the EU Green Deal require solar installation during major commercial retrofits. KfW promotional loans now mandate integrated PV-thermal designs for deep renovation subsidies. The logistics belt around Leipzig and Dresden anchors bifacial warehouse deployment.
India
State-level net metering mandates in Maharashtra and Gujarat compel DISCOMs to offer grid export credits for industrial facilities. The MNRE rooftop solar programme creates regulatory floor demand. Textile mills across Tamil Nadu's Coimbatore cluster are specifying high-density monocrystalline systems.
Australia
Homeowner-financed systems dominate as third-party ownership structures face regulatory constraints. Digital direct-to-consumer platforms are compressing traditional installer lead-generation channels. Queensland and New South Wales residential markets show elevated bifacial penetration on elevated roof structures.
Japan
Feed-in tariff recalibration is compressing commercial project payback periods and accelerating capital rotation. METI grid connection standards define performance thresholds for module qualification. Osaka-Kobe industrial zones are driving warehouse rooftop deployment for manufacturing reshoring facilities.
Global Rooftop Solar Photovoltaic Market Competitive Environment
Concentration sits with vertically integrated Chinese manufacturers who control polysilicon supply through module assembly. The vendor base stratifies across three tiers: scale-driven volume leaders, technology specialists in n-type cell architectures, and regional EPC-integrated assemblers. Competitive moves center on backward integration into wafer and cell capacity, plus geographic diversification of manufacturing footprints to circumvent trade restrictions.
Among the integrated tier, LONGi Solar exemplifies upstream control from polysilicon through module assembly, while JinkoSolar anchors technology positioning through n-type cell specialization. Trina Solar represents scale-driven channel density in distributed installer networks. These three occupy positions that define competitive archetypes: captive supply security, performance tier leadership, and route-to-market saturation respectively.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar Inc. |
| JinkoSolar |
| Trina Solar |
| SunPower Corporation |
| JA Solar |
| LONGi Solar |
| Hanwha Q CELLS |
| Tata Power Solar Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization above 85% at Southeast Asian cell fabs is compressing module spot prices while concentrating procurement leverage with tier-one manufacturers. This scale concentration is simultaneously eroding margin buffers for second-tier assemblers and establishing price floors that resist further polysilicon cost declines.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across commercial rooftop deployments. Pricing stratifies across premium, standard, and economy tiers based on module efficiency certification and volume scale commitments. Cost compression in standard-tier monocrystalline modules is intensifying because Chinese capacity additions outpace demand absorption in European corridors. Residential homeowners exhibit highest price sensitivity, while utility-scale offtakers prioritize performance guarantees over per-watt economics.
Supply Chain Analysis
Just-in-time inventory preferences dominate module procurement for commercial EPCs with firm installation schedules, while strategic polysilicon stockpiling characterizes vertically integrated manufacturers hedging Xinjiang-origin material restrictions. Geographic supply concentration centers on China, Vietnam, and Malaysia for cell and module assembly. Raw material dependencies rest on metallurgical-grade silicon, silver paste, and aluminum frames. Single-source vulnerability around Xinjiang polysilicon feeds tariff exposure under US UFLPA enforcement. Distribution runs through authorized distributor networks and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Rooftop Solar Photovoltaic Market is cycling through a capital redeployment phase as feed-in tariff recalibration and IRA tax equity absorption reshape project finance structures.
For Market Incumbents: Fortify upstream control over wafer and cell capacity to defend margin capture against emerging n-type specialists. Secure IEC 61730 certification portfolios ahead of EU market access tightening. Prioritize installer channel density in Texas and Florida load growth corridors where interconnection queue delays create captive demand capture. For New Entrants and Emerging Players: UL 1703 certification fast-track enables market entry into California's storage-coupled retrofit wave. Target building-integrated configurations in Dutch and Belgian heritage districts where aesthetic compliance barriers limit incumbent competition. Pursue agrisolar canopy structures in Spain and Italy where dual land use economics bypass rooftop suitability constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EPCs with proprietary O&M service contracts and performance guarantee structures. Long-term viability over a multi-year window favors acquisition targets with captive installer networks and storage integration capabilities. Monitor California NEM 4.0 proposal timelines as the inflection signal for distributed solar valuation reset.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive supply security mitigates UFLPA exposure and secures margin capture across high-efficiency product lines. |
| N-Type Cell Capacity Buildout | Tunnel oxide passivated contact migration displaces PERC dominance in premium rooftop applications. |
| Storage Coupling Certification | California NEM 3.0 compliance preserves project economics through battery attachment mandates. |
| Installer Network Acquisition | Route-to-market density concentrates volume with vertically integrated manufacturers operating proprietary sales portals. |
| Agrisolar Development Partnership | Elevated tracking arrays over shade-tolerant crops unlock dual revenue streams in Mediterranean rural corridors. |
Study Parameters
The analysis maps monocrystalline, bifacial, polycrystalline, and thin-film technology sub-sectors, each validated through EPC contractors, utility planning officers, and module procurement leads at industrial offtakers. Primary interviews with grid operators and inverter system integrators combined with secondary validation against FERC interconnection filings, EIA capacity data, IEA deployment reports, and IEC certification registries. Bottom-up project pipeline aggregation triangulates against top-down manufacturer shipment disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology type, application segment, installation topology, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from unit shipment trajectories and average selling price evolution. Industry-specific forecast inputs incorporate interconnection queue timelines and net metering compensation rate restructuring.
Decision-makers should treat outputs as directional under prevailing IRA tax credit extension and EU Green Deal mandate assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case scenarios for polysilicon supply access and distribution network capacity allocation. Revision becomes warranted when tariff enforcement intensity or grid connection standard modifications cross thresholds that alter project viability calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Global Photovoltaic Market