
 Global Solar Panel Materials Market | 2026-2036
Global Solar Panel Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Panel Materials Market Analysis
The EU Green Deal is expanding compliance obligations for embodied carbon in solar imports, forcing module suppliers to document supply-chain emissions. LONGi Green Energy leverages integrated polysilicon-to-module operations to meet traceability mandates. JinkoSolar anchors its competitiveness through PERC and TOPCon cell architectures with industry-leading conversion efficiencies. First Solar differentiates via its proprietary Cadmium Telluride thin-film technology, which sidesteps silicon supply constraints entirely.
Solar panel materials encompass the semiconducting, conductive, and encapsulant substances that convert photons into direct-current electricity, with crystalline silicon wafers typically doped to achieve resistivity below 1 ohm-cm and laminated between ethylene-vinyl acetate sheets for decades of weather resistance. Silicon remains the dominant material type by installed capacity, though heterojunction production methods are gaining share as manufacturers pursue higher open-circuit voltages. Thin film deposition techniques sustain niche positions in utility-scale applications where temperature coefficients and shading tolerance outweigh efficiency premiums.
The EPA enforces hazardous substance rules for cadmium-containing thin-film modules, while China's MIIT sets national efficiency benchmarks through GB standards that phase out legacy cell technologies. India's BIS certification mandates and the EU's F-Gas Regulation on fluorinated greenhouse gases constrain fluoropolymer backsheet formulations. Stakeholders must track how divergent carbon-border adjustment mechanisms and local-content incentives reshape procurement geography and technology selection.
Market Dynamics
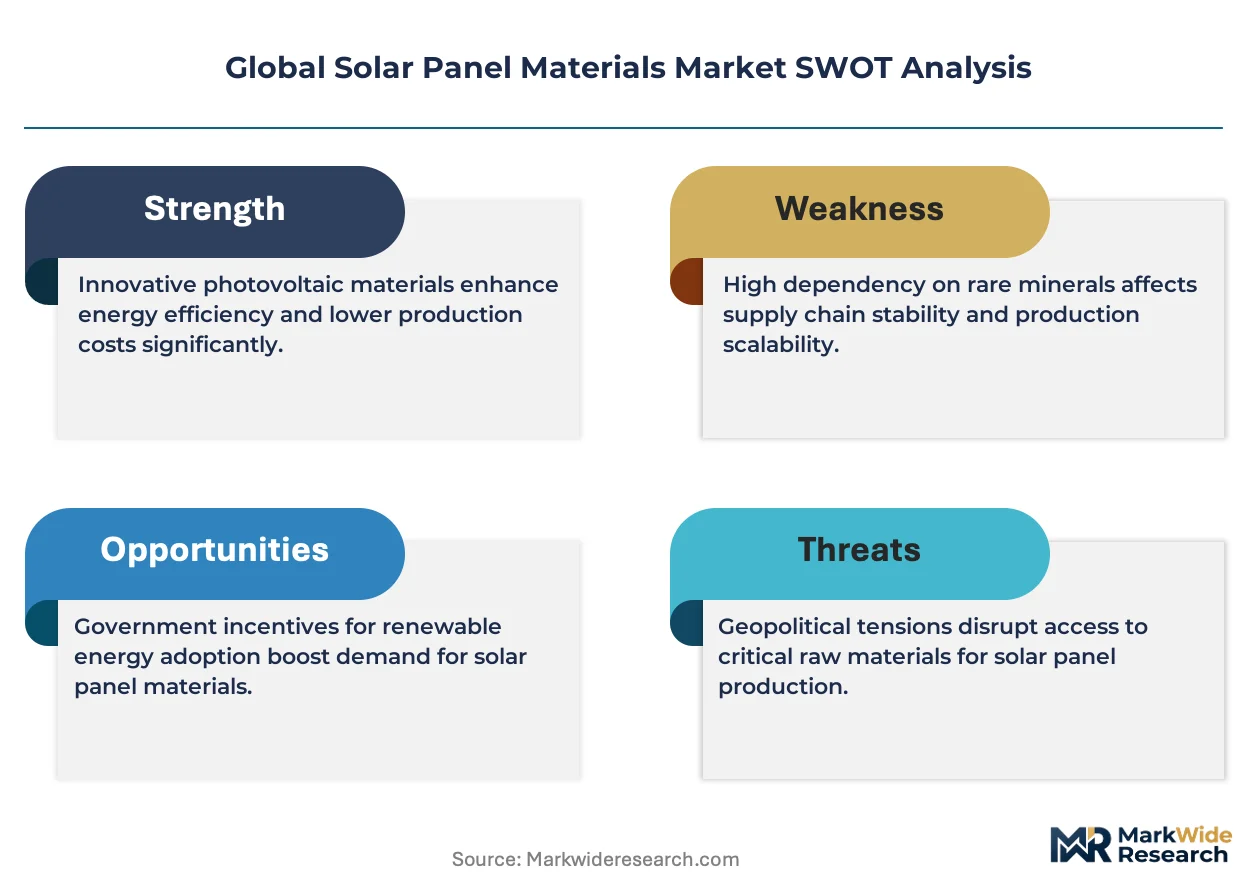
Cell architecture migration from PERC to TOPCon and heterojunction is compressing polysilicon purity requirements while expanding silver paste consumption patterns. This technical transition concentrates procurement leverage among wafer manufacturers with captive metallization capabilities.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Module suppliers must document supply-chain emissions, creating certified product premiums for traceable polysilicon sources.
- Utility-scale procurement acceleration:Developers in India and Brazil are locking multi-year supply agreements for high-efficiency cell materials under national renewable portfolio standards.
- Fluoropolymer backsheet substitution:The EU F-Gas Regulation is accelerating PET-based and co-extruded backsheet adoption, reshaping encapsulant demand toward POE resins.
Market Restraints
- Polysilicon supply concentration:China's Xinjiang and Inner Mongolia regions control over 80% of metallurgical-grade silicon refining, exposing buyers to logistics bottlenecks and trade policy volatility.
- Silver paste cost exposure:Metallization pastes represent 10-15% of cell manufacturing costs, with silver price volatility directly compressing margins at PERC and TOPCon lines.
- Cadmium regulatory friction:The EPA's hazardous substance rules for thin-film modules impose end-of-life recycling liabilities that constrain CdTe technology deployment in distributed residential segments.
Strategic Opportunities
- Brazil distributed generation underperformance:Net metering policies in Minas Gerais and São Paulo states are unlocking residential and commercial rooftop demand for imported high-efficiency modules.
- India PLI scheme localization:Production-linked incentives for polysilicon-to-module manufacturing are attracting greenfield investments in Gujarat and Tamil Nadu.
- Building-integrated photovoltaics convergence:Architectural glass and solar cell lamination technologies are merging, opening premium pricing in commercial facade retrofits across Germany and the Netherlands.
Industry Challenges
- Cell metallization skill scarcity:Screen printing and laser doping technicians command wage premiums as TOPCon and heterojunction lines require finer line-width control than legacy PERC equipment.
- Dual certification timeline compression:India's BIS certification and the EU's CBAM documentation requirements are extending product qualification cycles by 4-6 months for new module suppliers.
- Wafer thinning integration complexity:Sub-130 micron wafer handling demands vacuum gripper and edge-reinforcement equipment retrofits that disrupt existing cell line throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Panel Materials Market |
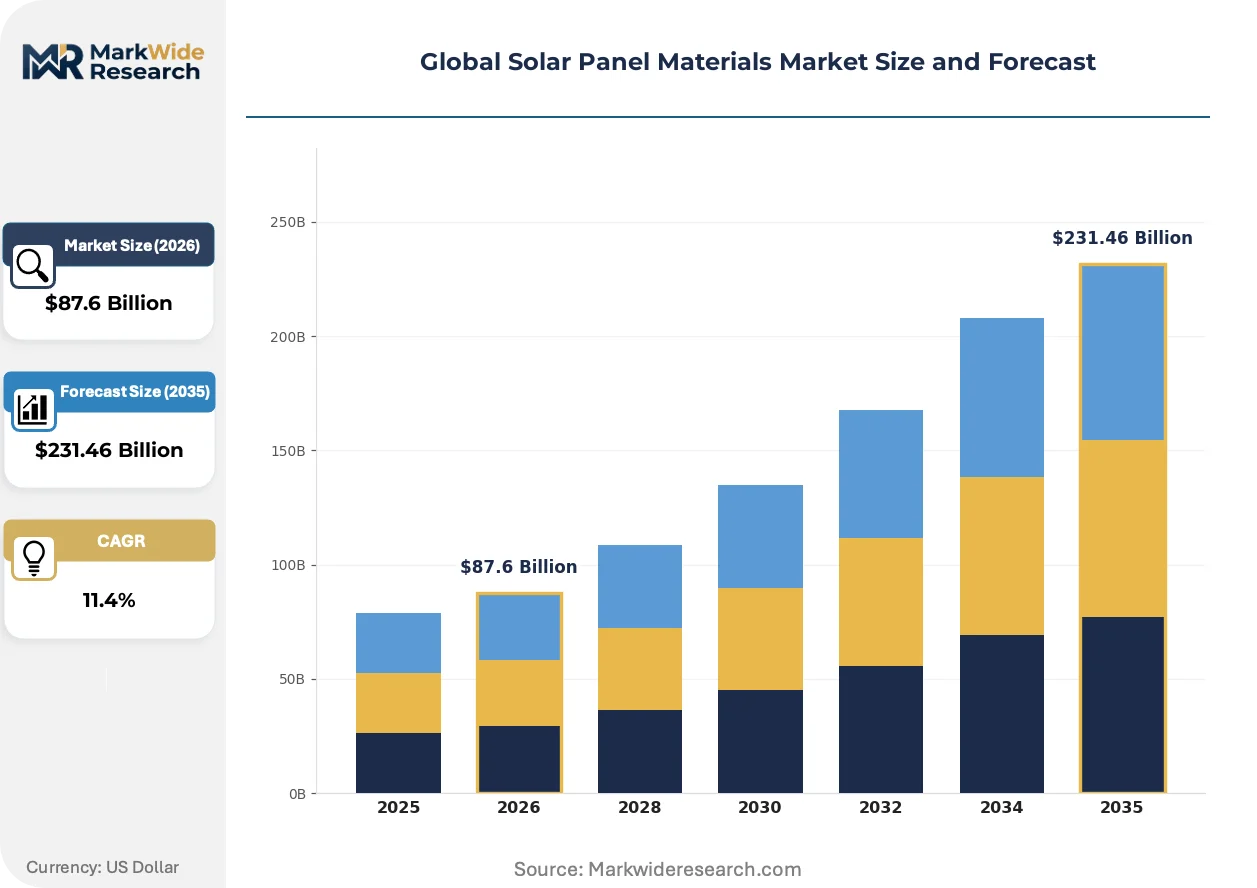
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon, Cadmium Telluride, Copper Indium Gallium Selenide, Organic Photovoltaics Application: Residential, Commercial, Utility Scale, Off-Grid Production Method: C-Si Production, Thin Film Deposition, Printing Technology, Heterojunction Technology End User: Energy Suppliers, Manufacturers, Installers, Research Institutions |
| Companies Covered | LONGi Green Energy, JinkoSolar, JA Solar, Trina Solar, Tongwei Solar, Canadian Solar, First Solar, Xinyi Solar Holdings, Aiko Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Panel Materials Market Emerging Trajectories
Heterojunction cell architectures and copper metallization are redistributing competitive advantage away from silver-dependent incumbents. These shifts compress cost structures while expanding efficiency ceilings for new manufacturing entrants.
Copper-plated cell metallization is decentralizing supply chain risk for silver-intensive manufacturers. LONGi Green Energy and REC Group are piloting light-induced plating lines that eliminate screen-printed silver fingers entirely. This technology is decentralizing procurement leverage from silver traders toward equipment suppliers with proprietary plating chemistry IP.
China's MIIT GB standards are phasing out legacy aluminum-back surface field cell technologies below 21% efficiency. Domestic module manufacturers must retool lines or exit subsidy-eligible procurement pools. Jiangsu and Anhui province facilities are responding fastest due to concentrated equipment supplier ecosystems in Suzhou and Hefei.
Long-term power purchase agreements are displacing spot market module procurement among European utility-scale developers. Aggregators in Germany and Spain are bundling 10-15 year offtake contracts with module supply guarantees, compressing developer working capital requirements. This pattern is most visible in subsidy-free solar parks in southern Spain where merchant price exposure drove initial risk aversion.
Global Solar Panel Materials Market Segmentation
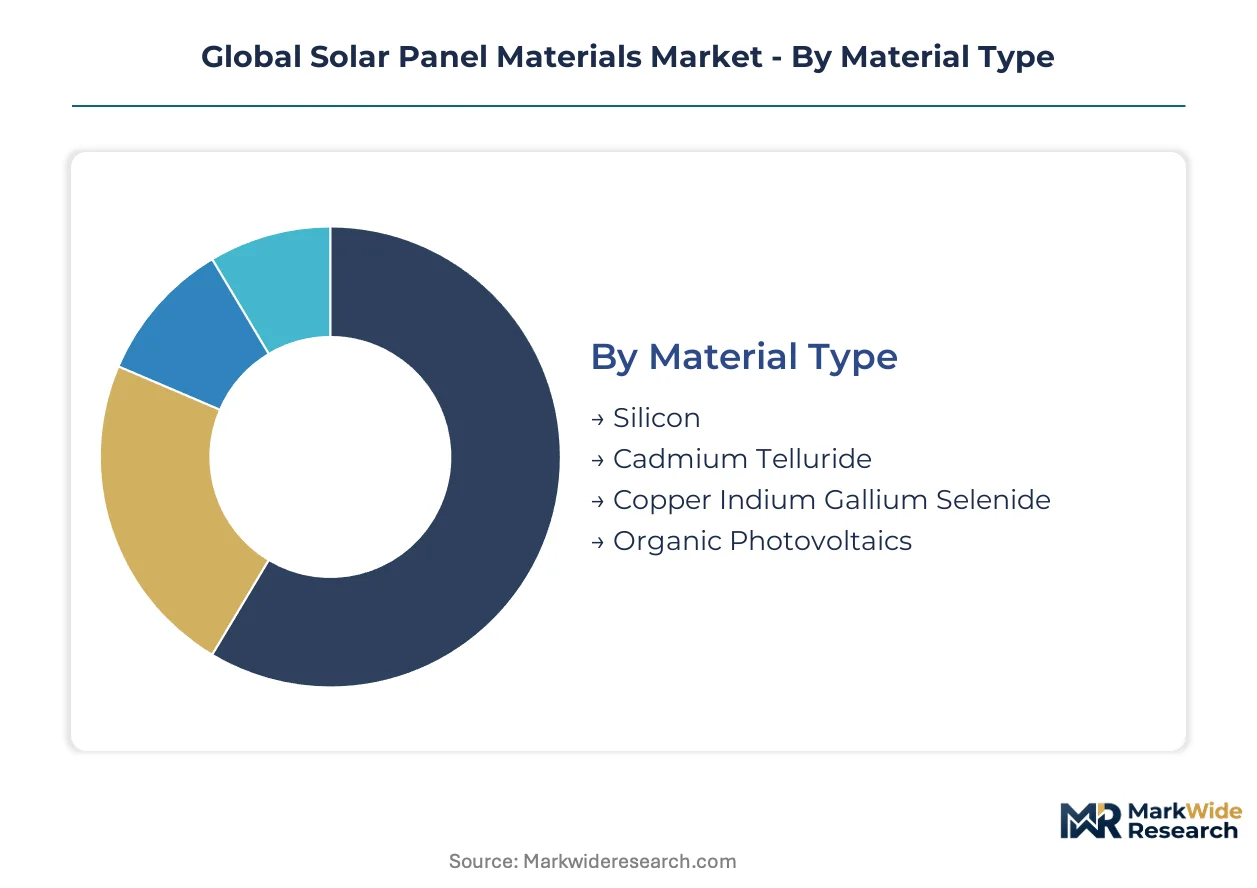
Technology differentiation across material architectures and production methods determines procurement economics and regulatory compliance pathways for module suppliers. Segmentation reveals where efficiency premiums concentrate versus where cost minimization dominates purchasing decisions.
Material Type:
Technical specifications around bandgap engineering and carrier mobility separate commodity supply from premium tier positioning.
- Silicon:Crystalline silicon wafers doped with phosphorus or boron achieve resistivity below 1 ohm-cm for optimal charge carrier transport. Demand clusters in China's Jiangsu and Anhui provinces where polysilicon refining and wafer slicing capacity co-locate, driven by the MIIT's GB efficiency standards phasing out sub-21% cell architectures.
- Cadmium Telluride:Thin-film CdTe layers deposited via vapor transport onto glass substrates deliver superior temperature coefficients for utility-scale desert installations. Procurement concentrates among First Solar's integrated manufacturing network, constrained by EPA hazardous substance rules imposing end-of-life recycling liabilities that limit residential segment penetration.
- Copper Indium Gallium Selenide:CIGS absorber layers enable flexible substrate applications and improved shading tolerance. MiaSole and Solar Frontier anchor niche supply for building-integrated and portable power segments.
- Organic Photovoltaics:Solution-processed polymer-fullerene blends target ultra-low-cost disposable electronics and indoor energy harvesting. Heliatek and Armor Group pilot production for commercial facade integration.
Silicon leads on scale; Cadmium Telluride leads on momentum in utility-scale procurement.
Application:
Project scale and offtake structure reshape material specification priorities across customer segments.
- Residential:Rooftop systems under 20kW prioritize module aesthetics and warranty length over absolute efficiency. Installers in Germany and the Netherlands specify black-framed monocrystalline products with 25-year performance guarantees.
- Commercial:Behind-the-meter installations at manufacturing facilities and warehouses balance roof loading constraints with demand charge reduction. India's net metering policies in Gujarat and Tamil Nadu accelerate procurement of high-wattage modules.
- Utility Scale:Ground-mounted solar parks above 5MW drive volume concentration for standardized module formats. Developers in Brazil's Minas Gerais state lock multi-year supply agreements under national renewable portfolio standards.
- Off-Grid:Remote power systems for telecommunications and rural electrification prioritize durability over efficiency. Installations across sub-Saharan Africa and Southeast Asian islands specify robust frame designs and bypass diode redundancy.
Utility Scale commands procurement volume; Residential climbs fastest on distributed generation policy support.
Production Method:
Capital intensity and yield rates differentiate manufacturing technology selection for new capacity deployment.
- C-Si Production:Conventional crystalline silicon ingot growing and wire sawing dominates installed manufacturing base. LONGi Green Energy and Tongwei operate integrated polysilicon-to-module lines capturing margin at each process step.
- Thin Film Deposition:Chemical vapor deposition and sputtering techniques enable CdTe and CIGS manufacturing without silicon supply exposure. First Solar's Perrysburg and Kulim facilities demonstrate gigawatt-scale thin-film economics.
- Printing Technology:Roll-to-roll coating of organic semiconductors targets breakthrough cost structures for flexible applications. Konica Minolta and Eight19 develop pilot lines for building-integrated and consumer electronics markets.
- Heterojunction Technology:Amorphous silicon deposition onto crystalline wafers achieves open-circuit voltage advantages exceeding conventional PERC architectures. REC Group and Meyer Burger expand heterojunction capacity to capture efficiency premiums in European and Japanese markets.
C-Si Production retains manufacturing dominance; Heterojunction Technology gains share fastest on efficiency roadmaps.
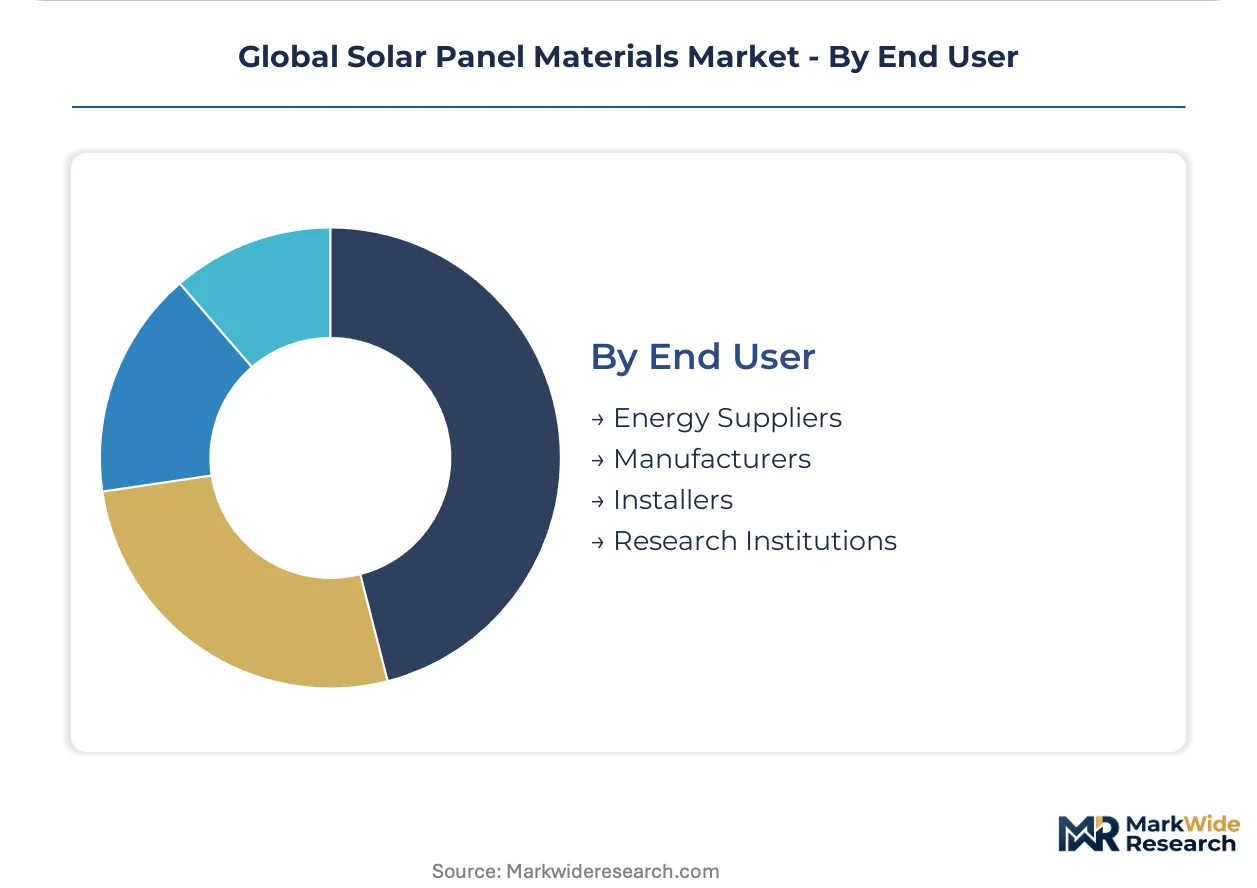
End User:
Technical sophistication and procurement scale separate stakeholder material requirements across the value chain.
- Energy Suppliers:Utility and independent power producers specify bankable module suppliers with proven degradation rates. European developers bundle 10-15 year offtake contracts with supply guarantees to secure project finance.
- Manufacturers:Cell and module producers procure polysilicon, wafers, and encapsulant materials against efficiency and traceability mandates. China's MIIT documentation requirements and the EU's CBAM carbon border adjustments reshape supplier qualification.
- Installers:EPC contractors and system integrators optimize balance-of-system costs through module selection. Rooftop specialists in São Paulo state navigate Brazil's distributed generation regulations for net metering eligibility.
- Research Institutions:National laboratories and university programs drive next-generation material development. Fraunhofer ISE and NREL pilot perovskite tandems and copper metallization techniques.
Energy Suppliers drive procurement volume; Manufacturers face the steepest compliance trajectory on embodied carbon documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon refining specialists and wafer slicing technicians concentrate in China's Jiangsu and Anhui provinces, anchoring the industry's largest talent pool. German engineering clusters and Indian manufacturing zones compete for secondary positions through targeted vocational programs and production-linked incentive schemes.
China
Metallurgical-grade silicon refining dominates in Xinjiang and Inner Mongolia, supplying over four-fifths of global feedstock. The MIIT enforces GB efficiency standards that phase out legacy cell architectures below 21% conversion rates. Suzhou and Hefei equipment ecosystems enable rapid line retooling for heterojunction and TOPCon migrations.
Germany
Building-integrated photovoltaic demand surges across commercial facade retrofits in Berlin and Munich metropolitan corridors. The EU Green Deal's embodied carbon mandates force module suppliers to document supply-chain emissions through CBAM documentation requirements. Fraunhofer ISE anchors research commercialization in Freiburg, piloting perovskite tandem architectures.
India
Net metering policies in Gujarat and Tamil Nadu accelerate distributed generation procurement for residential and commercial rooftops. The PLI scheme attracts greenfield polysilicon-to-module investments with production-linked incentives spanning five-year qualification windows. Mundra and Hazira port clusters facilitate imported high-efficiency module clearance for utility-scale developers.
Brazil
Multi-year supply agreements lock under national renewable portfolio standards in Minas Gerais and São Paulo states. ANVISA coordinates with environmental regulators on module import certification timelines. Distributed generation underperformance in residential segments creates procurement openings for imported high-wattage products.
United States
First Solar's integrated CdTe manufacturing network bypasses silicon supply constraints entirely for utility-scale desert installations. The EPA enforces hazardous substance rules imposing end-of-life recycling liabilities on cadmium-containing thin-film modules. Perrysburg, Ohio and Kulim, Malaysia facilities demonstrate gigawatt-scale thin-film economics without polysilicon exposure.
Global Solar Panel Materials Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent technology roadmaps. The vendor base stratifies into three tiers: integrated polysilicon-to-module operators capturing margin at each process step, pure-play cell and wafer specialists, and thin-film technology licensors sidestepping silicon supply chains entirely. Dominant competitive moves include captive metallization capability acquisition and heterojunction production line licensing.
Among Chinese integrated producers, LONGi Green Energy and Tongwei Solar occupy positions exemplifying backward integration into polysilicon refining. First Solar represents the thin-film archetype through proprietary vapor transport deposition. These three anchors illustrate how technology selection—crystalline silicon heterojunction versus cadmium telluride thin-film—determines supply chain risk profile and regulatory compliance pathway.
| Leading Market Players |
|---|
| LONGi Green Energy |
| JinkoSolar |
| JA Solar |
| Trina Solar |
| Tongwei Solar |
| Canadian Solar |
| First Solar |
| Xinyi Solar Holdings |
| Aiko Solar |
| Others |
Supply Flow & Price Mechanics
Certified low-carbon module premiums versus commodity spot pricing bifurcates procurement economics across the Global Solar Panel Materials Market, with EU Green Deal traceability mandates compressing margins for undocumented supply chains while rewarding integrated polysilicon-to-module operators with documented emissions profiles. This tier divergence concentrates purchasing leverage among utility-scale developers locking long-term offtake contracts, while distributed installers absorb spot market volatility for unverified imports.
Pricing Analysis
Bundled long-term supply guarantees dominate utility-scale procurement, separating bankable module suppliers with certified degradation rates from spot-market traders serving distributed segments. Price differentiation rests on carbon-border documentation and efficiency tier certification, with CBAM-compliant products commanding premiums against non-compliant alternatives. Cost compression in standard-efficiency crystalline silicon intensifies as China's MIIT phases out sub-21% cell architectures, squeezing legacy manufacturers. Residential installers in Brazil and India exhibit highest price sensitivity, while European utility developers prioritize bankability over unit cost.
Supply Chain Analysis
India's PLI scheme and Brazil's local-content incentives for renewable portfolio standards are reshaping sourcing geography away from concentrated Chinese polysilicon refining. Metallurgical-grade silicon feedstock draws from Xinjiang and Inner Mongolia, while wafer slicing capacity clusters in Jiangsu and Anhui. Silver paste and high-purity quartz crucibles represent critical input dependencies. Single-source vulnerability in polysilicon refining exposes buyers to logistics bottlenecks and trade policy friction. Distribution runs through port clusters at Mundra, Santos, and Rotterdam for regional module assembly and developer offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Solar Panel Materials Market functions as a regulatory compounder, with the EU Green Deal's embodied carbon mandates and CBAM documentation requirements driving demand for traceable supply chains and certified low-carbon products.
For Market Incumbents: Deploy captive metallization capabilities as the priority defensive lever. Acquire laser doping and screen printing technician talent pools to maintain yield rates through TOPCon and heterojunction transitions. Expand heterojunction licensing programs to capture efficiency premiums before copper-plated alternatives displace silver-dependent architectures. For New Entrants and Emerging Players: Building-integrated photovoltaic installers in German and Dutch commercial facade retrofits represent the most penetrable buyer archetype underserved by standardized module suppliers. Target architectural glass laminators seeking solar cell integration partnerships. Pursue co-development agreements with European engineering firms holding facade retrofit project pipelines. For Investors and Strategic Acquirers: Asymmetric upside sits with heterojunction equipment suppliers holding proprietary plating chemistry intellectual property. Frame long-term viability around copper metallization adoption curves displacing silver paste dependencies. Watch for inflection in European utility PPA bundling rates as signal for bankable module supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | LONGi Green Energy and Tongwei Solar capture margin at each process step while meeting EU traceability mandates. |
| Heterojunction Production Line Licensing | REC Group and Meyer Burger expand capacity to capture efficiency premiums in carbon-sensitive European markets. |
| Copper Metallization Pilot Programs | Light-induced plating lines eliminate silver finger dependencies, redistributing procurement leverage toward equipment suppliers. |
| Long-term Power Purchase Agreement Bundling | German and Spanish aggregators compress developer working capital through 10-15 year offtake-supply guarantees. |
| Fluoropolymer Backsheet Substitution | PET-based and co-extruded alternatives accelerate under EU F-Gas Regulation, reshaping encapsulant demand toward POE resins. |
Methodological Framework
Direct dialogue with polysilicon procurement managers, cell line engineers, utility developer planning officers, and EPC contractor project directors grounded this analysis in operational reality. Secondary validation drew from MIIT GB standard filings, EU CBAM documentation requirements, Indian PLI scheme qualification records, and utility-scale project development databases across Brazil and Europe. Bottom-up capacity assessments and top-down demand modeling triangulate market sizing.
Bottom-up manufacturing capacity modeling across polysilicon refining, wafer slicing, cell fabrication, and module assembly segments converged with top-down renewable portfolio standard targets and power purchase agreement pipelines. Segmentation dimensions include material architecture, production method, application scale, and end-user sophistication. CAGRs derive from installed capacity buildout trajectories against policy-mandated procurement floors. Silver price volatility and wafer thinning yield rates serve as key forecast sensitivity inputs across the projection horizon.
Underlying measurement precision varies by segment; utility-scale procurement volumes carry tighter precision than distributed generation estimates given consolidated developer disclosure. Forecasts reflect documented policy assumptions including EU Green Deal implementation timelines and India's PLI scheme qualification windows. Module import tariff shifts and polysilicon logistics disruptions represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Global Ultra Efficient Solar Power Market