
 Industrial Pump Control Panels Market | 2026-2036
Industrial Pump Control Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Pump Control Panels Market Analysis
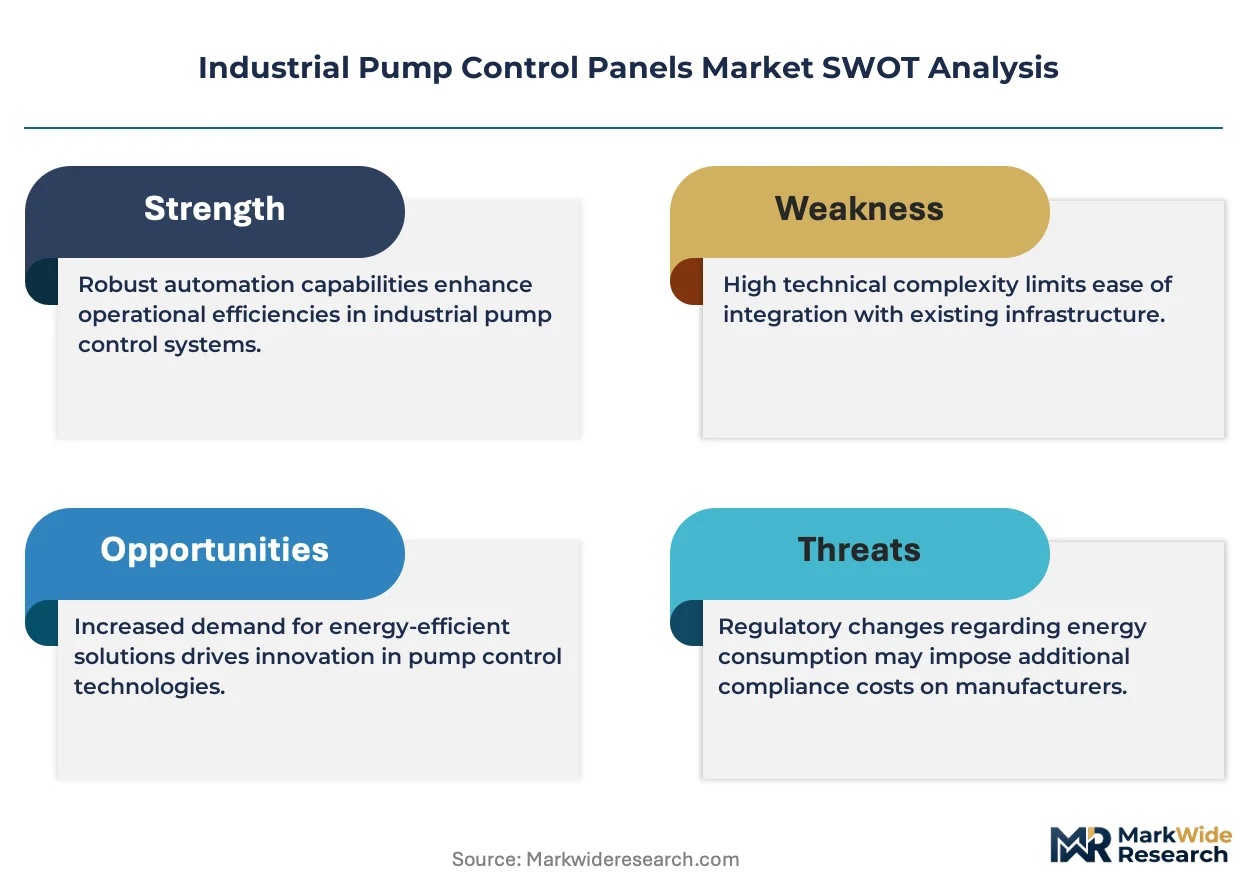
Automation engineering talent scarcity is bifurcating the competitive landscape between full-service system integrators and component suppliers. Siemens leverages its vertically integrated automation portfolio to dominate turnkey pump station projects across European water infrastructure. Rockwell Automation sustains its North American position through FactoryTalk-integrated control architectures that anchor municipal and industrial accounts. Schneider Electric differentiates via EcoStruxure platform compatibility, extending its presence in hybrid energy pump installations across Asia-Pacific markets.
Industrial pump control panels are electromechanical enclosures housing motor starters, variable frequency drives, programmable logic controllers, and protection relays designed to regulate pump operation across flow rates, pressure setpoints, and fault conditions. These systems typically operate at voltage classes from 230V to 690V with ingress protection ratings of IP54 through IP66 for harsh industrial environments. Smart control type configurations are capturing the fastest expansion as IoT-enabled diagnostics and predictive maintenance protocols displace manual and semi-automatic alternatives in critical service applications. Wall-mounted enclosures retain volume leadership in retrofit installations where space constraints and existing infrastructure limit freestanding deployment, while rack-mounted variants are gaining traction in centralized SCADA-controlled treatment facilities.
UL 508A panel shop certification governs North American construction standards, while IEC 61439 series directives shape European assembly and testing protocols for low-voltage switchgear assemblies. China's GB 7251 standards and compulsory CCC marking create distinct compliance pathways for suppliers targeting domestic infrastructure tenders. India's BIS certification requirements and CEA grid connectivity mandates are tightening technical specifications for electrically powered pump control systems deployed in agricultural and municipal schemes. Stakeholders must monitor evolving cybersecurity frameworks for operational technology networks as NIST SP 800-82 and IEC 62443 adoption spreads beyond energy into water and chemical processing infrastructure.
Market Dynamics
Water treatment utilities in Germany, the United States, and China are accelerating replacement cycles for electromechanical pump controls as IEC 62055 and IEEE 519 tighten harmonic mitigation requirements. This regulatory compression is forcing panel manufacturers to redesign motor starter architectures and VFD integration protocols.
Growth Catalysts
- Smart control type configurations:IoT-enabled diagnostics and predictive maintenance protocols are displacing manual and semi-automatic alternatives in critical municipal water infrastructure.
- IEC 61439 compliance mandates:European assembly and testing protocols for low-voltage switchgear assemblies are standardizing panel construction quality across cross-border water treatment tenders.
- China's GB 7251 standards:Compulsory CCC marking requirements are creating captive domestic demand for certified control panel suppliers targeting infrastructure modernization programs.
Market Restraints
- Copper and silicon steel price volatility:Raw material input swings compress margins for panel shops building motor starter and VFD enclosures at fixed contract pricing.
- Automation engineering talent scarcity:Shortage of PLC programming and SCADA integration specialists limits deployment velocity for smart control retrofits.
- Legacy electromechanical substitution:Existing relay-based pump stations with decades of operational life resist premature replacement despite efficiency gaps.
Strategic Opportunities
- India's agricultural pump electrification:CEA grid connectivity mandates and BIS certification requirements are opening standardized procurement channels for control panel OEMs.
- Cybersecurity framework convergence:NIST SP 800-82 and IEC 62443 adoption into water infrastructure creates demand for hardened OT network architectures in pump control systems.
- Rack-mounted enclosure formats:Centralized SCADA-controlled treatment facilities are shifting from wall-mounted retrofits toward standardized rack integration.
Industry Challenges
- Multi-standard certification timelines:Simultaneous UL 508A, IEC 61439, and GB 7251 compliance testing extends product launch cycles by 8-14 months.
- Legacy system integration complexity:Retrofit installations require custom protocol gateways to bridge proprietary SCADA networks with modern IoT-enabled pump diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Pump Control Panels Market |
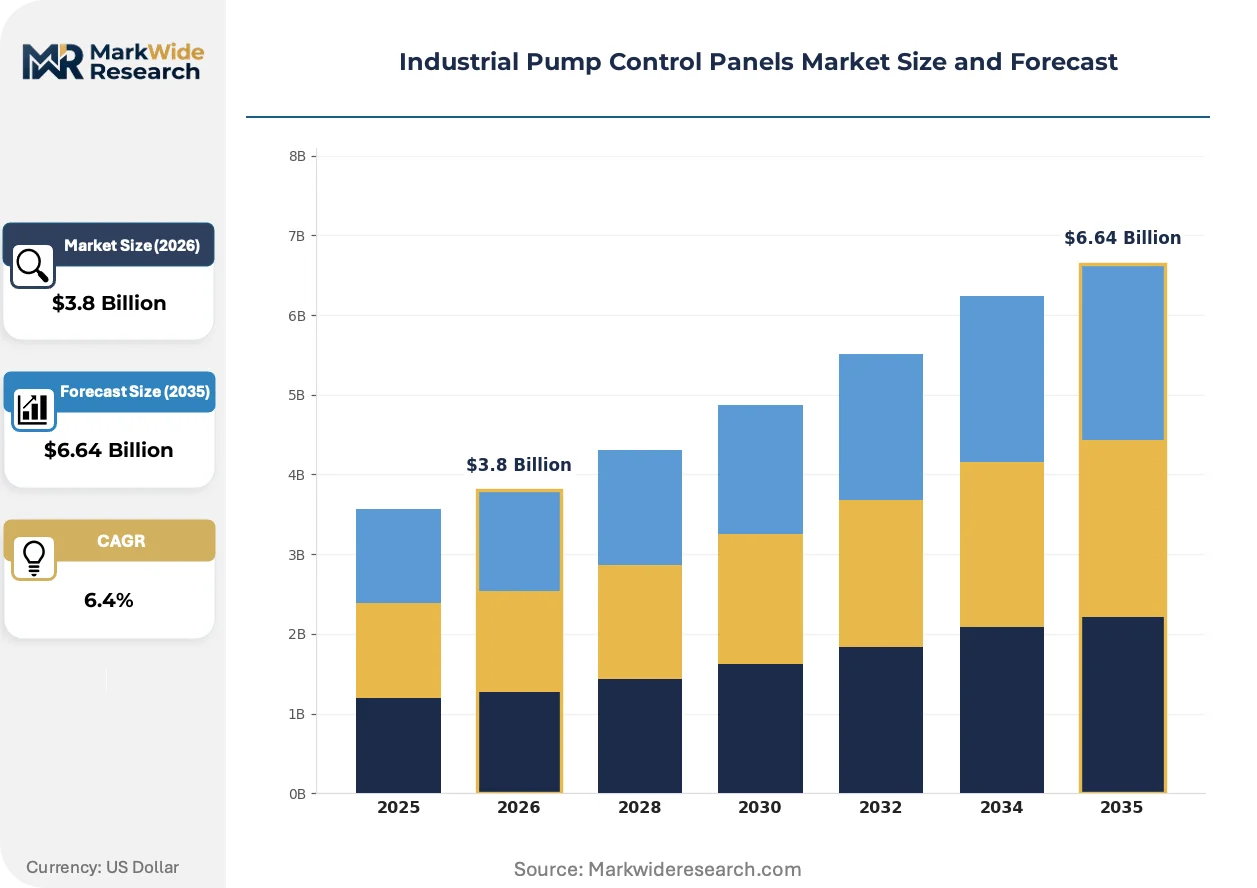
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Control Type: Manual, Automatic, Semi-Automatic, Smart End User: Manufacturing, Oil & Gas, Water Treatment, Chemicals Power Source: Electric, Solar, Diesel, Hybrid Mounting Type: Wall-Mounted, Freestanding, Portable, Rack-Mounted |
| Companies Covered | Siemens, Rockwell Automation, Emerson Electric, Schneider Electric, ABB, Xylem, Grundfos Holding A/S, Honeywell, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Pump Control Panels Market Emerging Trajectories
Digital twin technology and edge computing architectures are reshaping how pump control panels generate operational value. Vendors are racing to embed predictive algorithms directly into VFD firmware rather than relying on cloud-only analytics.
Edge-native vibration monitoring is bifurcating the aftermarket service model for critical pump installations. Municipal water authorities in Germany and the Netherlands are deploying sensor-integrated control panels that stream bearing health data directly to maintenance dispatch systems. This capability is bifurcating competitive positioning between full-service integrators with diagnostic platforms and component suppliers without embedded analytics.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant pump control retrofits in industrial cooling applications. Panel specifications now require compatibility with low-GWP refrigerant systems and variable-speed compressor protocols. European HVAC contractors are specifying IEC 61439-compliant assemblies with integrated harmonic filtering to meet utility interconnection standards.
Utility procurement departments are unbundling control panel supply from turnkey installation contracts. North American water authorities now separate hardware specification from systems integration, forcing panel shops to certify directly under utility master service agreements rather than subcontracting through EPC firms. This pattern is most visible in California and Texas municipal water districts with centralized purchasing authorities.
Industrial Pump Control Panels Market Segmentation
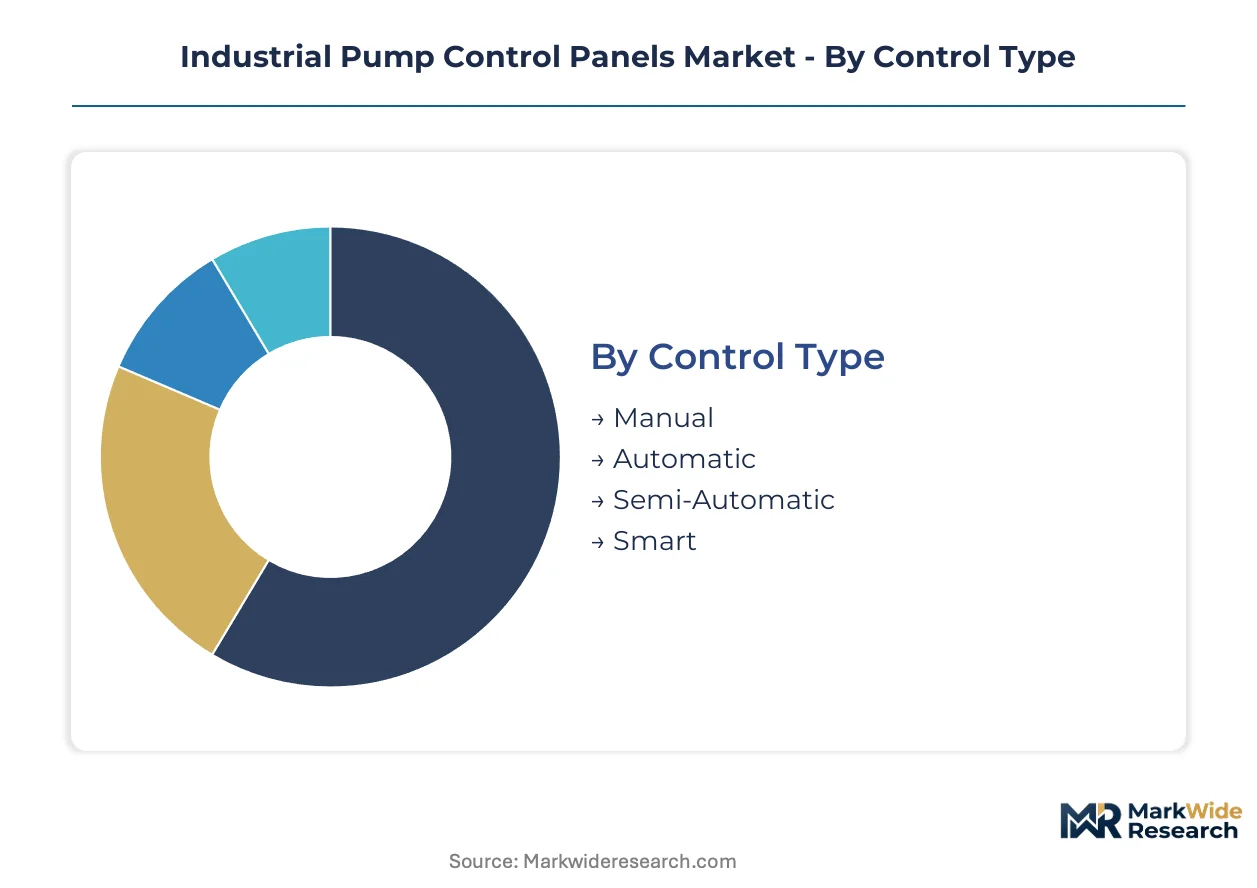
Pump control panel procurement patterns diverge sharply across operational contexts. Specification priorities for harmonic compliance, enclosure ingress protection, and SCADA integration create distinct segment boundaries that reshape supplier positioning.
Control Type:
Smart configurations face the strongest substitution pressure from edge-native diagnostics platforms that bypass traditional panel architectures entirely.
- Smart:Embedded VFD firmware runs predictive algorithms locally, streaming bearing health data to maintenance dispatch systems in German and Dutch municipal networks. IEC 62443 cybersecurity hardening and NIST SP 800-82 compliance are becoming mandatory in North American water utility tenders.
- Automatic:Relay-logic and PLC-based architectures dominate retrofit installations where legacy SCADA protocols resist cloud connectivity. Demand concentrates in chemical processing facilities requiring precise pressure setpoint regulation without IoT infrastructure investment.
- Manual:Simple electromechanical starters persist in agricultural and small-scale industrial pumping where capital constraints override efficiency gains.
- Semi-Automatic:Hybrid designs blend local pushbutton control with remote status monitoring, serving mid-tier water treatment plants transitioning toward full automation.
Smart configurations retain volume leadership in new infrastructure; automatic systems hold the steepest expansion curve in retrofit markets.
End User:
Cost tier stratification separates specification-intensive municipal tenders from price-sensitive industrial accounts.
- Water Treatment:IEC 62055 and IEEE 519 harmonic mandates are forcing VFD-integrated panel redesigns across German, United States, and Chinese utility procurement cycles. Smart control adoption is displacing electromechanical alternatives in critical service applications.
- Oil & Gas:Explosion-proof enclosures and SIL-rated safety systems dominate upstream and midstream specifications. IEC 61439 compliance and ATEX certification create dual regulatory burdens for panel suppliers.
- Chemicals:Corrosion-resistant materials and sealed conduit entries address aggressive process environments. Demand clusters in specialty chemical manufacturing requiring precise flow control.
- Manufacturing:General industrial pumping applications prioritize cost efficiency over advanced diagnostics, sustaining demand for basic motor starter configurations.
Water treatment commands the premium pricing tier; manufacturing absorbs the highest shipment volumes.
Power Source:
Application context determines energy architecture selection across grid-connected and off-grid operational environments.
- Electric:Standard 230V to 690V configurations serve the majority of industrial and municipal installations. UL 508A and IEC 61439 construction protocols govern regional supply chains.
- Solar:DC-AC conversion integration and battery backup systems address agricultural electrification schemes in India under CEA grid connectivity mandates. BIS certification requirements standardize procurement channels.
- Diesel:Prime power and standby applications persist in remote oilfield operations and emergency backup systems where grid reliability is insufficient.
- Hybrid:Dual-source architectures combining grid power with solar or diesel backup are gaining traction in decentralized water treatment facilities seeking operational resilience.
Electric systems dominate installed base; hybrid configurations are climbing the fastest among new specifications.
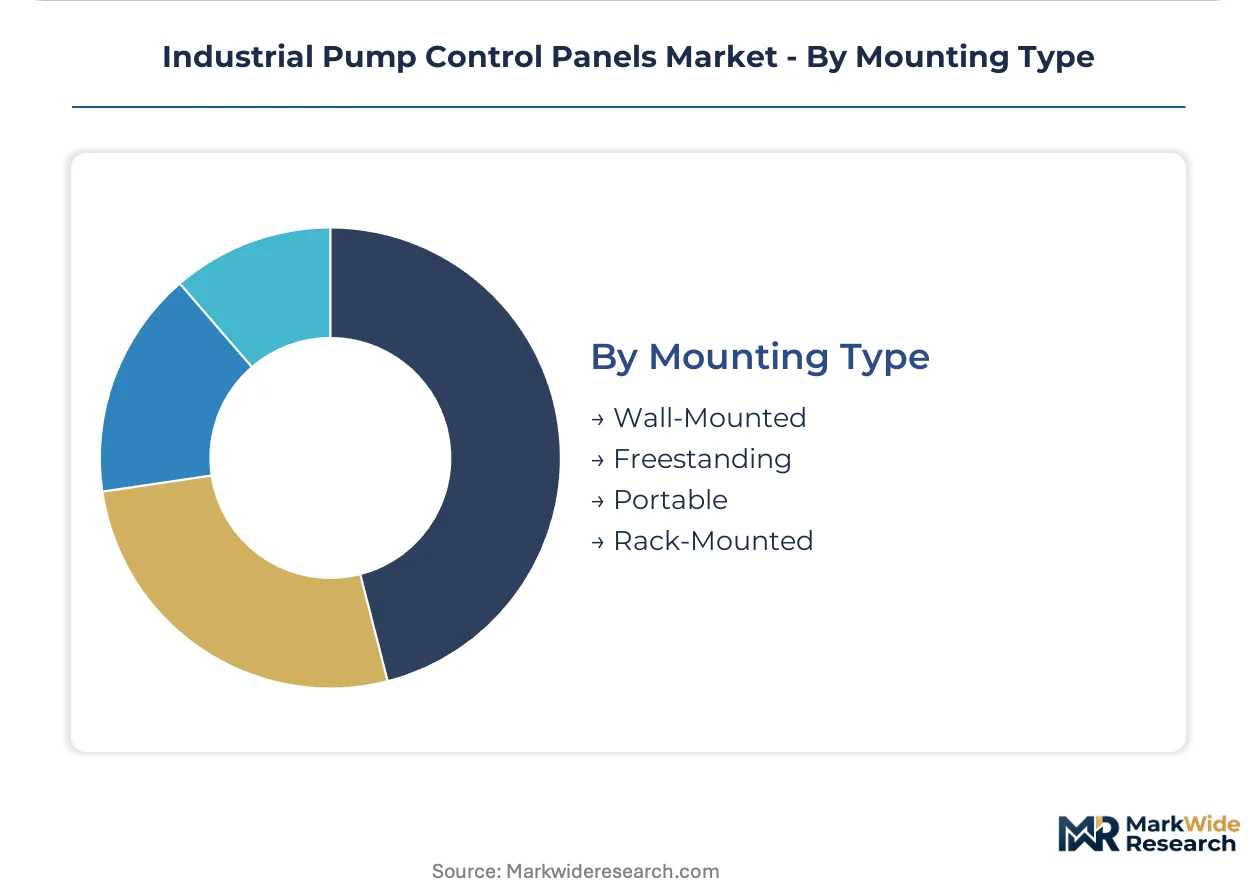
Mounting Type:
Customer infrastructure constraints dictate enclosure format selection between retrofit compatibility and greenfield optimization.
- Wall-Mounted:Compact enclosures with IP54 through IP66 ratings serve space-constrained retrofit installations where existing infrastructure limits footprint expansion. Volume leadership persists in European and North American upgrade cycles.
- Rack-Mounted:Standardized 19-inch configurations integrate into centralized SCADA-controlled treatment facilities, enabling modular expansion and hot-swappable component replacement.
- Freestanding:Floor-mounted cabinets accommodate larger motor starters and isolation transformers in heavy industrial applications with available plant floor space.
- Portable:Skid-mounted or caster-equipped designs serve temporary dewatering, construction site pumping, and emergency response deployments requiring rapid relocation.
Wall-mounted formats retain volume leadership; rack-mounted variants are gaining share fastest in centralized facility designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA drinking water infrastructure mandates are compressing replacement cycles across United States municipal utilities, while tightening IEC 61439 compliance in Germany and GB 7251 enforcement in China reshape procurement specifications for cross-border panel suppliers.
United States
California and Texas water districts are unbundling control panel supply from turnkey EPC contracts under centralized purchasing authority reforms. EPA Lead and Copper Rule revisions are accelerating smart control retrofits in legacy pump stations. Chicago and Houston industrial corridors are absorbing the highest shipment volumes for wall-mounted retrofit enclosures.
Germany
Ruhr Valley water treatment clusters are deploying edge-native vibration monitoring integrated directly into VFD firmware for predictive maintenance dispatch. EU F-Gas Regulation phase-down schedules are forcing refrigerant pump control panel redesigns with low-GWP compatibility. Bavarian municipal utilities are leading IEC 62055 harmonic compliance adoption across European cross-border tenders.
China
Yangtze River Delta infrastructure modernization is driving captive demand for CCC-marked GB 7251-compliant assemblies. MIIT dual carbon goals are tightening energy efficiency specifications for electrically powered pump controls in municipal schemes. Shandong Province agricultural pump electrification programs are absorbing hybrid solar-grid control configurations under CEA-influenced technical standards.
India
Maharashtra and Gujarat agricultural pump electrification schemes are opening standardized procurement channels under BIS certification and CEA grid connectivity mandates. Telangana municipal water authorities are piloting smart control retrofits with embedded cybersecurity hardening. Karnataka industrial zones are absorbing rack-mounted configurations for centralized SCADA-controlled treatment facilities.
Netherlands
Randstad water authorities are deploying sensor-integrated control panels streaming bearing health data directly to maintenance dispatch systems. REACH and RoHS compliance are tightening material specifications for corrosion-resistant enclosures in coastal treatment plants. Rotterdam port industrial clusters are specifying IEC 61439-compliant assemblies with integrated harmonic filtering for utility interconnection.
Industrial Pump Control Panels Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-service system integrators commanding turnkey pump station projects while component suppliers compete on enclosure fabrication and VFD integration speed. The competitive landscape bifurcates between vertically integrated automation portfolios and focused panel shops certified under UL 508A or IEC 61439 protocols. Dominant competitive moves include backward integration into VFD firmware development and geographic expansion through utility master service agreement certifications.
Among Germany-based industrial conglomerates, Siemens anchors the full-service integrator archetype through vertically bundled automation portfolios. Rockwell Automation exemplifies the North American systems integration model with FactoryTalk-anchored control architectures. Schneider Electric occupies a position within the platform-centric tier, leveraging EcoStruxure compatibility for hybrid energy pump installations.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Emerson Electric |
| Schneider Electric |
| ABB |
| Xylem |
| Grundfos Holding A/S |
| Honeywell |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
UL 508A and IEC 61439 certification regimes simultaneously gate supplier qualification and stratify price tiers across the industrial pump control panels market, forcing panel shops to absorb compliance costs while utilities unbundle procurement to capture margin compression.
Pricing Analysis
Long-term offtake contracts dominate municipal utility procurement in Germany and the United States, while spot purchasing persists in agricultural and small industrial segments. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-cyberhardened smart configurations from basic relay-logic panels. Cost compression in standard-tier wall-mounted retrofits is intensifying because copper and silicon steel price volatility outpaces contract escalation clauses. Agricultural pump electrification schemes in India exhibit the highest price sensitivity; German Ruhr Valley water authorities show the lowest due to predictive maintenance ROI mandates.
Supply Chain Analysis
Strategic stockpiling of VFDs and motor starters characterizes North American panel shops anticipating lead time volatility, while European integrators favor just-in-time coordination with Siemens and ABB distribution hubs. Manufacturing concentrates in Germany, the United States, and China, with enclosure fabrication drawing from Chinese steel mills and VFD semiconductors resting on Taiwanese foundry output. Single-source vulnerability in IGBT modules creates exposure to regional logistics chokepoints. Distribution runs through authorized systems integrators for turnkey projects and direct panel shop relationships for unbundled hardware supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as North American water authorities centralize procurement under master service agreements, fragmenting the vendor base between certified direct suppliers and displaced EPC subcontractors.
For Market Incumbents: Secure IEC 61439 and UL 508A dual-certification capacity to defend against emerging Asian panel shops capturing unbundled contract flows. Backward integration into edge-native VFD firmware development anchors recurring revenue streams as cloud-only analytics face displacement. For New Entrants and Emerging Players: Differentiate on cybersecurity-hardened architectures targeting NIST SP 800-82 compliance gaps in mid-tier North American utilities. India's agricultural pump electrification schemes under CEA mandates represent the most penetrable geography; pursue BIS certification as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart control configurations requiring embedded sensor integration and firmware development. Target panel shops with certified utility master service agreements and captive VFD integration capabilities. Watch for IEC 62055 harmonic compliance adoption velocity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VFD Firmware | Captures predictive maintenance revenue streams from German municipal utilities. |
| Dual-Certification Expansion | UL 508A and IEC 61439 compliance opens unbundled procurement channels in Texas and California. |
| Cybersecurity Hardening Investment | NIST SP 800-82 alignment addresses emerging tender requirements in North American water districts. |
| Geographic Certification Push | BIS and CCC marking penetration captures India's agricultural electrification procurement waves. |
| Edge-Native Diagnostics Development | Embedded bearing health algorithms displace cloud-dependent competitors in Dutch Randstad networks. |
Methodological Framework
The analysis maps smart, automatic, manual, and semi-automatic control configurations, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and utility maintenance directors. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, IEC and UL certification registries, and municipal procurement databases anchored supply-side and demand-side estimates. Bottom-up panel shop capacity modeling and top-down utility capital expenditure tracking enabled cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include control type, end-user industry, power source architecture, and mounting format. CAGRs were derived from installed base replacement cycles and infrastructure modernization program commitments. Forecast inputs incorporated raw material price trajectory assumptions and regulatory compliance timeline accelerations.
The analysis sits within stated boundaries; outcomes outside sustained copper price stability and certification regime enforcement would require recalibration. Forecasts reflect documented assumptions regarding utility procurement unbundling velocity and automation engineering labor availability. Revision becomes warranted when cybersecurity framework adoption crosses critical mass thresholds in water infrastructure tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market