
 Global Submersible Pumps Market | 2026-2036
Global Submersible Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submersible Pumps Market Analysis
China is rewriting capacity dynamics in submersible pump manufacturing through expanded foundry and motor-winding investments. Grundfos Holding A/S leverages its vertically integrated Danish operations to sustain premium positioning in energy-efficient systems. Xylem Inc. competes through digital monitoring integration across its dewatering portfolio. KSB SE & Co. KGaA anchors its presence with heavy-duty borewell configurations for mining and municipal segments.
Submersible pumps are sealed motor-pump units designed to operate while fully immersed in fluid, typically constructed from cast iron or stainless steel housings with impeller clearances measured in millimeters to handle solids-laden media. These systems transfer water, slurry, or hydrocarbons from submerged sources to surface delivery points across agricultural, industrial, and utility infrastructure. Centrifugal technology dominates volume production due to its scalability across head and flow requirements, while solar product types represent the fastest-expanding category as off-grid irrigation displaces diesel sets in emerging economies. Wastewater management applications command durable margin pools because abrasive media demand hardened materials and aftermarket service contracts.
EPA efficiency standards in the United States and EU Ecodesign regulations under the EU Green Deal compel manufacturers to redesign hydraulic sections and motor laminations for lower specific energy consumption. China's GB standards and India's BIS certification create parallel compliance pathways that shape export strategies and local production decisions. Stakeholders must monitor how fragmented national efficiency regimes fragment procurement specifications and whether modular platform architectures can absorb divergent regulatory loads without proliferating SKU complexity.
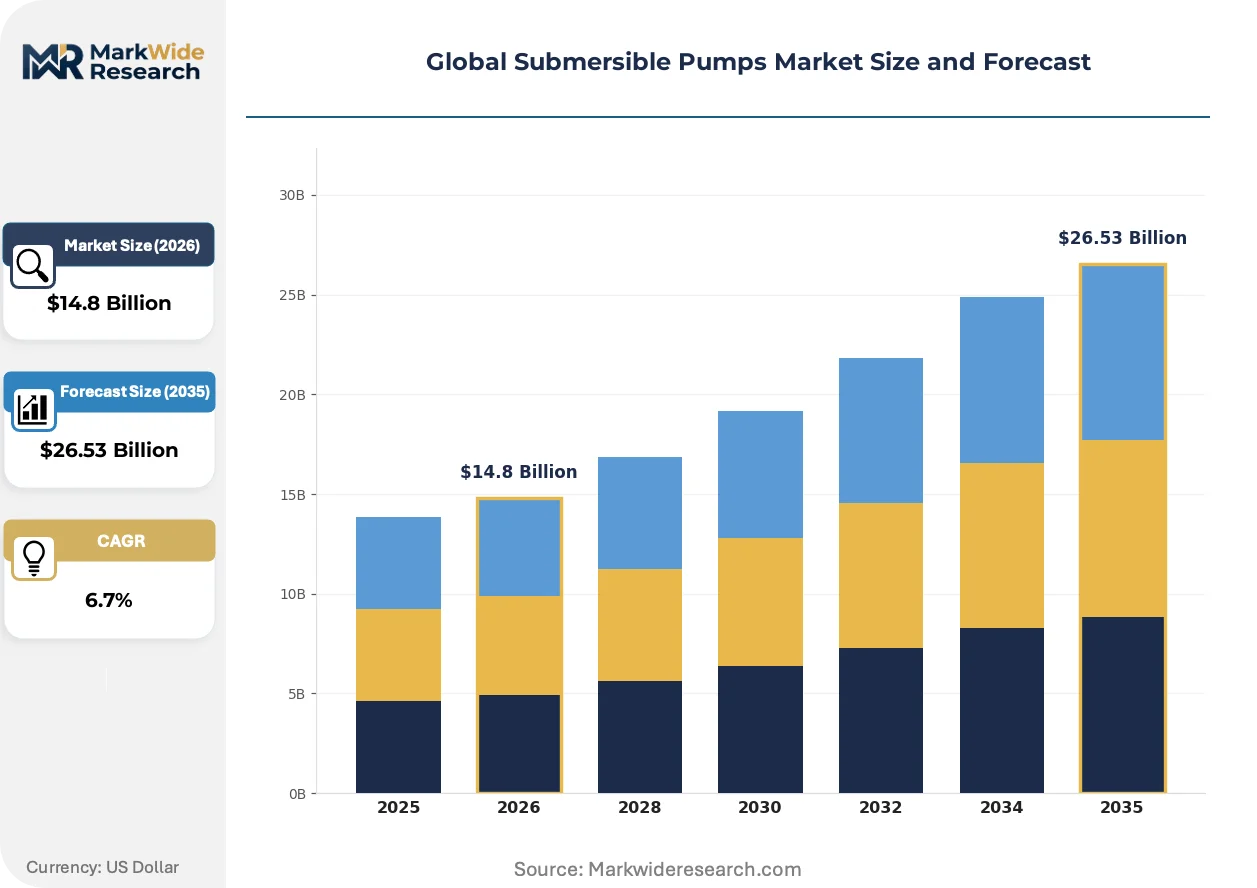
Market Dynamics
Energy efficiency mandates across multiple jurisdictions are forcing simultaneous redesign of motor laminations and hydraulic sections, compressing development cycles while expanding aftermarket service revenue pools for compliant equipment.
Growth Catalysts
- EU Ecodesign regulations:The EU Green Deal mandates stricter energy efficiency standards for pumping equipment, compelling municipal utilities to accelerate replacement schedules for aging wastewater infrastructure.
- Solar pump technology:Photovoltaic-powered submersible systems are displacing diesel sets across India's agricultural belt as farmers electrify irrigation networks.
- Southeast Asian wastewater expansion:Municipalities in Vietnam, Indonesia, and Thailand are building centralized sewage treatment capacity requiring solids-handling submersible configurations.
Market Restraints
- Copper and rare-earth price volatility:Motor winding materials and permanent magnet inputs face supply concentration from Chinese processing facilities, squeezing margin predictability for manufacturers.
- Technical limitation in abrasive media:Hardened impeller materials extend lead times and raise unit costs for mining slurry applications, limiting addressable market penetration.
- Regulatory fragmentation:Parallel compliance with China's GB standards, India's BIS certification, and EU Ecodesign creates SKU proliferation without proportional volume scaling.
Strategic Opportunities
- Underpenetrated African irrigation:Solar submersible pumps face limited competition in East African smallholder markets where grid extension remains uneconomical.
- Digital monitoring convergence:Integration of vibration sensors and cloud analytics with pump hardware enables predictive maintenance contracts in industrial water management.
- US IRA incentives:The Inflation Reduction Act subsidizes energy-efficient agricultural equipment upgrades, accelerating electric pump adoption in California's Central Valley.
Industry Challenges
- Skilled technician scarcity:Installation and repair of sealed motor-pump units requires specialized training that outpaces vocational pipeline output in emerging markets.
- Legacy system integration friction:Retrofitting variable-frequency drives onto existing borewell infrastructure demands custom electrical engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submersible Pumps Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical, Hydraulic, Air-Driven, Solar Application: Agricultural Irrigation, Wastewater Management, Industrial Processes, Oil & Gas Extraction End User: Municipalities, Construction, Agriculture, Energy Technology: Vortex, Centrifugal, Positive Displacement, Jet Pump |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., Sulzer Ltd., KSB SE & Co. KGaA, Flowserve Corporation, Franklin Electric Co., Inc., Ebara Corporation, Tsurumi Manufacturing Co., Ltd., WILO SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submersible Pumps Market Emerging Trajectories
Digitalization and material science advances are compressing the traditional divide between hardware durability and software-enabled performance optimization across pump portfolios.
Permanent magnet synchronous motors are replacing induction designs in high-head applications, delivering efficiency gains that municipal utilities in Germany and Denmark are capturing through accelerated procurement cycles. The technology is rendering obsolete the standard asynchronous motor platforms that dominated agricultural and commercial specifications for three decades.
EPA efficiency standards in the United States are tightening minimum performance requirements for clean water pumps above 1 horsepower, forcing manufacturers to redesign hydraulic sections and source higher-grade electrical steel. The industrial dewatering segment is responding by consolidating supplier relationships to secure compliant component pipelines ahead of enforcement deadlines.
Equipment-as-a-service models are emerging in European municipal water management, with operators paying per cubic meter pumped rather than owning capital assets outright. Dutch and Danish utilities are piloting these arrangements most aggressively, transferring operational risk to OEMs while locking in long-term maintenance revenue streams for suppliers.
Global Submersible Pumps Market Segmentation
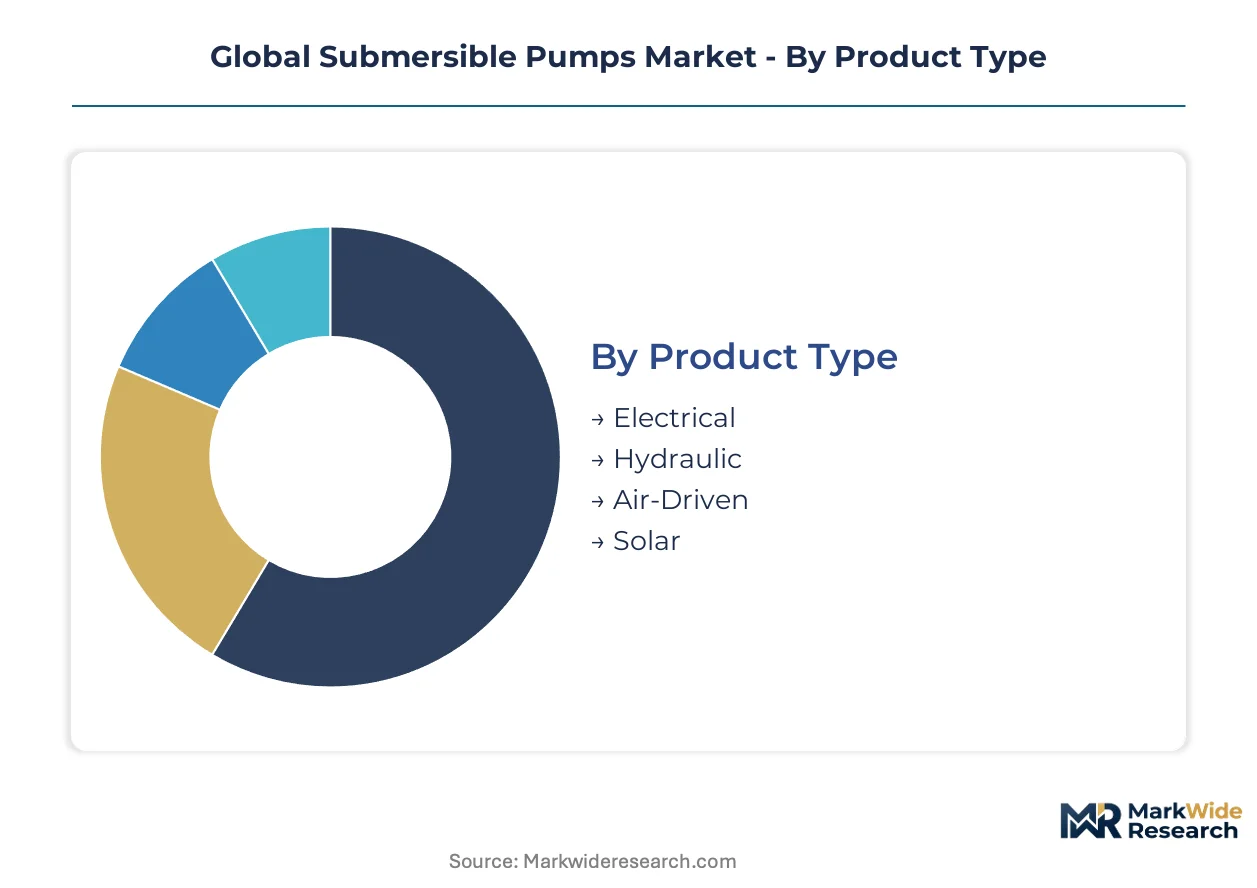
Submersible pump procurement patterns diverge sharply across power sources, fluid handling requirements, and operator sophistication. Segment boundaries are blurring as solar-electrical hybrids and smart centrifugal systems capture cross-category demand.
Product Type:
Mature electrical platforms dominate installed base volumes while emerging solar configurations reshape rural deployment economics.
- Electrical:Grid-connected induction and permanent magnet motors power the majority of installed agricultural and municipal systems. Indian state electricity boards and Vietnamese irrigation cooperatives are accelerating replacement of inefficient legacy models under efficiency mandates.
- Solar:Photovoltaic arrays paired with DC brushless motors eliminate fuel logistics for off-grid operators. East African smallholder cooperatives and Rajasthan's farm clusters are the primary demand concentrators as lithium-ion storage costs compress payback periods.
- Hydraulic:Explosion-proof configurations serve underground mining dewatering where electrical ignition risks are prohibitive.
- Air-Driven:Pneumatic systems handle volatile hydrocarbon transfer in refinery sump applications requiring intrinsic safety.
Electrical configurations retain volume leadership; solar holds the steepest expansion curve.
Application:
Cost tier stratification separates price-sensitive agricultural volume from premium-margin industrial specifications.
- Wastewater Management:Solids-handling vortex and grinder pumps process raw sewage and stormwater overflow. Danish municipal utilities and Indonesian district water authorities are specifying hardened cast iron impellers to extend service intervals in abrasive media.
- Agricultural Irrigation:Borewell submersibles lift groundwater for field-scale distribution across India's Indo-Gangetic plain and Brazil's Cerrado mechanized farms. Diesel-to-electric conversion subsidies are restructuring procurement priorities in Punjab and Haryana.
- Industrial Processes:Chemical-resistant stainless steel housings manage corrosive coolant and process water recirculation.
- Oil & Gas Extraction:ESPs (electrical submersible pumps) handle crude lift and produced water disposal in mature conventional fields.
Agricultural irrigation commands absolute unit volumes; wastewater management delivers the most durable margin pools.
End User:
Customer type determines specification complexity, with public procurement favoring lifecycle cost models and private operators prioritizing capital efficiency.
- Municipalities:Centralized sewage and drinking water utilities specify energy efficiency certifications and 15-year service life guarantees. German Stadtwerke and Thai provincial waterworks are consolidating supplier panels to secure compliance with EU Ecodesign and local efficiency codes.
- Agriculture:Individual farmers and irrigation cooperatives select on first-cost and fuel displacement economics. India's PM-KUSUM scheme is channeling solar pump subsidies toward Punjab, Maharashtra, and Gujarat agrarian belts.
- Construction:Temporary dewatering for foundation excavation and tunneling drives rental fleet demand.
- Energy:Geothermal plant operators and oilfield service companies require high-temperature, high-head configurations.
Municipalities anchor premium specification demand; agriculture generates the highest absolute shipment volumes.
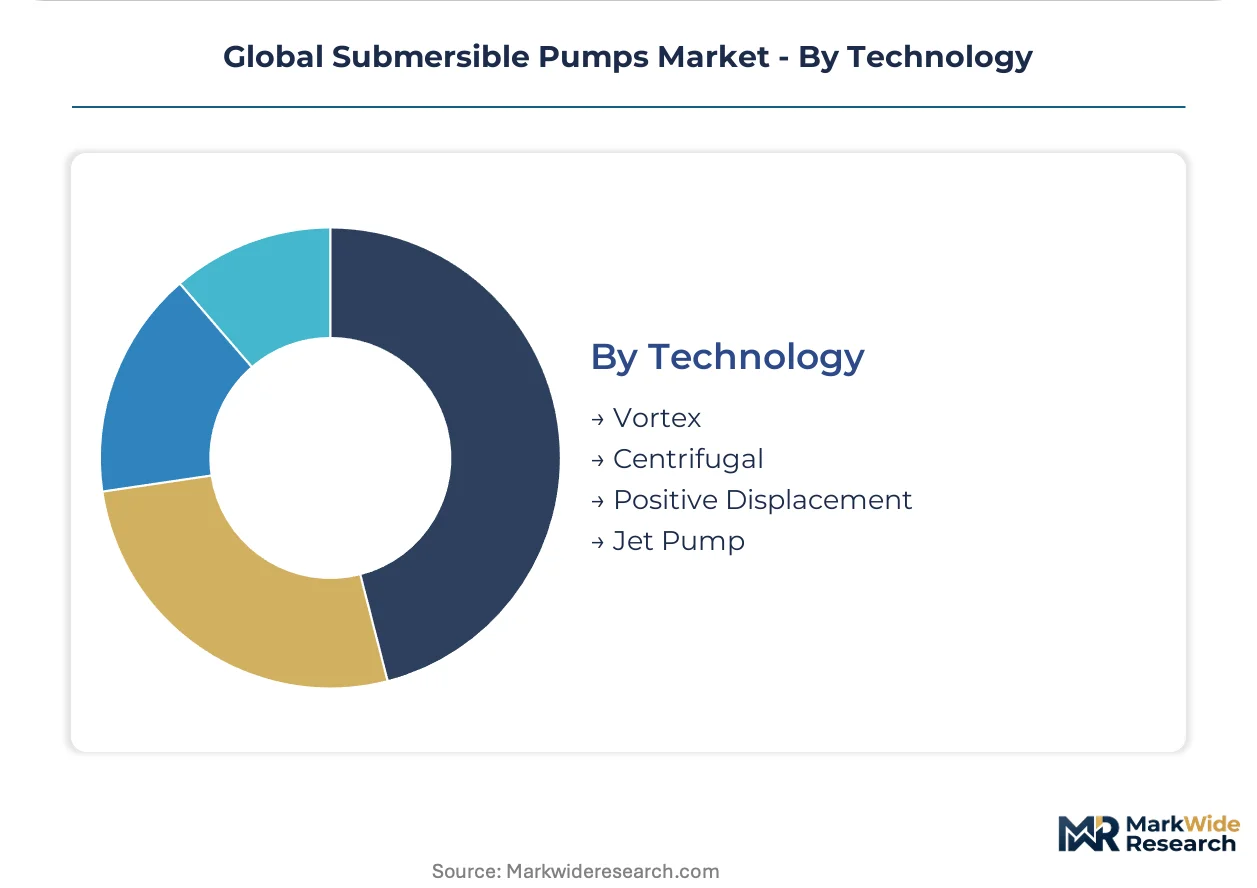
Technology:
Supply concentration in permanent magnet motor manufacturing is tilting competitive advantage toward centrifugal and vortex pump architectures.
- Centrifugal:Radial and mixed-flow impeller designs scale across head ranges from shallow drainage to deep borewell extraction. Chinese foundry clusters and Italian precision casting specialists are the primary sourcing nodes for hydraulic sections.
- Vortex:Recessed impeller configurations pass large solids and fibrous material without clogging. Netherlands-based water technology firms are embedding vortex pumps in smart sewer network monitoring systems.
- Positive Displacement:Progressive cavity and diaphragm mechanisms handle high-viscosity sludge and chemical metering.
- Jet Pump:Eductor configurations supplement centrifugal lift in shallow well applications with high sand content.
Centrifugal technology retains manufacturing scale dominance; vortex configurations are gaining share fastest in smart wastewater infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA efficiency standards anchor demand in the United States while EU Ecodesign regulations and China's GB standards create parallel compliance pathways across three distinct manufacturing geographies. Municipal wastewater upgrades and agricultural diesel displacement are restructuring procurement priorities in emerging and developed markets alike.
United States
California's Central Valley irrigation districts and Texas Permian Basin oilfield operators drive specification diversity. The Inflation Reduction Act subsidizes energy-efficient agricultural equipment upgrades. Houston hosts the largest concentration of ESP service providers for unconventional hydrocarbon extraction.
Germany
Ruhr Valley municipal utilities and Bavarian manufacturing clusters demand premium efficiency certifications. EU Ecodesign regulations under the EU Green Deal mandate lifecycle cost optimization in public procurement. Dortmund-based foundry networks supply hardened impeller castings for abrasive media applications.
China
Zhejiang and Jiangsu province pump manufacturing clusters serve domestic agricultural electrification and export markets simultaneously. GB standards for motor efficiency create compliance thresholds for local production. Taizhou's foundry district is expanding stainless steel casting capacity for chemical-resistant configurations.
India
Punjab and Haryana agrarian belts are converting diesel borewell sets to electric and solar-powered systems under PM-KUSUM subsidies. BIS certification requirements shape import substitution strategies. Coimbatore's motor-winding cluster is scaling permanent magnet synchronous production for high-head agricultural specifications.
Brazil
Cerrado mechanized farms and Minas Gerais mining operations generate divergent specification demand. ANVISA and environmental licensing requirements govern industrial water management equipment. São Paulo state's pump distributors are consolidating solar-irrigation product portfolios for northeastern semi-arid expansion.
Global Submersible Pumps Market Vendor Landscape
Capability concentration sits with European specialists commanding premium efficiency tiers; scale advantage sits with Asian foundry-integrated manufacturers. The market structures around three tiers: vertically integrated European OEMs with captive motor production, Chinese fabricators with foundry-to-assembly cost structures, and regional specialists serving abrasive media niches. Dominant competitive moves include permanent magnet motor platform standardization and predictive maintenance service bundling.
Among Danish and German engineering groups, Grundfos Holding A/S and KSB SE & Co. KGaA exemplify the premium-tier archetype with vertically integrated European manufacturing. Xylem Inc. anchors the digital-integrated segment through its dewatering portfolio positioning. These three represent contrasting pathways: captive supply chain control, heavy-duty borewell specialization, and software-enabled performance optimization respectively.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| Sulzer Ltd. |
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| Franklin Electric Co., Inc. |
| Ebara Corporation |
| Tsurumi Manufacturing Co., Ltd. |
| WILO SE |
| Others |
Supply Flow & Price Mechanics
Taizhou's foundry district in Zhejiang province anchors global casting capacity for stainless steel pump housings, concentrating upstream leverage that translates into tiered pricing power across export markets. Chinese motor-winding clusters in Jiangsu and permanent magnet processing facilities in Inner Mongolia feed cost-advantaged platforms that undercut European premium tiers by thirty to fifty percent on comparable hydraulic specifications. Municipal utilities in Germany and Denmark absorb these premiums for EU Ecodesign-certified equipment, while Indian agricultural cooperatives and Vietnamese irrigation districts gravitate toward standard-grade configurations sourced through Guangdong trading houses.
Pricing Analysis
European-Delhi price spreads exceed forty percent for equivalent borewell capacities, with German Stadtwerke paying lifecycle-cost premiums against Punjabi farmers selecting on first-cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling. Cost compression in economy tiers is intensifying because Chinese fabricators are absorbing rare-earth magnet volatility through backward integration into permanent magnet supply. Agricultural cooperatives exhibit highest price sensitivity; German municipal utilities least.
Supply Chain Analysis
Zhejiang foundries and Jiangsu motor assemblers hold dominant contract-manufacturing capacity for global OEMs sourcing standard-grade equipment. Raw material dependencies center on copper winding wire from Chinese smelters, neodymium-iron-boron magnets from Inner Mongolia processing facilities, and electrical steel from Baosteel and Nippon Steel mills. Single-source vulnerability concentrates in rare-earth magnet supply where Chinese export licensing creates regulatory chokepoints. Distribution runs through regional pump distributors in São Paulo, Lagos, and Jakarta who maintain localized inventory for agricultural aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor engineering talent and hardened impeller metallurgy expertise are scarce assets that constrain competitive replication across efficiency tiers. Foundry-integrated manufacturers with captive motor production command structural advantages that pure assemblers cannot readily match.
For Market Incumbents: Insulate premium positioning by accelerating permanent magnet platform standardization across agricultural and municipal product lines. Defend against Chinese cost leaders by embedding predictive maintenance software that locks in long-term service contracts with Dutch and Danish utilities. Expand captive supply of electrical steel laminations to offset magnet price volatility exposure. For New Entrants and Emerging Players: Pursue solar-electrical hybrid configurations for East African smallholder markets where grid extension remains uneconomical and incumbent distribution is sparse. Target Kenyan and Tanzanian irrigation cooperatives through pay-per-use equipment-as-a-service models that eliminate capital barriers. Partner with lithium-ion storage integrators to bundle DC brushless pumps with battery systems for off-grid deployment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because municipal wastewater infrastructure replacement cycles and agricultural diesel displacement create durable installed-base expansion. Target mid-tier European specialists with EU Ecodesign certification pipelines and established Stadtwerke relationships. Monitor permanent magnet price indices and Chinese export license issuance frequency as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Platform Standardization | Grundfos and KSB capture EU Ecodesign compliance advantages across agricultural and municipal segments. |
| Predictive Maintenance Service Bundling | Xylem's vibration-sensor integration locks in fifteen-year municipal contracts with Dutch water authorities. |
| Solar-Electrical Hybrid Product Expansion | Franklin Electric and Ebara target Rajasthan farm clusters under PM-KUSUM subsidy schemes. |
| Foundry Capacity Expansion in Zhejiang | Chinese fabricators absorb stainless steel casting demand from chemical-resistant industrial specifications. |
| Equipment-as-a-Service Model Piloting | Danish utilities transfer operational risk to OEMs while securing guaranteed maintenance revenue streams. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with pump OEM product managers, municipal utility procurement officers, agricultural cooperative equipment heads, and aftermarket service technicians; and secondary validation through customs trade databases, SEC 10-K filings, EU Ecodesign registration records, and BIS certification listings. Bottom-up triangulation across regional shipment estimates and top-down cross-checks against foundry capacity utilization produced convergent volume and value outputs.
Forecast inputs span power source segmentation, application-tier margin structures, end-user procurement sophistication, and technology-platform efficiency trajectories across the analysis window. CAGRs derive from regression analysis against agricultural electrification rates, wastewater infrastructure investment pipelines, and solar PV cost curves. Modeled variables include diesel-to-electric conversion subsidies, rare-earth magnet price elasticity, and municipal lifecycle-cost procurement adoption.
Sensitivities concentrate around Chinese rare-earth export policy shifts, EU Ecodesign enforcement timing, and Indian state-level subsidy disbursement continuity. Forecasts reflect documented assumptions regarding permanent magnet cost trajectories and agricultural electrification penetration curves. Quarterly review of magnet price indices, BIS certification issuance rates, and PM-KUSUM disbursement data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Wind Powered Water Pumps Market