
 Global Flow Control Market | 2026-2036
Global Flow Control Market Size, Share, and Industry Trends Forecast 2026-2036
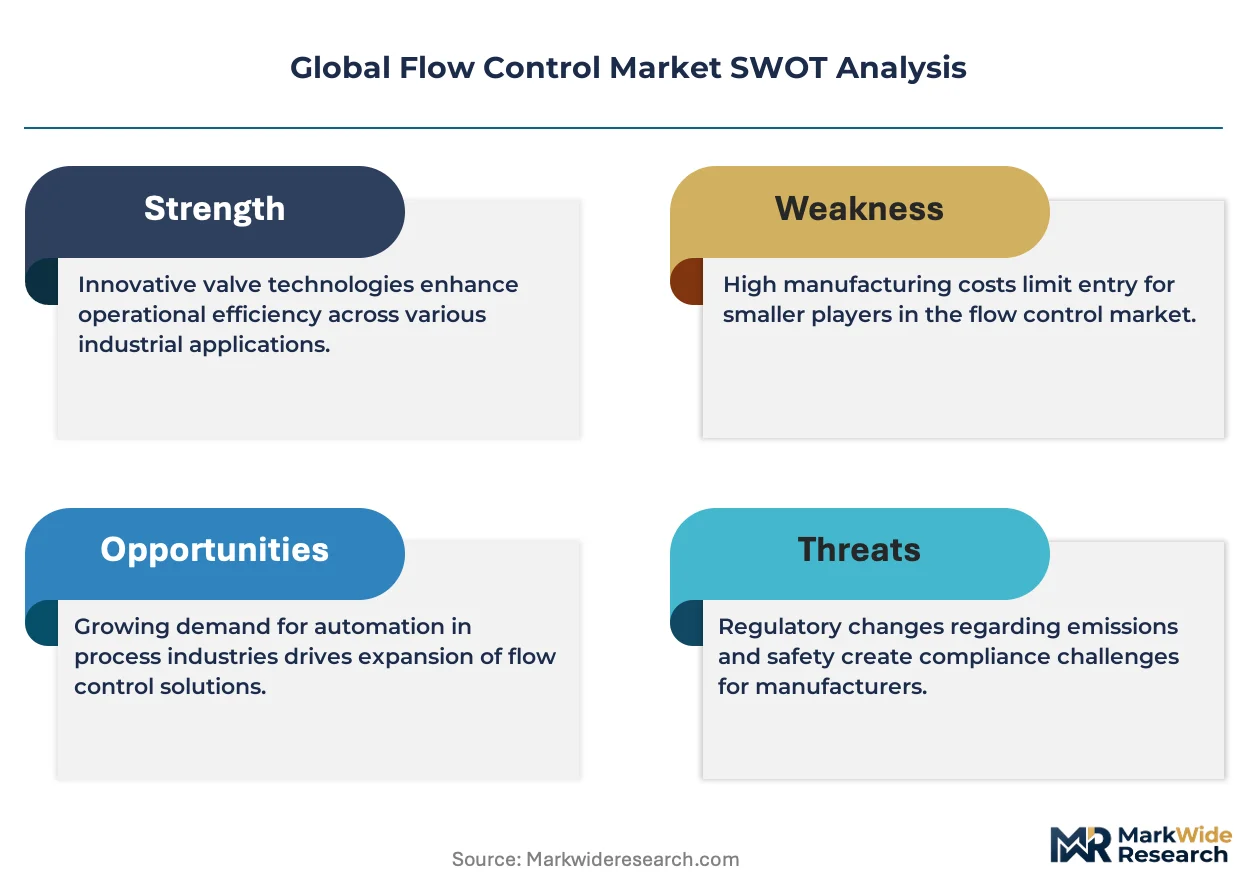
Global Flow Control Market Analysis
The EPA Lead and Copper Rule is decoupling legacy valve specifications from new procurement criteria, forcing municipal buyers to recertify supplier qualifications. Siemens AG leverages its digital twin platforms to anchor long-term service contracts with North American water authorities. Emerson Electric Co. sustains R&D intensity across its Fisher valve portfolio, while Flowserve Corporation dominates severe-service applications in upstream hydrocarbon processing.
Flow control encompasses the mechanical and electromechanical systems that modulate fluid dynamics through pipelines, vessels, and process equipment, typically operating across pressure ratings from ANSI Class 150 to 4500 and temperature ranges spanning cryogenic to 815°C. These systems enable precise management of mass transfer, thermal exchange, and chemical reaction kinetics in continuous and batch operations. Valves capture the dominant share of product-type revenue due to replacement cycles in aging petrochemical infrastructure, while automated technology segments expand fastest as distributed control system integration becomes standard in greenfield chemical processing facilities. Oil and gas end users still represent the deepest margin pools, though water treatment applications are accelerating on the back of non-revenue water reduction mandates.
The EPA enforces maximum contaminant levels that dictate material selection and sealing performance in potable water applications, while REACH restricts hazardous substance content in valves exported to European process industries. China's MEE imposes emission intensity thresholds that directly determine actuator specification requirements for domestic refinery expansions. Stakeholders must monitor how carbon border adjustment mechanisms in the European Union and prospective U.S. analogs reshape sourcing economics for cast and forged valve bodies.
Market Dynamics
The EPA Lead and Copper Rule revisions are decoupling legacy valve specifications from new procurement criteria, forcing municipal water authorities to recertify supplier qualifications and accelerating replacement cycles across aging distribution infrastructure.
Growth Catalysts
- Water treatment automation:Utilities are scaling automated valve deployments to meet tightening effluent standards. Distributed control system integration becomes standard in greenfield chemical processing facilities.
- China's pipeline modernization:State-owned water groups execute multi-billion-yuan infrastructure programs. Domestic refinery expansions drive actuator specification upgrades under MEE emission intensity thresholds.
- REACH material compliance:European process industries face hazardous substance restrictions in valve exports. Cast and forged body sourcing economics reshape under carbon border adjustment mechanisms.
Market Restraints
- Specialty alloy cost volatility:Nickel and chromium price swings squeeze margins on severe-service valve production. Foundry capacity concentrates in select Asian supply basins.
- REACH compliance friction:European chemical registrants face extended substance evaluation timelines. Small-batch valve exporters absorb disproportionate testing burdens relative to volume.
- Electromechanical actuator substitution:Pneumatic systems face displacement in low-pressure municipal applications. Compressed air infrastructure maintenance costs drive buyer preference shifts.
Strategic Opportunities
- India municipal water infrastructure:AMRUT 2.0 allocations expand smart metering and pressure management deployments. State-level urban development authorities consolidate procurement authority.
- Hydrogen economy valve applications:Cryogenic and high-pressure ratings gain relevance in electrolyzer and fueling station builds. Green hydrogen project pipelines in Germany and Spain specify severe-service isolation requirements.
- Digital twin convergence:Physics-based simulation merges with real-time sensor feeds for predictive maintenance. North American water authorities anchor long-term service contracts around integrated platform deployments.
Industry Challenges
- Field engineering talent scarcity:Commissioning specialists for integrated valve-actuator-controller systems remain in short supply. OEM service organizations compete with system integrators for experienced personnel.
- Legacy DCS integration complexity:Brownfield chemical facilities require protocol translation layers for smart valve positioners. Project timelines extend where original control system documentation is incomplete.
- Fugitive emissions certification delays:ISO 15848-1 testing backlog stretches supplier qualification timelines. Third-party laboratory capacity constraints bottleneck new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flow Control Market |
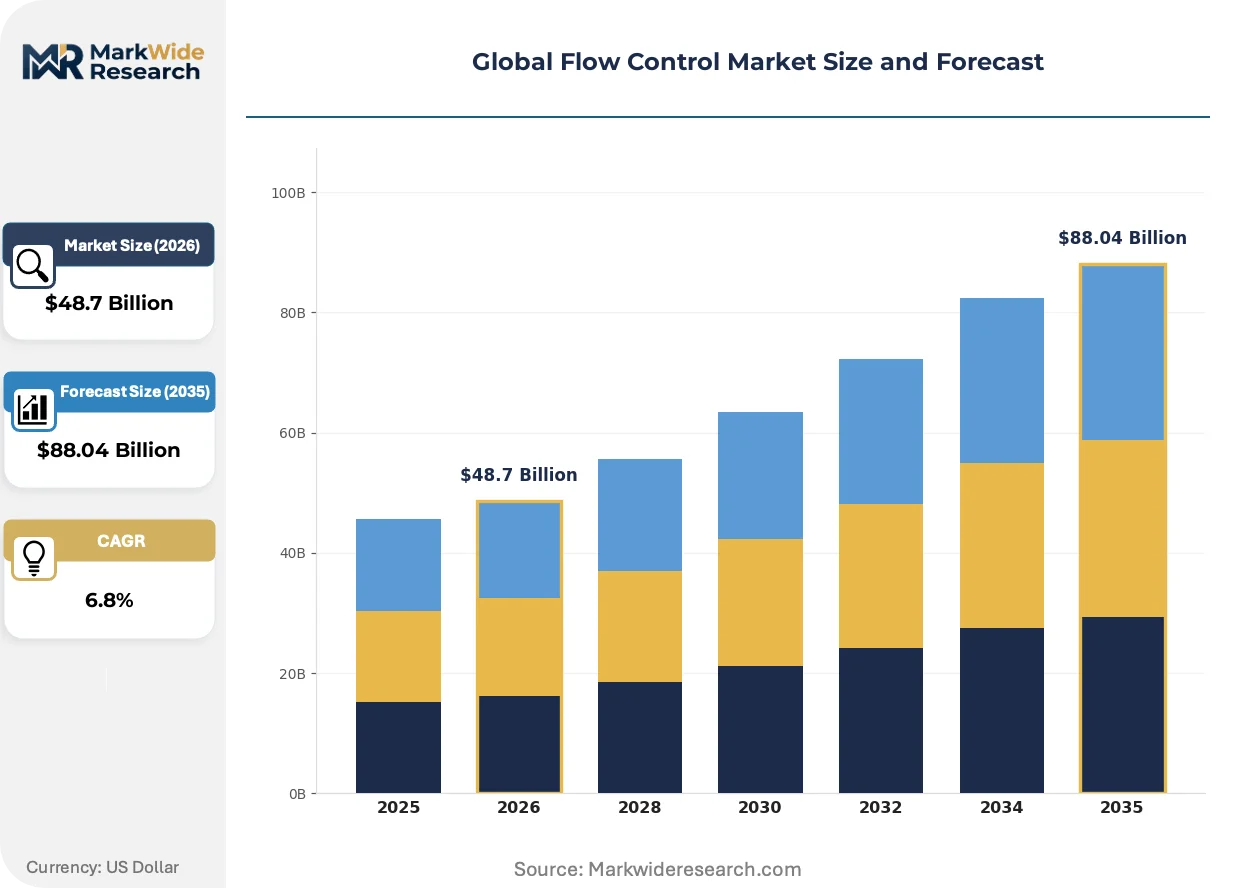
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Actuators, Regulators, Dampers Technology: Automated, Manual, Pneumatic, Hydraulic End User: Oil & Gas, Water Treatment, Chemical Processing, Power Generation Application: Pressure Control, Flow Regulation, Level Control, Temperature Management |
| Companies Covered | Siemens AG, Schneider Electric SE, Emerson Electric Co., Crane Holdings Co., Parker Hannifin Corporation, Flowserve Corporation, Alfa Laval AB, Valmet Oyj, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flow Control Market Emerging Trajectories
Intelligent valve positioners and edge-computing actuators are compressing the traditional separation between mechanical flow control and process optimization software. Equipment suppliers now compete on data architecture integration rather than pressure ratings alone.
Digital twin technology is consolidating vendor-customer relationships around continuous performance monitoring rather than episodic maintenance. Siemens anchors long-term service contracts with North American water authorities through physics-based simulation platforms. Equipment procurement decisions now weight software roadmap maturity equally with mechanical specifications.
REACH restrictions on hazardous substance content are forcing material science investments in sealing technologies. European process industries face compliance deadlines that compress supplier qualification timelines. Valve exporters to the EU are accelerating fluoropolymer alternative development to maintain market access.
Buying patterns among municipal water authorities are fragmenting as federal infrastructure funding flows through state revolving loan programs. Specification authority decentralizes to regional engineering consultants who prioritize total lifecycle cost over first-cost procurement. California and Texas utilities now lead in outcome-based maintenance contracting for automated valve networks.
Global Flow Control Market Segmentation
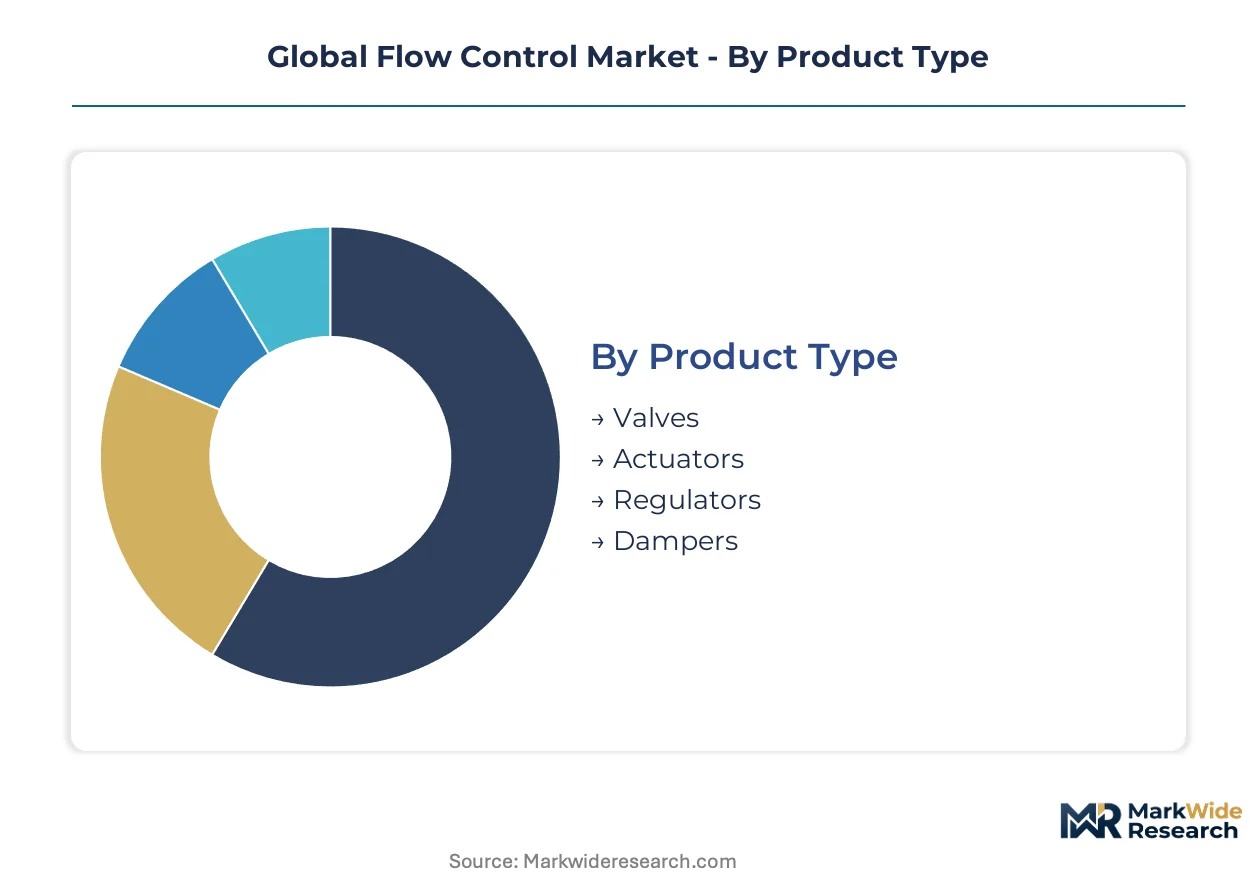
Flow control procurement decisions cascade through multiple technical and commercial dimensions. Specification authority varies sharply across product categories, with capital intensity and lifecycle cost calculations driving final vendor selection.
Product Type:
Capital intensity peaks in severe-service valve assemblies requiring exotic alloy castings and precision machining, while actuator investments scale with control system integration complexity.
- Valves:These assemblies modulate fluid pathways through disc, ball, or plug mechanisms rated from ANSI Class 150 to 4500. Demand concentrates in U.S. municipal water authorities replacing lead-contaminated legacy infrastructure under EPA Lead and Copper Rule mandates. Replacement cycles compress as tighter effluent standards force premature retirement of older cast-iron bodies.
- Actuators:Electromechanical and pneumatic drive systems convert control signals into mechanical valve positioning. China's state-owned water groups specify intelligent electric actuators for multi-billion-yuan pipeline modernization programs. MEE emission intensity thresholds dictate actuator selection for domestic refinery expansions.
- Regulators:Self-operating pressure control devices maintain downstream setpoints without external power.
- Dampers:Multi-vane or louvered flow control elements manage combustion air and flue gas in power generation.
Most installed capacity flows through Valves. Expansion is steepest in Actuators.
Technology:
Technology selection pivots on pressure-temperature ratings and response speed requirements, with automated systems commanding premium pricing for distributed control integration.
- Automated:Microprocessor-based valve positioners and networked actuators enable real-time process optimization. Greenfield chemical processing facilities in Germany and Spain specify automated technology as standard for hydrogen economy applications. Digital twin convergence anchors long-term service contracts with predictive maintenance capabilities.
- Pneumatic:Compressed air-driven actuation dominates high-cycle industrial applications. Compressed air infrastructure maintenance costs are displacing pneumatic preference in low-pressure municipal water applications across India AMRUT 2.0 deployments.
- Manual:Handwheel or lever-operated devices persist in isolation and bypass service.
- Hydraulic:Oil-pressure actuation serves high-force requirements in subsea and severe-service upstream hydrocarbon processing.
Manual technology retains the largest installed base. Automated systems are gaining share fastest.
End User:
End-user margins vary with asset criticality, with oil and gas commanding deepest pools while water treatment accelerates on regulatory enforcement.
- Oil & Gas:Upstream, midstream, and downstream operations require severe-service isolation and control. Flowserve Corporation dominates high-pressure high-temperature applications in upstream hydrocarbon processing. Fugitive emissions certification delays under ISO 15848-1 stretch supplier qualification timelines.
- Water Treatment:Municipal utilities and industrial effluent facilities deploy automated networks for non-revenue water reduction. California and Texas utilities lead outcome-based maintenance contracting for automated valve networks. Federal infrastructure funding decentralizes specification authority to regional engineering consultants.
- Chemical Processing:Batch and continuous operations demand corrosion-resistant materials and precise flow modulation.
- Power Generation:Thermal and renewable facilities require steam conditioning and cooling water management.
Chemical Processing holds the most mature installed base. Water Treatment shows the steepest expansion trajectory.
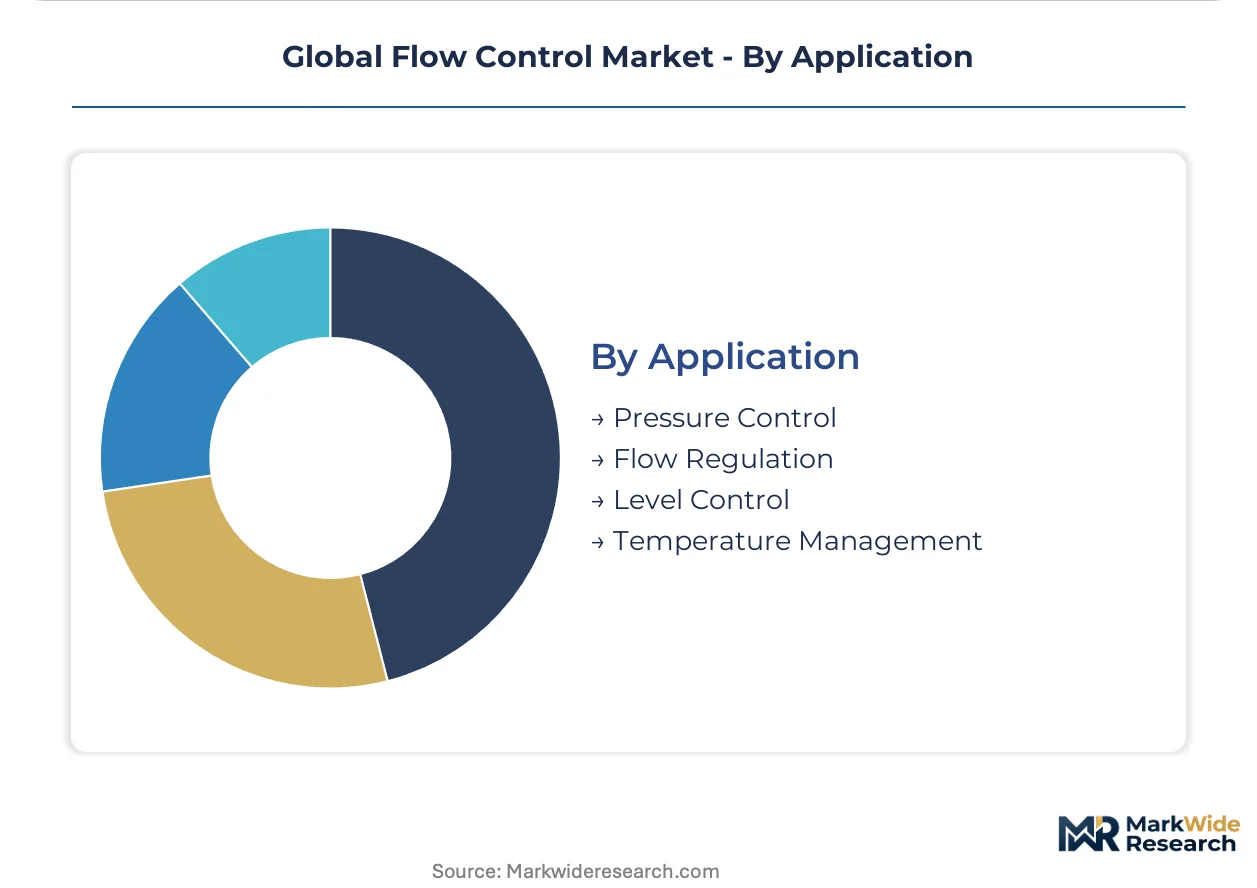
Application:
Application segmentation reflects process control hierarchy, with pressure and flow functions commanding higher specification authority than secondary thermal management.
- Pressure Control:Relief valves, regulators, and control valves maintain system boundaries against overpressure or vacuum conditions. Siemens AG leverages digital twin platforms for continuous performance monitoring in North American water authority contracts. Physics-based simulation merges with real-time sensor feeds for predictive maintenance.
- Flow Regulation:Throttling and on-off valves manage mass transfer rates in continuous processes. REACH hazardous substance restrictions force material science investments in sealing technologies for European process industry compliance.
- Level Control:Float and displacer-actuated valves maintain vessel inventory.
- Temperature Management:Mixing valves and heat exchanger bypass controls moderate thermal profiles.
Flow Regulation accounts for the greatest installed volume. Pressure Control is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commissioning specialists for integrated valve-actuator-controller systems cluster in Germany, the United States, and China, anchoring regional service capabilities. These talent pools shape where OEMs locate technical centers and where complex projects secure field engineering support.
United States
Municipal water authorities drive automated valve procurement to replace lead-contaminated legacy infrastructure under EPA Lead and Copper Rule mandates. Federal infrastructure funding flows through state revolving loan programs, decentralizing specification authority to regional engineering consultants in California and Texas. Outcome-based maintenance contracting for automated valve networks now dominates procurement in these states.
China
State-owned water groups execute multi-billion-yuan pipeline modernization programs requiring intelligent electric actuators. MEE emission intensity thresholds dictate actuator specifications for domestic refinery expansions. Yangtze River Delta industrial clusters concentrate foundry capacity for severe-service valve castings serving both domestic and export demand.
Germany
Green hydrogen project pipelines specify cryogenic and high-pressure severe-service isolation requirements for electrolyzer builds. REACH hazardous substance restrictions force material science investments in fluoropolymer sealing alternatives. Ruhr industrial basin facilities anchor predictive maintenance platform deployments through physics-based simulation integration.
India
AMRUT 2.0 allocations expand smart metering and pressure management valve deployments across state-level urban development authorities. Compressed air infrastructure maintenance costs drive buyer preference shifts toward electromechanical actuators in low-pressure municipal applications. Gujarat and Maharashtra industrial corridors concentrate procurement authority consolidation efforts.
Japan
Precision machining capabilities for exotic alloy valve components concentrate in Nagoya and Osaka industrial clusters. METI standards shape domestic refinery actuator specifications for emission intensity compliance. Domestic OEMs anchor long-term service contracts through integrated digital twin platforms for continuous performance monitoring.
Global Flow Control Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive control system portfolios. Tier-one positions concentrate among firms combining valve manufacturing with distributed control system integration capabilities. Three archetypes dominate: full-stack automation providers, severe-service specialists, and component-focused fabricators. Strategic moves center on digital twin platform licensing and backward integration into exotic alloy foundry capacity.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the full-stack automation archetype through its digital twin platform deployments. Emerson Electric Co. and Flowserve Corporation occupy distinct specialist positions within the competitive map. These three firms represent the spectrum from integrated control system providers to severe-service application-focused suppliers.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| Emerson Electric Co. |
| Crane Holdings Co. |
| Parker Hannifin Corporation |
| Flowserve Corporation |
| Alfa Laval AB |
| Valmet Oyj |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Intelligent actuator migration from pneumatic to electromechanical architectures simultaneously compresses lifecycle cost economics and concentrates procurement authority among control system integrators with platform-level bundling power. Municipal water authorities in California and Texas now weight software roadmap maturity equally with mechanical specifications, reshaping how suppliers capture margin across hardware-software boundaries.
Pricing Analysis
Bundled digital twin service contracts versus unbundled component procurement defines the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG's integrated platform deployments from Fisher valve standalone sales and commodity cast-iron replacements. Price differentiation rests on ISO 15848-1 certification grade and distributed control system integration depth. Cost compression in standard-tier pneumatic actuators is intensifying because electromechanical substitution accelerates in low-pressure municipal applications. Regional engineering consultants in federal infrastructure-funded states exhibit highest price sensitivity; severe-service hydrocarbon processors show least.
Supply Chain Analysis
Dual-sourcing requirements mandated by North American water authorities and European process industries force qualification of secondary foundry partners. Geographic supply concentration centers on China for Yangtze River Delta casting capacity, Germany for precision machining clusters, and India for AMRUT 2.0 deployment manufacturing. Raw material dependencies hinge on nickel-chromium alloy feedstock, fluoropolymer sealing compounds, and rare-earth permanent magnets for intelligent actuators. Single-source vulnerability concentrates in exotic alloy foundry capacity serving severe-service applications. Distribution runs through OEM direct sales for large project deployments and specialized distributors for replacement part fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flow control rests on digital twin platform bundling that captures recurring service revenue above commodity hardware replacement cycles. Electromechanical actuator cost curves and REACH-compliant material substitutions enable premium-tier positioning.
For Market Incumbents: Hedge against electromechanical displacement in pneumatic-dominant segments by accelerating backward integration into rare-earth magnet supply chains and fluoropolymer alternative R&D. Anchor long-term service contracts through physics-based simulation platforms before regional engineering consultants consolidate procurement authority. Certification investment in ISO 15848-1 fugitive emissions testing capacity defends position against qualification backlog bottlenecks.
For New Entrants and Emerging Players: Edge-computing actuator architectures with native distributed control system protocols offer entry into brownfield chemical facility retrofit demand. White-space targets concentrate in India AMRUT 2.0 smart metering deployments and Germany-Spain green hydrogen electrolyzer isolation requirements. Outcome-based maintenance contracting for municipal water authorities provides the most penetrable go-to-market angle against incumbent episodic service models.
For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused fabricators lacking digital twin platform capabilities or captive control system portfolios. Long-term viability across the projection horizon favors full-stack automation providers and severe-service specialists with Yangtze River Delta foundry access. Acquisition target archetype: mid-cap valve manufacturers with established REACH compliance and unexploited hydrogen economy ratings. Watch MEE emission intensity threshold tightening as inflection indicator for Chinese domestic refinery expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Licensing | Siemens AG anchors North American water authority contracts through physics-based simulation integration. |
| Backward Integration into Exotic Alloy Foundry Capacity | Flowserve Corporation secures severe-service casting supply for upstream hydrocarbon processing dominance. |
| REACH-Compliant Fluoropolymer Alternative Development | European valve exporters maintain market access against hazardous substance restriction deadlines. |
| Intelligent Electric Actuator Scale-Up | China's state-owned water groups specify networked actuators for multi-billion-yuan pipeline programs. |
| Outcome-Based Maintenance Contracting | California and Texas utilities shift procurement from first-cost to lifecycle cost optimization. |
Methodological Framework
Direct dialogue with plant engineers at municipal water authorities, procurement leads at state-owned refinery operators, aftermarket service heads at severe-service valve OEMs, and distributed control system integrators anchored qualitative grounding. Secondary validation drew from EPA Lead and Copper Rule revision filings, MEE emission intensity threshold documentation, REACH substance evaluation timelines, and customs data on alloy valve trade flows. Bottom-up and top-down triangulation cross-checked unit shipment estimates against capital expenditure disclosures in water infrastructure and hydrocarbon processing sectors.
Bottom-up volume modeling built from product-type segmentation across valves, actuators, regulators, and dampers, intersected with technology tiers, end-user industries, and application functions. Top-down demand validation referenced federal infrastructure funding allocations, state revolving loan program disbursements, and green hydrogen project pipeline announcements. CAGRs derived from regression analysis of historical replacement cycles against regulatory enforcement acceleration. Industry-specific forecast inputs incorporated ISO 15848-1 certification backlog duration and intelligent actuator penetration curves in municipal water automation.
The model holds under stable alloy price volatility and continued EPA-MEE-REACH regulatory enforcement trajectories; deviation in nickel-chromium cost spikes or carbon border adjustment mechanism implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Curb Valves Market
Valves
Mooring Inspection Market
Valves
Pneumatic Positioner Market
Valves
Global Control Valves Market
Valves
Hydraulic Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Butterfly Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Manual Control Valve Market
Valves
Angle Opening Ball Locator Market
Valves
Emergency Venting System Market
Valves
Global Plug Valve Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Safety Valve Market
Valves
Pipeline Strainers Market
Valves
Mechanical Shaft Seal Market