
 United Kingdom Oil and Gas Midstream Market | 2026-2036
United Kingdom Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Oil and Gas Midstream Market Analytics
Software-defined pipeline monitoring is hardening into a standard service layer across UK midstream contracts. SSE PLC leverages its North Sea infrastructure footprint to bundle digital monitoring with capacity reservations. INEOS Capital Limited anchors its Grangemouth operations with integrated terminal-to-refinery logistics control. Navigator Holdings Ltd. competes on specialized liquefied gas shipping routes serving British import terminals.
The United Kingdom oil and gas midstream sector encompasses transportation, storage, processing, and distribution activities between upstream extraction and downstream refining, operating through pipelines with typical diameters of 24-48 inches for trunk lines and pressure ratings up to 1440 psi. Its primary purpose moves crude oil, natural gas, and NGLs from North Sea platforms and import terminals to domestic refineries, power stations, and petrochemical complexes. Pipeline transport dominates value capture given the maturity of the UK continental shelf pipeline network, while LNG facilities represent the fastest-growing service type as Britain deepens import dependence post-domestic production decline. Storage terminals retain stable margin pools due to strategic reserve obligations and seasonal demand balancing.
The North Sea Transition Authority governs offshore pipeline licensing and decommissioning bonds, while the Health and Safety Executive enforces pipeline integrity management under PSR 1996 regulations. Ofgas shapes market access through third-party tariff structures for national transmission systems. Stakeholders must monitor hydrogen blending mandates and carbon capture readiness standards that will determine which legacy pipelines secure repurposing licenses versus early retirement.
Market Dynamics
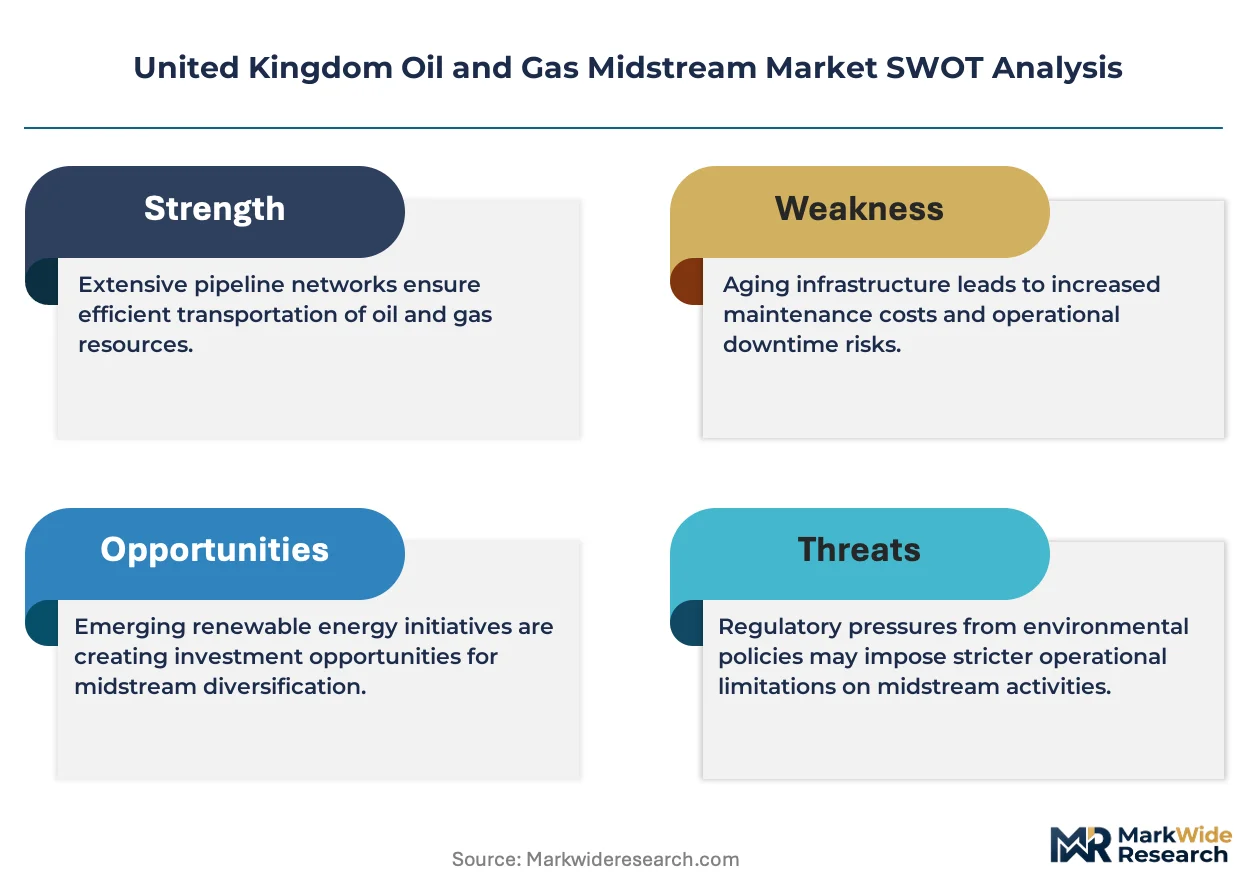
The North Sea Transition Authority's accelerated decommissioning timelines are compressing asset lifecycles across United Kingdom pipeline networks, forcing operators to choose between costly life-extension investments and premature infrastructure retirement before hydrogen-ready repurposing standards crystallize.
Growth Catalysts
- Power generation offtake expansion:UK utilities are securing long-term capacity reservations on trunk pipelines serving combined-cycle gas turbine facilities, locking in transport volumes that stabilize midstream revenue baselines.
- Hydrogen-ready corridor development:The government's hydrogen production targets are concentrating investment around pipeline routes connecting Scottish offshore wind zones to Grangemouth industrial clusters.
- PSR 1996 integrity mandates:Health and Safety Executive enforcement of pipeline safety regulations is driving replacement cycles for aging North Sea infrastructure, creating sustained demand for inspection and rehabilitation services.
Market Restraints
- Domestic production decline:Maturing North Sea fields are reducing throughput volumes on legacy trunk lines, stranding capacity and diluting per-unit transport economics.
- Steel input volatility:Pipeline construction costs fluctuate with global steel plate prices, complicating long-dated capex planning for operators facing uncertain hydrogen conversion timelines.
- Import terminal concentration:LNG receiving capacity clusters at three coastal sites, creating single-point vulnerability and limiting route diversification for supply security.
Strategic Opportunities
- Carbon capture readiness licensing:The North Sea Transition Authority's emerging CO2 transport framework offers first-mover advantages for pipelines securing dual-use oil and carbon dioxide certification.
- Terminal-to-refinery digital integration:Real-time inventory optimization across INEOS Grangemouth and neighboring storage facilities is compressing working capital cycles for integrated operators.
- Scottish hydrogen backbone conversion:SGN's network repurposing trials in Aberdeen and Fife are establishing regulatory precedents for blending-ready infrastructure standards.
Industry Challenges
- Subsea engineering talent scarcity:Specialist pipeline inspection and repair capabilities are concentrating among retiring workforce cohorts, constraining decommissioning execution capacity.
- Hydrogen embrittlement material science:Uncertainty around steel compatibility with high-pressure hydrogen transport is delaying final investment decisions on conversion projects.
- Third-party access tariff disputes:Ofgas pricing reviews are creating regulatory lag between cost recovery claims and approved revenue allowances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Oil and Gas Midstream Market |
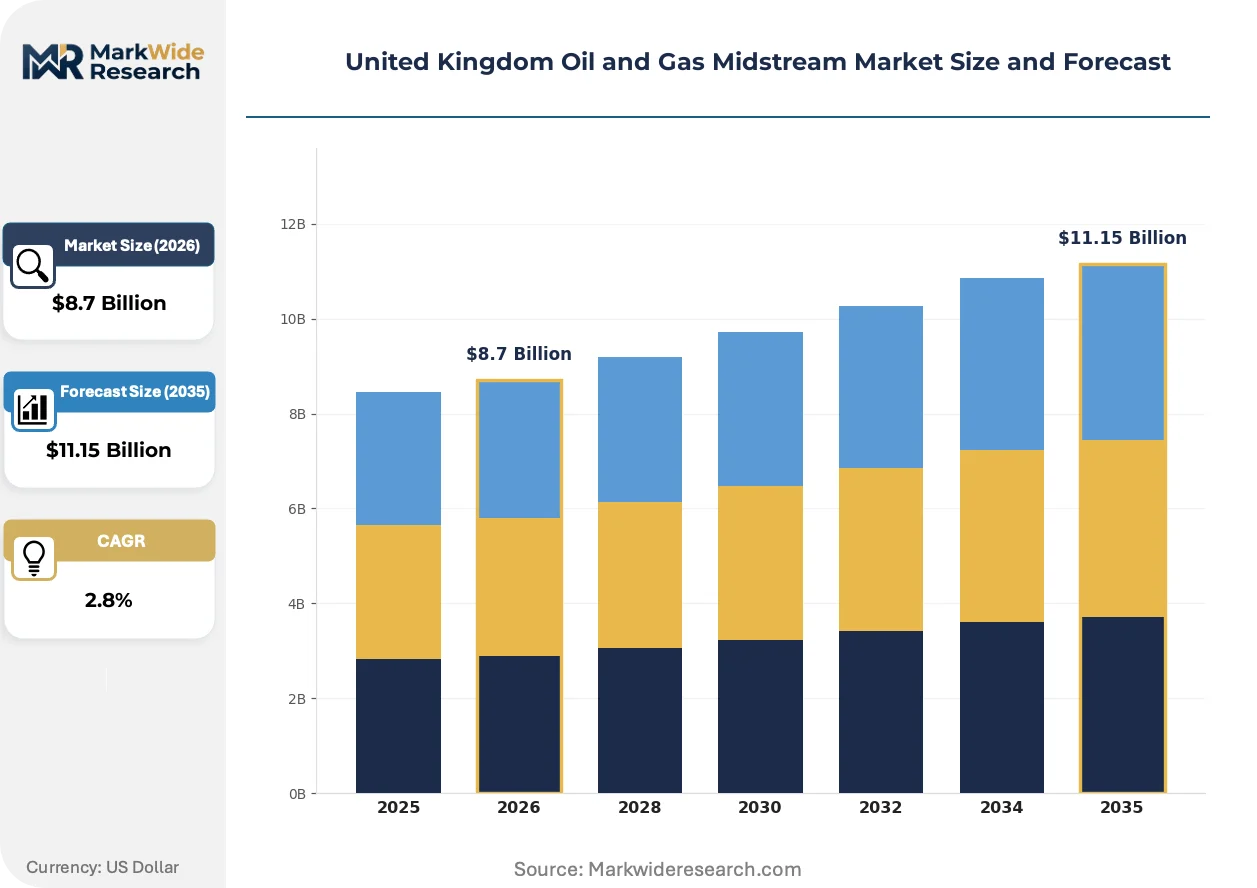
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transportation, Storage, Processing, Distribution Service Type: Pipelines, Tankers, Terminals, Processing Facilities End User: Refineries, Petrochemical Plants, Utility Companies, Traders Technology: Pipeline Transport, Pumping Systems, LNG Facilities, Monitoring Systems |
| Companies Covered | SSE PLC, ConocoPhillips Company, Storengy SA, Navigator Holdings Ltd., TORM plc, GASSCO, Interconnector Limited, INEOS Capital Limited, E.ON UK plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Oil and Gas Midstream Market Evolving Landscape
Digital layer integration is compressing operational response times across United Kingdom midstream assets, unifying previously siloed monitoring functions into continuous feedback systems that reshape maintenance economics and regulatory compliance workflows.
Software-defined pipeline monitoring is unifying leak detection, pressure management, and predictive corrosion analytics into single-platform architectures. North Sea operators are deploying these systems across aging trunk lines where manual inspection cycles previously dominated integrity management. The convergence is compressing incident response windows from days to hours while reducing regulatory inspection burden through automated compliance documentation.
The North Sea Transition Authority's decommissioning security bonds framework is forcing asset owners to prefund end-of-life liabilities. Offshore pipeline operators must now demonstrate financial provision for full removal costs before license extensions, reshaping portfolio valuation methodologies. Scottish sector assets face the steepest compliance pressure given concentration of aging infrastructure and proximity to sensitive fishing grounds.
Utility procurement patterns are compressing contract durations from decade-long capacity reservations toward shorter-term flexible offtake agreements. Power generators serving balancing markets prefer interruptible transport terms that align with renewable intermittency, displacing baseload pipeline commitments. This rotation is most visible in northern England corridor negotiations where CCGT operators negotiate seasonal swing capacity rather than flat annual volumes.
United Kingdom Oil and Gas Midstream Market Segmentation
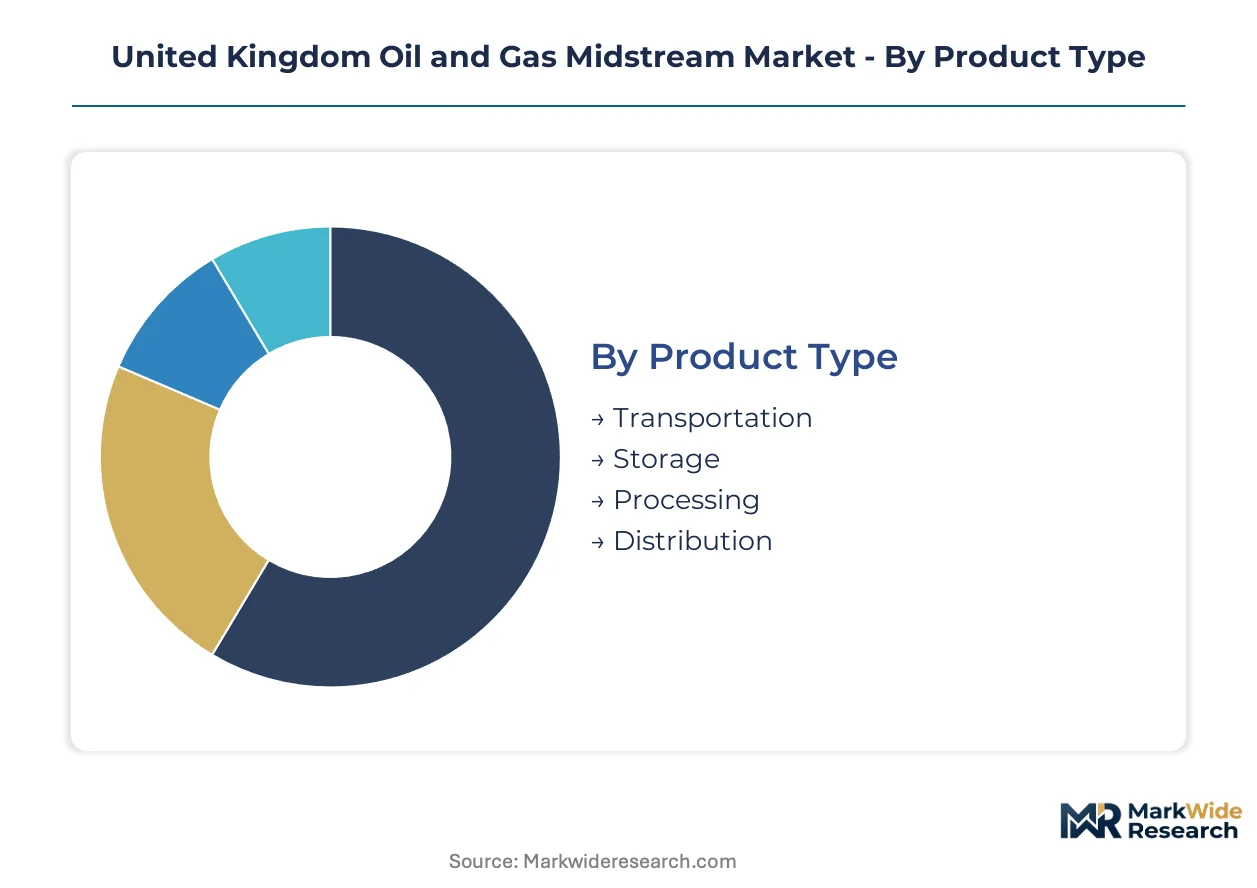
Midstream operators in the United Kingdom configure service portfolios around infrastructure maturity and hydrogen conversion timelines. Segment boundaries are blurring as pipeline assets pivot from pure hydrocarbon transport to dual-use carbon and hydrogen corridors.
Product Type:
Standalone transport services dominate contracted revenue, while integrated processing-storage bundles capture margin premiums in Grangemouth and Teesside clusters.
- Transportation:Trunk pipelines with 24-48 inch diameters and pressure ratings up to 1440 psi move crude and natural gas from North Sea platforms to onshore terminals. Scottish corridors serving offshore wind-to-hydrogen zones are locking in the longest reservation contracts as utilities secure carbon-neutral feedstock routes.
- Storage:Strategic reserve terminals and seasonal balancing facilities maintain stable margin pools under statutory stockholding obligations. Demand concentrates at coastal sites with jetty access for import diversification, though single-point concentration at three terminal clusters creates supply security exposure.
- Processing:NGL fractionation and gas treatment facilities bridge upstream composition variability and downstream specification requirements.
- Distribution:Last-mile pipeline networks and truck-rail intermodal hubs serve dispersed industrial offtake points across northern England.
Transportation leads volumes today; Storage is gaining share fastest as strategic reserve mandates deepen.
Service Type:
Asset-heavy pipeline and terminal infrastructure commands pricing power, while specialized shipping and processing services compete on utilization efficiency and contract flexibility.
- Pipelines:The mature UK continental shelf network captures value through sunk-cost economics and regulated third-party access tariffs. North Sea Transition Authority decommissioning timelines are compressing asset lifecycles, forcing operators toward early hydrogen-ready conversion or premature retirement.
- Terminals:LNG receiving and crude storage facilities at coastal sites anchor import-dependent supply security. Grangemouth and Milford Haven terminals are integrating real-time inventory optimization with adjacent refinery operations, compressing working capital cycles for captive offtakers.
- Tankers:Specialized liquefied gas shipping routes serve British import terminals with spot and term charter flexibility.
- Processing Facilities:Gas treatment and NGL recovery units at terminal complexes add value through composition upgrading.
Pipelines anchor revenue baselines; Terminals are expanding most quickly as LNG import dependence deepens.
End User:
Utility procurement patterns are shortening contract durations, while refinery and petrochemical demand maintains longer-term capacity commitments.
- Utility Companies:Combined-cycle gas turbine operators serving balancing markets prefer interruptible transport terms aligned with renewable intermittency. Northern England corridor negotiations now emphasize seasonal swing capacity over flat annual volumes, displacing baseload pipeline commitments.
- Refineries:Grangemouth and Pembroke facilities secure dedicated terminal-to-refinery logistics with integrated digital monitoring layers. INEOS Capital Limited anchors operations with captive pipeline and storage capacity, insulating margin exposure to third-party tariff disputes.
- Petrochemical Plants:Ethylene crackers and aromatics complexes require consistent naphtha and natural gas liquid feedstock deliveries.
- Traders:Merchant intermediaries exploit storage and transport arbitrage across seasonal price spreads and geographic differentials.
Refineries retain the longest contract tenors; Utility Companies are driving the steepest demand trajectory shift.
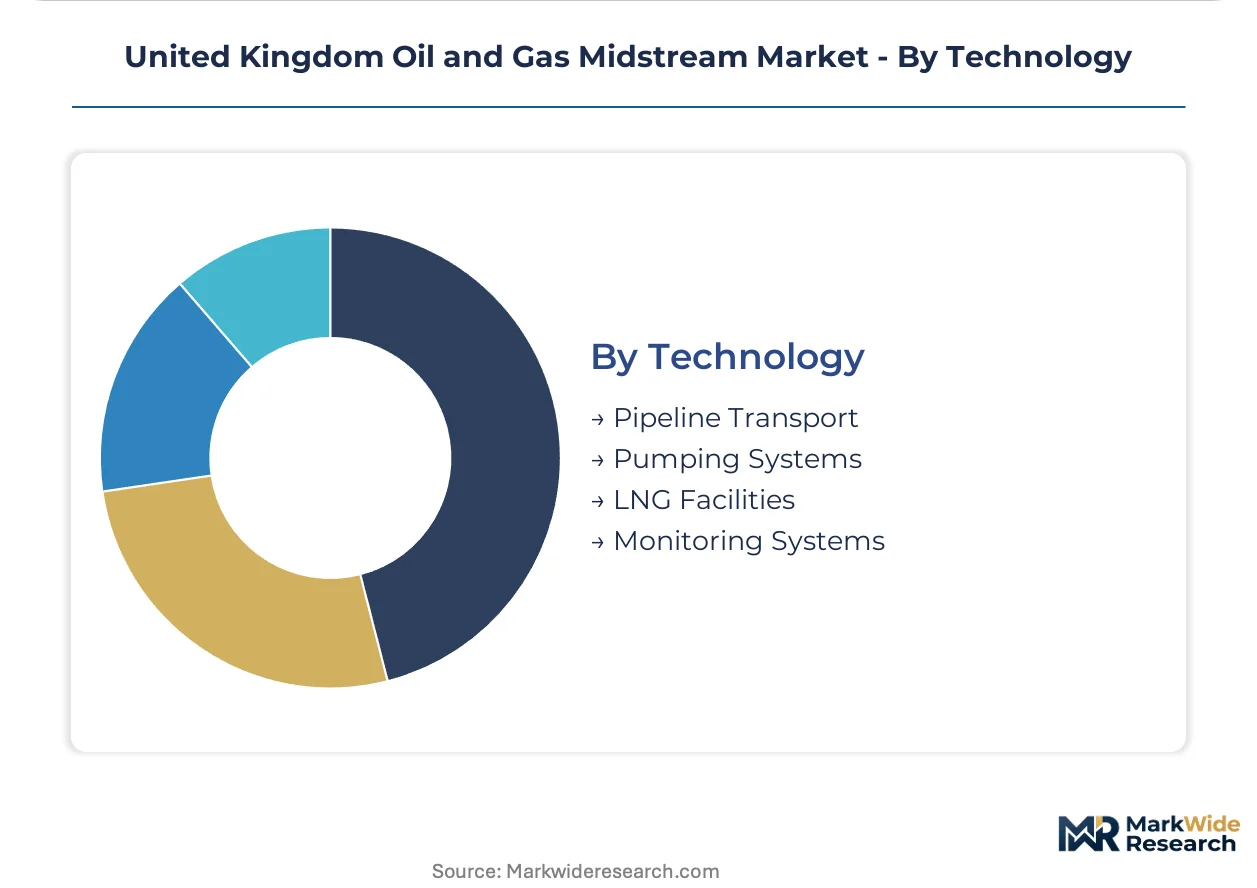
Technology:
Digital monitoring layers are hardening into standard contract inclusions, while physical transport infrastructure faces material science constraints on hydrogen compatibility.
- Pipeline Transport:Steel trunk lines face hydrogen embrittlement uncertainty that delays final investment decisions on high-pressure conversion projects. SGN's network repurposing trials in Aberdeen and Fife are establishing regulatory precedents for blending-ready infrastructure standards.
- Monitoring Systems:Software-defined platforms unify leak detection, pressure management, and predictive corrosion analytics into single architectures. SSE PLC bundles digital monitoring with capacity reservations, compressing incident response windows from days to hours while automating Health and Safety Executive compliance documentation.
- Pumping Systems:Compression stations maintain flow assurance across declining North Sea throughput volumes.
- LNG Facilities:Regasification and liquefaction infrastructure enables supply source diversification beyond domestic production decline.
Pipeline Transport dominates installed base value; Monitoring Systems are climbing the fastest as regulatory inspection burdens intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's offshore pipeline density contrasts sharply with England's terminal-centric import infrastructure, revealing divergent asset utilization strategies across the United Kingdom's midstream geography.
Scotland
North Sea platform decommissioning accelerates throughput decline on aging trunk lines serving Aberdeen and Peterhead. The North Sea Transition Authority enforces accelerated decommissioning security bonds, compressing operator decision windows. Grangemouth industrial cluster anchors hydrogen-ready corridor development, with SGN conducting network repurposing trials in Aberdeen and Fife to establish blending standards.
North England
Combined-cycle gas turbine utilities drive interruptible transport demand aligned with renewable intermittency patterns. Ofgas third-party access tariff structures shape corridor negotiations across Teesside and Merseyside terminals. Hydrogen production targets concentrate investment around pipeline routes connecting offshore wind zones to industrial clusters in Humberside.
Midlands
Strategic reserve storage obligations sustain terminal margins at coastal sites with jetty access for import diversification. Health and Safety Executive PSR 1996 enforcement drives replacement cycles for aging pressure vessels and tankage. Birmingham and Leicester distribution hubs face working capital compression as real-time inventory optimization spreads from integrated refinery operations.
Wales
Milford Haven LNG terminal anchors supply security for southwest Britain's dispersed industrial demand. The North Sea Transition Authority's carbon capture readiness licensing offers dual-use certification pathways for pipelines serving Pembroke refinery complex. South Wales petrochemical corridors retain longer-term capacity commitments compared to utility procurement patterns elsewhere.
United Kingdom Oil and Gas Midstream Market Competitive Landscape
Top-tier vendors anchor integrated infrastructure portfolios, while specialized shipping and storage operators compete on route efficiency and contract flexibility. The United Kingdom midstream sector exhibits tiered consolidation around incumbent pipeline owners with sunk-cost network advantages. Three archetypes dominate: integrated energy majors with captive terminal-to-refinery logistics, independent pipeline operators bundling digital monitoring with capacity reservations, and specialized liquefied gas shipping companies. Competitive moves concentrate on hydrogen-ready conversion partnerships and carbon capture readiness licensing to secure repurposing advantages ahead of decommissioning deadlines.
Within the integrated infrastructure tier, SSE PLC and INEOS Capital Limited exemplify divergent strategic positioning. SSE PLC leverages its North Sea footprint through bundled service offerings that combine physical capacity with software-defined monitoring layers. INEOS Capital Limited anchors its position through captive terminal-to-refinery integration at Grangemouth, insulating operations from third-party tariff volatility. Navigator Holdings Ltd. occupies a specialized position among independent shipping operators, competing on liquefied gas route flexibility to British import terminals.
| Leading Market Players |
|---|
| SSE PLC |
| ConocoPhillips Company |
| Storengy SA |
| Navigator Holdings Ltd. |
| TORM plc |
| GASSCO |
| Interconnector Limited |
| INEOS Capital Limited |
| E.ON UK plc |
| Others |
Value Network & Pricing Analysis
Utility procurement compression toward interruptible transport terms is forcing midstream operators to restructure capacity reservation models, compressing revenue baselines and redirecting capital toward digital monitoring bundles that command premium pricing.
Pricing Analysis
Capacity additions in LNG import terminals are reshaping price floors across coastal storage corridors. Contract-based long-term offtake agreements still anchor revenue stability for Grangemouth and Milford Haven operators, though spot-market exposure is climbing. Price differentiation hinges on hydrogen-ready certification status and digital monitoring integration depth. Margins are tightening in legacy North Sea trunk lines as throughput volumes decline, while hydrogen corridor developers capture premium tier positioning.
Supply Chain Analysis
Specialist subsea engineering talent scarcity in Aberdeen and Stavanger is extending lead times for pipeline inspection and decommissioning services. Steel plate sourcing draws from China, South Korea, and India, with high-grade alloys for hydrogen service resting on German and Japanese metallurgical capabilities. Single-source vulnerability concentrates in subsea valve and compression equipment. Distribution runs through integrated terminal-to-refinery logistics at Grangemouth and coastal LNG receiving sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Midstream margin expansion hinges on hydrogen-ready conversion premiums offsetting legacy hydrocarbon revenue compression, with digital monitoring bundling emerging as the primary cost-down lever.
For Market Incumbents: Hedge decommissioning liability exposure through accelerated hydrogen corridor partnerships before North Sea Transition Authority timelines crystallize. Secure carbon capture readiness licensing for dual-use pipeline certification, and deepen vertical integration into terminal-to-refinery digital layers to insulate against Ofgas tariff disputes. For New Entrants and Emerging Players: The premium-to-economy gap in software-defined monitoring services opens white-space for specialized analytics vendors. Target Scottish hydrogen backbone trials with blending-ready infrastructure certification tools, and pursue utility procurement officers with flexible interruptible capacity platforms that align with renewable intermittency patterns. For Investors and Strategic Acquirers: Asymmetric upside sits with pipeline operators holding sunk-cost North Sea network positions convertible to hydrogen transport. Five-to-ten year viability favors assets with proximity to Grangemouth and Aberdeen industrial clusters. Watch North Sea Transition Authority decommissioning bond enforcement as inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Pipeline Conversion | Secures repurposing licenses ahead of North Sea Transition Authority decommissioning deadlines. |
| Carbon Capture Readiness Licensing | Establishes dual-use certification for CO2 transport under emerging NSTA frameworks. |
| Digital Monitoring Platform Integration | Compresses incident response windows while automating Health and Safety Executive compliance. |
| Terminal-to-Refinery Logistics Control | Captures working capital efficiency through real-time inventory optimization at Grangemouth. |
| Interruptible Capacity Contract Development | Aligns transport terms with utility balancing market exposure and renewable intermittency. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down pipeline capacity tracking forms the analytical core. Primary interviews with North Sea platform operators, Ofgas regulatory affairs leads, utility planning officers, and Health and Safety Executive inspectors combined with secondary validation from North Sea Transition Authority license filings, Ofgas tariff review documents, and EIA European gas trade data. Top-down and bottom-up triangulation ensures segmentation integrity.
Input-output matrices map transport volume flows across product type, service type, end user, and technology dimensions over the projection horizon. CAGRs derive from regression analysis against North Sea production decline curves and hydrogen production target trajectories. Forecast inputs incorporate North Sea Transition Authority decommissioning timeline scenarios and Ofgas third-party access pricing review outcomes.
Caveats apply where North Sea Transition Authority bond enforcement intensity or hydrogen embrittlement material science breakthroughs could materially shift the outlook. Forecasts reflect assumptions around regulatory timeline adherence and steel compatibility certification progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Well Testing Services Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
North America Proppants Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Europe Digital Oilfield Market