
 Asia Pacific Submersible Pump Market | 2026-2036
Asia Pacific Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Submersible Pump Market Insights
Wastewater management is decoupling from oil and gas as the dominant demand driver across the Asia Pacific Submersible Pump Market. Ebara Corporation leverages its centrifugal pump specialization to anchor municipal contracts in Japan and Southeast Asia. Sulzer AG sustains competitive positioning through R&D intensity in corrosion-resistant materials for aggressive fluid environments.
A submersible pump is a hermetically sealed motor-pump unit designed to operate fully immersed in fluid, typically constructed with stainless steel or cast iron housings and featuring impeller diameters ranging from 100 mm to over 1,000 mm for flow rates up to several thousand cubic meters per hour. Its primary purpose is to lift, transfer, or pressurize liquids from boreholes, sumps, or submerged sources without cavitation risk. Centrifugal designs dominate installed bases across power ratings due to mature manufacturing economics, while solar-powered installations represent the fastest-expanding power source category as off-grid irrigation projects multiply in India and Indonesia. Vertical installation configurations retain margin concentration in deep-well mining and geothermal applications where shaft length and thrust bearing specifications create technical barriers to entry.
India's BIS certification requirements and China's GB standards enforced by SAMR shape product compliance costs and market access timelines for imported equipment. Australia's TGA-equivalent electrical safety frameworks and Japan's METI energy efficiency directives add layered certification obligations across the region. Stakeholders must monitor divergence between national efficiency mandates and the interoperability demands of cross-border project contractors.
Market Dynamics
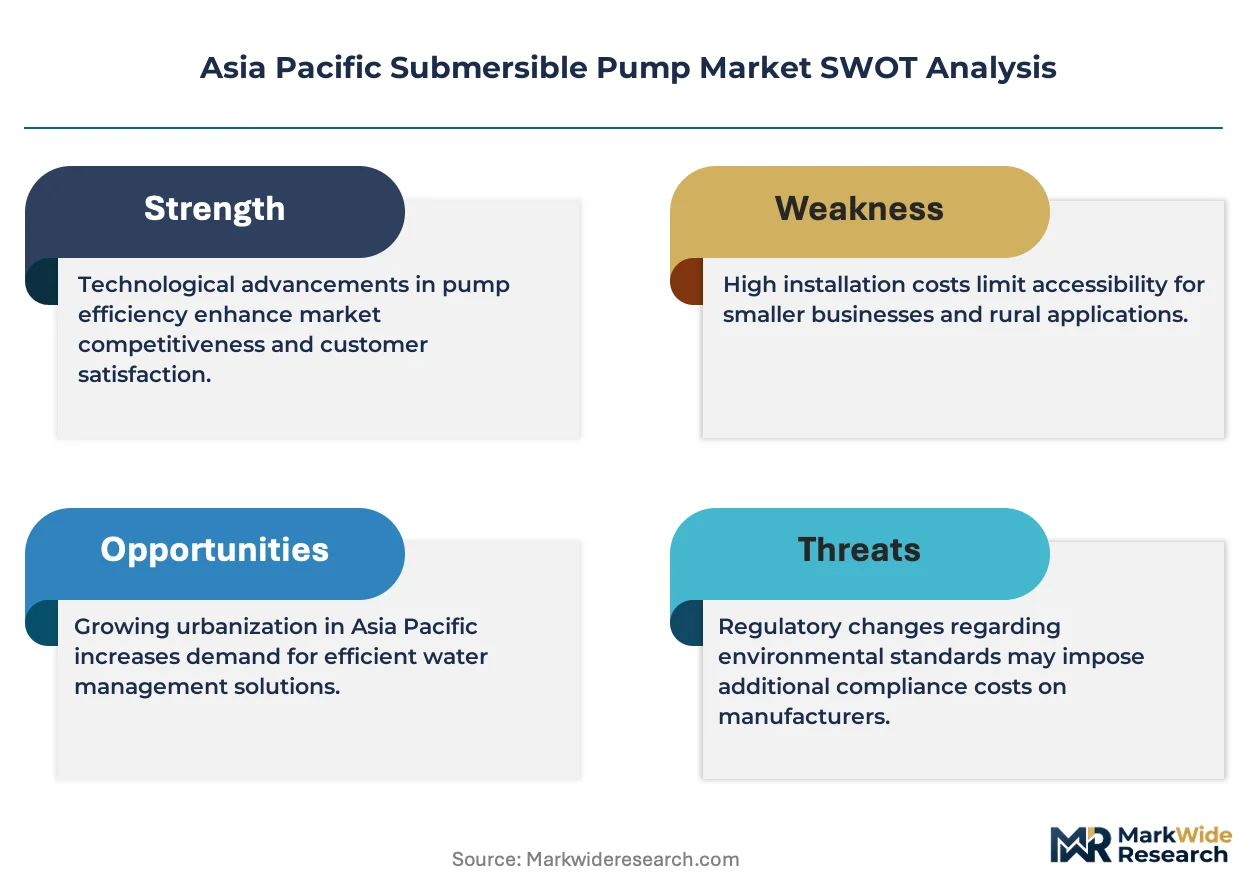
Wastewater infrastructure mandates across Chinese megacities are accelerating equipment replacement cycles, while India's BIS certification deadlines compress import timelines for European and Japanese manufacturers. Mining dewatering requirements in Australia's Pilbara and geothermal expansion in Indonesia's Java belt are fragmenting demand specifications.
Growth Catalysts
- GB Standard Enforcement:China's SAMR-mandated efficiency tiers for municipal pumping stations are forcing upgrades in Beijing and Shanghai treatment facilities, creating replacement demand for premium submersible units.
- Geothermal Field Expansion:Indonesia's capacity additions in the Dieng and Patuha fields require high-temperature submersible pumps with specialized elastomer seals, pulling in specialized suppliers from Japan and South Korea.
- Solar Irrigation Subsidies:India's PM-KUSUM scheme for off-grid agricultural pumping is displacing diesel-powered alternatives across Rajasthan and Gujarat, expanding addressable market for DC-compatible submersible designs.
Market Restraints
- Stainless Steel Price Volatility:Nickel alloy cost swings directly compress margins on corrosion-resistant pump housings, forcing manufacturers to absorb input spikes or risk specification downgrades.
- Regional Supply Concentration:Critical motor winding and permanent magnet production clusters in Zhejiang province create single-point vulnerability for Asia-Pacific pump assembly lines.
- Cast Iron Substitution Limits:Aggressive fluid chemistries in Indonesian geothermal brines prevent material downgrades from duplex stainless, locking cost structures at premium tiers.
Strategic Opportunities
- Vietnam Industrial Zone Buildout:Northern provinces surrounding Hai Phong harbor underpenetrated demand for process water submersibles as electronics manufacturing parks expand cooling infrastructure.
- Digital Pump Monitoring:Vibration sensor and cloud analytics convergence enables predictive maintenance contracts, shifting revenue from hardware sales to recurring service streams.
- Philippines Flood Control:Manila's Department of Public Works drainage modernization program creates specification windows for high-capacity dewatering pumps with rapid-deployment frames.
Industry Challenges
- Multi-Jurisdiction Certification:Cross-border project contractors face sequential BIS, GB, and METI approval timelines that stretch product launch windows by 8-14 months.
- Deep-Well Technical Labor Scarcity:Installation and commissioning of 500-meter-plus geothermal pumps requires specialized crews concentrated in Japan and Australia, constraining deployment velocity in emerging fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Submersible Pump Market |
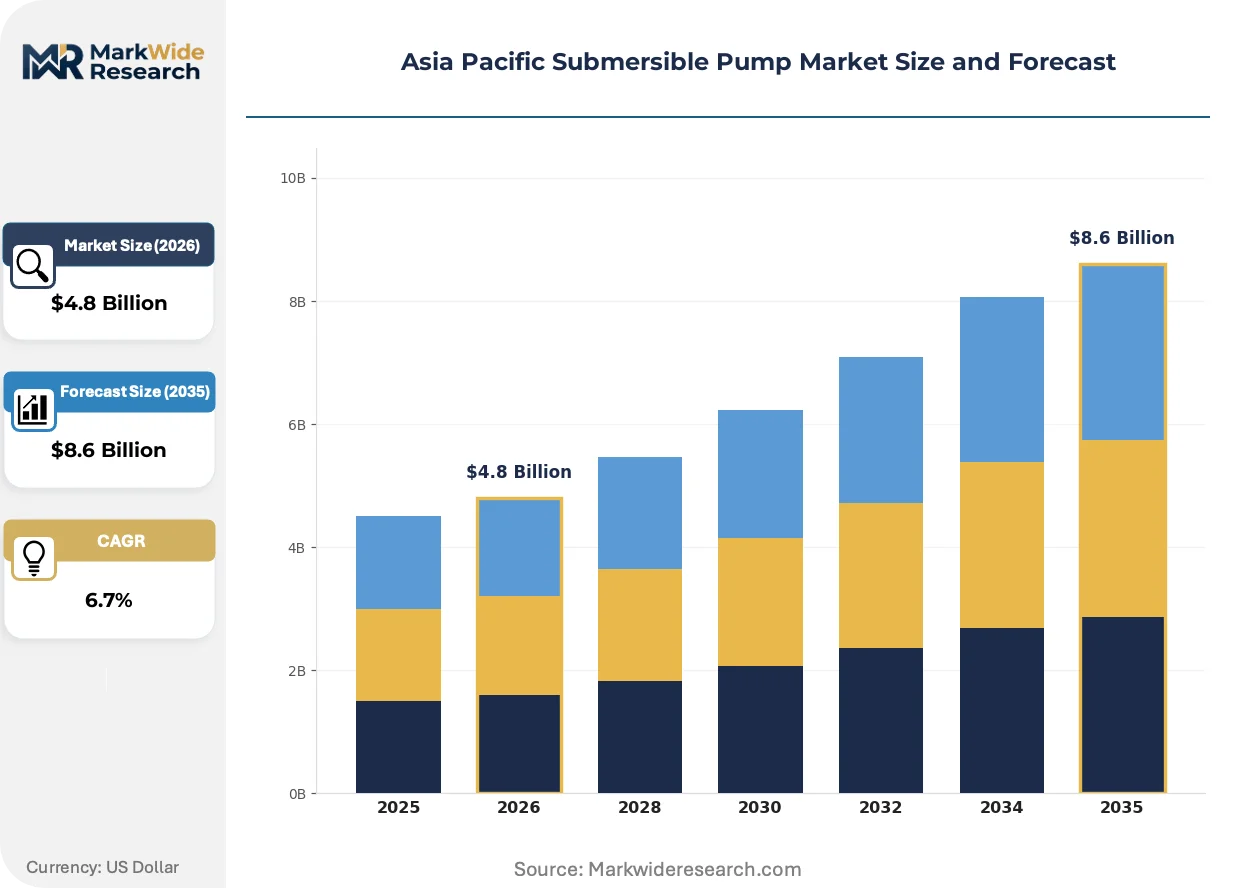
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vortex, Semi-Submersible, Positive Displacement, Centrifugal End User: Agriculture, Oil & Gas, Construction, Wastewater Management Installation: Vertical, Horizontal, Floating, Integrated Power Source: Electric, Diesel, Solar, Wind |
| Companies Covered | Schlumberger Limited, Sulzer AG, Flowserve Corporation, Atlas Copco AB, Havells India Ltd, Baker Hughes Co, Halliburton Co, Weir Group PLC, Ebara Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Submersible Pump Market Trends and Innovations
Permanent magnet synchronous motor technology is compressing energy consumption benchmarks across Asia-Pacific pumping infrastructure, while digital twin deployment is rewiring aftermarket service economics. Material science advances in ceramic-bearing surfaces are extending mean time between failures in abrasive fluid environments.
Variable frequency drive integration is integrating with submersible pump motors to enable real-time flow matching against dynamic head conditions. Municipal water authorities in Japan and South Korea are retrofitting existing installations with VFD-compatible controllers, reducing energy draw during off-peak demand periods. This integration is compressing the total cost of ownership gap between premium efficient motors and standard induction designs.
China's dual carbon goals enforced through MEE provincial audits are tightening emissions accounting for energy-intensive manufacturing facilities. Industrial pump users in Jiangsu and Guangdong must now document lifecycle energy consumption in procurement tenders, favoring suppliers with verified efficiency certifications. High-head mining applications in Inner Mongolia are responding by specifying IE4-rated submersible motors despite 15-20% capital cost premiums.
Asset-as-a-service contracting is displacing traditional equipment purchase models across Australian mining and Indonesian geothermal sectors. Engineering procurement contractors now bundle pump supply with guaranteed availability clauses, transferring operational risk to OEM service organizations. This shift concentrates most visibly in Western Australia's iron ore corridors where unplanned dewatering downtime carries seven-figure hourly penalties.
Asia Pacific Submersible Pump Market Segmentation
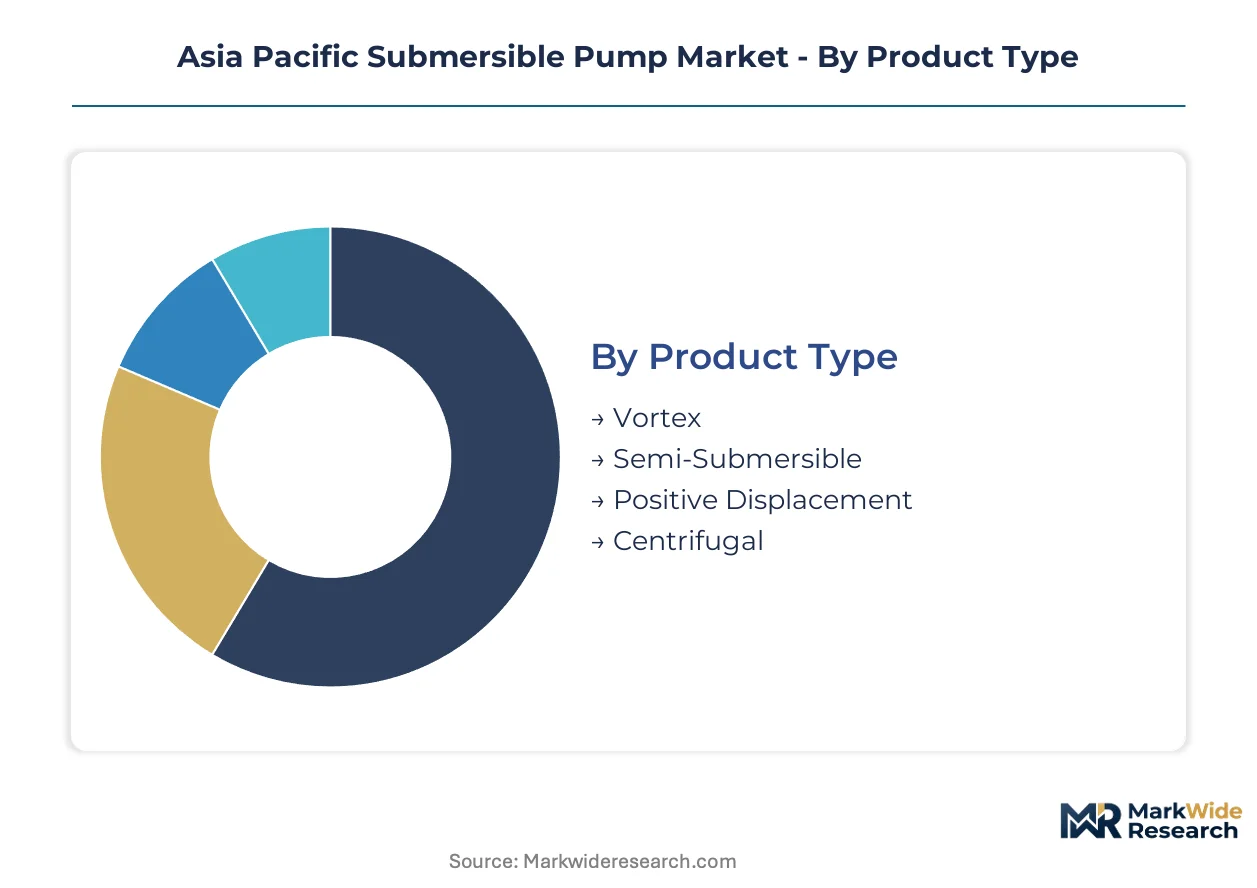
Segmentation in the Asia Pacific Submersible Pump Market reveals how equipment specifications fragment across installation environments and energy access conditions. Understanding these divides clarifies why manufacturers maintain parallel product architectures rather than unified platforms.
Product Type:
Standalone pump units dominate municipal and agricultural procurement, while embedded configurations integrate into packaged treatment skids and mobile dewatering systems.
- Centrifugal:Impeller-driven designs with volute casings handle high-flow, moderate-head applications across municipal water networks. Demand clusters in Chinese megacity treatment facilities where SAMR-mandated efficiency tiers force equipment replacements.
- Vortex:Recessed impeller configurations pass solids without clogging, serving raw sewage and slurry applications. Mining dewatering contracts in Australia's Pilbara region specify these units for abrasive ore-laden groundwater.
- Semi-Submersible:Motor-above-water designs suit shallow sump installations with limited submergence depth. Indonesian electronics manufacturing parks deploy these for process cooling water recirculation.
- Positive Displacement:Progressive cavity and piston mechanisms deliver precise flow control for chemical dosing and viscous fluid handling. Geothermal brine injection in Java's Dieng field requires these for high-pressure reinjection.
Volume placements concentrate in Centrifugal; the faster expansion belongs to Vortex.
End User:
Cost-tier stratification separates specification-intensive industrial buyers from price-sensitive agricultural procurement.
- Wastewater Management:Municipal treatment plants and sewer networks demand corrosion-resistant stainless construction with extended mean time between failures. China's MEE provincial audits now embed lifecycle energy accounting into tender evaluations.
- Agriculture:Irrigation and drainage applications prioritize capital efficiency over operating cost optimization. India's PM-KUSUM subsidy scheme is accelerating displacement of diesel-powered units with solar-compatible DC pumps across Rajasthan and Gujarat.
- Oil & Gas:Offshore platforms and downstream facilities require explosion-proof motor enclosures and API-compliant materials. Australian offshore maintenance schedules drive replacement demand for subsea boosting units.
- Construction:Temporary dewatering for foundation work and tunneling favors rapid-deployment skid-mounted configurations. Philippines flood control programs in Manila specify high-capacity units with quick-connect discharge manifolds.
Contract values peak in Oil & Gas; steepest expansion trajectory runs through Agriculture.
Installation:
Application context dictates whether pumps operate as independent assets or integrated subsystems within larger process trains.
- Vertical:Deep-well configurations with extended shaft assemblies serve borehole extraction and geothermal production. Japan's METI energy efficiency directives favor these for high-head municipal supply.
- Horizontal:Surface-mounted wet-pit arrangements simplify maintenance access in treatment plant dry-well installations. South Korean municipal retrofits increasingly specify these for VFD-compatible upgrades.
- Floating:Pontoon-mounted units adapt to variable water levels in reservoirs and flood control basins. Vietnam's industrial zone buildout around Hai Phong creates specification windows for process water intake.
- Integrated:Pre-engineered packages combine pumps with controls and piping for rapid field deployment. Australian mining contractors favor asset-as-a-service models bundling these with availability guarantees.
Installed base dominance sits with Vertical; Integrated configurations are climbing the fastest.
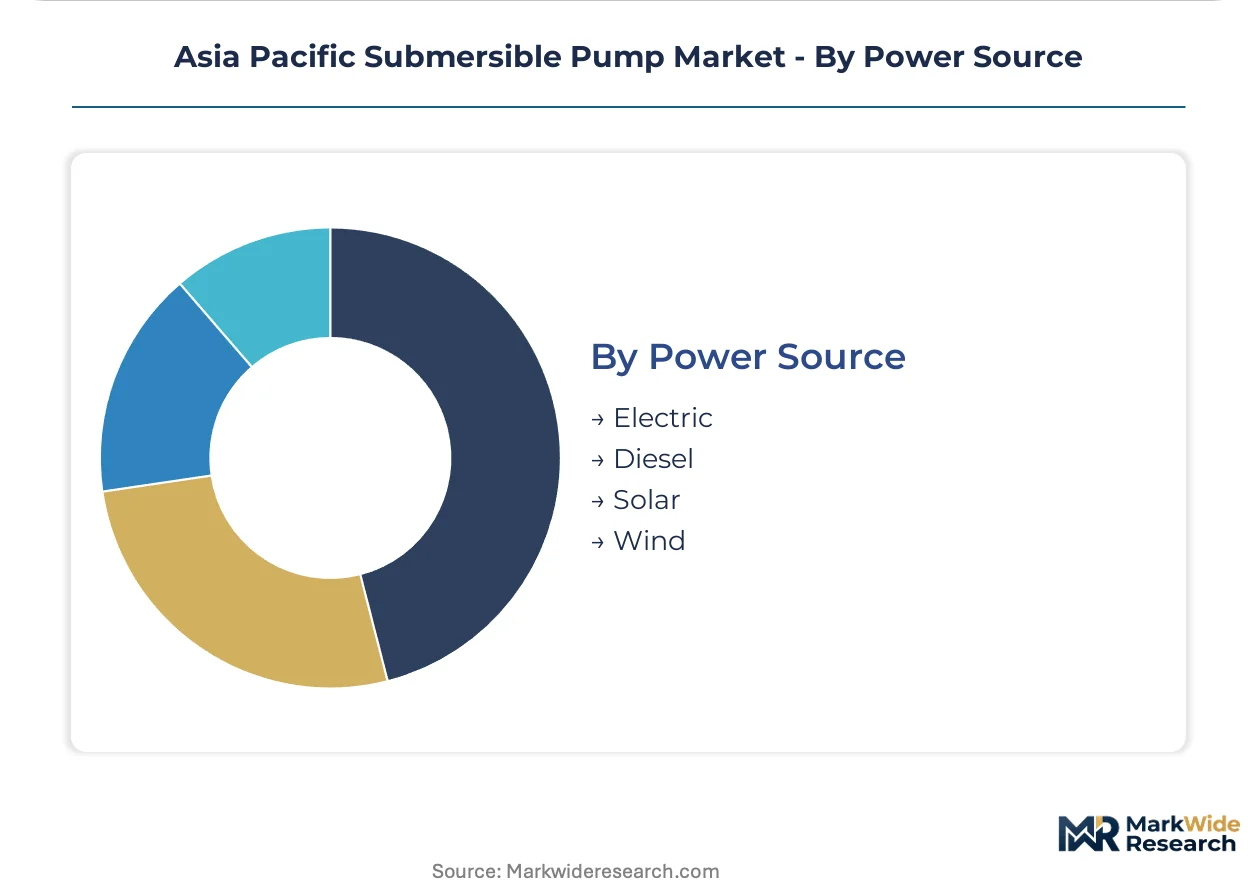
Power Source:
Grid access quality and fuel cost exposure segment procurement across rural and urban deployment contexts.
- Electric:Grid-connected AC motors dominate established infrastructure with reliable utility supply. China's dual carbon goals enforced through MEE audits now require IE4-rated motors in Jiangsu and Guangdong industrial tenders.
- Solar:DC brushless motors with photovoltaic arrays serve off-grid irrigation and remote water supply. Indonesia's archipelago geography makes these essential for outer island community water systems.
- Diesel:Engine-driven portable units retain relevance for emergency dewatering and construction mobilization. India's BIS certification deadlines compress import timelines for European engine-pump packages.
- Wind:Mechanical windmill-to-pump linkages persist in remote Australian pastoral stations with consistent wind regimes. Hybrid wind-solar configurations are emerging for remote Indonesian agricultural cooperatives.
Deployment scale favors Electric; Solar is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates submersible pump manufacturing capacity across Zhejiang and Jiangsu provinces, while consumption spreads across wastewater infrastructure, mining, and geothermal applications throughout the Asia Pacific region.
China
SAMR-mandated GB efficiency tiers are forcing equipment replacements in Beijing and Shanghai municipal treatment facilities. MEE provincial audits now embed lifecycle energy accounting into procurement tenders for Jiangsu and Guangdong industrial users. Zhejiang province hosts critical motor winding and permanent magnet production clusters supplying regional assembly lines.
Japan
METI energy efficiency directives favor vertical deep-well configurations for high-head municipal water supply applications. Ebara Corporation leverages centrifugal pump specialization to anchor municipal contracts across domestic and Southeast Asian markets. The Kanto region around Tokyo concentrates R&D activity in corrosion-resistant materials for aggressive fluid environments.
India
BIS certification deadlines compress import timelines for European and Japanese manufacturers seeking market access. The PM-KUSUM subsidy scheme accelerates displacement of diesel-powered units with solar-compatible DC pumps across Rajasthan and Gujarat agricultural belts. Bureau of Indian Standards mandates are reshaping product compliance requirements for both domestic producers and importers.
Australia
TGA-equivalent electrical safety frameworks add layered certification obligations for equipment deployment. Mining dewatering requirements in Western Australia's Pilbara region drive demand for vortex pumps handling abrasive ore-laden groundwater. Asset-as-a-service contracting bundles pump supply with guaranteed availability clauses, transferring operational risk to OEM service organizations.
Indonesia
Geothermal capacity additions in the Dieng and Patuha fields require high-temperature submersible pumps with specialized elastomer seals. The Java belt expansion pulls in specialized suppliers from Japan and South Korea for technical commissioning support. Archipelago geography makes solar-powered DC pumps essential for outer island community water systems.
Asia Pacific Submersible Pump Market Competitive Landscape
Top-tier vendors anchor municipal and industrial infrastructure contracts, while mid-tier specialists occupy agricultural and construction segments. The market structure fragments across centrifugal, vortex, and positive displacement technology domains. Two strategic archetypes dominate: diversified industrial conglomerates with corrosion-resistant materials expertise, and focused pump specialists with deep-well installation capabilities. Competitive moves concentrate on geographic expansion through local certification partnerships and portfolio diversification into digital monitoring services.
Among Swiss-based precision engineering groups, Sulzer AG exemplifies the corrosion-resistant materials archetype through sustained R&D intensity. Japanese specialists including Ebara Corporation occupy positions in municipal water infrastructure across domestic and Southeast Asian markets. Schlumberger Limited and Baker Hughes Co represent the oilfield services diversification vector, leveraging subsea boosting expertise into geothermal and industrial dewatering applications.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Sulzer AG |
| Flowserve Corporation |
| Atlas Copco AB |
| Havells India Ltd |
| Baker Hughes Co |
| Halliburton Co |
| Weir Group PLC |
| Ebara Corporation |
| Others |
Pricing and Supply Chain Analysis
Nickel alloy cost volatility propagates through stainless steel pump housing fabrication into three-tier pricing stratification across premium corrosion-resistant, standard cast iron, and economy-grade agricultural units. Procurement officers in Chinese municipal treatment facilities absorb premium tier premiums for GB-compliant efficiency ratings, while Indian solar irrigation buyers drive economy tier volume through PM-KUSUM subsidy eligibility thresholds.
Pricing Analysis
Margin tightening in premium submersible tiers reflects SAMR-mandated efficiency certification costs layered onto duplex stainless raw material exposure. Three-tier pricing structure across premium, standard, and economy levels separates IE4-rated municipal contracts from standard induction agricultural units and diesel-to-solar conversion subsidies. Price differentiation hinges on corrosion-resistant material grade and METI energy efficiency verification. Agricultural procurement in Rajasthan and Gujarat exhibits acute price sensitivity; Australian mining contractors accept capital premiums for asset-as-a-service availability guarantees.
Supply Chain Analysis
Regional distribution centers in Shanghai, Singapore, and Sydney anchor hub-and-spoke fulfillment patterns for spare parts and replacement units. Manufacturing concentration in Zhejiang and Jiangsu provinces feeds from permanent magnet and motor winding clusters vulnerable to single-source disruption. Raw material dependencies span nickel alloy sheet, ceramic bearing inserts, and specialized elastomer seals for geothermal applications. Tariff exposure on European and Japanese component imports through India's BIS certification timeline compression elevates landed cost uncertainty. Distribution runs through authorized dealer networks for municipal specifiers and direct EPC contractor relationships for mining and geothermal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor technology is displacing standard induction designs across Asia-Pacific pumping infrastructure, compressing energy consumption benchmarks and rewiring procurement evaluation criteria toward lifecycle cost accounting.
For Market Incumbents: Anticipate margin compression from Chinese motor manufacturers achieving GB efficiency tier compliance at lower cost structures than Japanese and European heritage brands. Defensive consolidation through captive supply of permanent magnet rotor assemblies in Zhejiang-adjacent facilities reduces single-source vulnerability. METI efficiency directive alignment and BIS certification pre-positioning defend municipal contract renewal rates against emerging domestic competitors.
For New Entrants and Emerging Players: E-commerce platform direct-to-irrigation-cooperative routes bypass established dealer networks in Indian agricultural belts. White-space concentration in Vietnam's Hai Phong electronics manufacturing corridor and Philippines flood control modernization programs offers specification windows before incumbent certification completion. Solar-compatible DC pump specialization with PM-KUSUM subsidy documentation support accelerates agricultural market penetration against diesel legacy installed base.
For Investors and Strategic Acquirers: Asset-as-a-service contract proliferation in Western Australian iron ore corridors is the leading indicator that operational risk transfer models will extend across Indonesian geothermal and Chinese municipal outsourcing frameworks. Acquisition targets with predictive maintenance software stacks and vibration analytics capabilities capture recurring revenue transformation. Watch for geothermal field commissioning crew scarcity forcing OEM service organization acquisitions in Japan and Australia.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Manufacturing Scale-Up | Zhejiang province clustering reduces dependency on imported rotor assemblies for IE4-rated municipal contracts. |
| Digital Predictive Maintenance Platform Launch | Vibration sensor cloud analytics enable recurring service revenue streams displacing transactional hardware sales. |
| Geothermal Commissioning Crew Training Joint Venture | Japan-Australia technical partnership addresses 500-meter-plus installation labor scarcity constraining Java field expansion. |
| Solar DC Pump Certification Fast-Track | PM-KUSUM subsidy eligibility documentation accelerates displacement of diesel units in Rajasthan agricultural belts. |
| Corrosion-Resistant Materials R&D Partnership | Ceramic-bearing surface advances extend mean time between failures in Dieng field abrasive brine environments. |
Research Methodology
Document review covered customs trade databases, SAMR efficiency tier filings, and BIS certification registries, complemented by interviews with municipal procurement directors at Chinese megacity water authorities, maintenance engineers at Australian Pilbara mining operations, and geothermal project developers in Indonesia's Java belt. Secondary validation drew from METI energy efficiency disclosures, PM-KUSUM subsidy disbursement records, and permanent magnet supply chain documentation from Zhejiang industrial clusters. Bottom-up equipment shipment analysis and top-down infrastructure investment tracking were cross-referenced for triangulation.
Historical deployment patterns across Chinese wastewater treatment facilities, Indian agricultural electrification programs, and Australian mining expansion cycles were cross-referenced against panel input from EPC contractors and OEM service organizations. Segmentation modeling spanned product type centrifugal-to-positive-displacement splits, power source electric-to-solar transition rates, and installation vertical-to-integrated configuration shifts. CAGRs were derived from infrastructure investment pipeline analysis and equipment replacement cycle timing across the projection horizon. Forecast inputs incorporated SAMR enforcement trajectory assumptions and nickel alloy price regime sensitivity.
The model holds under continued GB standard enforcement and PM-KUSUM subsidy continuity; deviation in Chinese municipal fiscal capacity or Indian renewable energy certificate pricing would shift replacement demand timing. Forecasts reflect documented assumption sets regarding certification timeline compression and geothermal field development velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market