
 Subsea Pumping System Market | 2026-2036
Subsea Pumping System Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Pumping System Market Analytics
Modular subsea pump packaging is consolidating as the dominant procurement model, replacing standalone component purchases with integrated skid-mounted systems that reduce offshore installation time. Baker Hughes Company leverages its turbomachinery heritage to anchor high-horsepower electromechanical pump contracts in ultra-deepwater provinces. Schlumberger Limited sustains technology leadership through its OneSubsea joint venture, which specializes in combining subsea boosting with subsea processing architectures. TechnipFMC plc competes on integrated system delivery, controlling the interface between pump modules and subsea distribution units.
A subsea pumping system comprises pressure-boosting equipment installed on the seabed to transport hydrocarbons from wellheads to surface facilities, typically operating at depths exceeding 300 meters and pressures above 10,000 psi to overcome natural reservoir decline. Electromechanical pumps dominate the product type landscape due to their efficiency in high-flowrate crude oil service, while hydraulic pumps retain niche positions in subsea chemical injection and gas lifting applications. Oil extraction remains the largest application segment, though produced water management is gaining structural importance as operators face stricter discharge limits and seek to reinject formation water to maintain reservoir pressure.
The American Petroleum Institute's API 17D and API RP 17V standards govern subsea equipment design verification and pump testing protocols, directly shaping supplier qualification timelines and capital deployment schedules for offshore projects. Norway's Petroleum Safety Authority enforces functional safety requirements under IEC 61508 that mandate redundant control systems on subsea installations in the North Sea. Stakeholders must monitor evolving decommissioning liabilities and carbon intensity benchmarks, as these regulatory extensions will increasingly determine project economics and equipment specification priorities.
Market Dynamics
Modular subsea pump packaging is consolidating procurement patterns across ultra-deepwater provinces, compressing installation timelines and reshaping supplier qualification criteria as integrated skid-mounted systems displace standalone component sourcing.
Growth Catalysts
- Pre-salt basin development:Brazil's pre-salt formations drive large-scale subsea processing infrastructure deployment, with Petrobras and international operators committing to multi-well boosting architectures that require high-horsepower electromechanical systems.
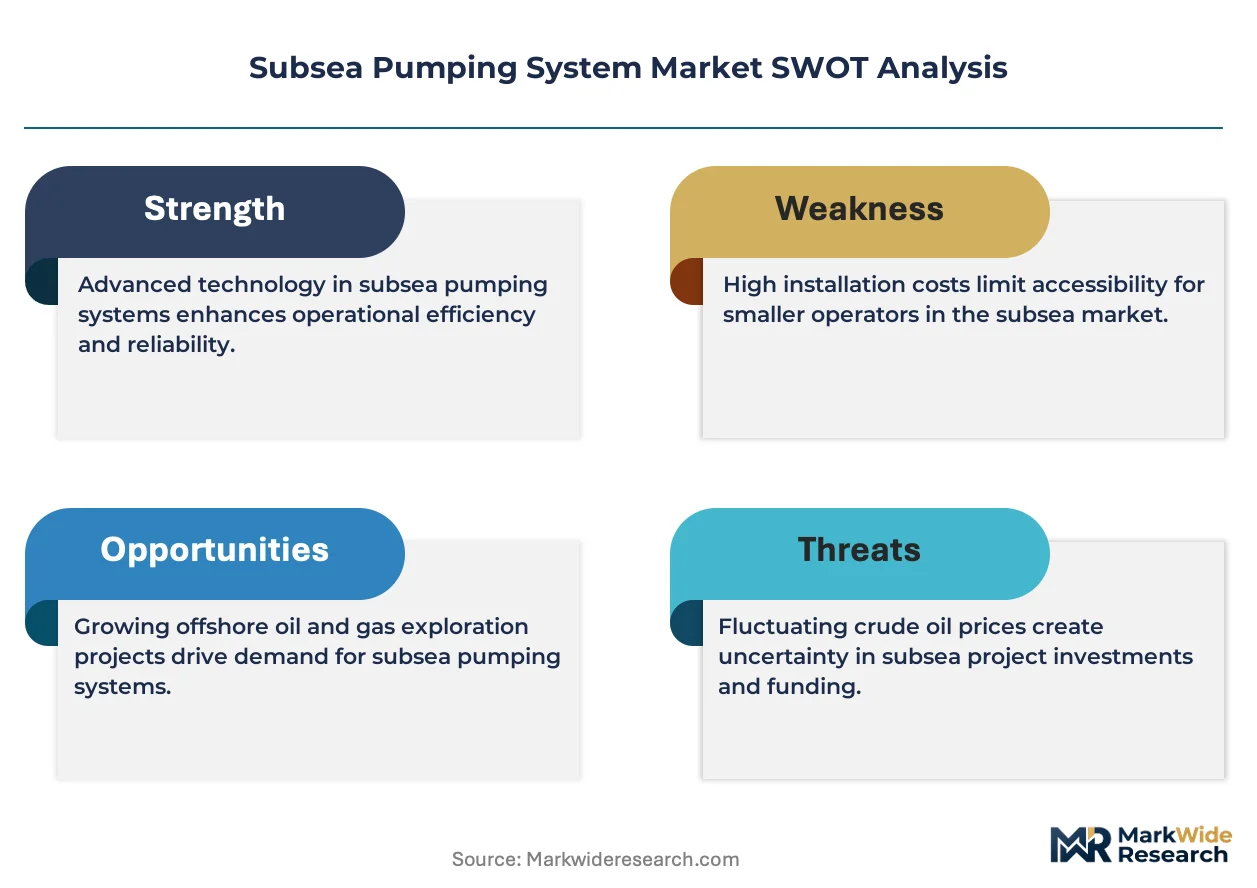
- API 17D standard tightening:The American Petroleum Institute's enhanced material and testing requirements for subsea wellhead equipment is elevating supplier technical barriers and accelerating qualification investments among equipment manufacturers.
- Produced water reinjection:Stricter discharge limits in the North Sea and Gulf of Mexico are forcing operators to deploy subsea pumps for formation water management, expanding addressable equipment demand beyond crude oil extraction.
Market Restraints
- Specialized alloy supply concentration:Duplex and super-duplex stainless steel production for high-pressure pump housings concentrates in European and Japanese mills, creating input cost volatility and extended lead times for non-integrated fabricators.
- IEC 61508 functional safety mandates:Norway's Petroleum Safety Authority requires redundant control architectures on all North Sea installations, adding engineering complexity and certification duration that extends project sanctioning timelines.
- Hydraulic pump substitution limits:Electromechanical systems dominate crude boosting above 5,000 horsepower, constraining hydraulic pump vendors to niche chemical injection and gas lift applications with smaller contract values.
Strategic Opportunities
- Decommissioning liability frameworks:Emerging carbon intensity benchmarks and asset retirement obligations in Norway and the UK are creating demand for subsea pump refurbishment and life-extension services that defer capital replacement.
- Electrification of subsea distribution:Convergence of high-voltage wet-mate connector technology with variable speed drive systems enables all-electric subsea boosting architectures that eliminate hydraulic power units and umbilical complexity.
- West Africa greenfield development:Underpenetrated deepwater provinces off Senegal, Mauritania, and Côte d'Ivoire present first-mover positioning for integrated subsea processing suppliers as international operators advance final investment decisions.
Industry Challenges
- Subsea controls systems integration:Combining pump modules with subsea distribution units requires specialized software engineering talent that concentrates among a handful of vendors, creating bottlenecks in project execution schedules.
- API RP 17V testing protocols:Extended factory acceptance testing for high-pressure pump qualification compresses delivery windows and strains manufacturing capacity during periods of concurrent project awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Pumping System Market |
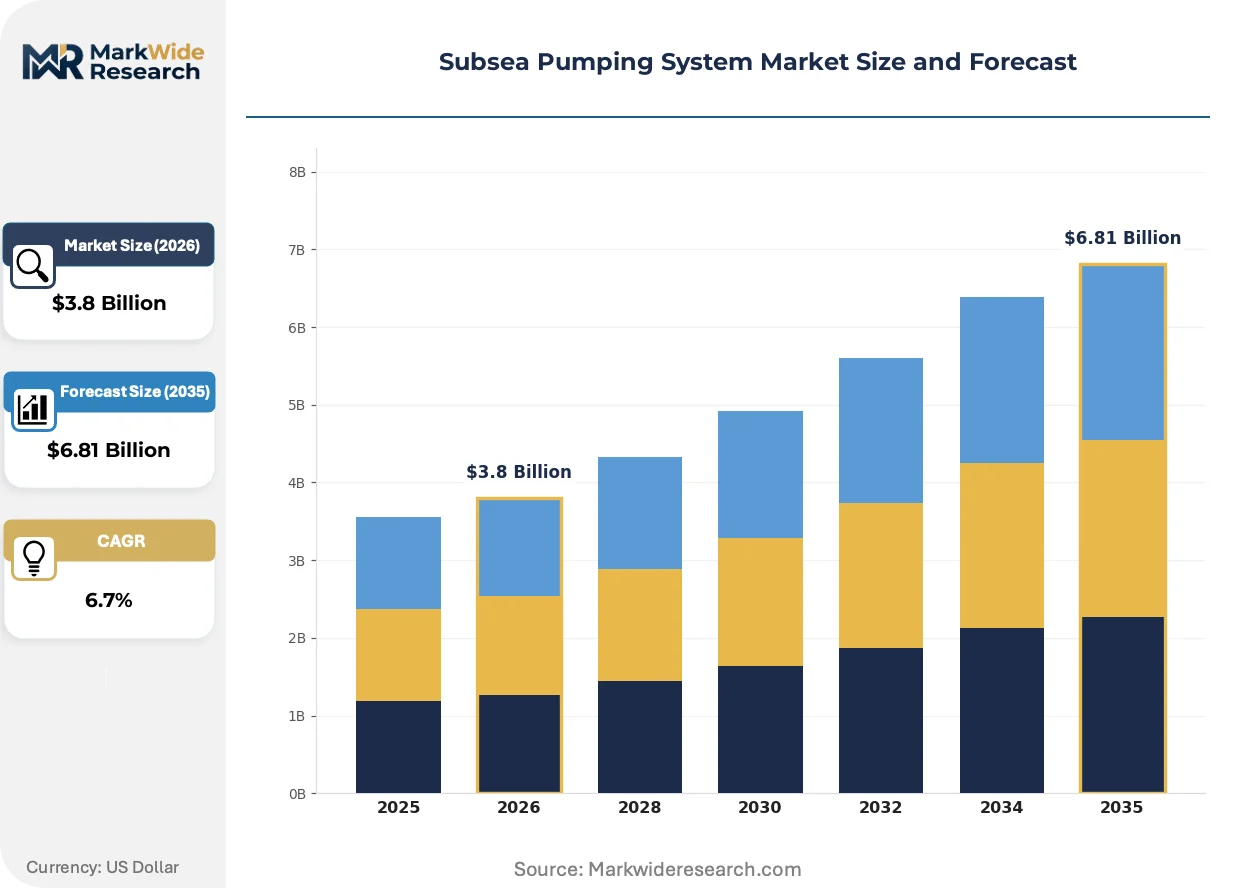
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Pumps, Hydraulic Pumps, Submersible Pumps, Positive Displacement Pumps Application: Oil Extraction, Water Injection, Gas Lifting, Produced Water Management Installation Type: Fixed Systems, Mobile Systems, Modular Systems, Integrated Systems End User: Oil & Gas Companies, Offshore Platforms, Subsea Contractors, Energy Providers |
| Companies Covered | Baker Hughes Company, Schlumberger Limited, TechnipFMC plc, Aker Solutions ASA, Oceaneering International Inc., Halliburton Company, OneSubsea, Flowserve Corporation, Weatherford International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Pumping System Market Evolving Landscape
Wet gas compression technology is advancing rapidly as operators seek to boost multiphase flows without surface separation, compressing facility footprints and enabling tieback developments previously deemed uneconomic.
Permanent magnet motor technology is absorbing market share in high-horsepower subsea pump applications by eliminating gearbox maintenance and reducing power consumption. Major operators in Brazil and the Gulf of Mexico are specifying PMM-driven systems for new pre-salt and Lower Tertiary developments. The technology is absorbing engineering resources from traditional induction motor suppliers and forcing recalibration of aftermarket service strategies.
The EU's F-Gas Regulation is tightening restrictions on fluorinated greenhouse gases used in subsea cooling and insulation systems, compelling equipment redesigns across European continental shelf projects. Manufacturers are accelerating qualification of alternative dielectric fluids and vacuum-insulated motor designs to maintain market access. Offshore Norway faces the most immediate compliance pressure as the Petroleum Safety Authority integrates F-Gas phase-down timelines into facility consent processes.
Integrated service contracts are displacing equipment-only procurement as operators transfer operational risk to vendors through availability-based remuneration structures. International oil companies in Brazil and West Africa are bundling subsea pump supply with long-term maintenance and performance guarantees. This restructuring concentrates contract value among system integrators with in-house turbomachinery and controls capabilities.
Subsea Pumping System Market Segmentation
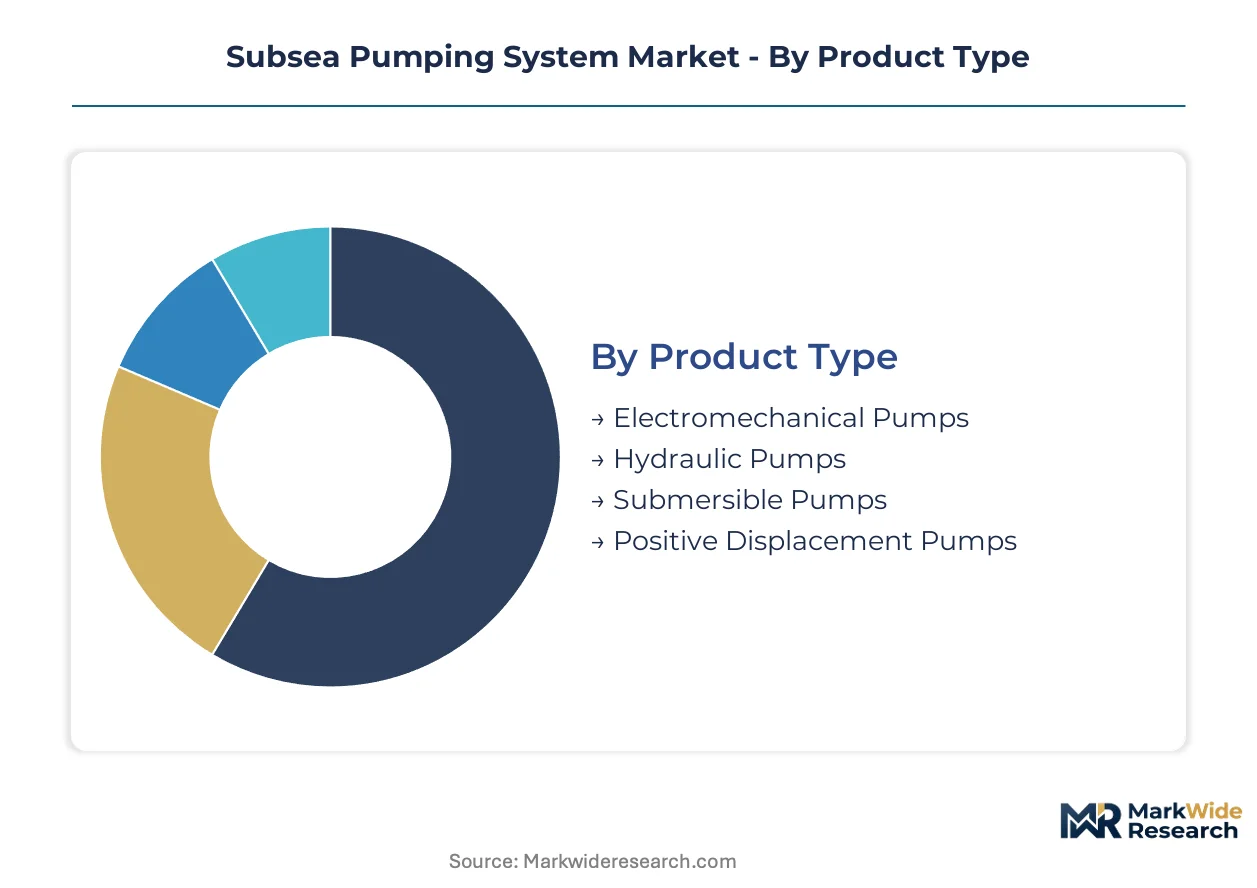
Subsea pumping system procurement hinges on matching pressure-boosting technology to reservoir characteristics and installation constraints. Operators weigh capital efficiency against operational flexibility when selecting across product architectures and deployment modes.
Product Type:
Equipment selection pivots on horsepower requirements and power transmission method, with electromechanical systems commanding premium contracts in deepwater crude service.
- Electromechanical Pumps:High-horsepower motor-driven centrifugal systems deliver crude oil boosting at pressures exceeding 10,000 psi. Brazil's pre-salt operators specify these for multi-well tieback architectures where efficiency and reliability dominate total cost of ownership calculations.
- Hydraulic Pumps:Fluid-driven positive displacement units operate without submerged electrical components, suiting chemical injection and gas lift duties. North Sea producers deploy these for subsea distribution where IEC 61508 redundancy requirements complicate electromechanical control architectures.
- Submersible Pumps:Sealed motor-pump assemblies for moderate-depth water injection service.
- Positive Displacement Pumps:Reciprocating or screw-type mechanisms for high-viscosity crude and multiphase flows.
Volume sits with electromechanical pumps; growth tilts toward hydraulic systems in gas lift retrofit applications.
Application:
Functional deployment determines system specification intensity, with crude extraction demanding the highest pressure ratings and control complexity.
- Oil Extraction:Reservoir pressure maintenance through subsea boosting of production flows to surface facilities. Gulf of Mexico operators deploy large-scale architectures here as Lower Tertiary discoveries require horsepower ratings above 5,000 to overcome natural decline.
- Produced Water Management:Formation water reinjection systems that maintain reservoir pressure while meeting discharge limits. Norway's Petroleum Safety Authority enforcement of stricter environmental protocols accelerates subsea pump deployment for this function.
- Water Injection:Seawater or aquifer water pressurization for secondary recovery.
- Gas Lifting:Artificial lift through compressed gas injection downhole.
Revenue concentrates in oil extraction; produced water management is climbing fastest as regulatory pressure mounts.
Installation Type:
Deployment architecture shapes offshore construction schedules and supplier risk allocation, with integrated packages displacing component-level procurement.
- Modular Systems:Skid-mounted pump packages pre-assembled and factory-tested before offshore transport. West Africa greenfield developments favor these for compressed installation windows where vessel day rates dominate project economics.
- Integrated Systems:Combined pump, control, and distribution units from single-source suppliers. Brazil's Petrobras mandates this approach for pre-salt complexity, transferring interface risk to vendors with in-house turbomachinery and controls capabilities.
- Fixed Systems:Permanent seabed installations for long-field-life developments.
- Mobile Systems:Retrievable units for marginal field tiebacks and intervention access.
Contract value pools in integrated systems; modular formats are expanding most quickly in cost-sensitive provinces.
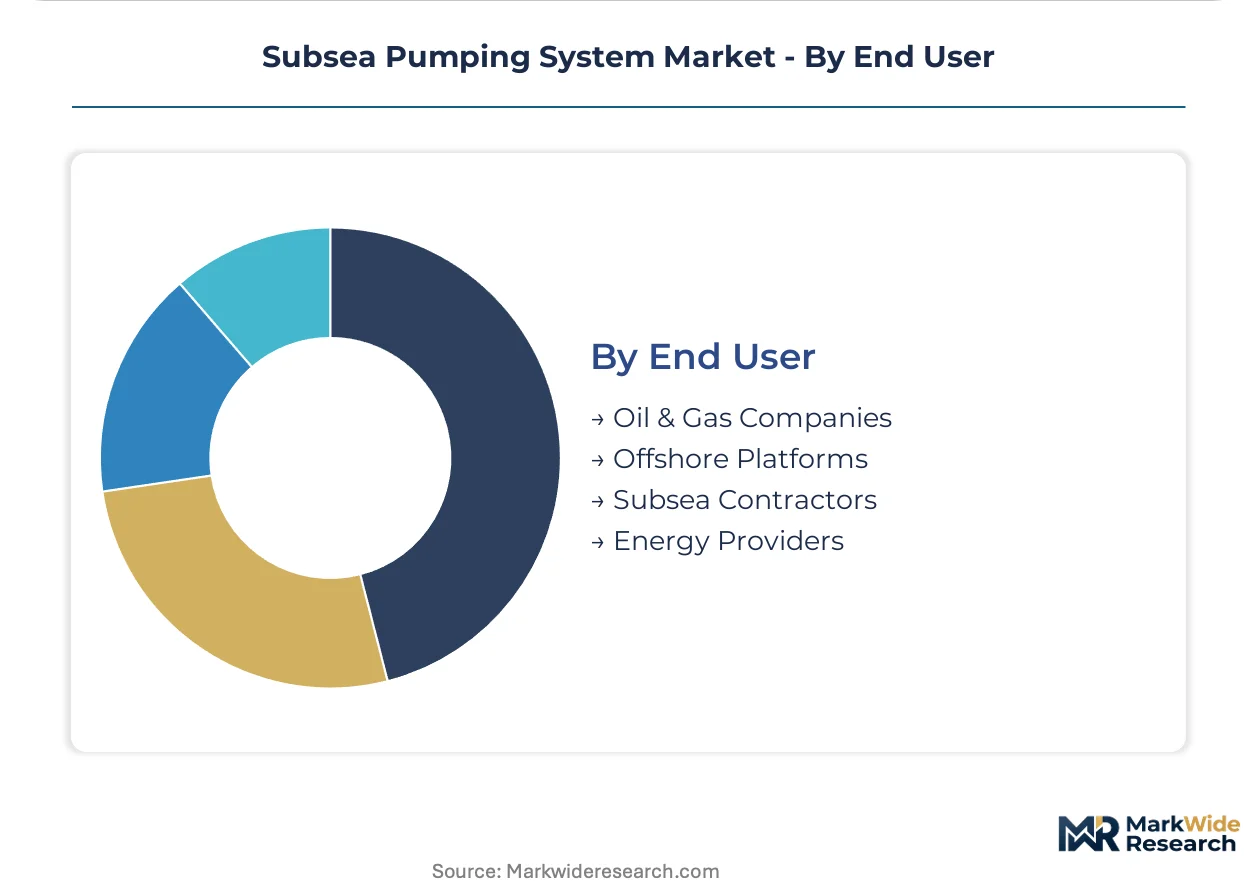
End User:
Buyer sophistication and balance sheet capacity determine procurement model selection, from equipment-only purchase to full-service availability contracts.
- Oil & Gas Companies:International and national oil companies with direct reservoir equity. These operators in Brazil and the Gulf of Mexico drive specification standards and consolidate contract awards among qualified system integrators.
- Subsea Contractors:Engineering, procurement, and construction firms executing field development programs. These intermediaries in Norway and the UK continental shelf bundle pump supply into larger subsea infrastructure packages.
- Offshore Platforms:Facility owners requiring boosting equipment for tieback processing.
- Energy Providers:Diversified utilities with offshore production assets.
Decision authority rests with oil and gas companies; subsea contractors are gaining procurement influence in integrated project delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt special fiscal regime anchors offshore equipment demand, concentrating subsea infrastructure investment in ultra-deepwater provinces where tax incentives accelerate field development timelines.
Brazil
Petrobras deploys large-scale boosting architectures across the Santos Basin pre-salt cluster, with international operators committing to multi-well tieback systems. ANP's local content requirements mandate domestic fabrication quotas for subsea equipment. Rio de Janeiro's Porto do Açu complex hosts integrated system assembly for pre-salt developments.
Norway
Equinor and Aker BP advance subsea processing tiebacks in the North Sea and Norwegian Sea to extend mature field economics. The Petroleum Safety Authority enforces IEC 61508 functional safety mandates requiring redundant control architectures. Stavanger's subsea technology cluster concentrates engineering expertise for high-pressure pump qualification.
United States
Lower Tertiary discoveries in the Gulf of Mexico drive demand for high-horsepower electromechanical systems above 5,000 horsepower. BSEE's well control regulations shape subsea equipment testing protocols for deepwater deployments. Houston's Energy Corridor hosts system integrators executing integrated project delivery for ultra-deepwater operators.
United Kingdom
North Sea decommissioning liabilities and carbon intensity benchmarks create demand for pump refurbishment and life-extension services. The North Sea Transition Authority's asset stewardship expectations pressure operators to defer capital replacement through equipment upgrades. Aberdeen's subsea supply chain coordinates life-of-field service contracts for aging infrastructure.
United Arab Emirates
ADNOC's expansion of artificial island developments and ultra-sour gas projects requires specialized subsea boosting for high-corrosion service. ADNOC's in-country value program mandates local manufacturing participation for offshore equipment procurement. Abu Dhabi's Khalifa Industrial Zone attracts subsea component fabricators serving Middle East offshore developments.
Subsea Pumping System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the subsea pumping system value chain, creating a tiered structure where integrated capabilities command premium contract positioning. The market consolidates around turbomachinery heritage and controls integration competence. Three archetypes dominate: full-system integrators with in-house pump and controls manufacturing, component specialists supplying into larger packages, and oilfield service conglomerates leveraging drilling relationships for equipment placement. Competitive moves concentrate on integrated project delivery partnerships and backward integration into high-pressure alloy fabrication.
Among diversified energy technology conglomerates, Baker Hughes Company and Schlumberger Limited occupy positions anchored by turbomachinery heritage and subsea processing joint ventures. TechnipFMC plc exemplifies the integrated system delivery archetype, controlling critical interfaces between pump modules and distribution units. These three entities represent the premium tier where contract value concentrates through availability-based remuneration structures.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Schlumberger Limited |
| TechnipFMC plc |
| Aker Solutions ASA |
| Oceaneering International Inc. |
| Halliburton Company |
| OneSubsea |
| Flowserve Corporation |
| Weatherford International plc |
| Others |
Value Network & Pricing Analysis
International oil companies in Brazil and the Gulf of Mexico anchor procurement volume for subsea pumping systems, concentrating contract awards among three integrated suppliers who command premium positioning through availability-based remuneration structures. This buyer concentration creates asymmetric pricing power where electromechanical pump packages for pre-salt developments trade at significant premiums over standard configurations.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Petrobras and Equinor compress project sanctioning timelines for pre-salt and North Sea tiebacks. Three-tier pricing structure across integrated system, modular package, and component-only levels separates full-service availability contracts from equipment-only procurement. Cost compression in hydraulic pump segments is intensifying because electromechanical systems capture all high-horsepower crude boosting above 5,000 horsepower. National oil companies show highest price sensitivity, while international majors prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Regional distribution centers in Stavanger, Houston, and Rio de Janeiro coordinate hub-and-spoke patterns for high-pressure pump modules and subsea controls. Manufacturing concentrates in Norway, the United States, and France for electromechanical systems; Japan and Germany anchor specialized alloy supply for duplex stainless steel housings. Raw material dependencies include super-duplex steel forgings, high-voltage wet-mate connectors, and permanent magnet motor assemblies. Single-source vulnerability in European and Japanese mill capacity for corrosion-resistant alloys creates input cost volatility. Distribution runs through integrated system integrators who control final assembly and offshore commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subsea pumping system supply is tightening around qualified electromechanical pump capacity, with API 17D certification timelines and super-duplex alloy lead times propping pricing power for integrated suppliers.
For Market Incumbents: Deploy backward integration into high-pressure alloy fabrication to secure captive supply of duplex steel forgings against Japanese and European mill concentration. Lock in long-term service contracts with Petrobras and Equinor before permanent magnet motor technology commoditizes. Hydraulic pump substitution from electromechanical systems threatens niche positioning; defend through IEC 61508-compliant control architectures for North Sea chemical injection duties. For New Entrants and Emerging Players: API RP 17V in the United States opens a window for specialized testing and qualification service providers as extended factory acceptance protocols strain incumbent manufacturing capacity. West Africa greenfield developments off Senegal and Mauritania present the most penetrable geography for first-mover integrated system positioning. Target produced water management retrofit opportunities in the UK North Sea where decommissioning liabilities pressure operators toward life-extension over capital replacement. For Investors and Strategic Acquirers: The window for entry favors controls integration specialists with software engineering talent for subsea distribution unit interfaces. Long-term viability hinges on electrification convergence—high-voltage wet-mate connector capabilities and variable speed drive competence determine acquisition value. Watch F-Gas Regulation compliance timelines in Norway as the inflection indicator for alternative dielectric fluid qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive supply of super-duplex steel eliminates Japanese and European mill dependency for high-pressure housings. |
| Permanent Magnet Motor Qualification | Brazil's pre-salt operators specify PMM-driven systems for efficiency gains in ultra-deepwater boosting service. |
| Integrated Service Contract Expansion | Availability-based remuneration transfers operational risk from Petrobras to vendors with turbomachinery heritage. |
| West Africa Greenfield Positioning | Senegal and Mauritania developments reward first-mover integrated system suppliers with compressed installation windows. |
| F-Gas Alternative Fluid Development | Norway's Petroleum Safety Authority integrates phase-down timelines into facility consent processes for European shelf access. |
Research Methodology
Document review covered subsea equipment qualification records, API 17D certification databases, and offshore project sanctioning announcements, complemented by interviews with subsea project engineers at international oil companies, turbomachinery procurement leads at national operators, controls systems specialists at integrated suppliers, and aftermarket service directors at component fabricators. Secondary validation drew from BSEE well control filings, Norwegian Petroleum Safety Authority facility consents, ANP local content compliance reports, and SEC disclosures from listed energy technology conglomerates. Bottom-up project pipeline aggregation was cross-checked against top-down equipment demand modeling.
Historical deployment patterns for electromechanical and hydraulic pump systems were cross-referenced against panel input from subsea engineering consultants to establish baseline penetration rates across the projection horizon. Segmentation dimensions modeled include product architecture, application function, installation type, and end-user procurement sophistication. CAGRs were derived from capacity-weighted project timelines and equipment specification intensity curves. Forecast inputs incorporated pre-salt basin development schedules, IEC 61508 functional safety mandate adoption, and permanent magnet motor technology displacement curves.
The model assumes a particular technology adoption path for all-electric subsea boosting architectures; alternative pathways for hydraulic power unit retention would alter the outlook for umbilical complexity and controls integration demand. Forecasts reflect documented assumptions regarding alloy supply elasticity, certification timeline stability, and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Droplet Separator Market