
 North America Axial Flow Pump Market | 2026-2036
North America Axial Flow Pump Market Size, Share, and Industry Trends Forecast 2026-2036
North America Axial Flow Pump Market Analytics
Buyer concentration across municipal water authorities is shifting as regional utility mergers consolidate procurement budgets across the Great Lakes and Ohio River watersheds. Flowserve Corporation leverages its aftermarket service network to sustain long-term municipal contracts. Xylem Inc. anchors its position through vertical integration into pump control systems. Sulzer AG competes on specialized alloys for abrasive wastewater applications.
An axial flow pump moves fluid parallel to the pump shaft using a propeller-shaped impeller, typically achieving flow rates exceeding 100,000 gallons per minute at low discharge heads for flood control and drainage systems. Submersible installations dominate municipal wastewater applications where dry-pit construction costs prove prohibitive. High capacity units command premium pricing in the oil and gas segment where continuous-duty reliability requirements exceed standard industrial specifications. Specialty configurations for offshore platforms represent the fastest-growing installation category as Gulf of Mexico producers deepen subsea tiebacks.
EPA enforcement of the Clean Water Act and NPDES permit standards shapes product specifications across the wastewater treatment segment, while API 610 compliance governs refinery and petrochemical pump selections. OSHA lockout-tagout regulations influence maintenance-access design for industrial facility installations. Stakeholders must monitor how evolving PFAS remediation mandates redirect municipal capital budgets toward higher-specification pump infrastructure.
Market Dynamics
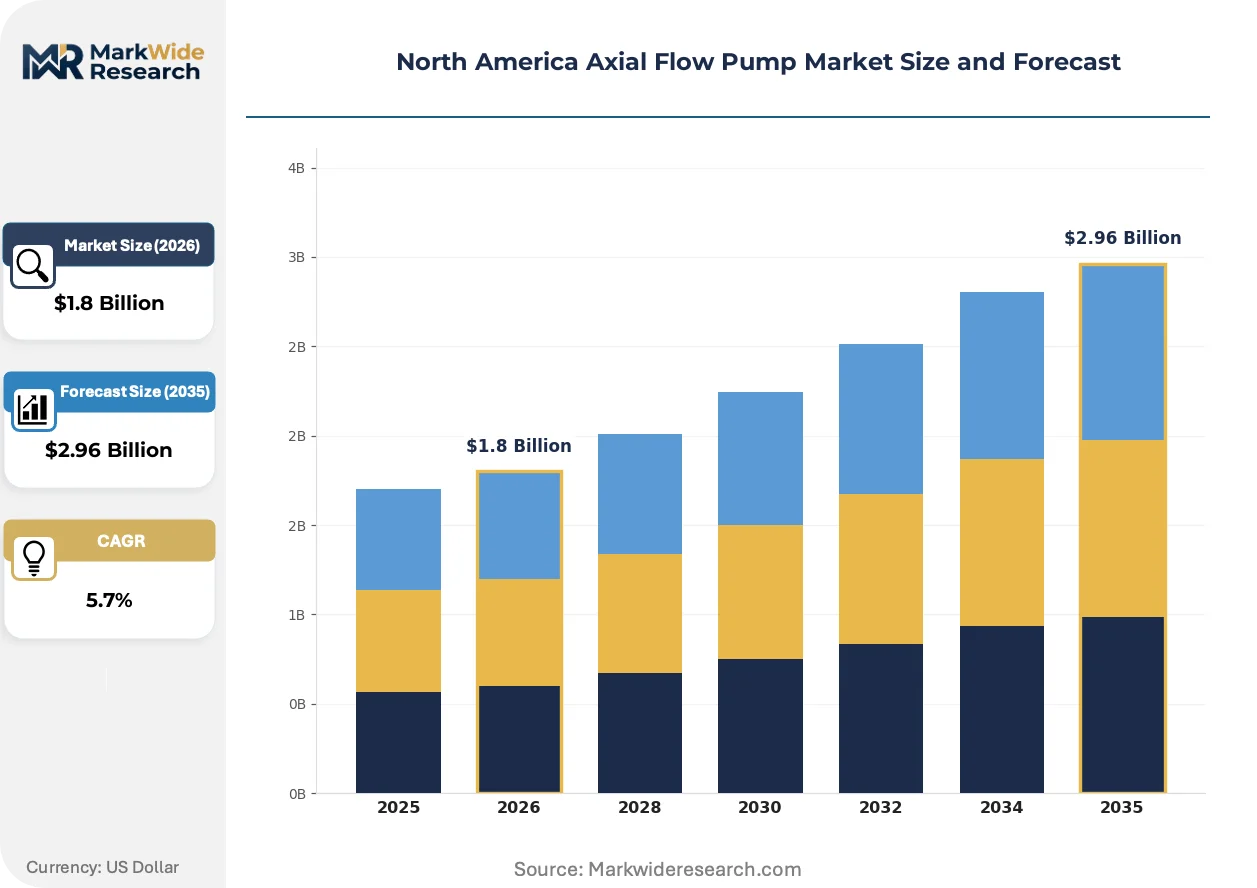
Combined sewer overflow mandates and refinery capacity additions on the Texas Gulf Coast are compressing procurement timelines while elevating technical specifications for high-capacity axial flow pump installations.
Growth Catalysts
- EPA Clean Water Act Enforcement:Tighter NPDES discharge standards across the Great Lakes basin are forcing municipal wastewater utilities to upgrade pump infrastructure for combined sewer overflow containment.
- Petrochemical Corridor Expansion:Refinery capacity additions along the Texas Gulf Coast are generating sustained demand for API 610-compliant specialty pumps with continuous-duty reliability specifications.
- Submersible Installation Preference:Dry-pit construction cost inflation is accelerating adoption of submersible configurations in municipal wastewater applications where budget constraints dominate capital planning.
Market Restraints
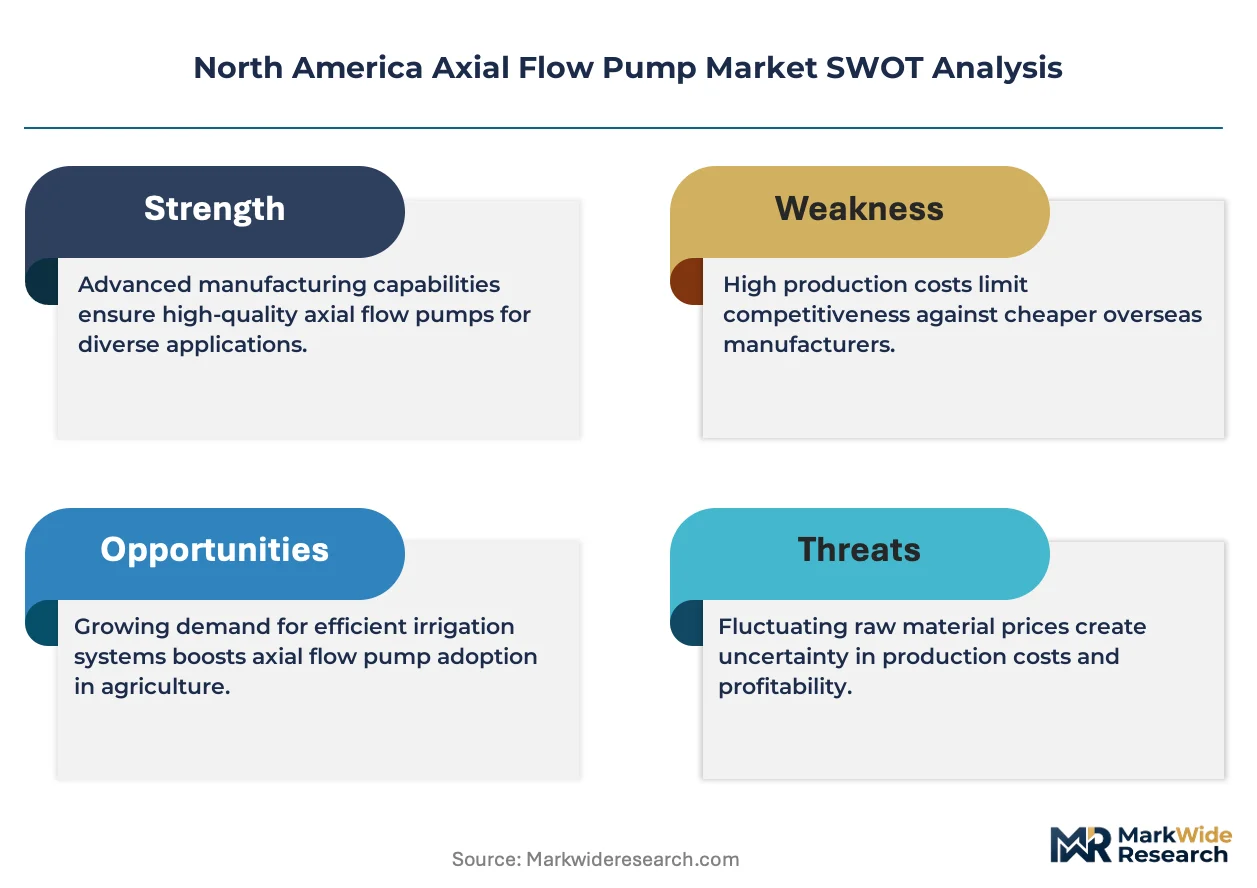
- Specialty Alloy Input Volatility:Nickel and chromium price swings directly impact manufacturing costs for abrasive wastewater pump configurations requiring hardened impeller materials.
- Gulf Coast Supply Concentration:Hurricane exposure risk along the Houston Ship Channel creates single-point vulnerability for pump assembly and coating operations serving North American demand.
- Technical Limitation at Depth:Seawater corrosion challenges constrain subsea tieback pump lifespans in deepwater Gulf of Mexico installations beyond 5,000 feet.
Strategic Opportunities
- PFAS Remediation Infrastructure:Emerging EPA mandates for per- and polyfluoroalkyl substance treatment are redirecting municipal capital budgets toward higher-specification pump systems with advanced sealing technologies.
- Canada Oil Sands Recovery:Underpenetrated opportunities exist in Alberta thermal extraction operations requiring high-volume, low-head pumps for steam-assisted gravity drainage water handling.
- Pump Control System Convergence:Integration of variable frequency drives with predictive maintenance software creates aftermarket revenue expansion for original equipment manufacturers.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX qualified welder shortages constrain production scaling for duplex stainless steel pump housings specified in offshore platform contracts.
- Legacy Control Integration:Municipal SCADA system incompatibility with modern digital pump monitoring creates deployment friction and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Axial Flow Pump Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Vertical, Horizontal, Specialty End User: Agriculture, Oil & Gas, Water Supply, Wastewater Treatment Installation: Onshore, Offshore, Pumping Station, Industrial Facility Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Flowserve Corporation, KSB SE & Co. KGaA, Sulzer AG, Grundfos AS, Weir Group PLC, Xylem Inc., Pentair PLC, Franklin Electric, Patterson Pump Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Axial Flow Pump Market Evolving Landscape
Digital monitoring systems and advanced material formulations are compressing maintenance intervals while expanding operational envelopes for axial flow pump deployments across municipal and industrial segments.
Computational fluid dynamics-optimized impeller geometries are overtaking traditional propeller designs in municipal flood control applications. Texas Gulf Coast drainage districts are specifying these profiles for 15% efficiency gains at partial load conditions. The technology is compressing energy consumption benchmarks for high-volume, low-head installations.
OSHA lockout-tagout regulatory updates are forcing redesign of pump access configurations in industrial facilities. Maintenance-platform geometry and isolation valve placement now face heightened scrutiny during pre-approval engineering reviews. Refinery operators in Louisiana and Texas are prioritizing designs that minimize confined-space entry requirements.
Performance-based service agreements are displacing traditional time-and-materials maintenance contracts in municipal procurement. Ohio River watershed utilities are bundling pump availability guarantees with remote monitoring subscriptions. This shift concentrates vendor selection criteria on demonstrated mean-time-between-failure data rather than upfront capital cost.
North America Axial Flow Pump Market Segmentation
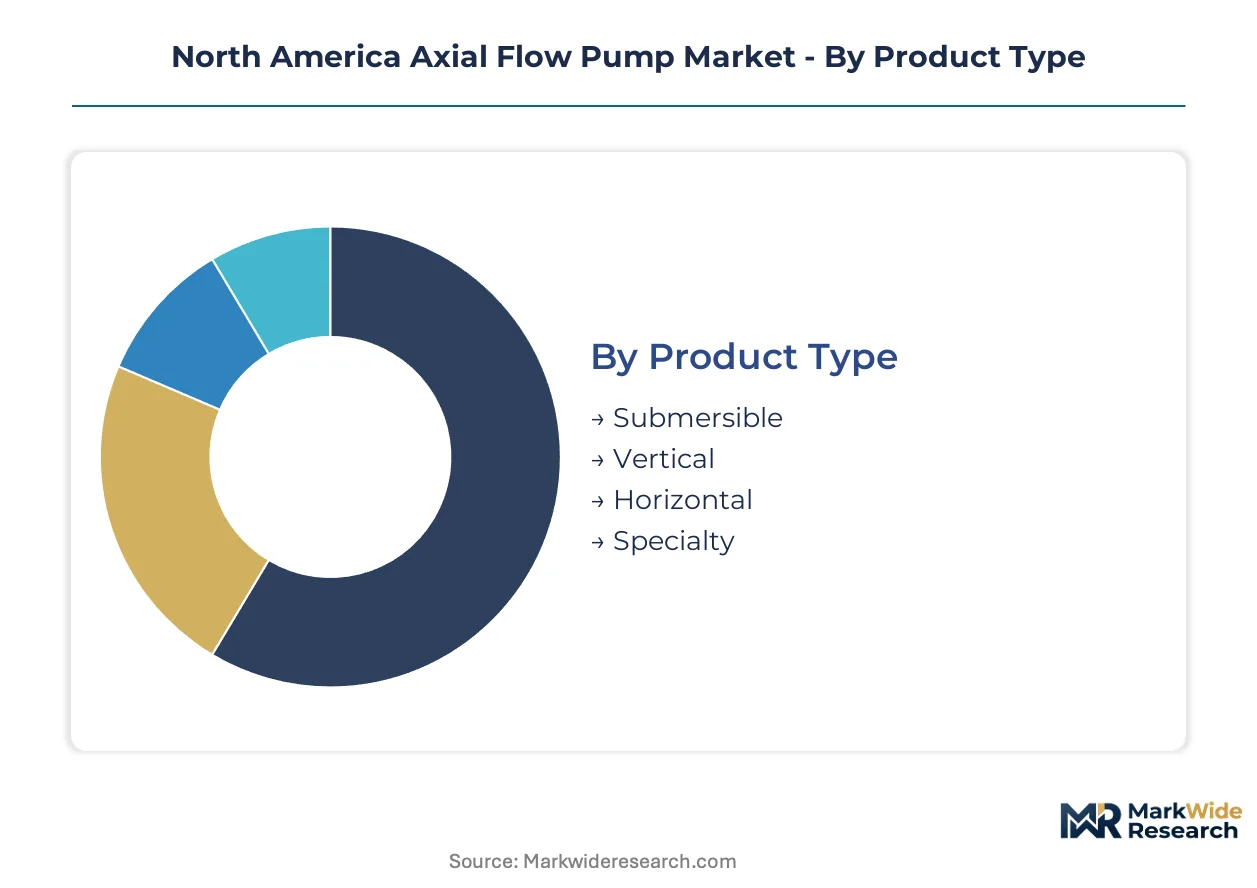
Axial flow pump procurement patterns diverge sharply across installation environments and duty specifications. Understanding these segment boundaries clarifies why submersible configurations dominate municipal budgets while specialty alloys command premium pricing in hydrocarbon extraction.
Product Type:
Impeller geometry and motor housing architecture define performance envelopes across flood control, process circulation, and deep-well dewatering applications.
- Submersible:Fully sealed motor and pump assemblies operate submerged in wet wells, eliminating dry-pit construction costs. Texas Gulf Coast drainage districts specify these for combined sewer overflow containment where EPA enforcement has tightened discharge standards.
- Vertical:Column-suspended designs with above-grade motors suit high-flow, low-head irrigation and cooling water circulation. Great Lakes basin utilities favor vertical configurations for raw water intake structures where maintenance access remains critical.
- Horizontal:Split-case or end-suction arrangements dominate industrial process loops with above-ground piping galleries. Ohio River watershed chemical processors specify horizontal pumps for abrasive slurry handling.
- Specialty:Custom-engineered units incorporate duplex stainless alloys or titanium impellers for seawater corrosion resistance. Offshore platform contractors in the Gulf of Mexico deploy these for subsea tieback installations beyond standard depth ratings.
Mature deployment sits with Vertical configurations in agricultural and municipal water supply. Newer deployment is concentrated in Specialty designs for deepwater hydrocarbon extraction.
End User:
Capital allocation cycles and regulatory exposure create distinct specification requirements across primary demand verticals.
- Agriculture:Large-scale irrigation districts in California's Central Valley and the High Plains Aquifer region specify high-volume, low-head pumps for groundwater transfer. Energy efficiency mandates from state water authorities are accelerating variable frequency drive adoption.
- Oil & Gas:Refinery capacity additions along the Texas Gulf Coast require API 610-compliant continuous-duty pumps with specialized mechanical seals. Steam-assisted gravity drainage operations in Alberta oil sands represent underpenetrated demand for thermal extraction water handling.
- Water Supply:Raw water intake and distribution systems in the Great Lakes basin emphasize reliability guarantees over upfront capital cost. Regional utility mergers are consolidating procurement budgets across watershed boundaries.
- Wastewater Treatment:Municipal utilities face combined sewer overflow mandates and emerging PFAS remediation requirements. EPA Clean Water Act enforcement is redirecting capital toward higher-specification pump infrastructure with advanced sealing technologies.
Established procurement patterns characterize Water Supply. The steepest expansion trajectory appears in Wastewater Treatment as regulatory mandates compound.
Installation:
Site constraints and environmental exposure dictate material selection, access geometry, and monitoring system integration.
- Onshore:Standard industrial and municipal installations with above-grade or dry-pit configurations. OSHA lockout-tagout regulations are forcing redesign of maintenance-platform geometry in refinery and chemical processing facilities.
- Offshore:Platform-mounted and subsea tieback pumps face seawater corrosion and accessibility constraints. Technical limitations beyond 5,000 feet constrain pump lifespans in deepwater Gulf of Mexico developments.
- Pumping Station:Centralized flood control and drainage infrastructure in coastal Louisiana and Texas. Computational fluid dynamics-optimized impeller geometries are displacing traditional propeller designs for partial-load efficiency gains.
- Industrial Facility:Process-integrated circulation within petrochemical complexes and power generation plants. Confined-space entry minimization has become a priority criterion in pre-approval engineering reviews.
Conventional deployment dominates Onshore installations. Offshore represents the fastest-climbing category as Gulf producers deepen subsea developments.
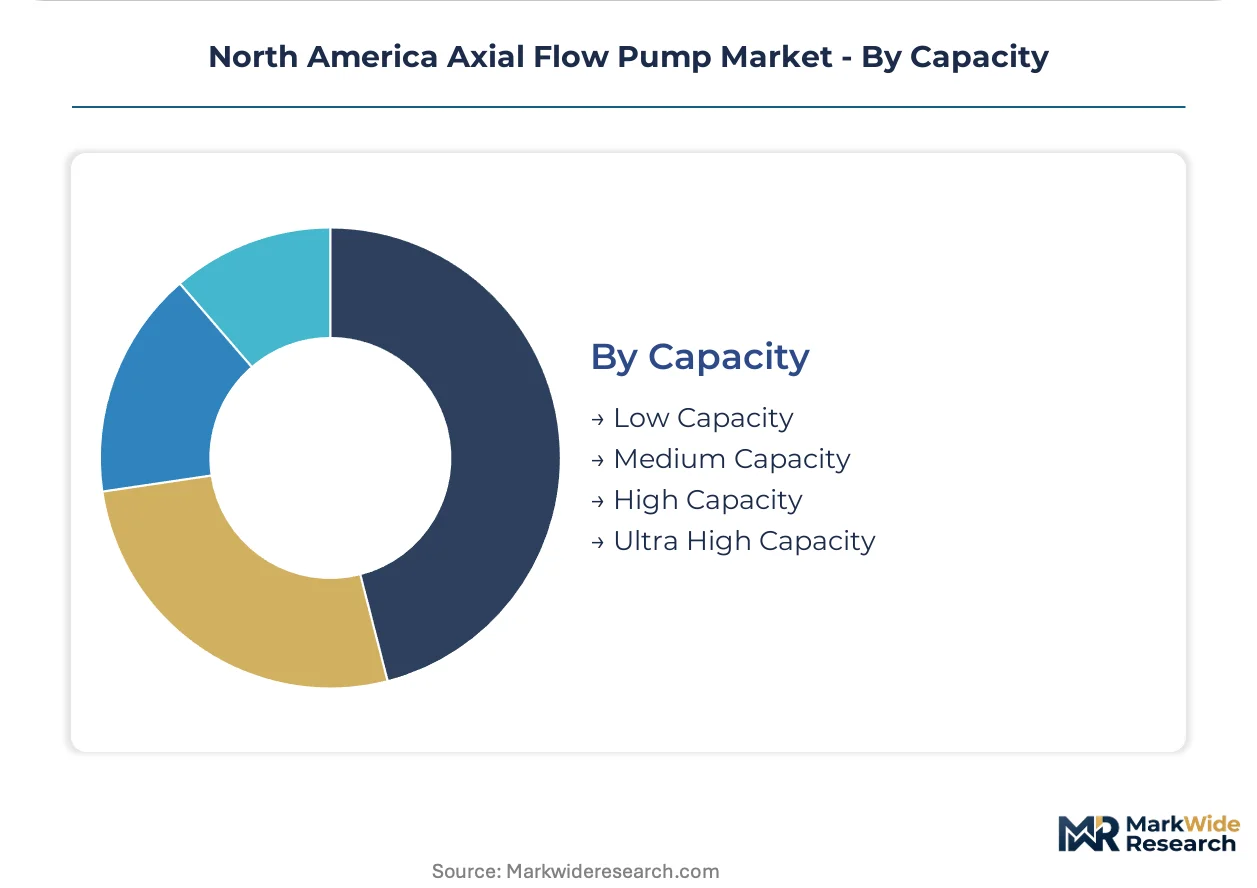
Capacity:
Flow rate thresholds determine impeller diameter, motor sizing, and structural foundation requirements across application segments.
- Low Capacity:Units below 10,000 gallons per minute serve localized drainage and small-scale irrigation. These configurations face margin compression from standardized manufacturing and limited customization requirements.
- Medium Capacity:10,000 to 50,000 gallons per minute range covers municipal wastewater lift stations and industrial process loops. Dry-pit construction cost inflation is accelerating submersible preference in this bracket.
- High Capacity:50,000 to 100,000 gallons per minute units dominate flood control districts and refinery cooling water systems. Premium pricing reflects continuous-duty reliability specifications exceeding standard industrial ratings.
- Ultra High Capacity:Exceeding 100,000 gallons per minute, these pumps address combined sewer overflow containment and large-scale raw water transfer. Nickel and chromium price volatility directly impacts manufacturing costs for hardened impeller materials in this segment.
Volume concentration rests with Medium Capacity municipal applications. Ultra High Capacity is gaining share fastest as infrastructure resilience funding expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel and chromium mining corridors in Ontario and Quebec supply specialty alloys for hardened impeller production across North American pump fabrication networks.
United States
Texas Gulf Coast petrochemical corridor drives API 610-compliant specialty pump demand for refinery capacity additions. EPA Clean Water Act enforcement tightens NPDES discharge standards across Great Lakes basin utilities. Houston Ship Channel assembly operations face hurricane exposure risk for coating and fabrication serving continental demand.
Canada
Alberta oil sands thermal extraction operations require high-volume, low-head pumps for steam-assisted gravity drainage water handling. Environment and Climate Change Canada regulations govern effluent quality from mining operations. Ontario manufacturing clusters around Hamilton and Sarnia supply duplex stainless steel components for abrasive wastewater configurations.
Mexico
Nuevo León industrial corridor attracts petrochemical pump procurement for Monterrey-area processing facilities. CONAGUA water authority mandates shape municipal wastewater infrastructure specifications. Northern border states concentrate maquiladora assembly operations serving cross-border supply chains for standard industrial pump configurations.
North America Axial Flow Pump Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital monitoring integration and predictive maintenance platforms. The vendor structure concentrates around three capability clusters: full-service multinationals with aftermarket networks, specialized alloy fabricators for abrasive applications, and integrated control system providers. Consolidation pressures favor scale players with captive service infrastructure. Competitive moves center on vertical integration into pump control electronics and performance-based service contract bundling.
Among Swiss-headquartered industrial specialists, Sulzer AG exemplifies the hardened-materials archetype for abrasive wastewater duty. Flowserve Corporation anchors the full-service multinational tier with extensive North American aftermarket presence. Xylem Inc. occupies a position emphasizing integrated control system convergence for municipal utility accounts.
| Leading Market Players |
|---|
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Sulzer AG |
| Grundfos AS |
| Weir Group PLC |
| Xylem Inc. |
| Pentair PLC |
| Franklin Electric |
| Patterson Pump Company |
| Others |
Value Network & Pricing Analysis
ASME Section IX certified welder concentrations in the Ohio River watershed and Ontario manufacturing corridors create labor-cost differentials that widen pricing spreads between premium offshore-rated pumps and standard municipal configurations. Nickel and chromium alloy premiums compound these tier separations as buyers trade off corrosion resistance against capital budget constraints.
Pricing Analysis
Volume concentrates in medium-capacity municipal submersibles while margins accrue to ultra-high-capacity specialty units for offshore tiebacks. Three-tier pricing structure across premium, standard, and economy levels separates API 610-certified continuous-duty pumps from dry-pit alternatives and irrigation-grade configurations. Cost compression in standard municipal tiers intensifies because of consolidated procurement budgets across Great Lakes utility mergers. Agricultural irrigation districts exhibit highest price sensitivity while Gulf petrochemical operators prioritize reliability guarantees over upfront capital cost.
Supply Chain Analysis
Specialty alloy supply rests on Ontario and Quebec nickel-chromium mining corridors, with duplex stainless fabrication concentrated in Hamilton and Sarnia industrial clusters. Pump casting and precision machining draw from Ohio River basin foundries, while final assembly and coating operations concentrate along the Houston Ship Channel. Single-source vulnerability runs through hurricane-exposed Gulf Coast coating facilities serving continental demand. Distribution runs through manufacturer-direct municipal contracts and industrial distributor networks for standard configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Clean Water Act enforcement and API 610 certification requirements create regulatory moats that favor incumbent players with established testing protocols and documented mean-time-between-failure data.
For Market Incumbents: Lock in long-term municipal service contracts by bundling predictive maintenance subscriptions with pump availability guarantees. Deepen backward integration into pump control electronics to capture margin from variable frequency drive convergence. Consolidate position against emerging digital-native entrants through captive aftermarket service infrastructure across Great Lakes and Ohio River watersheds. For New Entrants and Emerging Players: Municipal SCADA integration specialists offer the most penetrable channel partnership path for digital monitoring platforms targeting legacy control incompatibility pain points. Alberta oil sands thermal extraction water handling presents underpenetrated white-space for high-volume, low-head pump configurations. Pursue performance-based contracting models that displace time-and-materials maintenance arrangements in Ohio River watershed utilities. For Investors and Strategic Acquirers: Re-rating potential sits with specialized alloy fabricators possessing ASME Section IX welding certifications and documented offshore platform deployment records given accelerating Gulf of Mexico subsea tieback activity. Five-to-ten year viability favors players with captive control system integration capabilities and installed base telemetry access. Watch EPA PFAS remediation mandate timing as capital budget redirection signal for higher-specification pump infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Ontario duplex stainless supply secures margin control for abrasive wastewater configurations. |
| Predictive Maintenance Platform Launch | Remote monitoring subscriptions capture recurring revenue from Ohio River watershed utilities. |
| API 610 Certification Investment | Refinery compliance documentation opens Texas Gulf Coast petrochemical procurement channels. |
| Joint Venture with SCADA Integrators | Legacy control compatibility solutions reduce municipal deployment friction and commissioning delays. |
| Capacity Expansion in Alberta | Proximity to oil sands thermal extraction operations shortens lead times for steam-assisted gravity drainage water handling. |
Research Methodology
Trade association filings, EPA enforcement action records, and municipal procurement databases formed the secondary backbone for demand quantification and regulatory timeline mapping. Primary interviews with wastewater treatment plant engineers, petrochemical maintenance directors, pump distributor account managers, and aftermarket service technicians validated specification trends and procurement decision criteria. Bottom-up unit demand estimates across capacity tiers and installation types triangulated against top-down capital expenditure flows from utility and industrial operator budgets.
Top-down macroeconomic drivers and bottom-up segment-specific demand elasticities converged in the analytical framework. Segmentation dimensions spanned product architecture, end-use vertical, installation environment, and flow capacity tier. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and announced infrastructure project pipelines. Nickel price volatility coefficients and hurricane frequency assumptions informed cost and supply risk sensitivities.
Caveats apply where EPA PFAS mandate implementation timing, Gulf Coast hurricane severity, or nickel-chromium commodity swings could materially shift the outlook. Forecasts embed assumptions regarding continued Clean Water Act enforcement intensity and refinery capacity addition schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market