
 Oil and Gas Actuators Market | 2026-2036
Oil and Gas Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Actuators Market Analytics
Remote monitoring and predictive maintenance subscriptions is expanding the recurring revenue base for actuator suppliers beyond hardware sales. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor long-term service contracts with upstream operators. Rotork competes through its specialized service networks in offshore environments. Flowserve Corporation extends its aftermarket footprint through condition-based monitoring programs tied to actuator fleets.
Oil and gas actuators are electromechanical or fluid-powered devices that convert energy into mechanical motion to operate valves, chokes, and flow control equipment, typically delivering torque outputs from tens to thousands of newton-meters depending on application pressure class. These systems serve the critical function of enabling automated or remote operation of process equipment in hazardous, high-pressure hydrocarbon environments where manual intervention poses safety risks. Electric actuators lead the type category due to their precision control and lower maintenance profiles in onshore facilities, while smart actuators represent the fastest-growing technology segment as operators integrate IoT-enabled diagnostics to reduce unplanned shutdowns. Conventional actuators still occupy substantial installed bases across mature basins where capital replacement cycles lag digital upgrade timelines.
The EPA enforces methane performance standards under NSPS OOOOa that mandate leak detection and repair protocols, directly driving demand for automated valve actuation that eliminates manual venting events. API 6D and ISO 5211 standards govern actuator-to-valve interface dimensions and testing protocols, shaping product design requirements for market access across North American and international projects. OSHA process safety management rules further constrain manual intervention in hazardous process areas, reinforcing specification trends toward remote-operated actuator systems. Stakeholders must weigh total lifecycle service commitments against upfront hardware costs as procurement models shift toward performance-based contracting.
Market Dynamics
Offshore operators in the US Gulf Coast are accelerating actuator replacement cycles as EPA methane rules tighten fugitive emission standards for subsea valve automation, compressing capital planning horizons from seven years to four.
Growth Catalysts
- NSPS OOOOa mandates:The EPA's leak detection and repair protocols eliminate manual venting events, forcing upstream operators to specify automated actuation on all new wellhead installations.
- Subsea tieback projects:Deepwater developments in the Gulf of Mexico require fail-safe electrohydraulic actuators rated for 3,000-meter depths and 15,000 psi operating pressures.
- Petrochemical corridor expansion:Louisiana and Texas ethane crackers are commissioning valve automation packages at record rates to handle light feedstock switching.
Market Restraints
- Specialized alloy costs:Inconel 718 and super duplex stainless steel price volatility directly impacts subsea actuator bill-of-materials, with nickel fluctuations adding 12-18% cost uncertainty to quotes.
- Foundry concentration:Critical casting capacity for high-pressure housings concentrates in Germany and Japan, creating 26-week lead time exposure for non-standard torque configurations.
- API 6D certification friction:Fire-safe testing protocols add 14-18 months to product qualification timelines, freezing out smaller entrants from major project specifications.
Strategic Opportunities
- CCUS injection wells:Carbon capture projects in Wyoming and North Dakota need high-cycle actuators for CO2 plume management, opening a serviceable base outside traditional hydrocarbon production.
- Hydrogen blending infrastructure:Pipeline operators in the Netherlands and UK are retrofitting natural gas networks with hydrogen-compatible actuation, requiring new sealing material specifications.
- Digital twin convergence:Actuator OEMs bundling physics-based simulation with hardware shipments are capturing ten-year service contracts from integrated majors seeking predictive downtime avoidance.
Industry Challenges
- Subsea technician scarcity:ROV-operable actuator installation and intervention requires certified underwater robotics specialists, with training pipelines failing to match retirement rates in Aberdeen and Houston.
- Legacy SCADA integration:Brownfield facilities running 1990s-era distributed control systems face protocol translation costs that erase 30-40% of smart actuator upgrade value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Actuators Market |
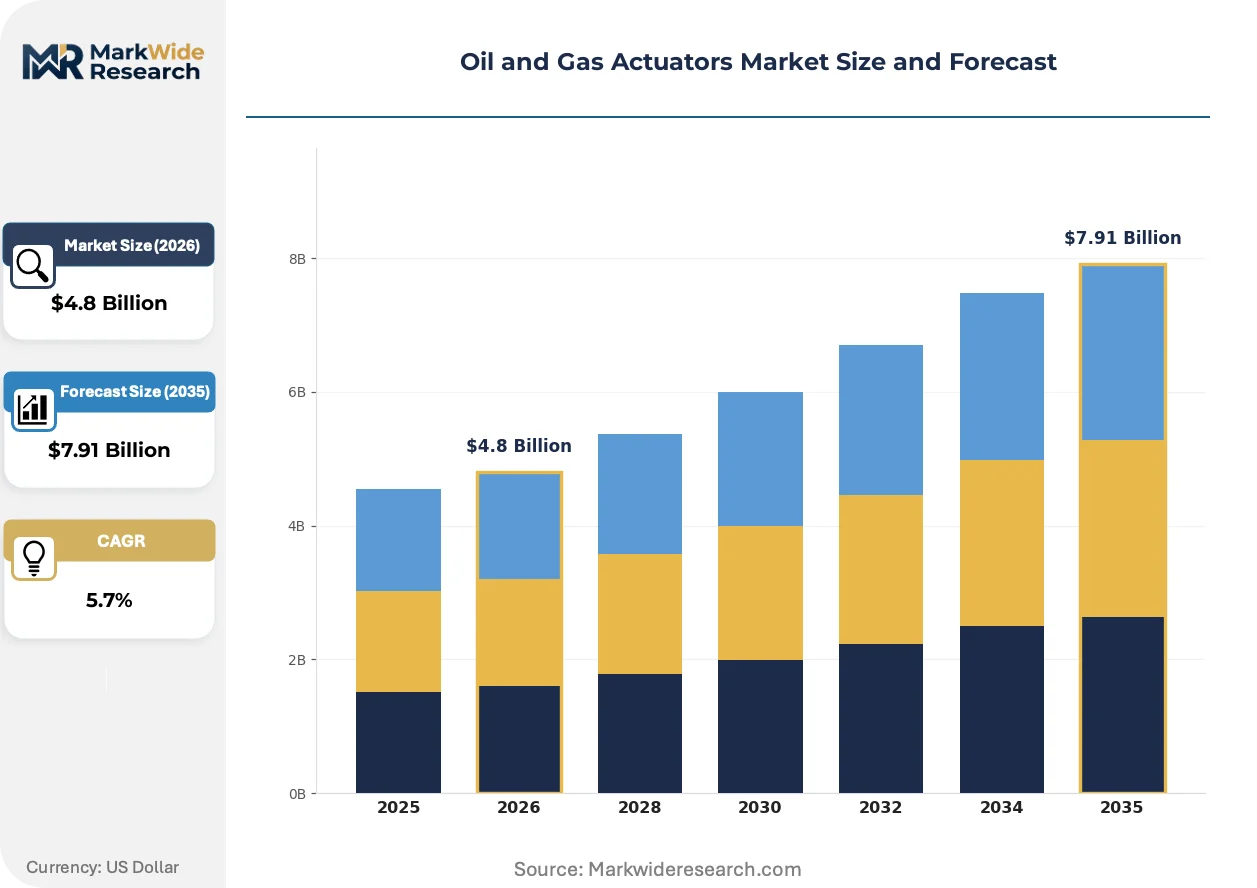
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Manual Actuators Application: Drilling, Pipeline, Refining, Production End User: Exploration Companies, Production Firms, Service Providers, Research Institutions Technology: Smart Actuators, Conventional Actuators, Digital Actuators, Remote-Controlled Actuators |
| Companies Covered | Emerson Electric Co., Rotork, Curtiss-Wright, AUMA Riester GmbH & Co. KG, Flowserve Corporation, ATI, QTRCO, Inc., REXA, Bray International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Actuators Market Evolving Landscape
Valve automation architecture is bifurcating between all-electric precision systems for onshore processing and electrohydraulic hybrids for subsea pressure extremes, with digital overlays becoming standard on both tracks.
Smart actuators with embedded vibration and temperature sensors are integrating edge computing capabilities that process diagnostic data locally before transmitting anomalies to shore-based control centers. Offshore platform operators in the North Sea and Gulf of Mexico are specifying these systems on all new greenfield builds, with retrofit demand following three to four years behind. This integration is compressing the traditional maintenance window from scheduled calendar-based interventions to condition-triggered responses, reducing unplanned shutdown frequency by enabling pre-failure component replacement.
REACH restrictions on perfluorinated sealing compounds are forcing actuator manufacturers to qualify alternative elastomer formulations for high-pressure hydrocarbon service. The industrial consequence is a 24-month recertification backlog at notified bodies as suppliers resubmit fire-safe and fugitive emission test data. Subsea applications face the tightest compliance timeline, with Norwegian operators under Petroleum Safety Authority jurisdiction requiring full material traceability documentation before platform installation permits issue.
Integrated majors are unbundling actuator procurement from valve package supply, establishing direct commercial relationships with automation specialists that bypass traditional valve OEM channels. This disintermediation concentrates in the US Permian and DJ Basins, where independent producers have long purchased complete valve-actuator assemblies from distributors. The new pattern fragments order volumes across more supplier relationships but reduces markup stacking, with buyers capturing 8-12% landed cost reduction on high-torque electric units through direct specification.
Oil and Gas Actuators Market Segmentation
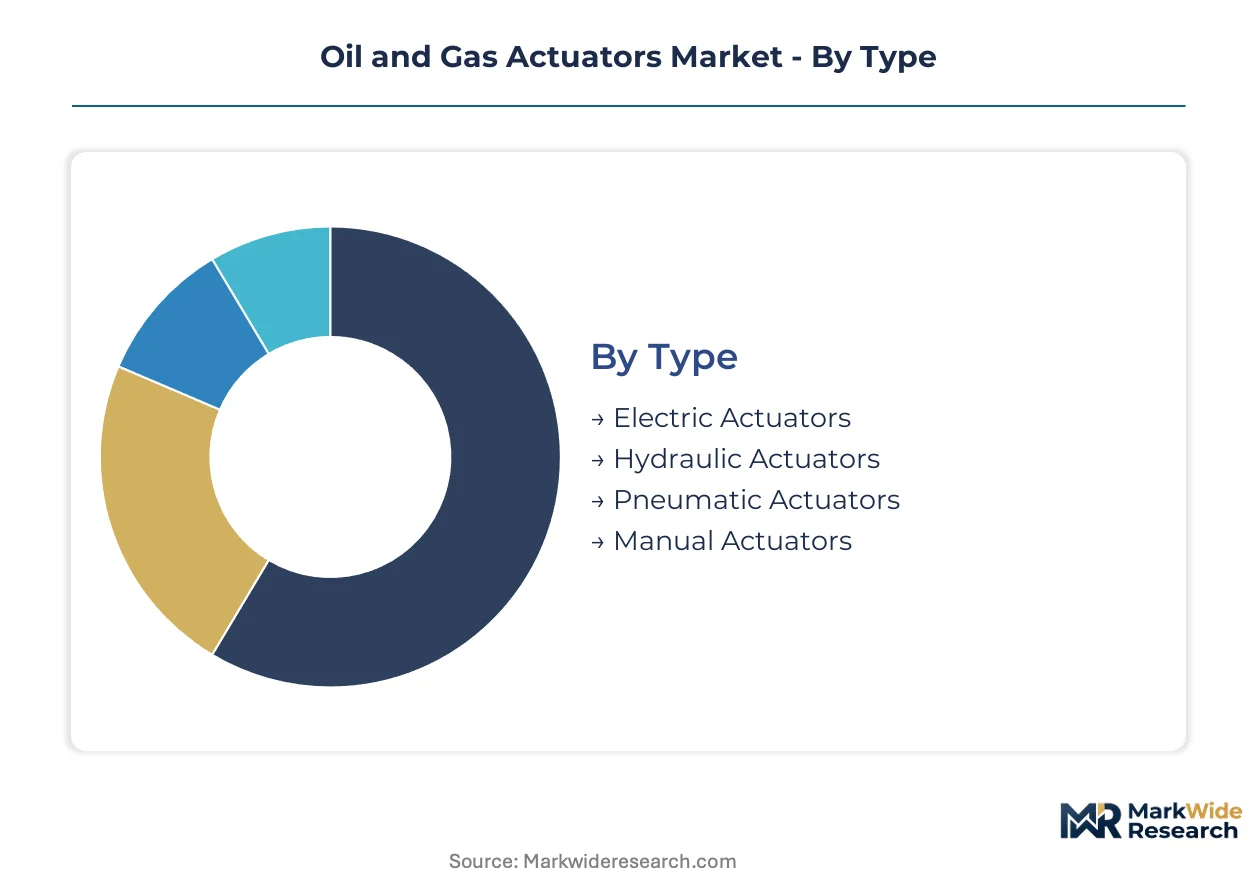
Actuator procurement in hydrocarbon operations hinges on matching torque output, power source availability, and automation depth to specific wellhead or processing conditions. Segmentation reveals how buyers trade off precision control against fail-safe reliability across divergent pressure and environmental regimes.
Type:
Power source accessibility and maintenance burden dominate actuator selection, with electric systems preferred where grid infrastructure exists and hydraulic units specified for subsea or remote locations lacking reliable electricity.
- Electric Actuators:These systems convert electrical energy into rotational or linear motion through servo motors or induction drives, delivering precise positioning with minimal periodic maintenance. Onshore processing facilities in the US Gulf Coast petrochemical corridor specify electric units for valve automation packages, driven by EPA methane rules that penalize pneumatic venting events and favor sealed electric alternatives.
- Hydraulic Actuators:Pressurized fluid systems generate substantial torque outputs through piston or vane mechanisms, operating reliably in explosive atmospheres without electrical ignition risks. Deepwater developments in the Gulf of Mexico require fail-safe electrohydraulic actuators rated for 3,000-meter depths and 15,000 psi pressures, with subsea tieback projects compressing replacement cycles from seven years to four under tightening fugitive emission standards.
- Pneumatic Actuators:Compressed gas-driven units offer rapid stroking speeds and intrinsic safety in hazardous zones, though venting during operation faces escalating regulatory pressure.
- Manual Actuators:Handwheel or lever-operated devices persist in low-cycle isolation valve applications where automation economics fail to justify capital expenditure.
Electric actuators lead on scale across onshore installations; hydraulic actuators lead on momentum in subsea capital deployment.
Application:
Operating pressure differentials and process criticality determine automation investment levels, with continuous flow applications commanding higher specification grades than intermittent isolation duties.
- Production:Wellhead choke and master valve automation enables remote shutdown capabilities and flow optimization across artificial lift and natural flow installations. Permian Basin operators are expanding electric actuator procurement for wellhead installations to comply with EPA NSPS OOOOa leak detection mandates that eliminate manual venting events.
- Refining:Catalytic cracking and hydroprocessing units require high-cycle actuators with fire-safe certification and tight shutoff performance to manage hazardous intermediate streams. Louisiana and Texas ethane crackers are commissioning valve automation packages at record rates to handle light feedstock switching, with actuators specified for frequent cycling between propane and ethane service.
- Pipeline:Long-distance transmission systems utilize gas-over-oil or all-electric actuation for compressor station isolation and block valve automation.
- Drilling:Blowout preventer control systems demand rapid-response hydraulic actuators with redundant accumulator capacity for emergency shear operations.
Production applications command the largest installed base; refining applications are climbing fastest on petrochemical corridor expansion.
End User:
Capital allocation authority and operational risk tolerance segment the buyer landscape, with integrated majors driving standardization and independents prioritizing procurement flexibility.
- Production Firms:Operating companies with retained production assets specify actuators as part of facility automation overhauls, emphasizing lifecycle service commitments over upfront hardware costs.
- Exploration Companies:Wildcat operators and appraisal drillers prioritize portable, rapid-deployment actuation for temporary well test configurations.
- Service Providers:Well construction and intervention contractors procure actuators for rental fleets, demanding ruggedized designs tolerant of field handling and cross-basin redeployment.
- Research Institutions:Universities and national laboratories acquire specialized actuators for flow loop testing and materials qualification under extreme pressure-temperature conditions.
Production firms dominate procurement volume; service providers are expanding fastest on rental fleet digitization.
Technology:
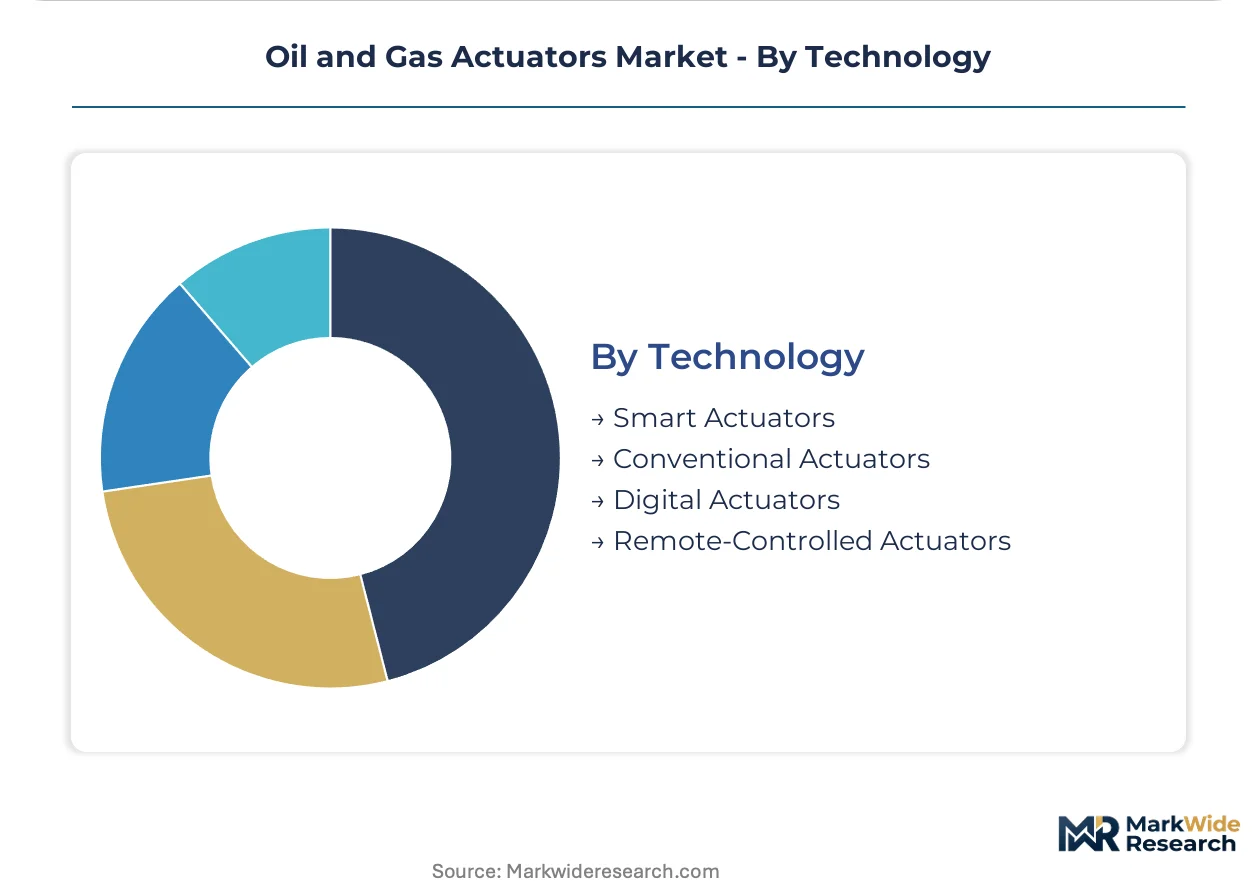
Diagnostic capability and connectivity architecture now differentiate actuator offerings as operators shift from calendar-based maintenance to condition-triggered intervention models.
- Smart Actuators:Embedded vibration, temperature, and torque sensors with edge computing capability process diagnostic data locally before transmitting anomalies to shore-based control centers. Offshore platform operators in the North Sea and Gulf of Mexico specify these systems on all new greenfield builds, with retrofit demand following three to four years behind as brownfield facilities address legacy SCADA integration costs.
- Remote-Controlled Actuators:Radio or satellite-linked units enable intervention in unmanned facilities and geographically dispersed well pads, reducing personnel exposure to hazardous atmospheres.
- Digital Actuators:Positioners with digital communication protocols integrate into distributed control systems, offering precise setpoint tracking and feedback.
- Conventional Actuators:Analog or basic on-off devices without embedded intelligence occupy substantial installed bases across mature basins where capital replacement cycles lag digital upgrade timelines.
Conventional actuators retain the largest installed population; smart actuators are gaining share fastest on predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates subsea actuator demand around the Gulf of Mexico, while Norway drives North Sea electrification standards that reshape specification requirements across the North Atlantic basin.
United States
Deepwater tieback projects in the Gulf of Mexico require fail-safe electrohydraulic actuators rated for 3,000-meter depths. EPA methane performance standards under NSPS OOOOa mandate automated valve actuation on all new wellhead installations. The Louisiana-Texas petrochemical corridor is commissioning valve automation packages at record rates for light feedstock switching.
Norway
Offshore platform operators specify smart actuators with embedded diagnostics on all greenfield builds in the North Sea. The Petroleum Safety Authority requires full material traceability documentation before platform installation permits issue. Stavanger-based engineering clusters are compressing actuator replacement cycles from seven years to four under tightening fugitive emission standards.
United Kingdom
Pipeline operators in the North Sea are retrofitting natural gas networks with hydrogen-compatible actuation systems. REACH restrictions on perfluorinated sealing compounds force manufacturers to qualify alternative elastomer formulations. Aberdeen's subsea service hubs face certified technician scarcity as ROV-operable actuator installation demands outpace training pipeline output.
Brazil
Pre-salt developments offshore require high-pressure actuators for subsea valve control at extreme depths. ANVISA and environmental regulators enforce material certification protocols for hydrocarbon service equipment. Rio de Janeiro's offshore engineering corridor is expanding local content requirements that shape procurement decisions for foreign actuator suppliers.
Saudi Arabia
Gas processing expansion and unconventional field development are driving actuator procurement for wellhead automation. The country's national oil company mandates fire-safe certification aligned with API 6D testing protocols. Eastern Province industrial cities are integrating smart actuator fleets into new processing facilities as part of downstream capacity expansion programs.
Oil and Gas Actuators Market Competitive Landscape
Top-tier vendors anchor premium-tier specification, while mid-scale specialists occupy regional project niches. The vendor base stratifies across three tiers: integrated automation conglomerates with digital ecosystem offerings, dedicated actuator manufacturers with subsea specialization, and regional fabricators serving brownfield replacement demand. Competitive positioning hinges on lifecycle service contracting and certification depth rather than hardware differentiation alone. M&A activity concentrates on digital capability acquisition, while capacity expansion targets subsea foundry partnerships in Germany and Japan.
Within the integrated automation tier, Emerson Electric Co. and Flowserve Corporation exemplify the shift toward performance-based contracting models. Rotork occupies a position among subsea specialists with established service networks in offshore environments. AUMA Riester GmbH & Co. KG represents the European precision manufacturing archetype, while Curtiss-Wright sits within the defense-industrial crossover segment serving extreme environment specifications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rotork |
| Curtiss-Wright |
| AUMA Riester GmbH & Co. KG |
| Flowserve Corporation |
| ATI |
| QTRCO, Inc. |
| REXA |
| Bray International |
| Others |
Value Network & Pricing Analysis
EPA methane performance standards under NSPS OOOOa are compressing procurement timelines for automated valve actuation, forcing foundries in Germany and Japan to prioritize high-pressure housing capacity for subsea tieback projects and elevating alloy-grade premiums across supplier quotes.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for standard electric actuator tiers while premium subsea electrohydraulic units retain markup power. Pricing stratifies across API 6D-certified premium tiers, mid-grade onshore electric systems, and economy manual backups. Cost compression in standard electric units is intensifying because Chinese manufacturers are expanding servo motor foundry output. Independent Permian producers show highest price sensitivity; integrated Gulf of Mexico operators prioritize fail-safe certification over unit cost.
Supply Chain Analysis
Freight costs for Inconel 718 and super duplex stainless steel from German and Japanese specialty mills add nonlinear cost escalation to subsea actuator deliveries. Critical casting capacity concentrates in Germany, Japan, and select Italian precision manufacturers. Bill-of-materials draws from nickel alloy suppliers, high-pressure seal compounders, and ROV-intervention electronics providers. Single-source vulnerability sits with Japanese foundry capacity for 15,000 psi-rated housings. Distribution runs through valve OEM channels, though integrated majors are disintermediating toward direct automation specialist relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oil and Gas Actuators Market functions as a stable compounder anchored by regulatory mandates that eliminate manual venting alternatives and perpetuate replacement demand across mature basins.
For Market Incumbents: Extend service contract duration through predictive maintenance platform bundling, capturing ten-year commitments from integrated majors seeking downtime avoidance. Deepen backward integration into Inconel 718 supply through offtake agreements with German specialty mills, insulating margin pressure from nickel volatility. Counter emerging Chinese electric actuator competition by embedding edge-computing diagnostics that brownfield SCADA integration cannot easily replicate. For New Entrants and Emerging Players: The price-point gap between premium API 6D-certified subsea units and economy onshore electric alternatives creates white-space opportunity for mid-tier smart actuators with condition-monitoring capability. Target the US Permian Basin wellhead automation retrofit wave, where independents seek EPA compliance without integrated-major procurement budgets. Enter through direct distributor relationships that bypass valve OEM markup stacking, capturing landed cost advantage on sealed electric alternatives to pneumatic venting systems. For Investors and Strategic Acquirers: Asymmetric upside sits with digital-twin-enabled actuator OEMs bundling physics-based simulation with hardware shipments. The five-to-ten-year viability window favors vendors with established subsea service networks in Aberdeen and Houston, where technician scarcity creates captive maintenance revenue. Watch for inflection where REACH restrictions on perfluorinated sealing compounds force 24-month recertification backlogs, advantaging suppliers with pre-qualified alternative elastomer formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Foundry Partnership | Secures Inconel 718 capacity for 3,000-meter rated electrohydraulic actuator production. |
| Digital Twin Platform Launch | Captures ten-year service contracts from Gulf of Mexico integrated majors. |
| Alternative Elastomer Qualification | Resolves REACH compliance backlog before Norwegian Petroleum Safety Authority deadlines. |
| Direct Procurement Channel | Bypasses valve OEM markup stacking for 8-12% landed cost reduction in Permian Basin. |
| Predictive Maintenance Subscription | Converts hardware sales to recurring revenue through Plantweb-equivalent ecosystem anchoring. |
Research Methodology
Direct dialogue with upstream automation engineers, subsea project procurement leads, valve OEM product managers, and aftermarket service directors anchored qualitative assessment, cross-referenced against API certification databases, EPA enforcement records, offshore project development trackers, and specialty alloy trade flow data. Bottom-up and top-down triangulation validated volume estimates across electric, hydraulic, pneumatic, and manual actuator categories.
Bottom-up modeling aggregated unit shipments by power source, application pressure class, and technology tier across the projection horizon. Top-down analysis calibrated aggregate market value against petrochemical capital expenditure cycles and subsea tieback project pipelines. CAGRs derived from regression against historical replacement cycle compression and regulatory mandate implementation timelines. Forecast inputs incorporated EPA NSPS OOOOa enforcement trajectory and REACH recertification backlog duration.
Caveats apply where nickel price volatility, German-Japanese foundry capacity constraints, or SCADA protocol translation costs for brownfield smart actuator integration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Latin America Hydraulic Filtration Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market