
 Asia Pacific Industrial Pumps Market | 2026-2036
Asia Pacific Industrial Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Pumps Market Outlook
Smart monitoring integration is tilting procurement criteria toward predictive-capable pump systems across Asia Pacific process industries. Ebara Corporation leverages its Japanese manufacturing base to dominate high-efficiency centrifugal supply for water infrastructure projects. Kirloskar Brothers Limited anchors its position through extensive distribution across India's industrial hinterland, while Grundfos Holding A/S competes on digital service layers that extend equipment lifecycle value.
Industrial pumps are mechanical devices engineered to move fluids through pressure differentials, typically constructed from cast iron, stainless steel, or specialized alloys with operating ranges spanning fractional horsepower to multi-megawatt installations in continuous-duty process environments. Centrifugal pumps occupy the largest installed base across Asia Pacific due to their scalability in water treatment and chemicals handling, while positive displacement systems command premium positioning in oil & gas applications where precise flow control under high-viscosity conditions determines process yield. Magnetic drive technology within the technology dimension is gaining fastest traction as chemical processors eliminate seal failure risks in hazardous fluid transfer operations.
China's MEE enforces escalating efficiency tiers under national GB standards that disqualify legacy pump models from new industrial construction permits. India's BIS certification mandates and Japan's METI Top Runner program create overlapping compliance burdens for multinational suppliers seeking cross-border equipment standardization. Stakeholders must weigh the capital cost of magnetic and advanced electric drive architectures against the operational savings locked in by tightening regulator thresholds across multiple Asia Pacific jurisdictions.
Market Dynamics
China's dual carbon goals and Japan's METI efficiency mandates are compressing the allowable efficiency floor for industrial fluid handling equipment, forcing asset replacement cycles to accelerate across Asia Pacific process industries.
Growth Catalysts
- MEE efficiency tiers:China's escalating GB standards disqualify legacy pump models from new industrial construction permits, compelling capital deployment toward compliant equipment.
- Water treatment procurement:Southeast Asian utilities are scaling energy-efficient pump acquisitions to meet expanding municipal infrastructure requirements.
- Magnetic drive adoption:Chemical processors across India's chemicals corridor are eliminating seal failure risks in hazardous fluid transfer through sealless pump architectures.
Market Restraints
- Specialized alloy input costs:Stainless steel and duplex alloy price volatility compresses margin structures for corrosion-resistant pump manufacturers.
- Regional supply concentration:High-efficiency motor and variable frequency drive sourcing concentrates among East Asian component suppliers, creating single-point vulnerability.
- Cross-border certification friction:India's BIS certification mandates and Japan's JIS standards impose overlapping compliance burdens that fragment product standardization.
Strategic Opportunities
- Vietnam manufacturing expansion:Underpenetrated industrial pump installation rates in Vietnamese chemicals and textiles processing create first-mover positioning potential.
- Predictive maintenance convergence:Vibration sensor integration with cloud analytics platforms enables outcome-based service contracting for continuous-duty installations.
- Australia mining belt digitalization:Remote monitoring adoption in Western Australian iron ore and lithium extraction operations opens premium pricing for connected pump systems.
Industry Challenges
- Magnetic drive engineering scarcity:Specialized magnet circuit design and containment shell metallurgy expertise concentrates among limited engineering talent pools.
- Legacy system integration complexity:Retrofitting smart monitoring capabilities onto existing pump installations requires custom protocol bridging and downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Pumps Market |
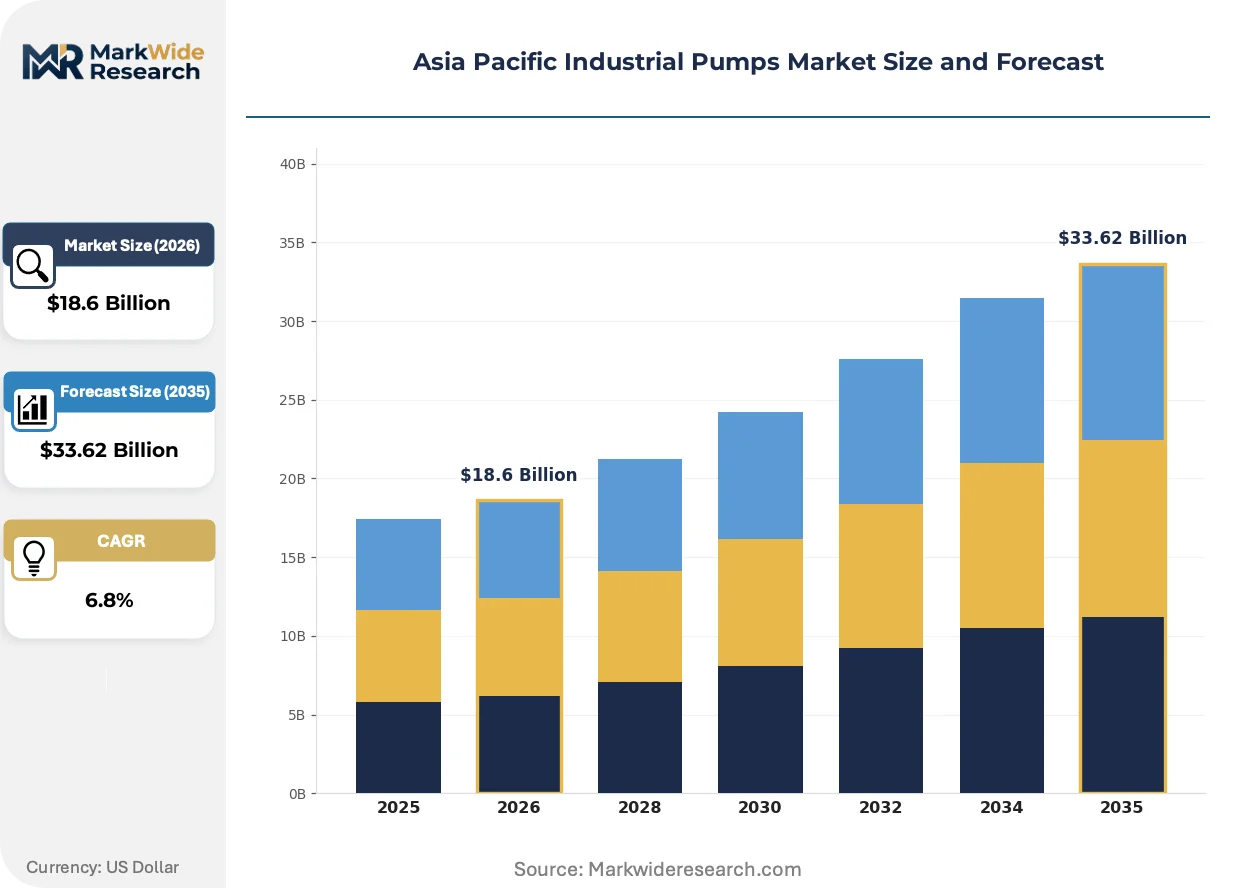
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Diaphragm, Gear End User: Manufacturing, Oil & Gas, Water Treatment, Chemicals Technology: Electric, Hydraulic, Pneumatic, Magnetic Application: Fluid Transport, Process Control, Wastewater Management, Cooling |
| Companies Covered | Ebara Corporation, KSB Group, Grundfos Holding A/S, Wilo SE, Weir Group PLC, Flowserve Corporation, Kirloskar Brothers Limited, Torishima Pump Manufacturing Co., Ltd., Sulzer Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Pumps Market Strategic Shifts
Digital twin architecture is compressing equipment commissioning timelines and enabling remote performance optimization across dispersed Asia Pacific industrial assets.
Magnetic drive pump technology is virtualizing seal maintenance requirements and eliminating fugitive emission pathways in chemical processing environments. Japanese and South Korean petrochemical operators are adopting these systems at accelerating rates for high-temperature organic solvent transfer. The technology is virtualizing traditional pump reliability engineering by shifting failure modes from mechanical seals to solid-state magnetic couplings.
China's MEE enforcement of GB 19762 efficiency standards for centrifugal pumps is mandating minimum efficiency index thresholds that render pre-2020 equipment designs non-compliant. Industrial construction permits now require pump specifications meeting Tier 2 or Tier 3 efficiency classifications. Chemical and power generation facilities in Jiangsu and Shandong provinces are responding with accelerated procurement of premium efficiency motor-pump packages.
Asset-as-a-service contracting is displacing traditional capital purchase models for large-scale water infrastructure projects. Australian municipal utilities and Indonesian palm oil processing complexes are piloting performance-guaranteed pump system leases with bundled maintenance obligations. This shift concentrates most visibly in Queensland's regional water authorities, where budget constraints favor operational expenditure structures over upfront capital deployment.
Asia Pacific Industrial Pumps Market Segmentation
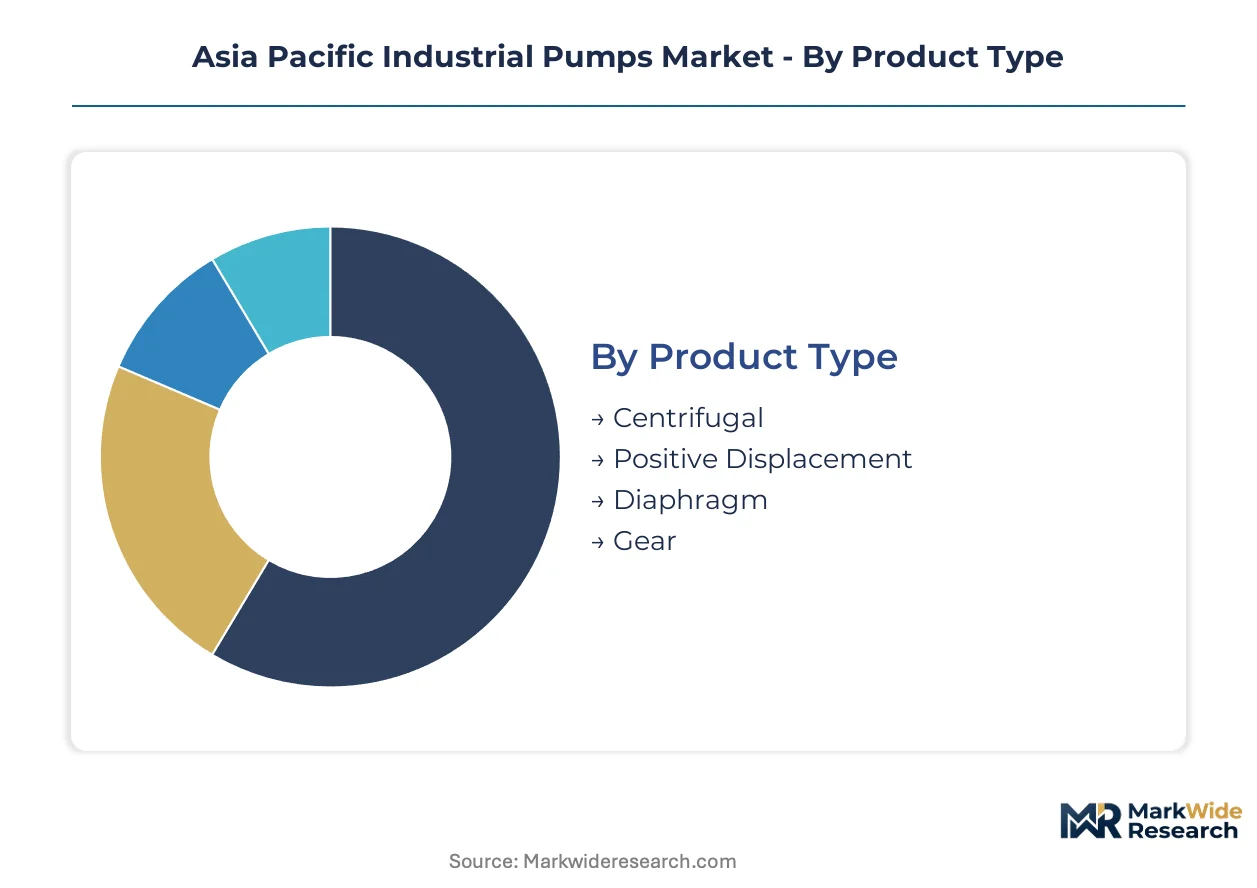
Industrial pump procurement across Asia Pacific follows distinct technical and commercial logics that fragment supplier strategies. End-use requirements in chemical corridors, mining belts, and municipal utilities create non-overlapping specification clusters that resist universal product platforms.
Product Type:
Mature centrifugal architectures dominate installed bases while emerging sealless technologies capture premium replacement cycles.
- Centrifugal:Radial and axial flow designs handle high-volume, low-viscosity fluid movement across water treatment and chemicals processing. China's Jiangsu and Shandong provinces deploy these systems heavily under MEE Tier 2 efficiency mandates that disqualify legacy motor-pump packages.
- Positive Displacement:Reciprocating and rotary mechanisms deliver precise volumetric flow control for high-viscosity hydrocarbon transfer. Australia's Western Australian iron ore operations specify these pumps for slurry density management in remote extraction environments.
- Diaphragm:Sealless reciprocating action isolates pumped media from mechanical components in hazardous chemical dosing applications.
- Gear:Intermeshing rotary elements provide steady, pulse-free flow for lubrication and hydraulic fluid circuits in precision manufacturing.
Centrifugal pumps handle the majority of throughput; magnetic-coupled variants within positive displacement systems are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive process industries from operational-expenditure-driven municipal procurement.
- Manufacturing:Discrete and process manufacturing operations deploy pumps for coolant circulation, parts washing, and hydraulic power transmission. India's industrial hinterland drives demand for standardized, maintainable equipment that minimizes production line downtime.
- Oil & Gas:Upstream extraction and downstream refining require API-standard pumps for high-pressure hydrocarbon handling. Japan's METI efficiency mandates compress allowable power consumption for fluid handling in petrochemical complexes.
- Water Treatment:Municipal utilities and industrial wastewater facilities prioritize energy efficiency in continuous-duty configurations. Southeast Asian procurement scales rapidly as urban infrastructure expands.
- Chemicals:Corrosive and hazardous fluid transfer demands metallurgical specialization in pump construction. India's chemicals corridor specifies duplex stainless and alloy containment shells for process reliability.
Water treatment commands the largest procurement volumes; chemicals processing shows the steepest specification escalation toward sealless architectures.
Technology:
Application context determines power transmission selection, with electric drives dominating stationary installations and pneumatic systems serving explosive atmospheres.
- Electric:AC induction and permanent magnet motors integrate with variable frequency drives for precise speed control. China's GB 19762 efficiency tiers mandate minimum performance indices that reshape motor-pump package procurement.
- Hydraulic:Fluid power transmission delivers high torque density for mobile and heavy-duty stationary equipment in mining and construction applications.
- Pneumatic:Compressed air drive eliminates ignition risks in volatile organic compound handling across solvents and coatings processing.
- Magnetic:Synchronous magnetic couplings transmit torque through containment shells without mechanical seals. Japanese petrochemical operators adopt these systems fastest for high-temperature organic solvent transfer.
Electric systems carry the bulk of installed capacity; magnetic drive technology expands most quickly as chemical processors eliminate fugitive emission pathways.
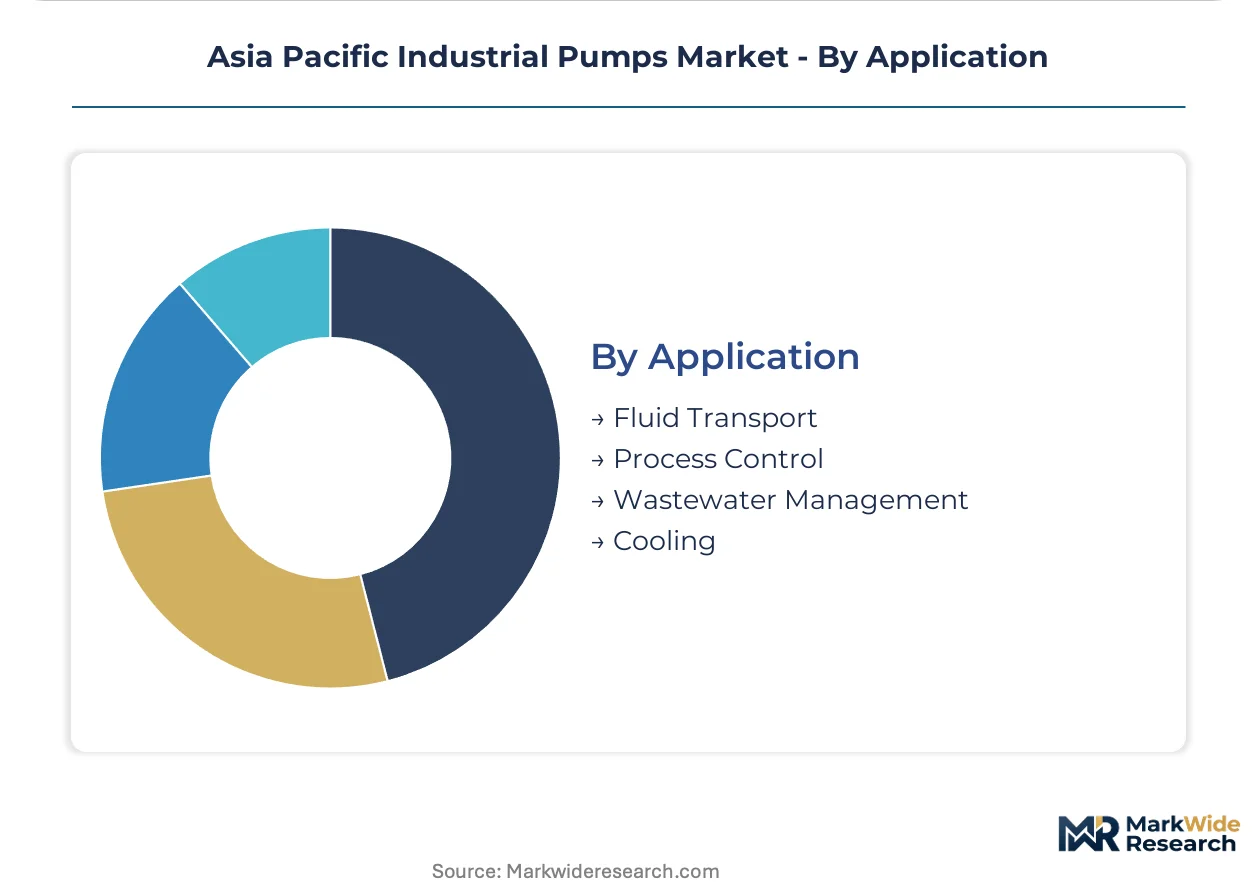
Application:
Volume concentration in bulk fluid movement contrasts with margin concentration in precision process control and critical cooling circuits.
- Fluid Transport:Pipeline and tank-to-tank transfer operations prioritize reliability and efficiency in high-duty-cycle configurations. Australia's mining belt specifies these systems for slurry and process water logistics.
- Process Control:Precise flow metering and pressure maintenance determine yield in batch and continuous chemical manufacturing. India's specialty chemicals sector demands tight tolerances for reactor feed control.
- Wastewater Management:Solids handling and corrosive effluent treatment require abrasion-resistant metallurgy and clog-resistant hydraulics.
- Cooling:Thermal management circuits in power generation and data centers depend on uninterrupted circulation for equipment protection.
Fluid transport absorbs the greatest equipment volumes; process control applications command the highest unit margins through specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pump manufacturing concentrates in East Asian industrial clusters while import dependency shapes procurement patterns across Southeast Asian emerging markets. Trade flows reflect divergent domestic production capabilities and regulatory alignment with efficiency standards. Currency volatility and tariff structures further differentiate national market access conditions.
China
Jiangsu and Shandong provinces drive domestic pump demand through chemicals and power generation capacity expansion. MEE enforcement of GB 19762 efficiency tiers disqualifies legacy equipment from new construction permits. Shanghai-based engineering procurement channels increasingly specify Tier 2 motor-pump packages for municipal water infrastructure.
Japan
PETrochemical complexes in Chubu and Kansai regions sustain premium demand for sealless transfer systems. METI Top Runner mandates compress allowable power consumption for fluid handling equipment. Osaka-area process engineering firms specify magnetic drive architectures for high-temperature organic solvent applications.
India
Maharashtra and Gujarat anchor chemicals corridor procurement for corrosion-resistant metallurgy. BIS certification requirements fragment cross-border equipment standardization. Vadodara and Mumbai industrial zones specify duplex stainless containment shells for hazardous fluid reliability.
Australia
Western Australian iron ore and lithium extraction operations drive slurry handling equipment specifications. TGA-equivalent mining safety protocols govern equipment selection for remote extraction environments. Pilbara region logistics operators prioritize connected monitoring systems for dispersed asset management.
Vietnam
Textiles and chemicals processing capacity expansion in Binh Duong and Dong Nai provinces creates first-mover positioning potential. Underpenetrated installation rates contrast with accelerating foreign direct investment flows. Ho Chi Minh City-area procurement channels show emerging specification sophistication for energy-efficient systems.
Asia Pacific Industrial Pumps Market Competitive Environment
On the supply side, the industry is tiered between integrated multinational systems providers and regional specialists serving price-sensitive procurement channels. Japanese and European headquarters anchor premium efficiency positioning while Indian and Southeast Asian fabricators compete on distribution proximity. Strategic archetypes separate digital service layer competitors from metallurgical specialists and volume-scale manufacturers. Consolidation activity concentrates in magnetic drive technology licensing and predictive maintenance platform acquisitions.
Among Japanese-headquartered manufacturers, Ebara Corporation and Torishima Pump Manufacturing Co., Ltd. occupy positions reflecting domestic engineering heritage and water infrastructure specialization. Grundfos Holding A/S represents the digital service archetype through cloud-integrated lifecycle offerings. Kirloskar Brothers Limited anchors Indian market presence through extensive distribution networks across industrial hinterlands. These three exemplify divergent competitive vectors: efficiency certification leadership, predictive capability integration, and geographic density penetration.
| Leading Market Players |
|---|
| Ebara Corporation |
| KSB Group |
| Grundfos Holding A/S |
| Wilo SE |
| Weir Group PLC |
| Flowserve Corporation |
| Kirloskar Brothers Limited |
| Torishima Pump Manufacturing Co., Ltd. |
| Sulzer Ltd. |
| Others |
Value Chain & Pricing Dynamics
East Asian motor and variable frequency drive suppliers anchor the component tier for premium efficiency pump assemblies, concentrating margin capture upstream while downstream OEMs and municipal buyers face compressed negotiation leverage on finished equipment.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Asia Pacific industrial pumps market. Price differentiation separates Tier 3 efficiency-certified packages from legacy motor-pump combinations and basic cast iron configurations. Cost compression in standard-tier equipment is intensifying because Chinese GB 19762 compliance mandates force rapid design turnover. Municipal utilities in Southeast Asia exhibit highest price sensitivity due to budget-constrained procurement protocols, while Japanese petrochemical operators show lowest sensitivity given METI-mandated reliability specifications.
Supply Chain Analysis
Tariff exposure between China and key Southeast Asian assembly markets dominates supply chain risk calculations for multinational pump manufacturers. High-efficiency motor production concentrates in China, Japan, and South Korea; containment shell metallurgy draws from Japanese and German specialty steel suppliers. Single-source vulnerability persists for rare-earth magnetic materials in sealless pump couplings. Distribution runs through regional engineering procurement channels in Shanghai, Mumbai, and Singapore that service project-based industrial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital service layer interoperability is reshaping competitive positioning in the Asia Pacific industrial pumps market, as predictive maintenance platforms create switching costs that traditional equipment vendors struggle to match.
For Market Incumbents: Insulate installed base relationships through captive aftermarket service contracts that bundle vibration monitoring and spare parts logistics. Accelerate backward integration into high-efficiency motor manufacturing to reduce exposure to East Asian component price volatility. Magnetic drive engineering talent scarcity threatens premium product lines; secure specialized magnet circuit design capabilities through targeted technical hiring in Osaka and Seoul industrial corridors. For New Entrants and Emerging Players: Build out Vietnamese chemicals and textiles processing corridors where underpenetrated installation rates coincide with accelerating foreign direct investment in Binh Duong and Dong Nai provinces. Asset-as-a-service contracting models in Australian municipal water infrastructure offer lower customer acquisition costs than traditional capital sales approaches. Partner with regional cloud analytics platforms to deliver predictive capability without proprietary software development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European-headquartered pump manufacturers seeking Asia Pacific geographic expansion through bolt-on acquisitions. Long-term viability hinges on regulatory compliance automation capabilities as MEE, METI, and BIS efficiency mandates tighten in parallel. Watch for magnetic drive technology licensing deals as inflection indicators of consolidation momentum in sealless architecture segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of GB 19762 Tier 2 efficiency motors secures compliance margin in Jiangsu procurement channels. |
| Predictive Maintenance Platform Launch | Cloud-integrated vibration analytics extends lifecycle revenue per unit for continuous-duty water treatment installations. |
| Magnetic Drive Technology Licensing | Sealless pump architectures eliminate fugitive emission pathways in Japanese petrochemical solvent transfer applications. |
| Vietnam Manufacturing Footprint Expansion | Proximity to Binh Duong textiles and Dong Nai chemicals processing reduces logistics cost for specification-intensive orders. |
| Asset-as-a-Service Contracting Model | Performance-guaranteed leases align Queensland municipal budget constraints with operational expenditure structures. |
Study Parameters
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service directors, and municipal water authority technical managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, BIS certification registries, MEE enforcement bulletins, and SEC filings from listed pump manufacturers. Bottom-up equipment shipment tracking and top-down industrial construction permit analysis were triangulated to establish market sizing.
Demand-supply balance modeling anchored the forecast framework across the analysis window. Segmentation dimensions included pump technology type, efficiency certification tier, end-use industry vertical, power transmission architecture, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression rates and greenfield installation trajectories. Key inputs incorporated MEE Tier 2 adoption curves in Chinese chemicals provinces and METI Top Runner compliance deadlines in Japanese petrochemical complexes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native pump service platforms or Chinese state-backed efficiency equipment consortia would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market