
 Digital Pump Market | 2026-2036
Digital Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pump Market Outlook
The EU Ecodesign Directive is rebalancing procurement criteria across European water utilities toward digitally controlled, energy-optimized pump systems. Grundfos Holding A/S leverages its vertical integration in smart motor technology to sustain premium positioning in municipal retrofits. Xylem Inc. anchors its competitive stance through IoT-enabled predictive maintenance platforms for industrial end users. Wilo SE differentiates via compact, high-efficiency digital pumps purpose-built for commercial building automation.
A digital pump integrates variable frequency drives, embedded sensors, and network-connected control logic to modulate flow and pressure against real-time demand curves, typically achieving efficiency gains unattainable with fixed-speed analog counterparts. Centrifugal digital pumps dominate installed base volumes across water supply and chemical processing applications, while positive displacement variants command margin premiums in precision dosing and food-grade hygienic duty. IoT integration and smart control systems represent the fastest-expanding technology layer, though variable frequency drives still constitute the largest revenue pool due to retrofit attachment rates in existing industrial infrastructure.
The US Department of Energy enforces pump efficiency standards under EPCA, while the EU Ecodesign Directive mandates minimum efficiency index thresholds that effectively exclude non-digital, fixed-speed equipment from new installations. China's MIIT issues GB standards for motor-driven pumps that increasingly reference networked monitoring capabilities as a compliance pathway. Stakeholders must weigh regulatory compliance timelines against the capital intensity of full-fleet digital upgrades, particularly in agricultural and residential segments where price sensitivity remains acute.
Market Dynamics
The EU Ecodesign Directive's minimum efficiency index thresholds are systematically excluding fixed-speed analog pumps from new installations, forcing a capital-intensive transition to digitally controlled infrastructure across municipal water systems and industrial processing facilities.
Growth Catalysts
- EU Ecodesign Directive:Mandates for networked monitoring capabilities in motor-driven equipment are compelling utilities to accelerate digital pump procurement timelines.
- Industrial retrofit cycles:Aging fixed-speed pump infrastructure in chemical processing and water treatment plants is reaching end-of-life replacement windows simultaneously.
- Smart city investments:Municipalities in Germany, China, and the United States are bundling digital pumping systems into integrated water management platforms.
Market Restraints
- Copper and rare earth magnet costs:Variable frequency drive manufacturing depends on concentrated supply chains for neodymium and dysprosium, creating input price volatility.
- Technical limitation:Embedded sensor calibration drift in harsh chemical environments requires frequent recertification, elevating total cost of ownership.
- Substitution threat:Pneumatic pumping systems retain cost advantages in explosive atmosphere applications where electrical certification costs are prohibitive.
Strategic Opportunities
- Agricultural irrigation:Subsidized efficiency programs in India and Brazil are opening procurement channels for solar-integrated digital pumps.
- Technology convergence:Edge computing and 5G industrial networks are enabling real-time pump optimization without cloud dependency.
- Regulatory tailwind:China's MIIT GB standards for networked monitoring create compliance-driven demand for retrofit digital control packages.
Industry Challenges
- Skill scarcity:Field technicians capable of commissioning IoT-enabled predictive maintenance platforms are concentrated in urban industrial corridors.
- Legacy integration friction:BACnet and Modbus protocol incompatibilities between existing building automation systems and new digital pump controllers extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pump Market |
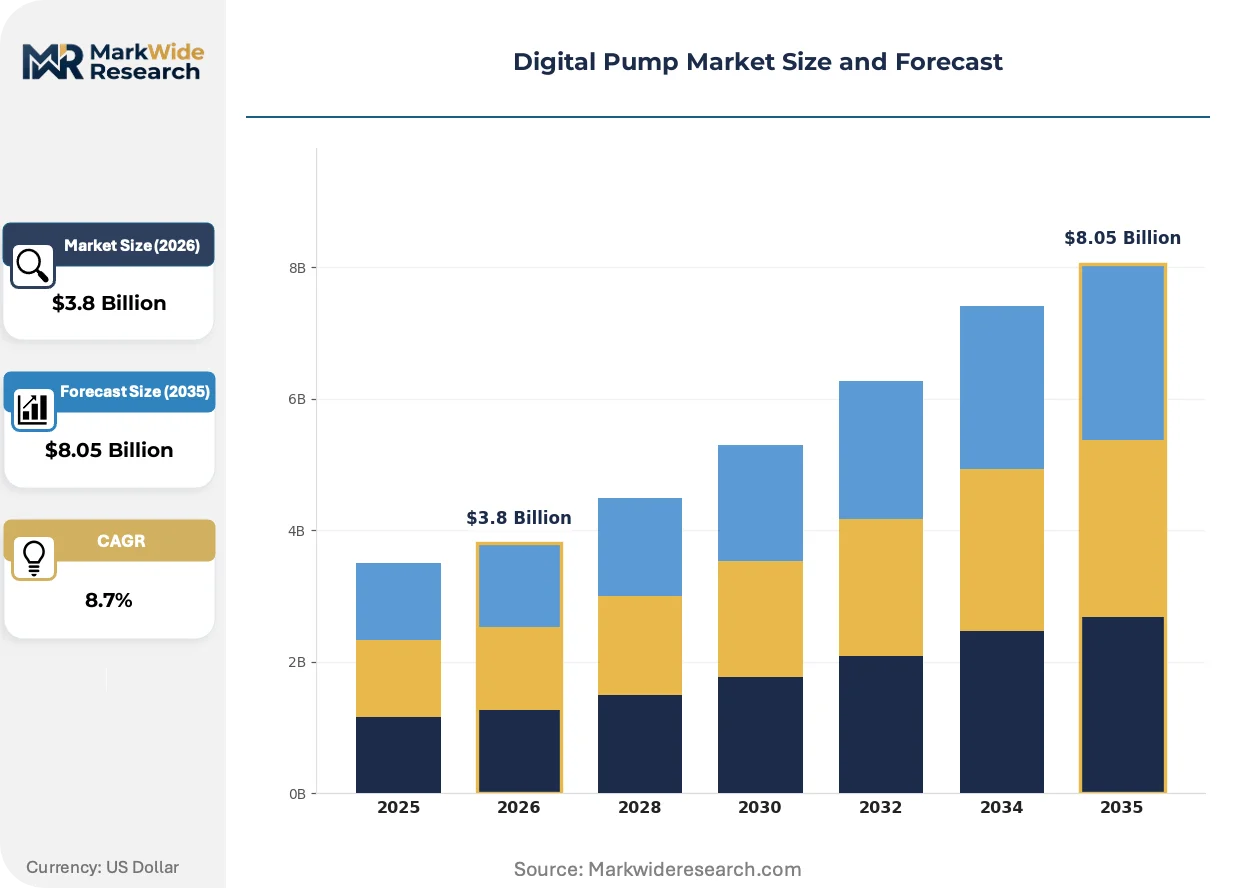
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Diaphragm, Peristaltic Application: Water Supply, Chemical Processing, Food & Beverage, Oil & Gas End User: Industrial, Commercial, Residential, Agricultural Technology: Smart Control Systems, IoT Integration, Variable Frequency Drives, Dosing Technology |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., Sulzer Ltd., Flowserve Corporation, Wilo SE, Kirloskar Brothers Limited, ITT Corporation, KSB Aktiengesellschaft, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pump Market Strategic Shifts
Digital pump architecture is converging with edge computing and machine learning inference, transforming standalone pumping equipment into distributed nodes within autonomous fluid management networks.
Embedded machine learning inference at the pump controller level is automating real-time impeller wear detection and cavitation prediction. Municipal water utilities in Germany are deploying these self-diagnosing units across district pressure zones. The technology is automating maintenance scheduling decisions previously requiring manual vibration analysis and site visits.
The EU Ecodesign Directive's 2023 recast tightens minimum efficiency index thresholds for motors above 0.75 kW, effectively mandating variable frequency drive integration. Industrial end users in chemical processing face compressed compliance timelines for fleet upgrades. Food-grade hygienic duty applications are responding with stainless-steel digital positive displacement pumps certified to EHEDG guidelines.
Service unbundling is separating hardware procurement from predictive maintenance subscriptions. Industrial buyers in the United States are negotiating multi-year performance guarantees rather than capital equipment purchases. Water utilities in California and Texas are piloting availability-based contracts where pump OEMs retain ownership and guarantee uptime metrics.
Digital Pump Market Segmentation
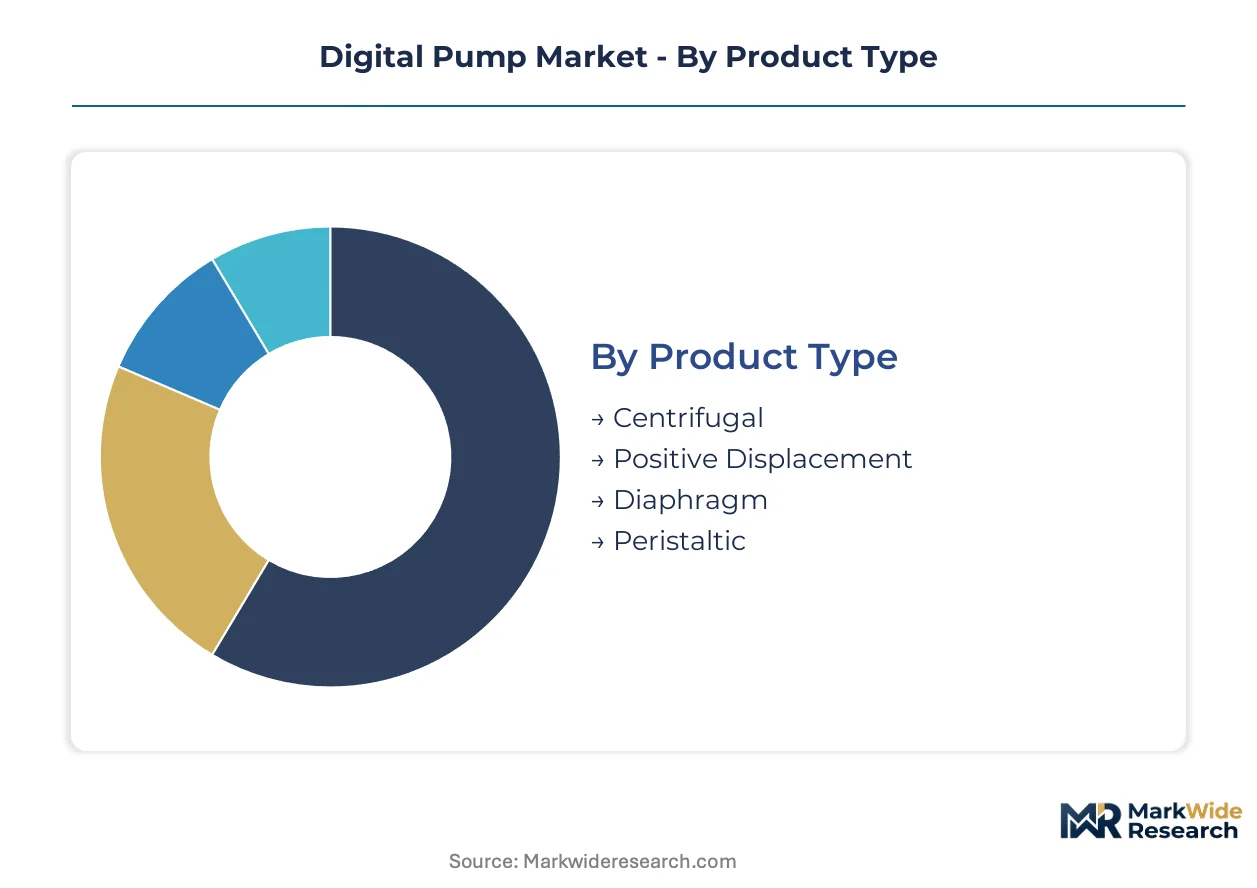
Digital pump segmentation reveals how efficiency mandates and retrofit economics concentrate investment across distinct equipment categories. Procurement patterns diverge sharply between volume-driven municipal water infrastructure and margin-rich precision applications in hygienic processing.
Product Type:
Centrifugal pumps dominate installed volumes while positive displacement variants capture premium pricing in precision duty cycles.
- Centrifugal:Impeller-based hydraulic design handles high-flow, low-viscosity applications across water supply networks and chemical circulation loops. Demand concentrates in Germany and the United States where municipal retrofit programs replace aging fixed-speed infrastructure under tightening Ecodesign thresholds.
- Positive Displacement:Rotary or reciprocating mechanisms deliver precise, pulse-free flow control for viscous fluids and hygienic applications. Food-grade installations in Denmark and Switzerland drive specification of EHEDG-certified stainless-steel variants with embedded torque feedback.
- Diaphragm:Sealed pumping chamber isolates fluid from mechanical components, enabling abrasive slurry handling and zero-leakage chemical transfer.
- Peristaltic:Hose compression mechanism eliminates contamination risk in biopharmaceutical dosing and analytical instrumentation feed systems.
Today's leader: Centrifugal. Tomorrow's challenger: Positive Displacement.
Application:
Water supply anchors replacement demand while chemical processing drives technology specification intensity.
- Water Supply:Municipal distribution networks and wastewater treatment plants require variable-speed pressure management across fluctuating demand curves. Utilities in California and Texas pilot availability-based contracting models where OEMs guarantee uptime metrics rather than sell capital equipment.
- Chemical Processing:Corrosive fluid handling and precise batch dosing demand explosion-proof enclosures and real-time viscosity compensation. Refineries along the US Gulf Coast specify NEMA 7/9 enclosures with edge-computing inference for cavitation prediction.
- Food & Beverage:Hygienic design standards mandate 3A-certified surfaces and clean-in-place compatibility for dairy and brewery applications.
- Oil & Gas:Subsurface artificial lift and pipeline boosting operations prioritize mean-time-between-failure over capital cost in remote extraction environments.
Water supply commands current procurement volumes. Chemical processing sets the technology frontier.
End User:
Industrial buyers dominate technology adoption while agricultural segments lag on connectivity investment.
- Industrial:Continuous-process manufacturing and bulk material handling operations mandate predictive maintenance integration to avoid unplanned shutdown costs. Chemical plants in the Netherlands and Belgium deploy self-diagnosing pump controllers with automated impeller wear detection.
- Commercial:Building automation systems in high-rise developments and district heating networks prioritize compact footprints and BACnet protocol compatibility.
- Residential:Price sensitivity limits digital feature penetration to premium HVAC and rainwater harvesting installations in affluent urban districts.
- Agricultural:Solar-integrated digital pumps gain traction in subsidized efficiency programs across India and Brazil, though field connectivity remains sparse.
Industrial end users set the specification standard. Agricultural channels represent the connectivity expansion opportunity.
Technology:
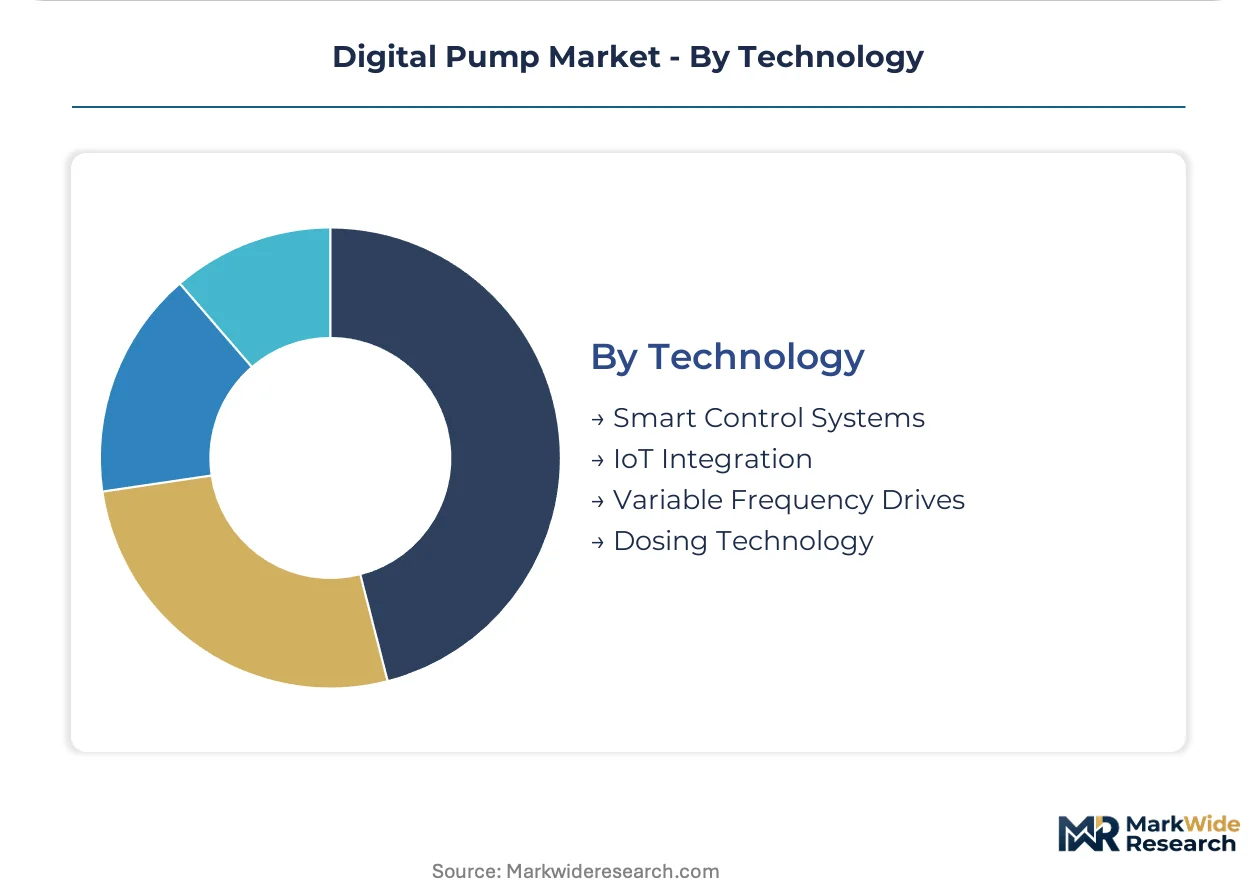
Variable frequency drives constitute the largest revenue pool while IoT layers expand fastest on retrofit attachment.
- Variable Frequency Drives:Motor speed modulation enables part-load efficiency gains unattainable with throttling valves or bypass loops. China's MIIT GB standards for networked monitoring increasingly reference VFD integration as a compliance pathway for motor-driven pump systems.
- IoT Integration:Cloud-connected sensors transmit vibration, temperature, and flow data to centralized asset management platforms. Germany's municipal utilities deploy these capabilities across district pressure zones to automate maintenance scheduling.
- Smart Control Systems:Embedded edge computing enables real-time optimization without cloud dependency, critical for facilities with intermittent connectivity.
- Dosing Technology:Precision stroke control and flow feedback loops enable ppm-accurate chemical injection in water treatment and pharmaceutical manufacturing.
Variable frequency drives anchor near-term revenue. IoT integration layers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Denmark, Germany, and Switzerland anchor European digital pump development, while Chinese manufacturing clusters and US municipal procurement offices concentrate deployment capacity.
United States
Municipal water utilities in California and Texas are piloting availability-based contracting models where OEMs guarantee uptime metrics. The Department of Energy enforces pump efficiency standards under EPCA that mandate variable frequency drive integration for new installations. Refineries along the US Gulf Coast specify explosion-proof digital pumps with edge-computing inference for cavitation prediction.
Germany
Industrial end users in chemical processing and water treatment are deploying self-diagnosing pump controllers with automated impeller wear detection. The EU Ecodesign Directive's 2023 recast tightens minimum efficiency index thresholds for motors above 0.75 kW. Municipal utilities across North Rhine-Westphalia and Bavaria are retrofitting district pressure zones with IoT-enabled predictive maintenance platforms.
China
Smart city investments in the Yangtze River Delta and Pearl River Delta are bundling digital pumping systems into integrated water management platforms. MIIT issues GB standards for motor-driven pumps that reference networked monitoring capabilities as a compliance pathway. Manufacturing clusters in Jiangsu and Zhejiang provinces are scaling variable frequency drive production for domestic retrofit programs.
India
Subsidized efficiency programs in Maharashtra and Gujarat are opening procurement channels for solar-integrated digital pumps in agricultural irrigation. The Bureau of Energy Efficiency administers the Perform, Achieve and Trade scheme that mandates energy consumption reductions in designated industrial facilities. Field connectivity remains sparse in rural Andhra Pradesh and Tamil Nadu despite hardware deployment.
Denmark
Food-grade hygienic duty applications in the Copenhagen corridor are specifying EHEDG-certified stainless-steel digital positive displacement pumps with embedded torque feedback. Danish environmental regulators enforce strict nitrogen discharge limits that drive precision dosing pump adoption in wastewater treatment. Engineering talent concentrated in the Øresund Region supports advanced control algorithm development for global export.
Digital Pump Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the digital pump value chain, creating a tiered structure where integrated motor manufacturers face pressure from modular control system specialists. The vendor base clusters around three strategic archetypes: full-stack pump OEMs with captive drive production, automation conglomerates with fluid handling divisions, and precision component specialists focused on sensor and controller modules. Consolidation pressure is intensifying as utilities favor single-source accountability for performance guarantees. Dominant competitive moves include backward integration into rare earth magnet supply chains and technology licensing partnerships for edge-computing inference engines.
Among European-headquartered full-stack producers, Grundfos Holding A/S and Wilo SE exemplify the integrated archetype with in-house smart motor capabilities. Xylem Inc. represents the automation-centric positioning of US-based fluid technology platforms. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| Sulzer Ltd. |
| Flowserve Corporation |
| Wilo SE |
| Kirloskar Brothers Limited |
| ITT Corporation |
| KSB Aktiengesellschaft |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
Performance-tier divergence between EHEDG-certified hygienic pumps and commodity water-supply units manifests in both margin structures and sourcing configurations, with premium stainless-steel variants drawing from Danish engineering clusters while standard centrifugal equipment feeds from Chinese VFD manufacturing basins.
Pricing Analysis
Bundled hardware-maintenance contracts are displacing transactional equipment sales among industrial buyers, particularly in US municipal utilities piloting availability-based uptime guarantees. Price differentiation rests on certification tier and after-sales service depth, with EHEDG and 3A hygienic certifications commanding substantial premiums over standard IP55 enclosures. Cost compression in the economy tier is intensifying because Chinese VFD manufacturers are scaling output for domestic retrofit programs. Agricultural irrigation remains the most price-sensitive segment, while chemical processing facilities prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility procurement in Germany and the United States, while distributor networks serve fragmented commercial building automation demand across India and Brazil. Manufacturing concentrates in China, Germany, and Denmark, with Jiangsu and Zhejiang provinces scaling variable frequency drive production for export markets. Neodymium and dysprosium rare earth magnets, plus copper windings, constitute critical input dependencies. Single-source vulnerability in rare earth processing creates exposure to export restriction risks. Distribution runs through authorized service partners for commissioning-intensive IoT-enabled installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital pump market functions as a stable compounder, with regulatory efficiency mandates across the EU, United States, and China creating predictable replacement cycles that underpin steady procurement growth.
For Market Incumbents: Anchor defensive positioning through backward integration into rare earth magnet supply chains and captive production of edge-computing controller modules. Consolidate channel control by acquiring regional service partners capable of commissioning IoT-enabled predictive maintenance platforms, countering the threat from modular control system specialists unbundling hardware from software subscriptions. For New Entrants and Emerging Players: The premium-to-economy price-point gap in agricultural irrigation equipment offers accessible entry terrain, particularly in subsidized efficiency programs across Maharashtra and Gujarat where field connectivity remains sparse. Target solar-integrated digital pump configurations for smallholder farms, leveraging government procurement channels as the primary go-to-market angle rather than direct OEM competition. For Investors and Strategic Acquirers: Consolidation pressure builds where utilities demand single-source accountability for performance guarantees, compressing the viable vendor base to full-stack producers with captive drive technology. The market supports long-term viability for integrated manufacturers controlling both hydraulic design and smart motor production. Monitor GB standard enforcement by China's MIIT as the signal indicating accelerated retrofit demand across industrial processing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures captive neodymium access for VFD production against Chinese export volatility. |
| Edge-Computing Controller Development | Enables real-time cavitation prediction without cloud dependency for remote extraction sites. |
| Availability-Based Contracting Model | Transforms capital equipment sales into recurring revenue streams with utility buyers. |
| EHEDG Certification Investment | Unlocks premium positioning in food-grade hygienic applications across Denmark and Switzerland. |
| Agricultural Irrigation Channel Partnership | Captures subsidized procurement flows in India and Brazil through government program alignment. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Interviews with plant engineers, municipal utility procurement directors, OEM aftermarket service heads, and building automation system integrators were triangulated against customs data, SEC 10-K disclosures, and EU Ecodesign Directive implementation reports. Bottom-up equipment shipment analysis and top-down energy efficiency mandate impact modeling were cross-referenced for convergence.
Rate-of-change decomposition separates retrofit replacement cycles from new installation demand across the projection horizon. Segmentation dimensions include pump architecture, application duty cycle, end-user industry, and technology layer adoption trajectory. CAGRs were derived from regression analysis of historical efficiency standard implementation patterns and correlated industrial capital expenditure cycles. Forecast inputs incorporate MIIT GB standard compliance timelines and EU Ecodesign Directive threshold adjustments.
Caveats apply where rare earth export restrictions or copper price volatility could materially shift the outlook for variable frequency drive manufacturing economics. Forecasts reflect assumptions regarding regulatory enforcement consistency and utility capital budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Fluid Transfer System Market