
 Lubrication Pump Systems Market | 2026-2036
Lubrication Pump Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lubrication Pump Systems Market Insights
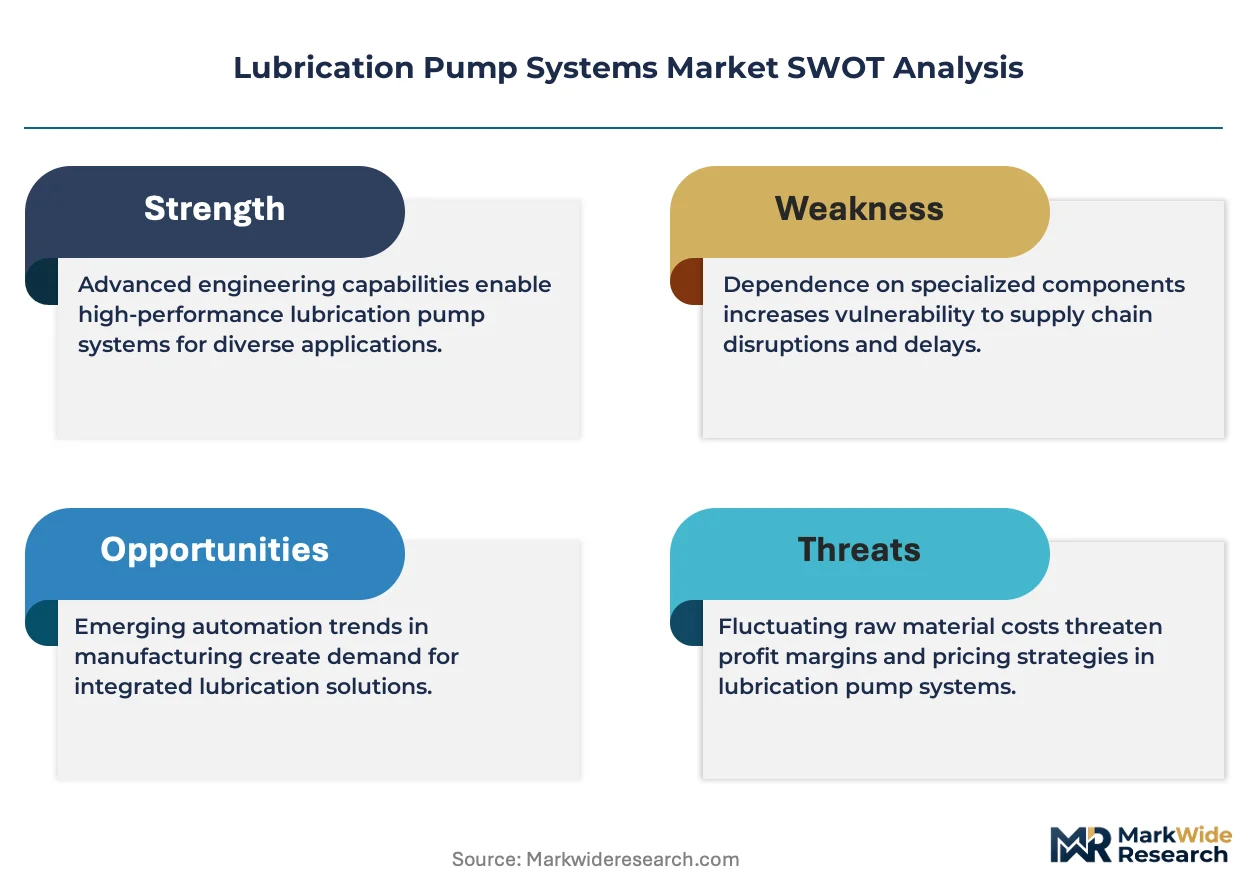
REACH compliance is shifting the cost-of-entry calculus for European suppliers of lubrication pump systems, forcing reformulation of seal materials and pump housings to eliminate restricted substances. SKF leverages its integrated bearing-lubrication platform to anchor premium positioning across Nordic industrial clusters. Graco Inc sustains manufacturing scale advantages in North American electric pump assemblies through captive supply of precision-machined components. Bijur Delimon International specializes in centralized lubrication architectures for heavy-duty mining and construction applications.
Lubrication pump systems are electromechanical or fluid-powered devices engineered to deliver controlled volumes of oil or grease to friction points at pressures typically ranging from 70 to 5,000 psi, with flow precision maintained through positive displacement, gear, or piston mechanisms. These systems reduce mechanical wear, extend component life, and enable continuous operation in automated production environments. Electric pumps lead installed base volumes across manufacturing plants and power generation units due to compatibility with Industry 4.0 control architectures, while pneumatic pumps capture share in hazardous-zone oil and gas facilities where spark-free operation is mandated. Positive displacement technology dominates precision-critical aerospace and marine engine applications where volumetric consistency directly affects safety margins.
EPA emissions standards and OSHA machinery guarding requirements shape product design and market access for equipment deployed in U.S. transportation services and manufacturing plants. EMA medical device lubrication protocols and EU machinery safety directives influence specification standards for pumps serving European aerospace and metalworking sectors. Stakeholders must monitor evolving carbon-border adjustment mechanisms and material traceability mandates to determine where backward integration into seal compound production preserves margin against compliance cost inflation.
Market Dynamics
Automated lubrication retrofits are compressing replacement cycles across metalworking and fleet operations, forcing suppliers to bundle predictive monitoring with hardware or face margin erosion from standalone pump commoditization.
Growth Catalysts
- EPA emissions enforcement:Fleet operators in the United States are retrofitting precision oil-delivery systems to reduce friction losses and meet stricter tailpipe standards, pulling demand for smart pump-motor combinations.
- China's equipment modernization:State-backed programs across the eastern manufacturing corridor favor integrated pump-monitoring packages, accelerating replacement of manual lubrication stations in automotive stamping plants.
- REACH compliance reformulation:European suppliers are redesigning seal compounds and pump housings to eliminate restricted substances, creating upgrade demand as older systems face obsolescence.
Market Restraints
- Specialized alloy supply concentration:Precision-machined pump housings depend on captive supply relationships concentrated in German and Japanese tooling networks, exposing assemblers to input bottlenecks.
- Pneumatic pump substitution ceiling:Hazardous-zone oil and gas facilities mandate spark-free operation, but pneumatic systems face displacement limits from advancing intrinsically safe electric alternatives.
- REACH certification timelines:ECHA substance restrictions extend product validation cycles by 12-18 months, freezing new entrants from European aerospace and medical device channels.
Strategic Opportunities
- India's PLI-linked manufacturing:Production-linked incentive schemes for heavy machinery are opening specification windows for centralized lubrication architectures in domestic mining equipment.
- IoT-predictive maintenance convergence:Vibration sensors married to cloud analytics are enabling outcome-based service models that lock in long-term pump consumable contracts.
- Japan's hydrogen infrastructure buildout:METI funding for hydrogen fueling stations creates demand for specialized high-pressure grease systems in compressor and valve applications.
Industry Challenges
- Mechatronics skill scarcity:Integrated pump-monitoring packages require field technicians fluent in both hydraulic systems and Industry 4.0 diagnostics, a combination scarce in Midwestern US maintenance pools.
- Legacy PLC integration friction:Retrofit projects in German automotive plants stall where 1990s Siemens control architectures resist API connectivity with modern lubrication controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubrication Pump Systems Market |
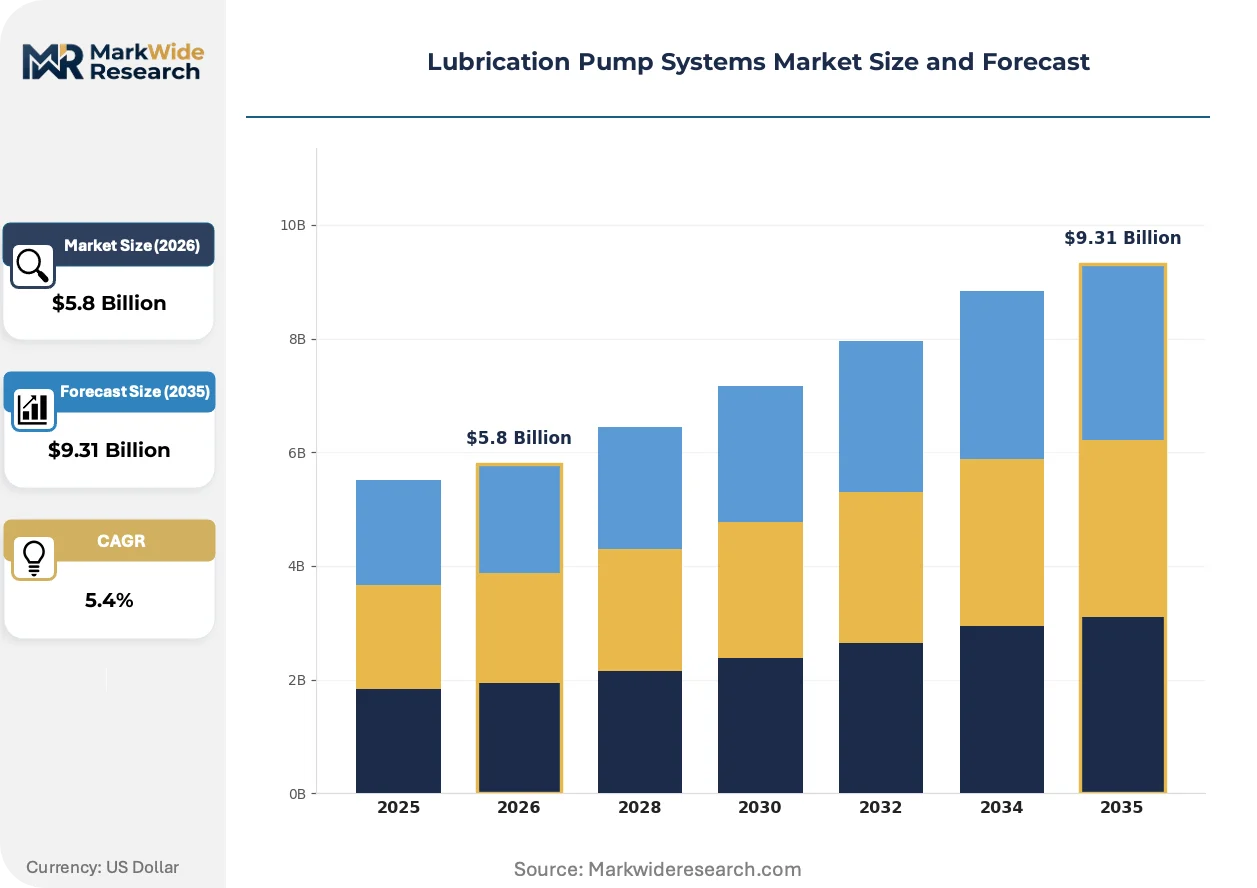
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pumps, Electric Pumps, Pneumatic Pumps, Hydraulic Pumps, Grease Pumps Technology: Positive Displacement, Gear Type, Piston Type, Diaphragm Type, Vane Type Application: Metalworking Machinery, Construction Equipment, Mining Operations, Textile Machines, Marine Engines End User Industry: Manufacturing Plants, Oil & Gas Facilities, Power Generation Units, Transportation Services, Aerospace |
| Companies Covered | SKF, Graco Inc, Groeneveld Group, Beka-Lube Products Inc, Cenlub Systems, Bijur Delimon International, DropsA, Lincoln Industrial, Trico Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubrication Pump Systems Market Trends and Innovations
Digital lubrication architectures are displacing timer-based mechanical distributors, compressing the value chain toward software-defined flow control and remote parameter adjustment.
Condition-based lubrication using ultrasonic film-thickness sensors is rewriting maintenance economics in wind turbine gearboxes. Siemens Gamesa and Vestas are piloting these systems across North Sea installations, enabling variable dosing that extends bearing life while cutting grease consumption by one-third. The technology is compressing scheduled maintenance intervals into predictive interventions.
REACH substance restrictions are forcing reformulation of nitrile and fluorocarbon seal compounds across European supply chains. ECHA's 2024 candidate list expansion is disqualifying legacy materials from medical device and food-contact pump applications, pushing compounders toward bio-based perfluoropolyether alternatives. German metalworking OEMs are absorbing 15-20% material cost premiums to retain CE marking access.
Buyer consolidation among North American fleet operators is compressing supplier rosters toward integrated platform vendors. Large logistics groups are unbundling after-sales service from initial pump procurement, instead contracting direct with telemetry-enabled lubrication-as-a-service providers. The shift is most visible in long-haul trucking networks across the I-80 corridor, where uptime guarantees now override capital equipment ownership.
Lubrication Pump Systems Market Segmentation
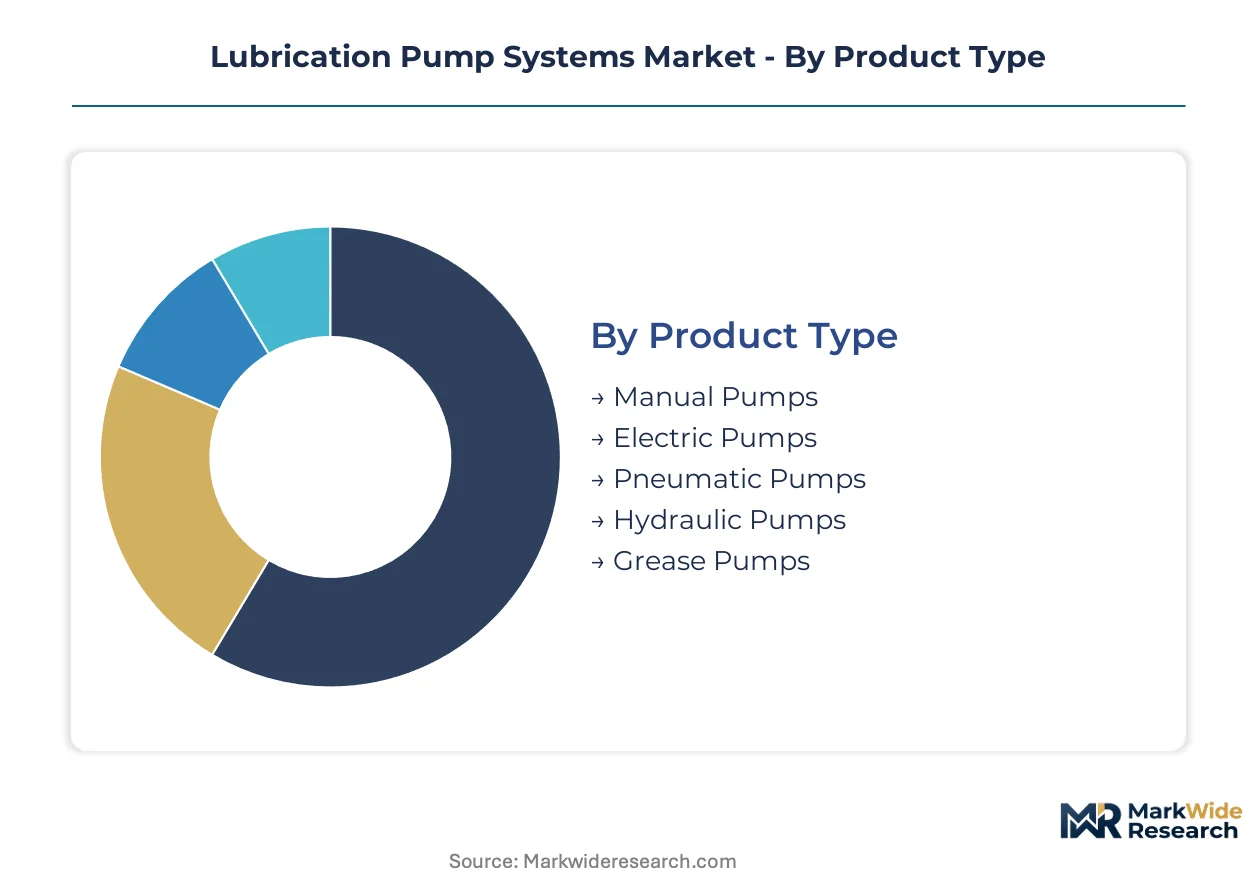
Segmentation in lubrication pump systems reveals divergent replacement dynamics across power sources, precision mechanisms, and duty-cycle environments. Upgrade cycles accelerate where Industry 4.0 retrofit incentives intersect with regulatory compliance deadlines.
Product Type:
Replacement-cycle velocity varies sharply by power source, with electrification mandates and hazardous-zone codes forcing divergent obsolescence timelines across installed bases.
- Electric Pumps:Brushless DC and AC induction motor architectures dominate new installations across automated production lines. Demand concentrates in Germany's automotive stamping plants where predictive maintenance retrofits displace timer-based mechanical systems.
- Pneumatic Pumps:Compressed-air-driven displacement units deliver spark-free operation in explosive atmospheres. Procurement clusters in Texas and Alberta oil-sands processing facilities where OSHA and CSA hazardous-location codes mandate pneumatic over electric alternatives.
- Manual Pumps:Hand-lever and foot-operated units persist in low-volume maintenance bays and mobile service applications.
- Hydraulic Pumps:Fluid-power intensifiers serve high-pressure centralized systems in heavy forging and extrusion equipment.
- Grease Pumps:High-viscosity displacement units with follower plates handle NLGI Grade 2 and 3 lubricants in mining and construction centralized architectures.
Volume placements concentrate in Electric Pumps; the faster expansion belongs to Pneumatic Pumps as intrinsically safe certifications extend their addressable market.
Technology:
Precision requirements and fluid compatibility dictate technology selection, with volumetric consistency commanding premium positioning in safety-critical applications.
- Positive Displacement:Reciprocating piston and rotary lobe mechanisms deliver fixed-volume output per cycle regardless of back-pressure. Aerospace engine manufacturers in Toulouse and Hamburg specify these systems where bearing starvation risks catastrophic failure.
- Gear Type:Meshing spur or helical gear sets provide continuous flow with minimal pulsation. Metalworking OEMs in Japan's Aichi prefecture integrate these pumps into coolant-lubricant delivery skids for high-speed machining centers.
- Piston Type:Axial and radial piston arrangements generate ultra-high pressures for hydrostatic bearing support.
- Diaphragm Type:Elastomer-separated pumping chambers isolate fluid from mechanical components in corrosive or sanitary environments.
- Vane Type:Sliding-vane rotary mechanisms offer compact footprint for mobile equipment hydraulic-lubricant combination circuits.
Revenue concentration sits with Positive Displacement; steepest expansion trajectory belongs to Gear Type as Asian machine-tool production scales.
Application:
Duty-cycle severity and contamination exposure create distinct specification tiers, with continuous-operation environments demanding redundant pump architectures.
- Metalworking Machinery:Coolant-lubricant delivery systems for cutting, grinding, and forming operations require chip-resistant filtration integration. Germany's Baden-Württemberg machine-tool cluster drives specification toward smart pumps with flow-feedback loops.
- Construction Equipment:Articulated loaders, excavators, and cranes need vibration-tolerant distributed lubrication. China's state-backed equipment modernization in Shandong province favors centralized pump-monitoring packages for fleet uptime guarantees.
- Mining Operations:Dust-laden atmospheres and shock loading demand heavy-duty progressive divider systems with purge capabilities.
- Textile Machines:High-speed spinning and weaving frames require micro-dose oil-mist systems with minimal fiber contamination.
- Marine Engines:Salt-air corrosion resistance and pitch-roll stability govern pump housing materials and mounting designs.
Installed base volume clusters in Metalworking Machinery; Mining Operations are gaining share fastest on commodity-cycle equipment reinvestment.
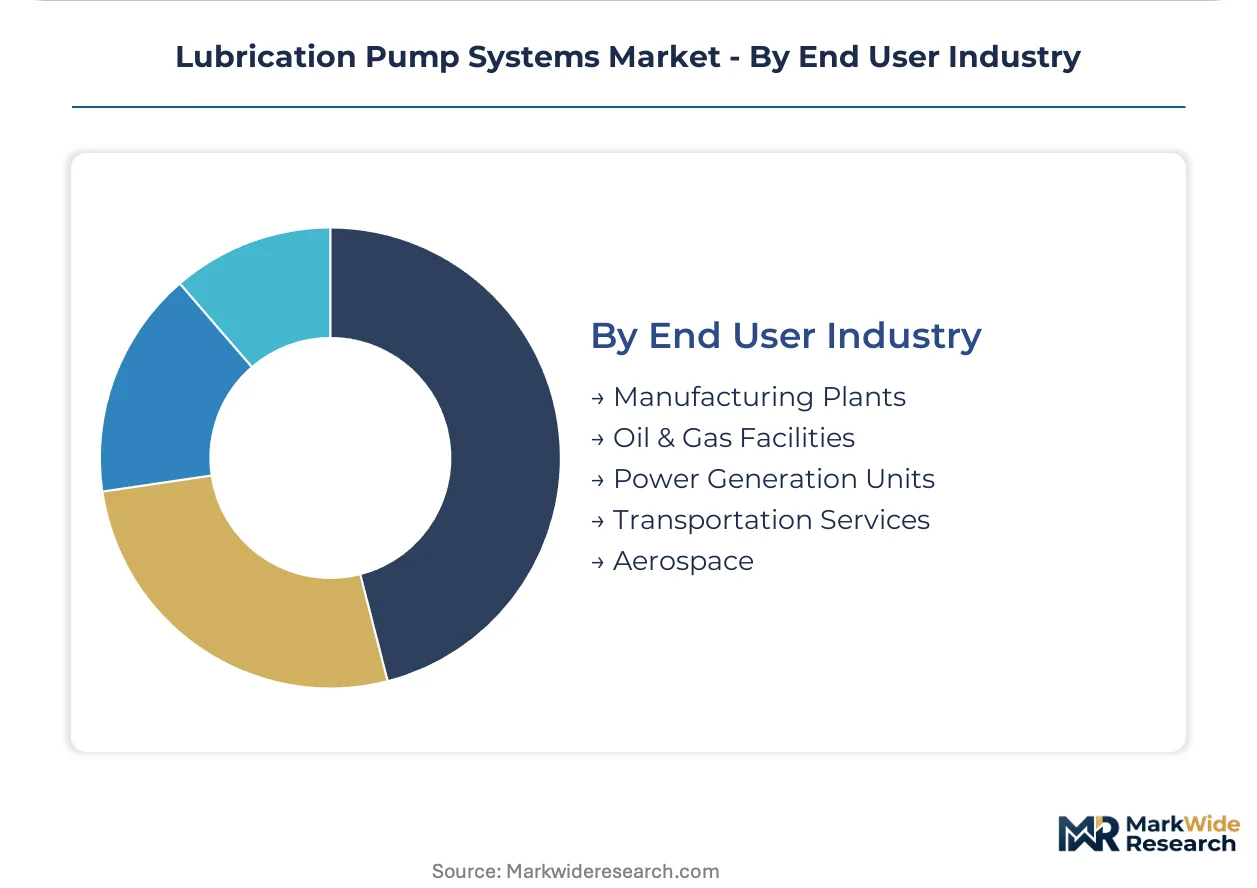
End User Industry:
Regulatory exposure and automation maturity shape procurement sophistication, with carbon-accounting pressures accelerating integrated system adoption.
- Manufacturing Plants:Discrete and process manufacturing operations deploy plant-wide lubrication networks with central monitoring. EPA emissions enforcement across Ohio and Michigan automotive stamping operations pulls demand for precision oil-delivery retrofits.
- Oil & Gas Facilities:Upstream, midstream, and downstream operations require explosion-proof and subsea-rated pump systems. North Sea platform operators specify condition-based lubrication with ultrasonic film-thickness monitoring.
- Power Generation Units:Gas turbine, steam turbine, and wind turbine generators need high-reliability bearing lubrication with emergency backup pumps.
- Transportation Services:Fleet operators for long-haul trucking and rail are unbundling service contracts toward telemetry-enabled lubrication-as-a-service models.
- Aerospace:Engine OEMs and MRO facilities mandate material traceability and AS9100-certified pump assemblies.
Current procurement volume centers on Manufacturing Plants; the expansion curve is steepest for Transportation Services as fleet telemetry contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern manufacturing corridor, where state-backed equipment modernization programs favor integrated pump-monitoring packages. Germany and Japan anchor precision retrofit activity. EPA enforcement in the United States pulls fleet operators toward smart oil-delivery systems.
China
Automotive stamping plants in Shandong province are replacing manual lubrication stations with centralized pump-monitoring architectures. MIIT equipment modernization directives accelerate replacement cycles. The Yangtze River Delta manufacturing belt drives specification toward Industry 4.0-compatible electric pump systems with predictive maintenance integration.
Germany
Metalworking machinery operators across Baden-Württemberg are expanding automated lubrication retrofits to compress unplanned downtime. REACH compliance deadlines force reformulation of seal compounds and pump housings. The Aachen-Düsseldorf industrial corridor concentrates demand for smart coolant-lubricant delivery skids with flow-feedback loops.
United States
Fleet operators across the I-80 trucking corridor are unbundling service contracts toward telemetry-enabled lubrication-as-a-service models. EPA emissions enforcement mandates precision oil-delivery retrofits to reduce friction losses. Ohio and Michigan automotive stamping operations pull demand for smart pump-motor combinations with predictive monitoring.
Japan
METI funding for hydrogen fueling infrastructure creates demand for specialized high-pressure grease systems in compressor applications. Machine-tool OEMs in Aichi prefecture integrate gear-type pumps into coolant-lubricant delivery skids. The Nagoya-Toyota industrial cluster drives specification toward volumetric consistency in high-speed machining centers.
India
Production-linked incentive schemes for heavy machinery open specification windows for centralized lubrication architectures in domestic mining equipment. BIS certification requirements shape product validation timelines. The Gujarat-Maharashtra manufacturing belt concentrates procurement of progressive divider systems for construction fleet uptime guarantees.
Lubrication Pump Systems Market Competitive Landscape
German and Swedish producers anchor one tier; American specialists hold manufacturing scale advantages in electric pump assemblies. The vendor base organizes around three strategic archetypes: integrated bearing-lubrication platform vendors, precision-machined component assemblers with captive supply, and centralized architecture specialists for heavy-duty applications. Consolidation pressure intensifies as fleet operators compress supplier rosters toward integrated platform vendors. Backward integration into seal compound production preserves margin against REACH compliance cost inflation.
Within the integrated platform tier, SKF leverages its bearing-lubrication convergence to anchor premium positioning across Nordic industrial clusters. Graco Inc exemplifies manufacturing scale advantages in North American electric pump assemblies through in-house production of precision-machined components. Bijur Delimon International occupies a position as a centralized architecture specialist for heavy-duty mining and construction applications. These three represent the competitive spectrum from component integration to application-specific system design.
| Leading Market Players |
|---|
| SKF |
| Graco Inc |
| Groeneveld Group |
| Beka-Lube Products Inc |
| Cenlub Systems |
| Bijur Delimon International |
| DropsA |
| Lincoln Industrial |
| Trico Corporation |
| Others |
Pricing and Supply Chain Analysis
Digital lubrication architectures are displacing mechanical distributors across German automotive plants and Chinese stamping facilities, simultaneously compressing hardware margins and concentrating procurement power among integrated platform vendors. This technology shift forces suppliers to absorb sensor and connectivity costs while competing for long-term consumable contracts.
Pricing Analysis
High-volume electric pump assemblies compete on manufacturing scale, while precision positive-displacement systems for aerospace command certification premiums. Price differentiation hinges on AS9100 aerospace certification and REACH-compliant seal compound traceability. Cost compression in standard electric pumps intensifies as Chinese OEMs expand domestic production capacity. Fleet operators in North American long-haul trucking show highest price sensitivity, prioritizing uptime guarantees over capital equipment ownership.
Supply Chain Analysis
Single-source vulnerability sits with precision-machined pump housings concentrated in German and Japanese tooling networks. Raw material flows draw from specialty alloy foundries in Germany, precision bearing manufacturers in Sweden, and seal compound producers in the United States. Tariff exposure on precision-machined components creates input cost volatility for North American assemblers. Distribution runs through OEM direct channels for large fleet operators and industrial distributors for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lubrication pump systems market is becoming a vertical-integration race, with seal compound backward integration and predictive software development as the decisive margin-preservation levers.
For Market Incumbents: To counter standalone pump commoditization, SKF and Graco must deepen captive supply of REACH-compliant seal compounds and bundle cloud-based flow analytics with hardware contracts. Locking in long-term consumable agreements through telemetry-enabled service models defends margin against price erosion in electric pump assemblies. For New Entrants and Emerging Players: Industrial distributors with existing fleet relationships represent the most viable channel partner type for penetrating India's PLI-linked mining equipment sector. Target construction OEMs in Gujarat and Maharashtra with progressive divider systems priced below European incumbent levels. White-space exists in hydrogen fueling station grease systems for Japan's METI-funded infrastructure buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by bearing and motion-control conglomerates seeking lubrication convergence. Long-term viability favors suppliers with backward-integrated seal production and certified aerospace assemblies. Monitor ECHA substance list expansions as the inflection signal for compliance-driven replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compounds | Captive production of REACH-compliant materials preserves margin against ECHA compliance cost inflation. |
| Predictive Maintenance Platform Launch | Cloud analytics bundling locks in consumable contracts with German automotive stamping operators. |
| AS9100 Certification Investment | Aerospace material traceability opens specification windows with Toulouse and Hamburg engine manufacturers. |
| Joint Venture in India | Local assembly partnerships capture PLI-linked mining equipment demand in Gujarat-Maharashtra belt. |
| Hydrogen Infrastructure Supply Agreement | METI-funded compressor applications create specialized high-pressure grease system demand in Japan. |
Research Methodology
Document review covered customs trade databases, SEC 10-K filings, and ECHA regulatory notices, complemented by interviews with maintenance directors at German automotive plants, OEM procurement teams in China's Yangtze River Delta, and aftermarket service heads at North American fleet operators. Secondary validation drew from MIIT equipment modernization directives, EPA emissions enforcement records, and METI hydrogen infrastructure funding disclosures. Bottom-up pump shipment data triangulated against top-down manufacturing capacity estimates.
Historical volume trends cross-referenced against panel input from plant engineers and lubrication system integrators across the projection horizon. Segmentation modeling spanned power source, precision mechanism technology, duty-cycle environment, and regional regulatory cluster. CAGRs derived from replacement-cycle velocity analysis intersecting with compliance deadline schedules. Industry-specific inputs included REACH certification timeline data and PLI scheme qualification criteria.
Caveats apply where ECHA substance restriction expansions or EPA enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions about Industry 4.0 retrofit adoption rates and hydrogen infrastructure deployment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market