
 Europe Asia Submerged Pump Market | 2026-2036
Europe Asia Submerged Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Asia Submerged Pump Market Insights
Modular pump-motor configurations is consolidating buyer preference across the Europe Asia Submerged Pump Market, as utilities and irrigation cooperatives favor standardized submersible assemblies over bespoke single-unit procurement. Xylem Inc. leverages its digital monitoring platforms to anchor premium positioning in European municipal water networks. Sulzer AG sustains engineering intensity in abrasive-duty mining applications across Central Asia. Grundfos Holding A/S dominates energy-efficient circulator integration for district heating retrofit programs in Scandinavia and South Korea.
Europe Asia submerged pumps are hermetically sealed centrifugal or positive-displacement machines designed to operate fully immersed in pumped fluid, typically constructed from cast iron, stainless steel, or specialized polymer housings with motor windings protected by oil-filled or water-filled cooling jackets; their primary purpose is to lift groundwater, process fluids, or wastewater without suction lift limitations or cavitation risk. Centrifugal configurations occupy the largest installed base across agricultural irrigation and municipal water supply due to proven head-flow performance, while solar-powered technology segments register the fastest adoption trajectory as off-grid irrigation expands in India, Vietnam, and the Philippines. Vortex impeller designs compete aggressively in wastewater treatment applications where solids handling determines operational uptime and maintenance scheduling.
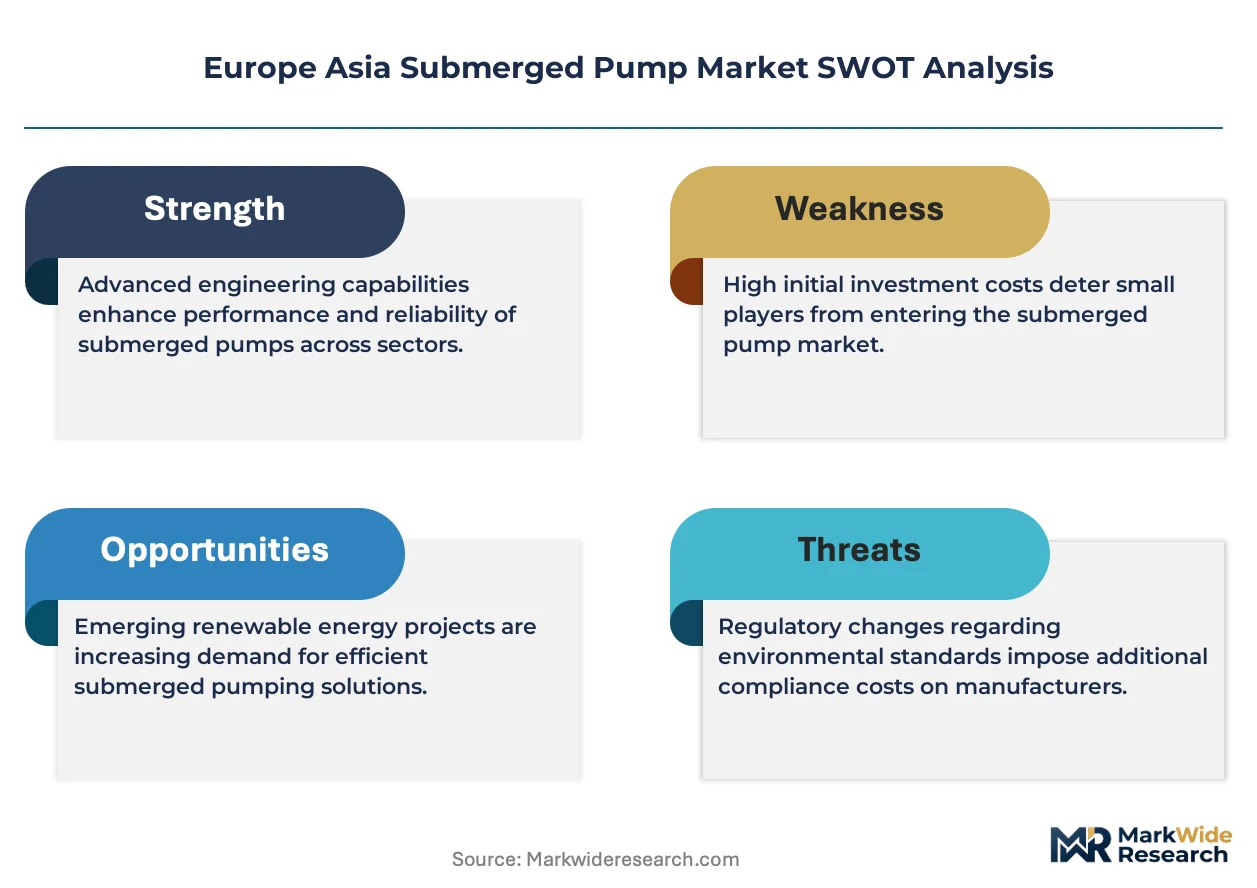
EMA energy efficiency frameworks and China's GB standards for motor-driven equipment are tightening minimum performance thresholds, effectively disqualifying lower-tier imports from non-compliant manufacturers. REACH substance restrictions and RoHS directives constrain elastomer and insulation material choices for pumps sold into EU member states, pushing suppliers toward fluoropolymer and thermoplastic alternatives. India's BIS certification requirements and CEA pumping system mandates add parallel compliance layers for equipment deployed in groundwater extraction. Stakeholders must monitor regulatory divergence between European ecodesign trajectories and Asia-Pacific national efficiency labeling schemes to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Modular pump-motor configurations are consolidating buyer preference across the Europe Asia Submerged Pump Market, as utilities and irrigation cooperatives favor standardized submersible assemblies over bespoke single-unit procurement. This structural shift toward interchangeability is compressing margins for custom engineering while rewarding platform-scale manufacturers.
Growth Catalysts
- Solar-powered irrigation expansion:Agricultural cooperatives across India's groundwater-dependent belts are replacing diesel units with photovoltaic-driven submersible systems to reduce operating expenditure and comply with state-level renewable procurement mandates.
- EU Ecodesign Directive:Tightening minimum efficiency thresholds for motor-driven equipment are accelerating replacement cycles in European municipal water networks, creating pull-through demand for premium submersible configurations.
- Aquaculture zone development:Indonesia's expanding shrimp and fish farming operations require reliable water circulation systems, driving procurement of corrosion-resistant stainless steel submersible pumps in coastal provinces.
Market Restraints
- Copper and rare earth price volatility:Motor winding materials and permanent magnet components face input cost pressure, squeezing manufacturing margins for mid-tier suppliers concentrated in Chinese industrial clusters.
- REACH substance restrictions:Elastomer and insulation material constraints for pumps sold into EU member states are forcing costly reformulation of sealing systems and cooling jacket compounds.
- Surface pump substitution:Progressing suction lift technology in centrifugal surface pumps threatens submersible share in shallow well applications across Southeast Asian smallholder farms.
Strategic Opportunities
- Vietnam's Mekong Delta:Underpenetrated deltaic irrigation infrastructure presents white space for solar-submersible hybrid systems serving rice intensification programs and saltwater intrusion mitigation.
- Digital monitoring convergence:Integration of IoT sensors with submersible motor controls enables predictive maintenance contracts, shifting revenue models toward recurring service streams in Scandinavian district heating networks.
- China's dual carbon goals:National efficiency labeling schemes and provincial green procurement incentives create regulatory tailwind for variable-frequency drive submersible pumps in industrial process applications.
Industry Challenges
- Submersible motor rewinding specialization:Shortage of technicians certified for hermetic motor repair in Central Asian mining regions extends equipment downtime and strains aftermarket service networks.
- BIS certification timelines:India's mandatory testing protocols for groundwater extraction equipment create 4-6 month product approval delays, complicating inventory planning for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Asia Submerged Pump Market |
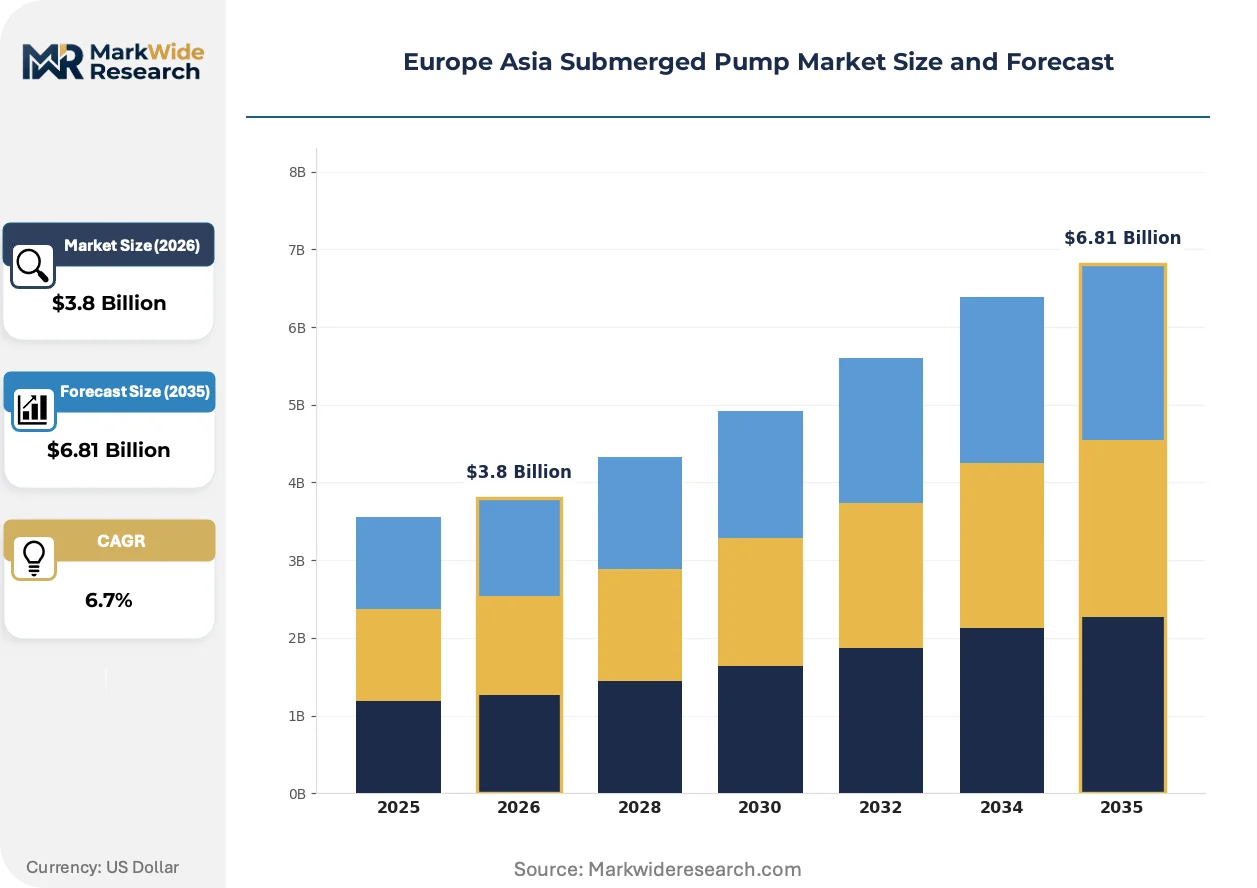
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vortex, Screw, Centrifugal, Gear Application: Agricultural Irrigation, Residential Drainage, Aquaculture, Wastewater Treatment Technology: Electric, Diesel, Solar, Hydraulic End User: Industrial, Municipal, Commercial, Domestic |
| Companies Covered | Xylem Inc., Sulzer AG, KSB SE & Co. KGaA, Grundfos Holding A/S, Ebara Corporation, Atlas Copco AB, Flowserve Corporation, Kubota Corporation, Wilo SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Asia Submerged Pump Market Trends and Innovations
Technology convergence and regulatory compression are actively reshaping competitive positioning in the Europe Asia Submerged Pump Market, with standardization and digitalization emerging as dominant vectors of change.
Permanent magnet synchronous motor technology is modularizing submersible pump architecture across agricultural and municipal segments. Danish and South Korean utilities are adopting plug-and-play motor-pump cartridges that slash field replacement time from days to hours. This standardization is modularizing supplier ecosystems, enabling third-party component sourcing and eroding captive aftermarket revenue for integrated manufacturers.
REACH substance restrictions and RoHS directives are constraining elastomer and insulation material choices for pumps sold into EU member states. Industrial consequences include accelerated fluoropolymer adoption for sealing systems and thermoplastic substitution in cable insulation. Wastewater treatment OEMs serving German and French municipal networks are responding with pre-certified material platforms that streamline cross-border compliance.
Cooperative procurement consortia are displacing fragmented individual purchasing across European irrigation districts and Asian aquaculture zones. Equipment distributors in the Netherlands and Thailand are consolidating last-mile service capabilities to capture recurring maintenance contracts. This channel consolidation is most visible in India's groundwater-dependent agricultural belts, where farmer producer organizations negotiate volume discounts and bundled technical support.
Europe Asia Submerged Pump Market Segmentation
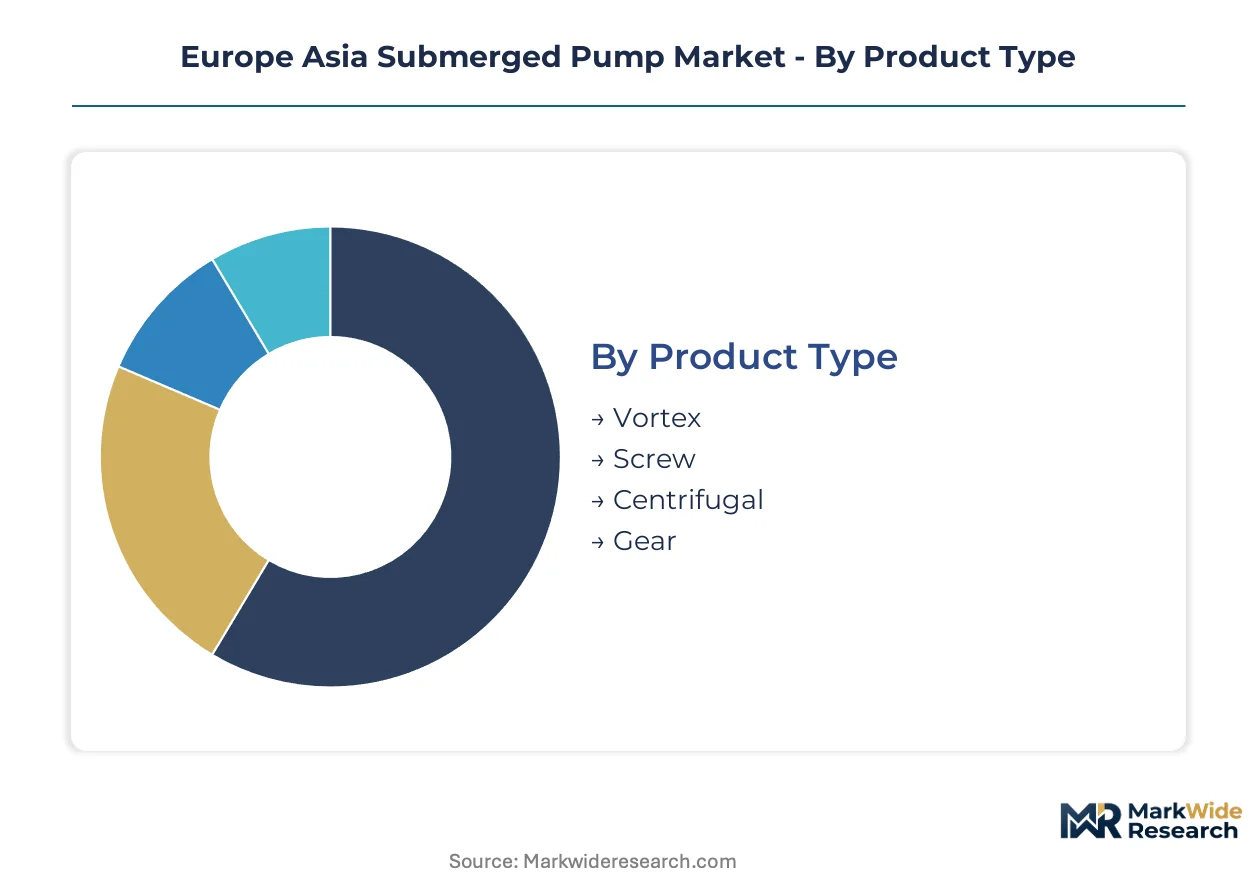
Submerged pump procurement patterns diverge sharply across product configurations and power sources, with certification requirements from BIS, EMA, and China's GB standards fragmenting supplier strategies. Understanding segment-specific compliance burdens and application intensity clarifies where margin compression and technology substitution risks concentrate.
Product Type:
REACH substance restrictions and RoHS directives impose divergent material certification costs across impeller architectures, with stainless steel housings facing stricter elastomer validation than cast iron alternatives.
- Centrifugal:Radial flow impellers constructed from cast iron or stainless steel dominate groundwater extraction and municipal distribution networks. India's agricultural belts in Punjab and Haryana drive procurement volume for standardized submersible borehole units.
- Vortex:Recirculating flow designs with recessed impellers handle high-solids wastewater without clogging. German and French municipal treatment facilities specify these configurations for sludge transfer applications under EMA effluent discharge frameworks.
- Screw:Progressive cavity mechanisms deliver consistent flow rates across varying viscosities. Food processing and industrial slurry applications in Poland and Thailand specify these for shear-sensitive fluid handling.
- Gear:Positive displacement rotary pumps manage high-pressure, low-flow conditions in hydraulic lift systems. Mining dewatering operations in Kazakhstan and Uzbekistan deploy these for deep-well extraction.
Centrifugal configurations sit at the top of the volume ranking, with Vortex designs climbing the fastest as EMA wastewater standards tighten solids-handling specifications.
Application:
End-use intensity varies by water stress geography and infrastructure maturity, with shallow well applications in Southeast Asia facing surface pump substitution pressure.
- Agricultural Irrigation:Borehole submersibles lift groundwater for rice intensification and horticulture across water-stressed districts. Solar-electric hybrids are displacing diesel units in Maharashtra and Gujarat under state renewable procurement mandates.
- Wastewater Treatment:Submersible mixers and sewage pumps handle raw influent and activated sludge. Danish and Dutch utilities specify corrosion-resistant stainless steel units for nutrient removal processes.
- Aquaculture:Circulation pumps maintain dissolved oxygen levels in intensive shrimp and fish farming. Indonesia's coastal provinces in Java and Sulawesi drive demand for saltwater-resistant polymer housings.
- Residential Drainage:Compact sump and sewage ejector pumps manage basement flooding and greywater. South Korean apartment retrofit programs and Polish single-family housing clusters sustain replacement demand.
Agricultural Irrigation commands the largest installed base, though Aquaculture is expanding most quickly as Indonesia scales export-oriented seafood production.
Technology:
Power source selection determines total cost of ownership calculations and regulatory exposure, with efficiency labeling schemes creating divergent compliance pathways.
- Electric:Grid-connected AC induction and permanent magnet synchronous motors dominate municipal and industrial installations. EU Ecodesign Directive thresholds accelerate replacement of sub-IE3 efficiency classes in German water utilities.
- Solar:Photovoltaic-driven DC submersibles with maximum power point tracking eliminate fuel logistics for off-grid irrigation. Vietnam's Mekong Delta and the Philippines' Palawan province represent underpenetrated deployment zones.
- Diesel:Compression-ignition engines persist in remote mining and emergency backup applications. China's dual carbon goals and provincial emissions enforcement compress new sales in industrial process markets.
- Hydraulic:Fluid power drives operate in explosive atmospheres where electrical spark risk is prohibitive. Central Asian oilfield services and underground mining contractors specify these for safety-critical dewatering.
Electric systems retain volume leadership across Europe and East Asia, while Solar configurations gain share fastest as photovoltaic module costs decline and irrigation electrification programs expand.
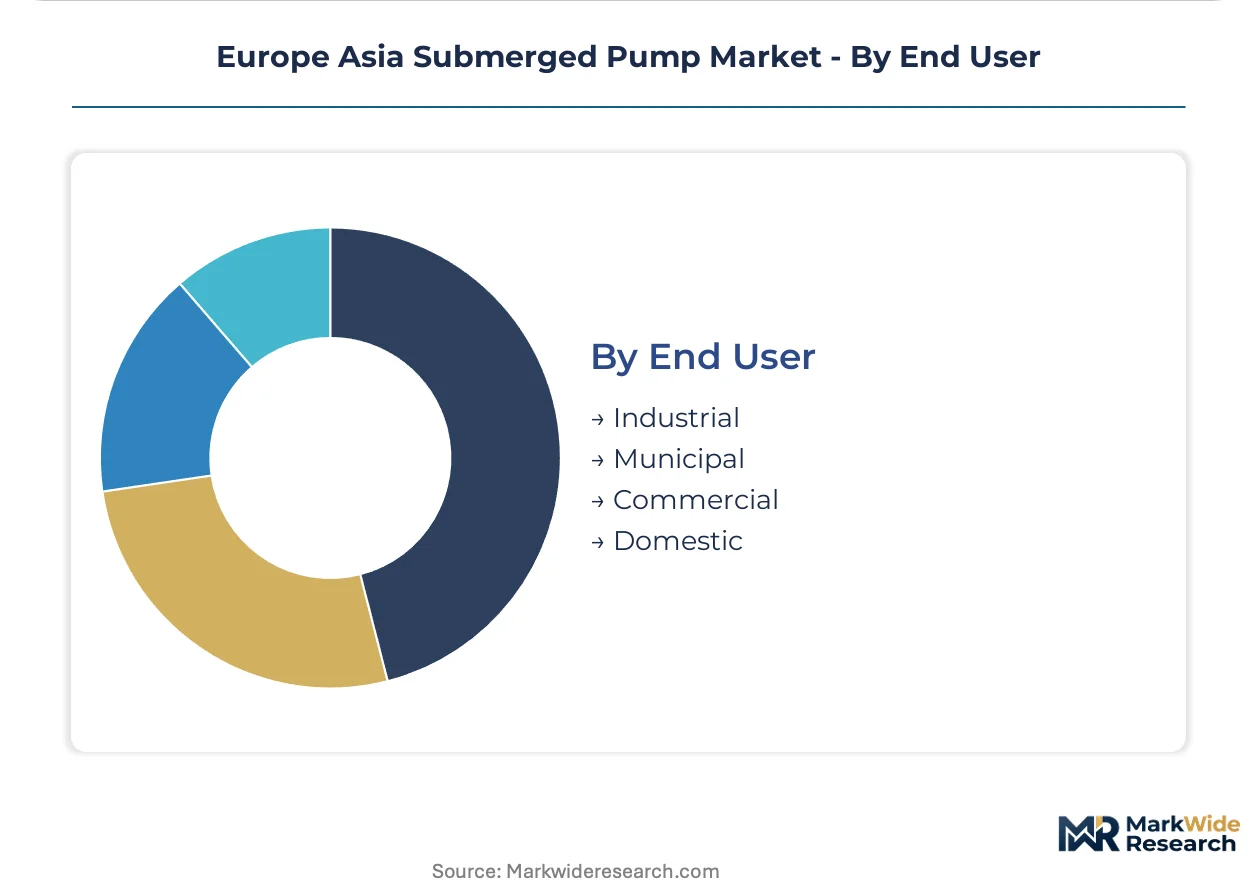
End User:
Customer scale determines procurement sophistication, with cooperative consortia displacing fragmented individual purchasing in agricultural and aquaculture segments.
- Municipal:City water authorities and wastewater utilities specify long-life submersibles with predictive maintenance contracts. Scandinavian district heating networks and South Korean metropolitan water services prioritize digital monitoring integration.
- Industrial:Process manufacturers and mining operators demand abrasive-duty configurations with rapid component interchangeability. Sulzer AG and Xylem Inc. anchor premium positioning in Central Asian copper extraction and Polish chemical processing.
- Commercial:Hotels, hospitals, and retail complexes require compact drainage and pressure boosting systems. Thailand's hospitality sector and India's healthcare infrastructure expansion sustain mid-tier procurement.
- Domestic:Individual households and smallholder farmers purchase through distributor networks with bundled technical support. India's farmer producer organizations negotiate volume discounts for groundwater extraction equipment.
Municipal end users represent the most stable revenue base, with Industrial customers showing the steepest expansion trajectory as process water recycling mandates intensify across Europe and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submersible pump manufacturing originated in European industrial centers during the mid-20th century, with German and Danish engineering firms pioneering hermetic motor designs for groundwater extraction. The technology diffused to Asia-Pacific through joint ventures and licensing agreements in the 1980s, establishing production clusters in China, India, and South Korea.
Germany
German municipal utilities drive replacement demand for high-efficiency submersible units in aging water distribution networks. The EU Ecodesign Directive mandates IE3 motor efficiency minimums, accelerating淘汰 of legacy installations. Industrial pump fabricators in the Ruhr Valley and Baden-Württemberg specialize in abrasion-resistant configurations for mining dewatering applications.
India
Groundwater-dependent agricultural belts in Punjab, Haryana, and Maharashtra consume standardized borehole submersibles for rice intensification and horticulture. BIS certification requirements and CEA pumping system mandates create 4-6 month product approval timelines for imported equipment. Farmer producer organizations in Gujarat negotiate volume procurement contracts with bundled technical support services.
China
Provincial green procurement incentives and national dual carbon goals compress demand for diesel-powered units in industrial process markets. GB standards for motor-driven equipment tighten minimum performance thresholds, disqualifying lower-tier imports. Manufacturing clusters in Zhejiang and Jiangsu provinces supply standardized submersible assemblies for domestic irrigation and export markets.
Indonesia
Expanding shrimp and fish farming operations in Java and Sulawesi coastal provinces drive procurement of corrosion-resistant stainless steel submersible pumps. Saltwater intrusion mitigation programs in the Mekong Delta region create demand for solar-electric hybrid circulation systems. Local distributors consolidate last-mile service capabilities to capture recurring maintenance contracts.
South Korea
Metropolitan water services in Seoul and Busan prioritize digital monitoring integration for district heating retrofit programs. Permanent magnet synchronous motor technology enables plug-and-play pump-motor cartridges that reduce field replacement time. Domestic manufacturers supply energy-efficient circulators for residential drainage and commercial pressure boosting applications.
Europe Asia Submerged Pump Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering intensity and aftermarket service depth, creating a tiered competitive structure. The vendor base spans integrated multinational corporations with full-stack manufacturing capabilities and regional specialists focused on price-competitive standardized units. Two dominant strategic archetypes emerge: platform-scale manufacturers leveraging modular architectures for interchangeability, and application-focused specialists commanding premiums in abrasive-duty or hygienic-process niches. Consolidation through strategic partnerships and geographic licensing agreements reshapes competitive boundaries.
Among Denmark-based integrated pump manufacturers, Grundfos Holding A/S exemplifies the premium-tier platform player with standardized submersible assemblies. Swiss industrial specialist Sulzer AG occupies a position within the abrasion-duty segment, while Japanese diversified industrial Ebara Corporation represents the Asia-Pacific engineering-intensive archetype. Xylem Inc. anchors the digital monitoring convergence tier, and KSB SE & Co. KGaA sits within the German municipal water infrastructure specialist category. These five named entities collectively illustrate the geographic and technological diversification patterns shaping procurement decisions across European and Asian end-use markets.
| Leading Market Players |
|---|
| Xylem Inc. |
| Sulzer AG |
| KSB SE & Co. KGaA |
| Grundfos Holding A/S |
| Ebara Corporation |
| Atlas Copco AB |
| Flowserve Corporation |
| Kubota Corporation |
| Wilo SE |
| Others |
Pricing and Supply Chain Analysis
Copper winding costs cascade through motor manufacturing clusters in Zhejiang and Jiangsu provinces, compressing margins for mid-tier assemblers serving price-sensitive agricultural cooperatives while premium European OEMs pass through material volatility via long-term municipal service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and aftermarket bundling. Premium tiers attach predictive maintenance contracts for Scandinavian district heating networks, while economy tiers compete on unit cost for Indian groundwater extraction. Cost compression in the standard tier is intensifying because Chinese GB efficiency standards disqualify legacy motor configurations. Municipal utilities show least price sensitivity due to lifecycle cost accounting; smallholder farmer cooperatives in Southeast Asia exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Certification gating through BIS, EMA, and REACH protocols fragments supplier access across procurement zones. Manufacturing concentrates in China, Germany, and Denmark. Motor windings draw from copper smelters in Chile and Zambia; permanent magnet supply rests on rare earth processing in China. Single-source vulnerability concentrates in neodymium magnet supply chains. Distribution runs through irrigation cooperative consortia in India and aquaculture zone distributors in Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as groundwater stress intensifies irrigation electrification mandates across water-stressed agricultural belts.
For Market Incumbents: Anchor platform-scale manufacturing in standardized submersible cartridges to capture recurring aftermarket revenue. Defend against solar-powered surface pump substitution by deepening predictive maintenance integration for European municipal accounts. Prioritize IE4 motor efficiency certification investment ahead of EU Ecodesign Directive tightening. For New Entrants and Emerging Players: China's dual carbon goals and provincial green procurement incentives open a window for variable-frequency drive submersible pumps in industrial process markets. Target Vietnam's Mekong Delta for solar-submersible hybrid deployment where saltwater intrusion mitigation programs lack established supplier relationships. Pursue cooperative procurement consortia as the primary go-to-market channel. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack capital for multi-certification compliance across BIS, EMA, and GB standards. Five-to-ten year viability favors platform-scale players with captive aftermarket service networks. Target acquisition archetype: regional specialists with established irrigation cooperative relationships and pending efficiency certification. Watch solar module cost trajectories as inflection indicator for off-grid submersible penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Platform Standardization | Plug-and-play cartridges reduce field replacement time for Danish and South Korean utilities. |
| Backward Integration into Copper Winding Supply | Captive motor production insulates margins from Zhejiang raw material volatility. |
| Digital Monitoring Convergence | IoT sensor integration enables predictive maintenance contracts in Scandinavian district heating. |
| Multi-Certification Pre-Approval Investment | Pre-certified REACH and BIS platforms streamline cross-border supply chain deployment. |
| Solar-Electric Hybrid System Launch | Photovoltaic-driven DC submersibles penetrate underelectrified Mekong Delta irrigation zones. |
Research Methodology
Bottom-up agricultural and municipal utility modeling reconciled against top-down manufacturing cluster tracking forms the analytical core of this study. Primary interviews with irrigation cooperative managers, municipal water authority procurement officers, aftermarket service technicians, and OEM engineering directors combined with secondary validation from customs trade data, CEA pumping system filings, EU Ecodesign Directive implementation reports, and BIS certification registries. Triangulation between demand-side project pipelines and supply-side capacity utilization rates anchors volume estimates.
Historical trendline analysis of replacement cycle timing, efficiency standard adoption curves, and solar electrification program deployment informs projection logic across the analysis window. Segmentation dimensions span impeller architecture, power source technology, end-use intensity, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to certified equipment procurement trajectories and groundwater extraction permit issuance patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or abrupt EU motor efficiency threshold acceleration. Model outputs reflect documented assumptions regarding cooperative procurement consolidation rates and photovoltaic cost decline trajectories. A model refresh is warranted upon material change in China's dual carbon policy enforcement intensity or BIS certification timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
United States Subsea Pumps Market