
 Single-Use Pump Market | 2026-2036
Single-Use Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Pump Market Analytics
The gap between premium and commodity tiers is broadening as validated single-use pumps for biopharmaceutical aseptic processing command pricing multiples over standard industrial disposable units. Watson-Marlow Fluid Technology Solutions dominates high-purity peristaltic designs through its specialized silicone tubing formulations and cleanroom-compatible assemblies. Sartorius AG leverages its integrated bioprocessing platform to anchor recurring consumable revenue streams alongside hardware placement.
A single-use pump is a fluid handling device engineered with disposable wetted components—typically molded thermoplastics, elastomeric tubing, or fluoropolymer diaphragms—designed for one operational cycle or campaign before replacement to eliminate cross-contamination risk and clean-in-place downtime. Peristaltic pumps lead installed base across biopharmaceutical fluid transfer due to their gentle low-shear action on sensitive biological media, while diaphragm pumps capture margin pools in high-precision dosing applications where pulsation control proves critical. Electromechanical technology occupies the fastest-expanding segment as brushless DC motor integration enables programmable flow profiles that pneumatic alternatives cannot match.
The US FDA enforces strict sterility assurance requirements under current Good Manufacturing Practice guidelines that effectively mandate validated single-use systems for multi-product biologics facilities. The European Medicines Agency's Annex 1 revision on sterile medicinal products further tightens contamination control expectations, pushing manufacturers toward pre-sterilized disposable pump assemblies with documented extractables and leachables profiles. Stakeholders must weigh total cost of ownership against capital avoidance as facility footprints shrink and batch flexibility becomes the decisive operational metric.
Market Dynamics
Biopharmaceutical manufacturers are compressing facility changeover times by eliminating clean-in-place protocols, forcing a wholesale reconfiguration of fluid handling infrastructure toward disposable architectures that trade capital avoidance for consumable lock-in.
Growth Catalysts
- FDA sterility guidelines:Current Good Manufacturing Practice mandates for multi-product biologics facilities effectively require validated single-use systems, accelerating facility retrofit timelines.
- Peristaltic pump technology:Low-shear fluid action preserves sensitive biological media integrity during downstream processing, expanding adoption in monoclonal antibody production workflows.
- German contract manufacturing:CMOs retrofitting legacy stainless-steel infrastructure with single-use alternatives are driving concentrated demand for pre-sterilized pump assemblies.
Market Restraints
- Silicone tubing supply concentration:Specialized platinum-cured formulations for high-purity applications depend on a narrow supplier base concentrated in Western Europe.
- Extractables and leachables testing burden:EMA Annex 1 revision demands documented validation profiles that extend qualification timelines and inflate compliance costs.
- Stainless-steel residual preference:Established biologics facilities with amortized capital equipment resist full conversion to disposable architectures.
Strategic Opportunities
- Cell and gene therapy manufacturing:Personalized medicine production requires ultra-flexible batch configurations that single-use pumps uniquely enable.
- Integrated bioprocessing platforms:Hardware placement strategies that anchor recurring consumable revenue streams are reshaping vendor-customer relationships.
- Pre-sterilized assembly standardization:ISO 13485 quality management adoption across emerging biopharmaceutical clusters reduces customer validation burden.
Industry Challenges
- Bioprocess engineering talent scarcity:Cross-functional expertise spanning fluid dynamics, materials science, and regulatory compliance remains concentrated among senior practitioners.
- Legacy system integration complexity:Retrofitting disposable pump assemblies into existing distributed control architectures demands customized interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Pump Market |
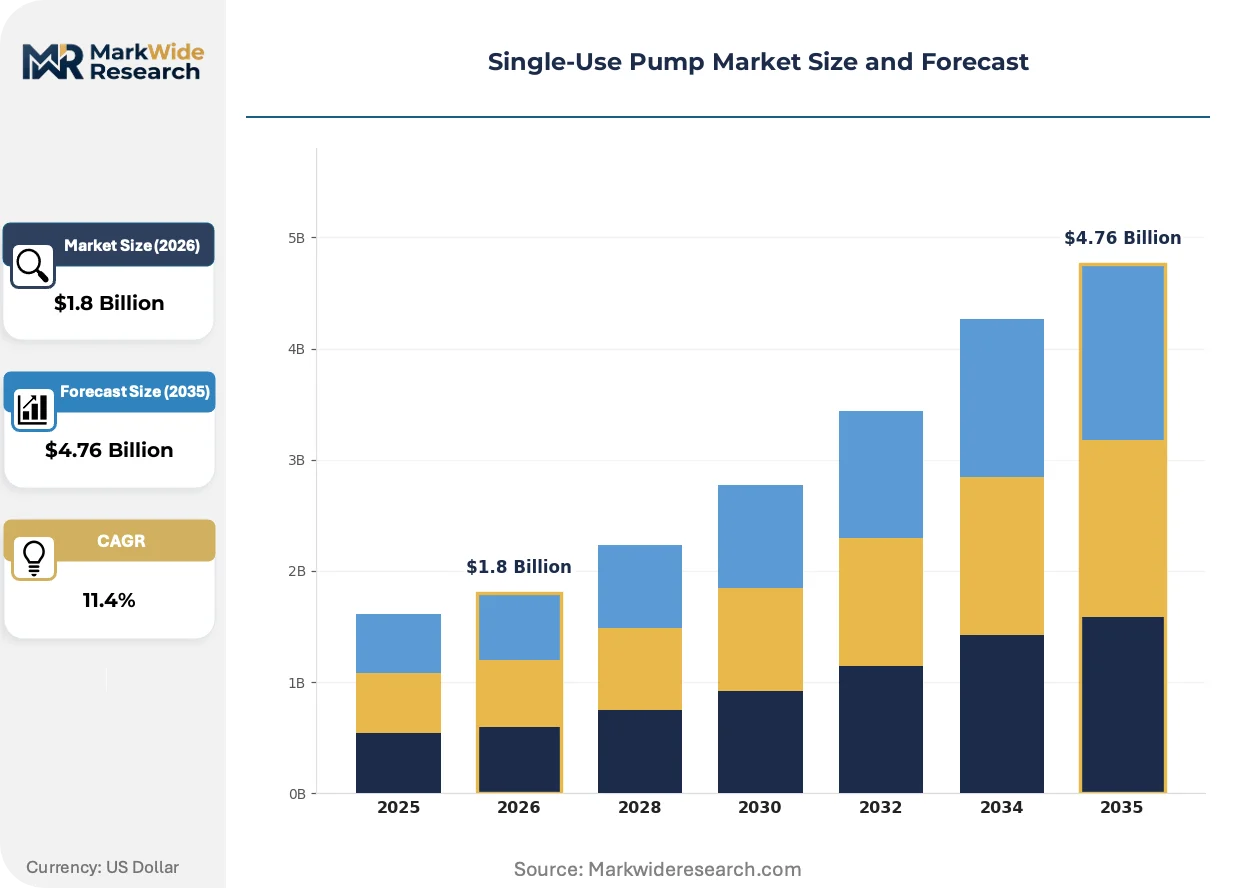
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Pumps, Diaphragm Pumps, Gear Pumps, Piston Pumps End User: Pharmaceuticals, Biotechnology, Food & Beverage, Chemical Processing Application: Fluid Transfer, Dosing, Irrigation, Waste Disposal Technology: Electromechanical, Pneumatic, Hydraulic, Manual |
| Companies Covered | Watson-Marlow Fluid Technology Solutions, Dover Corporation, Xylem, Levitronix, Spirax Group plc, Sartorius AG, Fluid Flow Products, Inc., SMC Corporation, Stobbe Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Pump Market Evolving Landscape
Electromechanical pump architectures are displacing pneumatic alternatives through programmable precision, while regulatory pressure on contamination control intensifies documentation requirements for disposable fluid path components.
Brushless DC motor integration into peristaltic pump designs is absorbing functionality previously requiring external control systems. Biopharmaceutical process engineers adopt these electromechanical units for programmable flow profiles in chromatography and tangential flow filtration steps. The technology is absorbing margin from pneumatic alternatives while compressing the addressable market for standalone pump controllers.
EMA Annex 1 revision on sterile medicinal products tightens contamination control expectations for aseptic processing equipment. Manufacturers must now document extractables and leachables profiles for all wetted components before facility qualification. Pre-sterilized disposable pump assemblies with validated documentation packages command preference in European biologics facility upgrades.
Consumables-led procurement models are displacing capital-equipment purchasing cycles in biopharmaceutical fluid handling. Large molecule manufacturers now prioritize total cost-per-batch metrics over upfront hardware acquisition costs. German and Swiss CMOs lead this shift, negotiating multi-year consumable supply agreements tied to pump hardware placement.
Single-Use Pump Market Segmentation
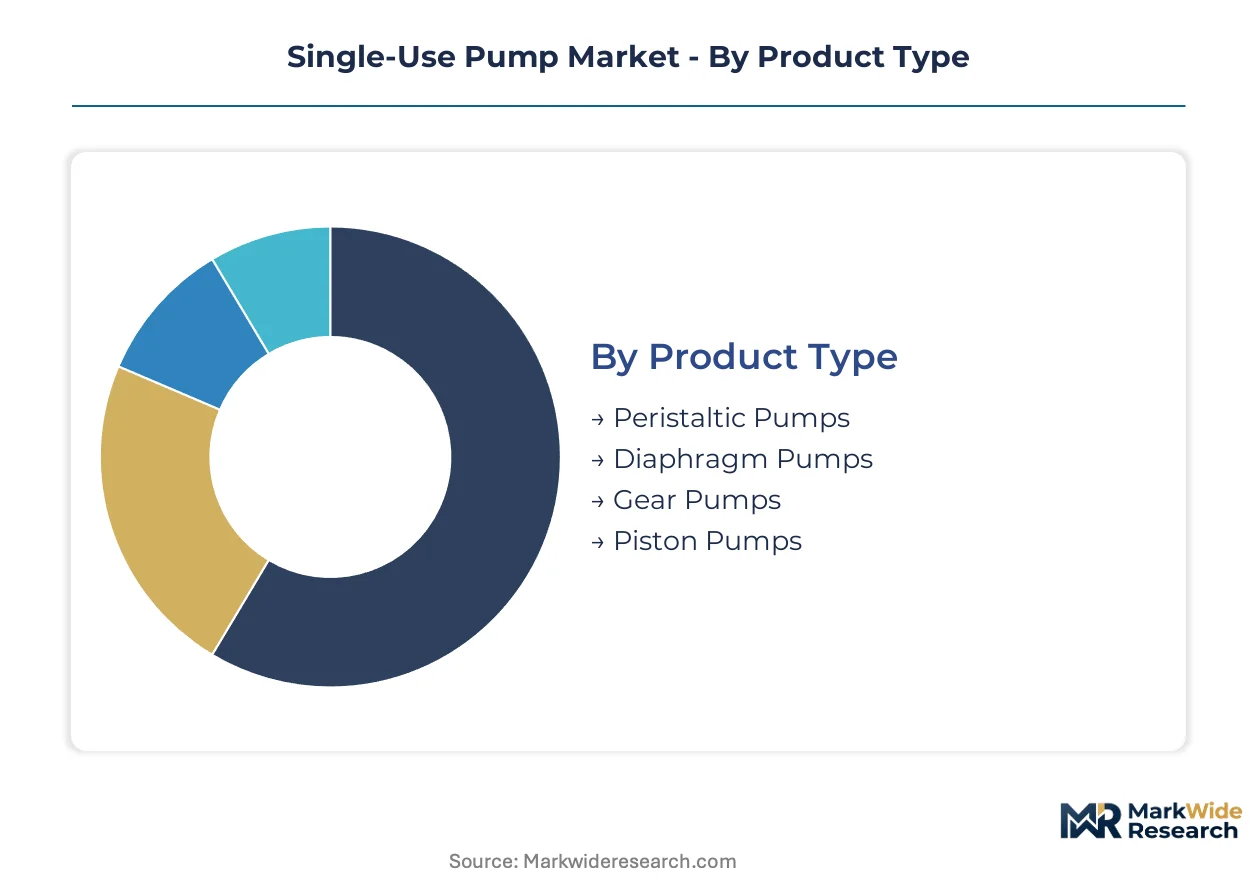
Single-use pump procurement decisions split across technical performance requirements and regulatory validation tiers. Biopharmaceutical manufacturers prioritize contamination control specifications while chemical processors emphasize chemical compatibility and throughput economics.
Product Type:
Buyers differentiate primarily by shear sensitivity of transferred media and precision requirements for downstream unit operations.
- Peristaltic Pumps:These systems employ elastomeric tubing compressed by rotating rollers to create gentle peristaltic action that preserves protein integrity in monoclonal antibody harvests. Demand concentrates in German and Swiss contract manufacturing facilities where FDA sterility guidelines mandate validated disposable fluid paths for multi-product suites. Low-shear characteristics dominate biopharmaceutical fluid transfer applications.
- Diaphragm Pumps:Fluoropolymer diaphragms reciprocate within sealed chambers to deliver pulse-dampened flow for high-precision chromatography buffer dosing. Margin pools accumulate in aseptic filling operations where pulsation control proves critical for volumetric accuracy. Biotechnology manufacturers specify these units for active pharmaceutical ingredient transfer steps.
- Gear Pumps:Molded thermoplastic gears mesh to provide continuous positive displacement for viscous cell culture media and high-concentration protein solutions.
- Piston Pumps:Single-use piston assemblies deliver accurate volumetric dosing for small-batch personalized medicine manufacturing requiring precise aliquot control.
Volume sits with Peristaltic Pumps; growth tilts toward Diaphragm Pumps.
End User:
Regulatory stringency and batch flexibility requirements create distinct procurement profiles across customer verticals.
- Pharmaceuticals:Large molecule drug manufacturers deploy validated single-use pump assemblies to eliminate cross-contamination risk between campaign changes. EMA Annex 1 revision on sterile medicinal products drives facility upgrades toward pre-sterilized disposable systems with documented extractables profiles. Multi-product biologics facilities represent the core installed base.
- Biotechnology:Cell and gene therapy developers require ultra-flexible batch configurations that single-use architectures uniquely enable for personalized medicine production. Start-up manufacturing suites in Boston and San Francisco prioritize rapid changeover capabilities over capital equipment longevity.
- Food & Beverage:Aseptic processing operations adopt disposable pumps for high-acid product transfer where clean-in-place protocol elimination improves line utilization.
- Chemical Processing:Specialty chemical manufacturers specify corrosion-resistant thermoplastic pumps for aggressive solvent handling in batch reactor feed applications.
Revenue concentrates in Pharmaceuticals; Biotechnology exhibits the steepest expansion trajectory.
Application:
Flow precision requirements and sterility assurance levels determine pump specification across unit operations.
- Fluid Transfer:Bulk media movement between upstream bioreactors and downstream purification trains demands high-purity peristaltic designs with platinum-cured silicone tubing. German CMOs retrofitting legacy stainless-steel infrastructure drive concentrated demand for pre-sterilized transfer assemblies.
- Dosing:Chromatography buffer addition and formulation steps require programmable flow profiles that electromechanical pump architectures deliver. Brushless DC motor integration enables precise gradient control previously requiring external control systems.
- Irrigation:Surgical and endoscopic fluid delivery applications specify medical-grade disposable pumps with validated sterility assurance levels.
- Waste Disposal:Contaminated effluent collection systems employ rugged disposable pumps for biologically active material containment and safe transfer to treatment.
Fluid Transfer commands installed base; Dosing captures margin expansion.
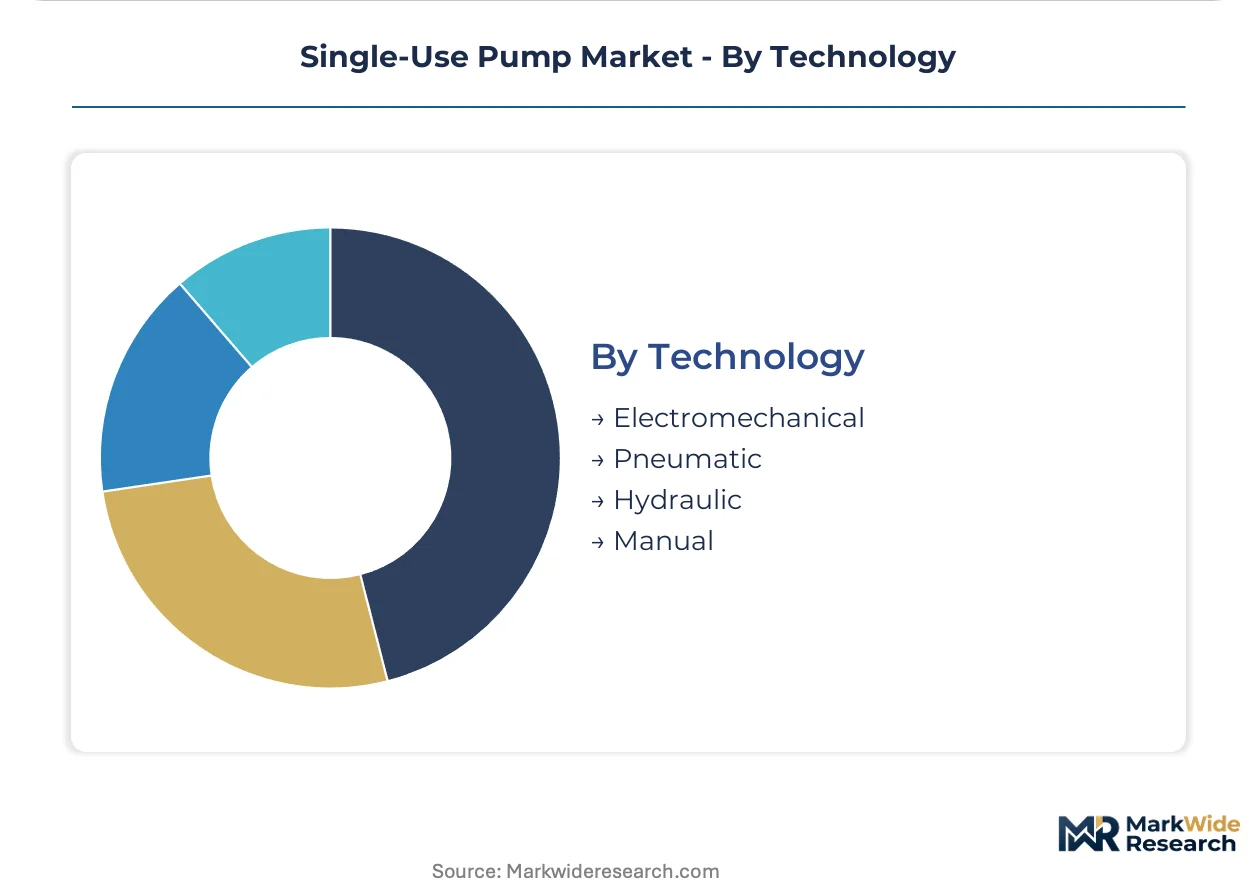
Technology:
Control sophistication and cleanroom compatibility separate procurement tiers in validated manufacturing environments.
- Electromechanical:Brushless DC motor integration enables programmable flow profiles with feedback control for chromatography and tangential flow filtration steps. Biopharmaceutical process engineers in Massachusetts and North Carolina facilities adopt these units for precision unit operations. The technology absorbs functionality previously requiring standalone pump controllers.
- Pneumatic:Compressed air-driven diaphragm mechanisms serve cost-sensitive applications where programmable precision remains secondary to capital avoidance and intrinsic safety.
- Hydraulic:Fluid power systems deliver high-force pumping for viscous media transfer in specialty chemical manufacturing outside sterile processing requirements.
- Manual:Hand-operated syringe pumps and squeeze bulbs serve research-scale applications and emergency backup scenarios in clinical settings.
Electromechanical systems lead technology migration; Pneumatic retains installed base in legacy facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors the most concentrated single-use pump demand in North America, with Greater Boston's cell and gene therapy cluster driving pre-sterilized assembly procurement for personalized medicine manufacturing.
United States
FDA sterility guidelines under current Good Manufacturing Practice mandate validated single-use systems for multi-product biologics facilities. The agency's contamination prevention emphasis accelerates facility upgrades toward disposable fluid handling architectures. North Carolina's Research Triangle and Massachusetts' Greater Boston corridor host the steepest retrofit timelines among contract manufacturing organizations.
Germany
EMA Annex 1 revision on sterile medicinal products tightens contamination control expectations for aseptic processing equipment. The country's national pharmaceutical regulator enforces documented extractables and leachables profiles before facility qualification. Bavaria's contract manufacturing organizations lead European retrofit activity, replacing legacy stainless-steel infrastructure with pre-sterilized disposable pump assemblies.
Switzerland
Swissmedic's stringent sterility assurance requirements align with EMA Annex 1 standards for biologics manufacturing. The country's precision engineering heritage supports high-purity peristaltic pump specification for monoclonal antibody production. Basel's pharmaceutical cluster concentrates demand for validated disposable fluid paths in multi-product facility configurations.
India
CDSCO's evolving biologics manufacturing guidelines push contract manufacturers toward disposable architectures that eliminate cross-contamination risk. The country's national pharmaceutical regulator emphasizes sterility assurance for export-oriented facilities. Maharashtra's biotech corridor and Karnataka's Bangalore cluster attract single-use pump deployment for biosimilar production workflows.
China
NMPA's quality management requirements for biopharmaceutical manufacturing drive adoption of pre-validated disposable systems. The national medical products administration tightens contamination control standards for sterile medicinal products. Shanghai's Zhangjiang Hi-Tech Park and Suzhou's biopharmaceutical zone concentrate domestic demand for electromechanical pump architectures with programmable flow profiles.
Single-Use Pump Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation documentation and cleanroom compatibility tiers. The vendor base stratifies between integrated bioprocessing platform providers and specialized fluid handling component fabricators. Three archetypes dominate: diversified industrial conglomerates with biopharma divisions, pure-play bioprocessing specialists, and precision pump engineering houses. Competitive moves center on hardware placement strategies that anchor recurring consumable revenue streams and multi-year supply agreement negotiations with contract manufacturing organizations.
Within the integrated platform tier, Sartorius AG exemplifies the consumables-led procurement model reshaping vendor-customer relationships. Among precision pump specialists, Watson-Marlow Fluid Technology Solutions occupies a position defined by high-purity peristaltic design expertise. Dover Corporation represents the diversified industrial archetype, leveraging cross-sector fluid handling capabilities to address biopharmaceutical applications.
| Leading Market Players |
|---|
| Watson-Marlow Fluid Technology Solutions |
| Dover Corporation |
| Xylem |
| Levitronix |
| Spirax Group plc |
| Sartorius AG |
| Fluid Flow Products, Inc. |
| SMC Corporation |
| Stobbe Group |
| Others |
Value Network & Pricing Analysis
Electromechanical pump architectures with brushless DC motor integration are compressing total cost-per-batch economics while simultaneously concentrating procurement leverage among German and Swiss contract manufacturing organizations. This technology transition rewards vendors who anchor recurring consumable revenue streams through hardware placement strategies, reshaping how biopharmaceutical buyers evaluate lifetime ownership costs against upfront capital avoidance.
Pricing Analysis
Value-based pricing anchored to batch yield assurance and contamination risk mitigation dominates validated single-use pump procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assemblies with documented extractables profiles from industrial-grade disposable units. Cost compression in commodity tiers is intensifying because Chinese and Indian contract manufacturers are localizing pre-sterilized assembly production. Large molecule drug manufacturers exhibit the least price sensitivity, prioritizing regulatory documentation over per-unit cost.
Supply Chain Analysis
Platinum-cured silicone tubing supply rests on Western European specialty elastomer producers, with German and Swiss chemical manufacturers controlling high-purity formulations. Molded thermoplastic pump housings draw from Chinese and German injection molding specialists, while fluoropolymer diaphragms rely on Japanese and American precision polymer fabricators. Single-source vulnerability in platinum-cured silicone concentrates risk exposure for biopharmaceutical-grade peristaltic designs. Distribution runs through authorized distributor networks serving validated manufacturing environments with chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EMA Annex 1 documentation burdens and extractables testing costs force sub-scale component fabricators toward exit. Regulatory compliance investment thresholds are accelerating attrition among undifferentiated suppliers.
For Market Incumbents: Extend consumables-led procurement models by negotiating multi-year supply agreements with Bavarian and North Carolina contract manufacturing organizations. Deepen backward integration into platinum-cured silicone tubing production to reduce Western European supply concentration exposure. Capture margin pools in cell and gene therapy manufacturing by pre-qualifying pump assemblies for personalized medicine batch configurations. For New Entrants and Emerging Players: Begin with ISO 13485-certified pre-sterilized assemblies targeting Indian and Chinese biosimilar producers where FDA validation documentation carries less procurement weight. The most penetrable segment sits with emerging biotech start-ups in Boston and San Francisco prioritizing rapid changeover over legacy stainless-steel compatibility. A direct-to-biotech sales model bypassing established distributor markups offers viable entry economics. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated bioprocessing platform providers seeking consumable revenue anchoring capabilities. Long-term viability favors vendors with captive silicone formulation expertise and documented EMA extractables libraries. Watch German CMO retrofit timelines as the inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables-Led Hardware Placement | Multi-year supply agreements with Bavarian CMOs anchor recurring revenue streams. |
| Backward Integration into Silicone Formulation | In-house platinum-cured tubing production reduces Western European supply concentration. |
| Cell Therapy Pre-Qualification Programs | Documented extractables profiles accelerate personalized medicine facility qualification timelines. |
| ISO 13485 Certification Expansion | Quality management adoption reduces customer validation burden in emerging biopharmaceutical clusters. |
| Electromechanical Control System Integration | Brushless DC motor architectures absorb functionality from standalone pump controllers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary fieldwork incorporated structured interviews with bioprocess engineering directors, regulatory affairs leads at multi-product biologics facilities, contract manufacturing procurement managers, and aftermarket service heads at precision pump distributors. FDA 483 inspection observations, EMA submission documents, and ISO 13485 certification databases provided secondary validation. Bottom-up facility retrofit tracking across Massachusetts, North Carolina, Bavaria, and Basel converged with top-down vendor revenue analysis.
Data-stream reconciliation across pump shipment volumes, consumable attachment rates, and facility qualification timelines informed the analytical framework. Segmentation dimensions spanned pump technology architecture, sterility assurance tier, end-user regulatory environment, and regional manufacturing cluster maturity. CAGRs were derived from installed base turnover rates and replacement cycle compression across the projection horizon. Electromechanical adoption curves and EMA Annex 1 implementation timelines served as industry-specific forecast inputs.
Regulatory enforcement intensity shifts, silicone raw material supply disruptions, and cell therapy manufacturing scale-out delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about sterility guideline harmonization and consumables procurement model persistence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market