
 Radial Flow Pump Market | 2026-2036
Radial Flow Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Flow Pump Market Analytics
China is tilting toward expanded domestic pump manufacturing capacity to serve Asia-Pacific water infrastructure needs. KSB SE & Co. KGaA leverages its vertical integration in foundry operations to control casting quality for large radial flow units. Flowserve Corporation anchors its position through aftermarket service networks that sustain recurring revenue from installed bases. Sulzer Ltd. specializes in corrosion-resistant alloy configurations for chemical process applications.
A radial flow pump directs fluid perpendicular to the pump shaft through an impeller with radial vanes, generating head primarily through centrifugal force rather than axial lift, with typical specific speeds below 2,000 RPM. These pumps handle clean or lightly contaminated liquids across moderate-to-high head and medium-flow duties in water distribution, process circulation, and pressure boosting systems. Centrifugal designs dominate installed capacity due to their mature supply chain and broad interchangeability, while mixed flow variants capture growth in flood control and large-scale drainage where head requirements sit between pure radial and axial solutions. Electric motor drives anchor the technology segment through grid reliability and variable frequency control, though solar-powered units gain traction in off-grid irrigation across water-scarce regions.
The US EPA sets efficiency benchmarks under the Clean Water Act that filter procurement criteria for municipal wastewater facilities, while EU Ecodesign Directive tiered requirements force redesign of motor-pump packages to meet minimum efficiency index thresholds. China's GB standards for pump energy consumption impose testing protocols that determine market access for domestic and imported equipment alike. Stakeholders must monitor how carbon border adjustment mechanisms and embodied carbon disclosure rules reshape sourcing decisions for cast components and motor assemblies.
Market Dynamics
EU Ecodesign Directive tiered efficiency mandates are forcing motor-pump package redesigns across European manufacturing bases, while China's GB standards create parallel compliance pathways that fragment certification requirements for multinational suppliers.
Growth Catalysts
- EU Ecodesign Directive:Tiered minimum efficiency index thresholds compel replacement of legacy motor-pump configurations in municipal water networks across Germany, France, and Italy.
- Irrigation modernization:China's state-led agricultural water reuse programs drive procurement volumes for medium-head radial flow units in the North China Plain.
- Casting quality control:Backward integration into foundry operations enables manufacturers to guarantee metallurgical consistency for large impeller components.
Market Restraints
- Copper and rare earth volatility:Electric motor winding costs fluctuate with commodity markets, compressing margin visibility for pump OEMs on fixed-price municipal contracts.
- Foundry concentration:Heavy casting capacity clusters in China's Hebei and Shandong provinces, creating geographic supply risk for European and North American assemblers.
- Axial flow substitution:Mixed-flow designs capture flood control applications where head requirements sit below pure radial pump optimal ranges.
Strategic Opportunities
- Solar-powered off-grid irrigation:Photovoltaic-driven variable frequency drives open addressable market in water-scarce regions of Sub-Saharan Africa and Central Asia.
- Corrosion-resistant alloys:Chemical process operators in the US Gulf Coast and Rotterdam-Antwerp corridor seek nickel-aluminum-bronze impeller configurations for brine handling.
- Aftermarket service unbundling:Predictive maintenance contracts based on vibration monitoring create recurring revenue streams independent of new equipment sales.
Industry Challenges
- Hydraulic design talent scarcity:Computational fluid dynamics expertise concentrates among aging specialist engineers in Germany and Japan, constraining product development bandwidth.
- Legacy control system integration:Variable frequency drives must interface with decades-old SCADA architectures in US municipal water districts, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Flow Pump Market |
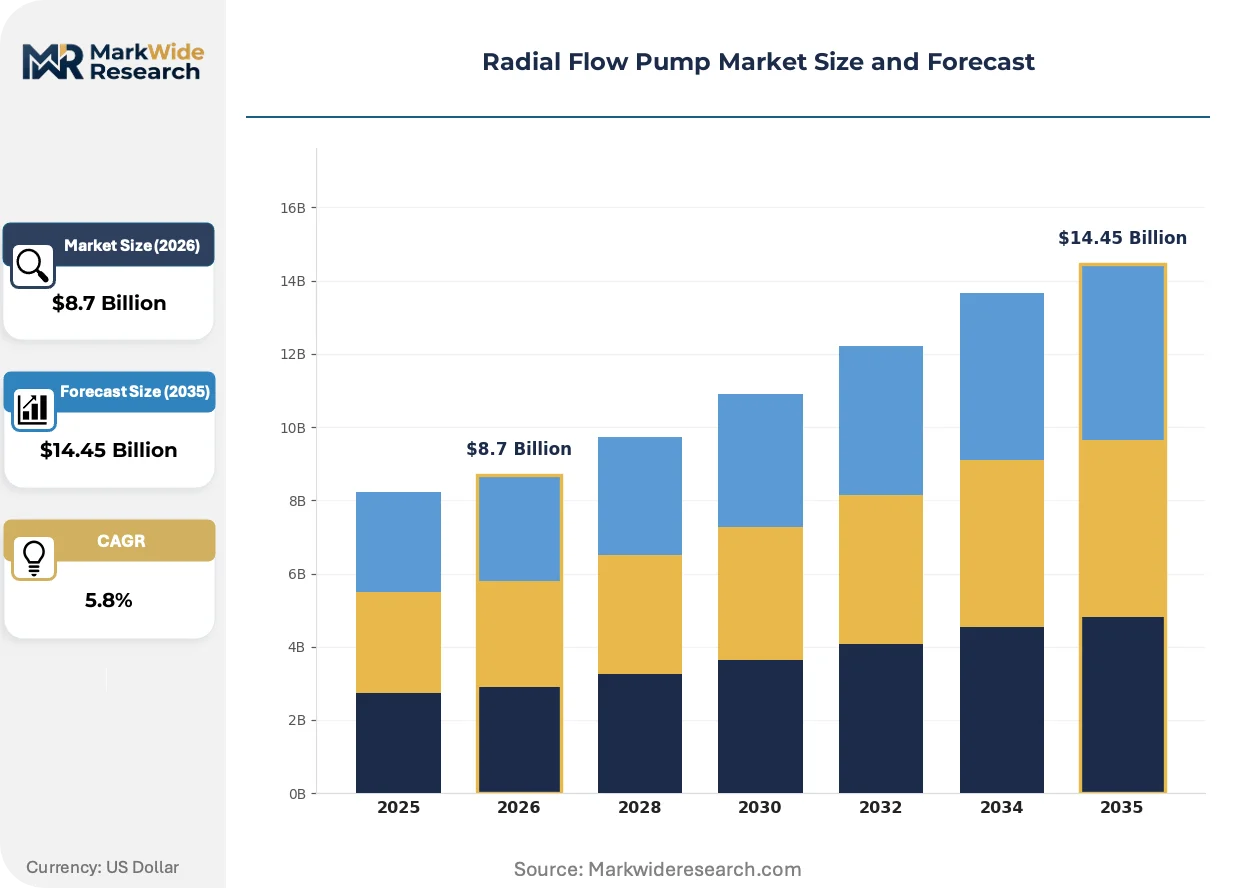
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric, Centrifugal, Axial, Mixed Flow End User: Agriculture, Mining, Wastewater Treatment, Power Generation Technology: Electric, Solar, Diesel-Powered, Hydraulic Application: Process Industry, Fire Protection, HVAC, Irrigation |
| Companies Covered | KSB SE & Co. KGaA, NEC Air Compressors, EGGER, Ruhrpumpen, Sulzer Ltd., Flowserve Corporation, Xylem Inc., Grundfos Holding A/S, Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Flow Pump Market Evolving Landscape
Digital twin technology is compressing product development cycles while regulatory efficiency mandates reshape hardware specifications. Equipment buyers increasingly prioritize total lifecycle cost over upfront capital expenditure.
Computational fluid dynamics simulation is virtualizing impeller design validation before physical prototyping. Municipal water authorities in Denmark and the Netherlands now require CFD-optimized hydraulic profiles for tenders above specified thresholds. This capability is virtualizing the traditional test-rig bottleneck, allowing manufacturers to iterate vane geometries in software rather than casting multiple physical prototypes.
The EU Ecodesign Directive's 2025 efficiency tier is accelerating permanent magnet motor adoption in integrated pump-motor packages. Manufacturers serving German and French municipal markets must redesign bearing configurations and cooling circuits to meet the new minimum efficiency index. Premium-tier suppliers are responding with modular motor platforms that scale across 11kW to 250kW duty points.
Lifecycle cost contracting is displacing capital-expense-focused procurement in Nordic water utilities. Danish and Swedish municipal buyers now structure payments around guaranteed energy consumption thresholds rather than unit purchase price. This model is most visible in Copenhagen's HOFOR and Stockholm's Stockholm Vatten operations, where ten-year service-inclusive agreements dominate new installations.
Radial Flow Pump Market Segmentation
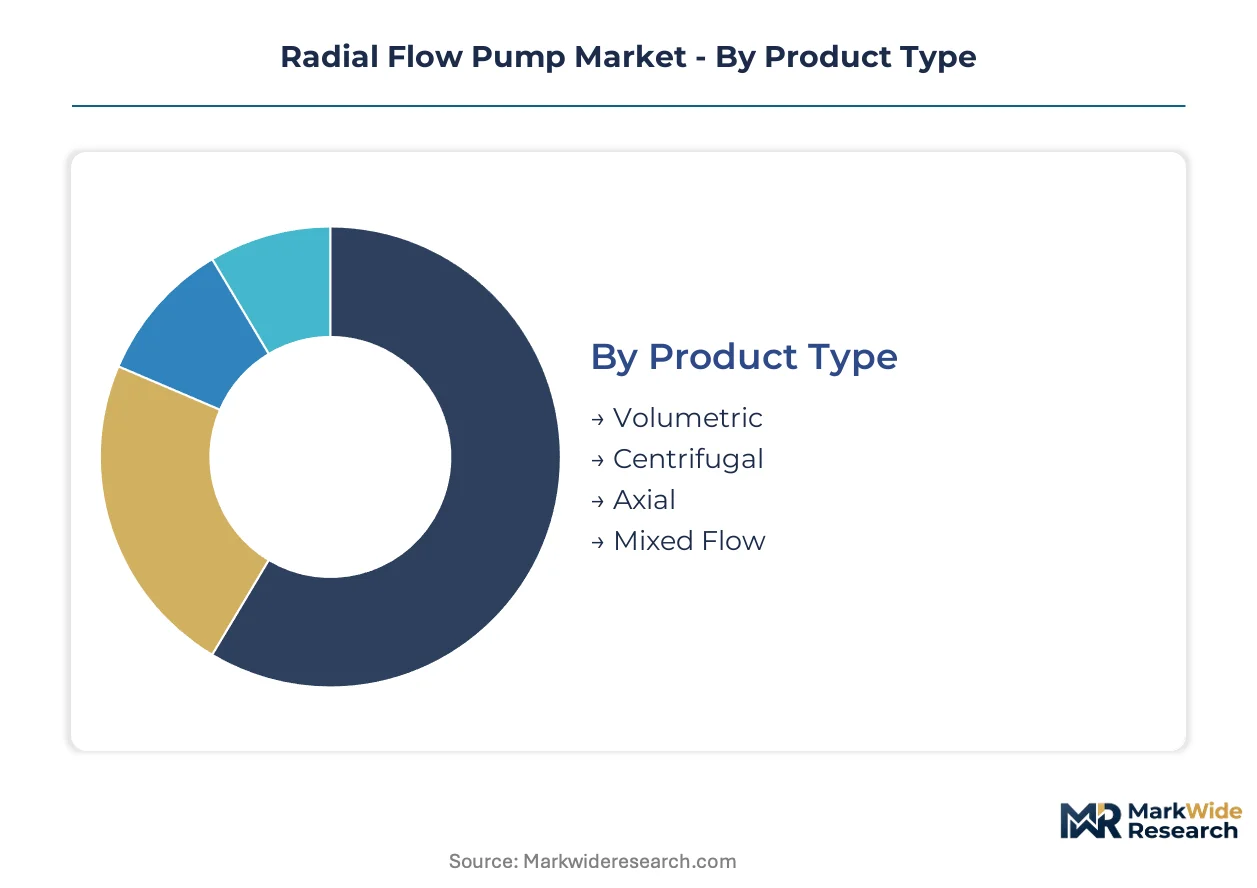
Segmentation in radial flow pumps reveals distinct procurement cycles across product architectures and energy systems. Replacement intervals vary from decades-long municipal installations to seasonal agricultural deployments. Understanding these temporal patterns shapes inventory positioning and service contract structures for manufacturers.
Product Type:
Centrifugal designs turn over slowest through embedded municipal infrastructure, while volumetric units cycle fastest in mobile process applications. Axial and mixed flow alternatives occupy intermediate replacement horizons in drainage and flood control.
- Centrifugal:Radial vane impellers generate head through pure centrifugal force with specific speeds below 2,000 RPM. Demand concentrates in German and French municipal water networks where EU Ecodesign Directive tiered mandates force motor-pump package replacements.
- Volumetric:Positive displacement mechanisms deliver precise flow control for high-viscosity process fluids. North Sea chemical operators and US Gulf Coast refiners specify these units for polymer and slurry handling where shear sensitivity matters.
- Axial:Propeller-style impellers move large volumes at low heads for flood control and raw water intake. China's Yangtze River basin drainage programs and Netherlands polder systems anchor procurement.
- Mixed Flow:Hybrid geometries blend radial and axial characteristics for intermediate head duties. Indonesian palm oil processing and Vietnamese aquaculture recirculation systems drive Southeast Asian volume.
Centrifugal designs dominate installed base. Volumetric configurations are where expansion concentrates in chemical process modernization.
End User:
Cost tier differentiation separates capital-intensive permanent installations from seasonal equipment with lower specification floors. Mining and power generation sit at premium engineering tiers; agriculture occupies economy positioning with price-sensitive procurement.
- Agriculture:Medium-head radial flow units serve surface irrigation and center-pivot systems across water-scarce regions. China's North China Plain state-led modernization programs and India's PM-KUSUM solar pump subsidies concentrate demand volume.
- Mining:Abrasion-resistant alloys and hardened impeller configurations handle tailings and slurry transport. Western Australian iron ore operations and Chilean copper belt dewatering specify premium metallurgy with 24-hour duty cycles.
- Wastewater Treatment:Submersible radial configurations manage raw sewage and activated sludge circulation. US EPA Clean Water Act efficiency benchmarks filter municipal procurement in California, Texas, and Florida districts.
- Power Generation:Boiler feed and cooling water applications require precision alignment and vibration control. Combined cycle gas turbine plants in the UAE and Saudi Arabia specify API-compliant packages for thermal duty.
Mining commands premium pricing tiers. Agriculture represents the steepest expansion trajectory through irrigation electrification programs.
Technology:
Volume concentration follows grid reliability geography, with solar penetration inverse to transmission infrastructure density. Diesel retains niche positioning in remote extraction and emergency backup.
- Electric:Grid-connected motor drives with variable frequency control anchor municipal and industrial installations. Danish HOFOR and Stockholm Vatten structure ten-year lifecycle cost contracts around guaranteed energy consumption thresholds.
- Solar:Photovoltaic-driven variable frequency drives enable off-grid irrigation in Sub-Saharan Africa and Central Asia. Kenya's Turkana irrigation schemes and Uzbekistan's Amu Darya delta deployments scale modular arrays.
- Diesel-Powered:Internal combustion drives serve emergency fire protection and remote construction dewatering. Australian mining camps and Canadian oil sands operations maintain backup fleets for grid failure scenarios.
- Hydraulic:Fluid power transmission operates in explosive atmospheres and subsea environments. North Sea oil platform ballast systems and subsea mining prototypes test this architecture.
Electric systems dominate installed base. Solar configurations are where expansion concentrates through rural electrification initiatives.
Application:
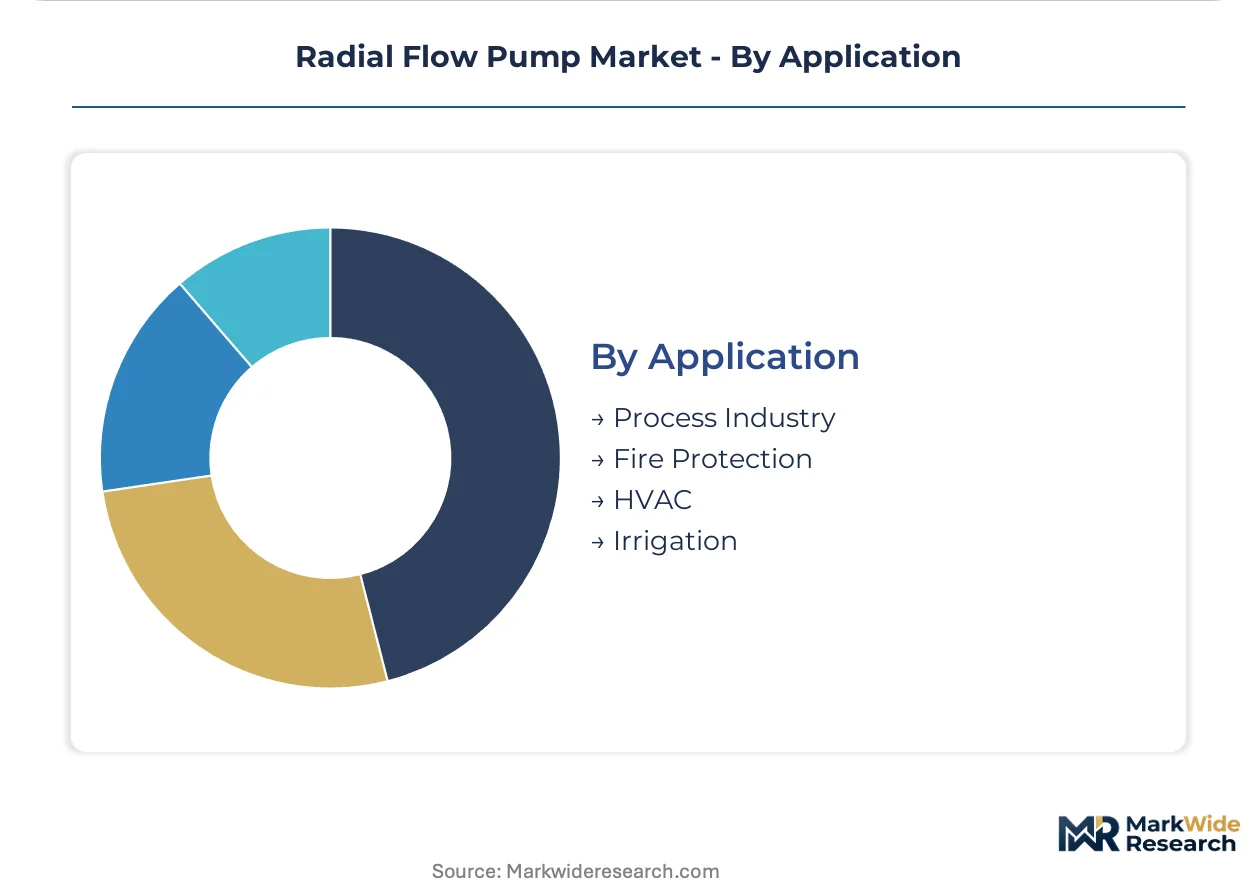
Customer type fragmentation separates specification-intensive engineered sales from catalog-driven replacement business. Process industry and fire protection demand custom hydraulic profiles; HVAC and irrigation accept standardized configurations.
- Process Industry:Corrosion-resistant nickel-aluminum-bronze and duplex stainless impellers handle aggressive chemistries. Rotterdam-Antwerp corridor refineries and Singapore Jurong Island petrochemical complexes specify Sulzer and Flowserve corrosion alloys.
- Fire Protection:UL/FM listed packages with guaranteed flow curves for sprinkler and standpipe systems. Dubai's high-rise construction codes and Singapore's SCDF mandates drive certification-heavy procurement.
- HVAC:Compact inline and base-mounted units for chilled water and condenser circuits. US commercial real estate in Texas and Florida replaces aging constant-speed configurations with variable frequency retrofits.
- Irrigation:Surface and pressurized distribution systems for agricultural water conveyance. Australia's Murray-Darling Basin efficiency mandates and Spain's Almería greenhouse complexes concentrate demand.
HVAC dominates installed base through building stock scale. Process industry applications are where expansion concentrates in chemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards anchor procurement protocols in China, the world's largest volume market for radial flow pumps. Municipal water infrastructure upgrades and industrial water reuse programs across multiple geographies are reshaping regional demand patterns and compliance requirements.
China
State-led irrigation modernization in the North China Plain and Yangtze River basin drainage programs drive procurement of medium-head radial flow units. GB standards for pump energy consumption impose mandatory testing protocols that determine market access for domestic and imported equipment. Foundry capacity concentrates in Hebei and Shandong provinces, supplying cast impeller components to assemblers nationwide.
Germany
EU Ecodesign Directive tiered efficiency mandates force replacement of legacy motor-pump configurations in municipal water networks across North Rhine-Westphalia and Bavaria. The 2025 efficiency tier accelerates permanent magnet motor adoption in integrated packages. KSB SE anchors manufacturing in Frankenthal, leveraging vertical integration in foundry operations for large unit casting quality.
United States
EPA efficiency benchmarks under the Clean Water Act filter procurement criteria for municipal wastewater facilities in California, Texas, and Florida districts. Variable frequency drive retrofits replace aging constant-speed configurations in commercial HVAC across Texas and Florida real estate. Mining operations in Arizona and Nevada specify abrasion-resistant alloys for tailings transport.
India
PM-KUSUM solar pump subsidies concentrate demand for photovoltaic-driven variable frequency drives in agricultural irrigation across Maharashtra and Gujarat. State-led canal modernization programs in Punjab and Haryana procure medium-head units for surface water distribution. Domestic manufacturing clusters in Tamil Nadu and Karnataka assemble electric motor drives for grid-connected installations.
Netherlands
Polder drainage systems and flood control infrastructure anchor demand for mixed-flow and axial alternatives alongside radial configurations. Danish and Swedish municipal buyers structure lifecycle cost contracts around guaranteed energy consumption thresholds. Rotterdam-Antwerp corridor refineries specify corrosion-resistant alloys for chemical process applications.
Radial Flow Pump Market Competitive Landscape
Vertically integrated multinationals and specialized regional fabricators split the market across distinct capability tiers. Concentration remains moderate with established European and Japanese manufacturers holding premium positions through aftermarket service networks. Three archetypes dominate: foundry-integrated OEMs controlling casting quality, corrosion-alloy specialists serving chemical process industries, and solar-irrigation assemblers targeting price-sensitive agricultural markets. Competitive moves center on backward integration into foundry operations and predictive maintenance service unbundling.
Among German-origin manufacturers, KSB SE & Co. KGaA exemplifies the foundry-integrated archetype through captive casting capacity. Sulzer Ltd. and Flowserve Corporation occupy positions within the corrosion-alloy specialist tier, serving chemical process operators in Rotterdam-Antwerp and US Gulf Coast corridors. These three anchors illustrate how geographic clustering around industrial demand centers shapes competitive positioning.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| NEC Air Compressors |
| EGGER |
| Ruhrpumpen |
| Sulzer Ltd. |
| Flowserve Corporation |
| Xylem Inc. |
| Grundfos Holding A/S |
| Ebara Corporation |
| Others |
Value Network & Pricing Analysis
Foundry capacity clustering in China's Hebei and Shandong provinces concentrates upstream metallurgical control, positioning captive casting operations as the primary margin pool for large radial flow unit manufacturers while exposing non-integrated assemblers to spot-market volatility in impeller components.
Pricing Analysis
Geographic price spreads of 15-25% separate European municipal procurement from Asian agricultural tenders, reflecting certification burden and after-sales bundling. Three-tier pricing structure across premium, standard, and economy levels aligns with API compliance tiers and foundry integration depth. Price differentiation hinges on UL/FM fire protection certification and permanent magnet motor efficiency grades. Pricing pressure stems from copper and rare earth commodity swings that compress visibility on fixed-price municipal contracts. Agricultural buyers in India and Sub-Saharan Africa exhibit highest price sensitivity; chemical process operators in Rotterdam-Antwerp and US Gulf Coast corridors show lowest.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for foundry-integrated OEMs serving European municipal networks. Cast impeller production concentrates in China, Germany, and Japan. Raw material dependencies center on copper motor windings, nickel-aluminum-bronze alloys, and rare earth permanent magnets. Single-source vulnerability runs through China's Hebei province heavy casting capacity. Distribution runs through authorized distributor networks for municipal specifications and direct OEM channels for agricultural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU Ecodesign Directive tiered mandates and China's GB standards create compliance barriers that privilege incumbent foundry-integrated manufacturers with established certification pathways.
For Market Incumbents: Pre-empt axial flow substitution in flood control applications by accelerating mixed-flow product line expansion. Deepen captive foundry capacity in Germany or India to offset geographic concentration risk in China's Hebei province. Secure permanent magnet motor supply agreements before efficiency tier upgrades tighten qualified supplier pools. For New Entrants and Emerging Players: Establish a beachhead in solar-powered off-grid irrigation across Kenya's Turkana schemes and Uzbekistan's Amu Darya delta, where modular photovoltaic arrays bypass entrenched electric distribution relationships. Target corrosion-resistant alloy retrofits in aging US Gulf Coast refineries as a specifications-light entry point. Lead with lifecycle cost contracting models proven in Nordic utilities to differentiate from capital-expense-focused incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corrosion-alloy specialists serving Rotterdam-Antwerp and Singapore Jurong Island petrochemical corridors. Long-term viability over a 5-10 year window rests on aftermarket service revenue unbundling and predictive maintenance contract penetration. Watch for carbon border adjustment mechanism implementation as the inflection signal that reshapes sourcing economics for cast components and motor assemblies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | KSB SE's Frankenthal captive casting guarantees metallurgical consistency for large impeller units serving EU municipal networks. |
| Permanent Magnet Motor Platform Development | Modular 11kW-250kW packages meet EU Ecodesign Directive 2025 efficiency tiers for German and French water authorities. |
| Predictive Maintenance Service Unbundling | Vibration-monitoring contracts create recurring revenue streams independent of new equipment sales for Flowserve's installed base. |
| Solar-Powered Irrigation System Deployment | Photovoltaic-driven VFDs open addressable markets in Kenya's Turkana schemes and Uzbekistan's Amu Darya delta. |
| Corrosion-Resistant Alloy Configuration | Nickel-aluminum-bronze impellers capture chemical process demand in Rotterdam-Antwerp and US Gulf Coast refineries. |
Research Methodology
A spread of perspectives from municipal water authority procurement directors, chemical process plant engineers, aftermarket service heads at major OEMs, and foundry operations managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC 10-K filings from listed pump manufacturers, EU Ecodesign Directive implementation reports, and China's GB standard testing protocols. Bottom-up unit shipment estimates triangulated against top-down energy consumption projections for municipal water networks.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling replacement cycles in embedded municipal infrastructure against agricultural electrification programs. Segmentation dimensions included product architecture, end-use industry, drive technology, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed regional procurement volumes and state-led program targets. Industry-specific inputs incorporated EU minimum efficiency index thresholds and China's state-led irrigation modernization schedules.
Stress conditions across copper and rare earth price volatility, foundry capacity utilization, and axial flow substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timing and program disbursement rates. Macroeconomic contraction, trade restriction escalation, or breakthrough magnetic material technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Global Pumps Market